
 IC Packaging and Testing Market | 2026-2036
IC Packaging and Testing Market Size, Share, and Industry Trends Forecast 2026-2036
IC Packaging and Testing Market Insights
Advanced packaging services with software-defined thermal management is consolidating value capture away from commoditized wire bonding. ASE Technology leverages its fan-out panel-level capacity to anchor premium positioning in system-in-package modules. Amkor Technology sustains geographic diversification across multiple assembly sites. JCET Group Co., Ltd. specializes in memory packaging for Chinese fabless designers.
IC packaging and testing encompasses the protective encapsulation, electrical interconnect, and functional verification of semiconductor die, employing processes such as flip-chip solder bumping, wafer-level redistribution layers, and thermal cycling validation to ensure signal integrity and mechanical reliability under operating stress. The primary purpose is to transform fragile silicon into deployable components for electronic systems while screening latent defects before shipment. Flip chip formats now dominate margin pools in high-performance computing applications where interconnect density determines bandwidth ceilings. Burn-in testing commands premium pricing in automotive and telecommunications end users where field failure costs dwarf upfront qualification expenses. Ceramic substrates retain niche strength in industrial automation and aerospace despite epoxy-based organic laminates capturing volume leadership.
FDA oversight of medical device semiconductor reliability, EPA restrictions on lead-based solder compositions under RoHS-aligned state rules, and FCC electromagnetic compatibility standards collectively shape product roadmaps and qualification burdens for US-bound shipments. China's SAMR enforces GB standards on packaging material content while MIIT promotes domestic substitution through dual carbon-aligned industrial policy. Stakeholders must monitor evolving test methodology requirements as chiplets displace monolithic die architectures and heterogeneous integration redefines failure analysis protocols.
Market Dynamics
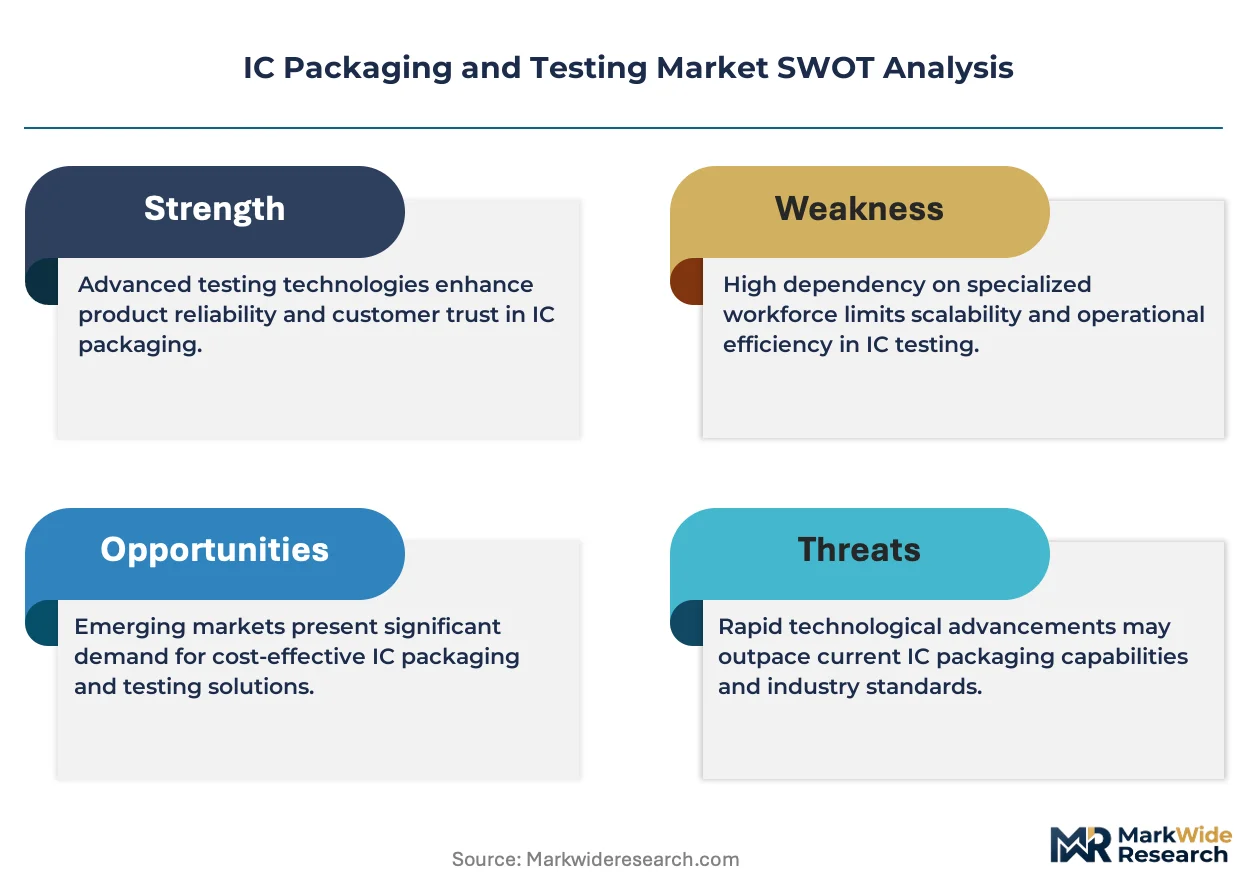
Chiplet-based heterogeneous integration is fragmenting monolithic die architectures and forcing packaging houses to reconfigure test protocols for multi-die verification rather than single-device qualification.
Growth Catalysts
- Automotive ADAS proliferation:High-reliability requirements for advanced driver-assistance systems are expanding burn-in testing volumes and ceramic substrate adoption for thermal cycling resilience.
- China's dual carbon policy:MIIT industrial directives and SAMR-enforced GB standards on packaging material content are accelerating domestic substitution investments and green material qualification.
- Fan-out panel-level processing:Wafer-level redistribution layer scaling is enabling system-in-package modules with superior interconnect density for bandwidth-constrained computing workloads.
Market Restraints
- Substrate supply concentration:ABF substrate manufacturing capacity remains concentrated among Japanese and Taiwanese suppliers, creating allocation bottlenecks for flip-chip ball grid array designs.
- Lead-free solder transition costs:EPA-aligned state RoHS implementations and ECHA REACH restrictions on hazardous substances are elevating material qualification expenses and alloy development cycles.
- Organic laminate thermal limits:Epoxy-based substrates face dielectric breakdown constraints under extreme power densities in high-performance computing, preserving ceramic niche premiums.
Strategic Opportunities
- India semiconductor ecosystem:PLI scheme incentives and BIS standards harmonization are attracting outsourced assembly and test investments for fabless design houses serving domestic electronics manufacturing.
- Medical device semiconductor reliability:FDA oversight of implantable and diagnostic device packaging is creating premium qualification service demand with extended traceability requirements.
- AI accelerator chiplets:Convergence of photonic interconnect and 3D stacking architectures is opening new failure analysis and thermal validation service categories.
Industry Challenges
- Multi-physics simulation expertise:Electromagnetic-thermal-mechanical co-design for heterogeneous packages requires scarce cross-functional engineering talent unmet by conventional mechanical or electrical training pipelines.
- Test equipment refresh cycles:Advantest and Teradyne platform obsolescence pressures capital allocation for high-pin-count digital and RF test cell expansion.
- IP licensing fragmentation:Die-to-die interconnect standards from UCIe, BoW, and proprietary foundry variants complicate test program portability across customer designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IC Packaging and Testing Market |
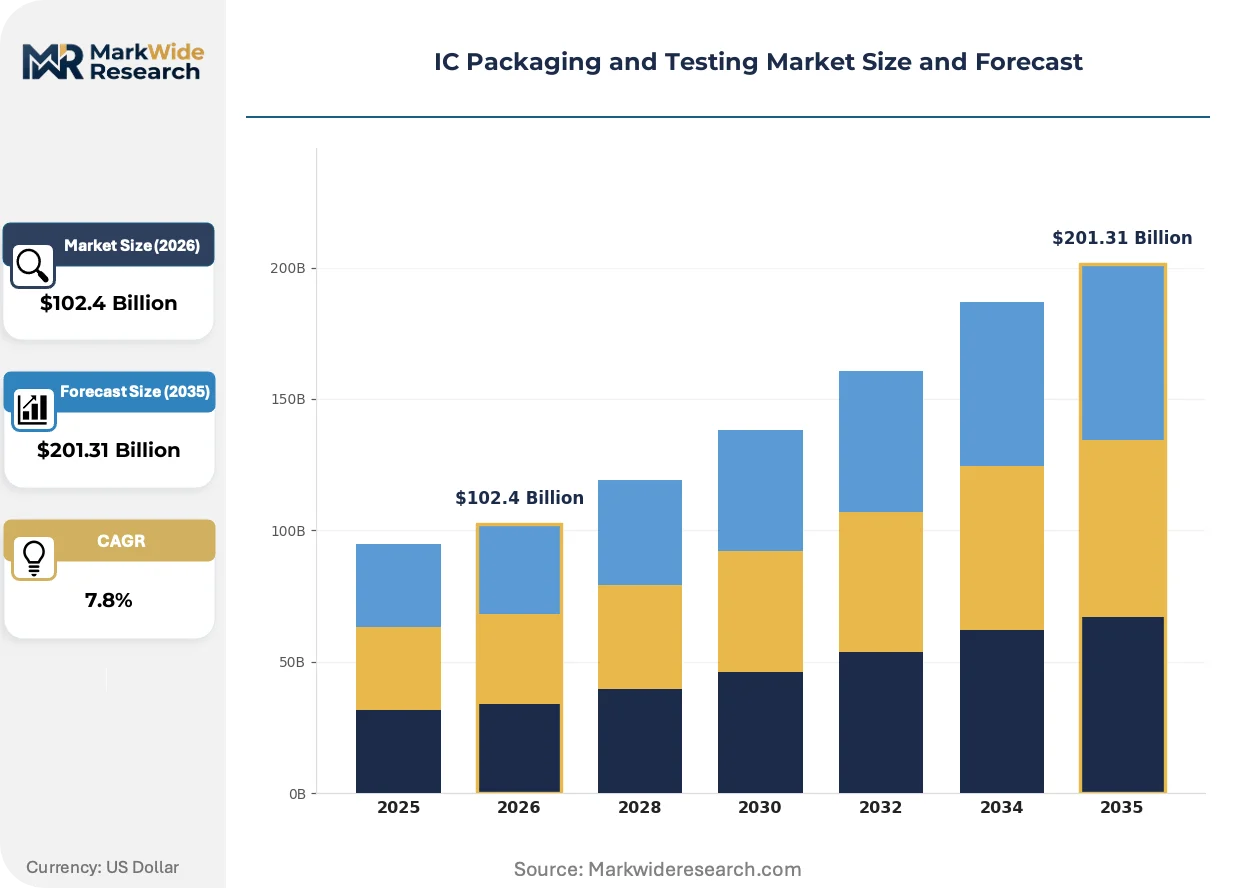
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $201.31 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
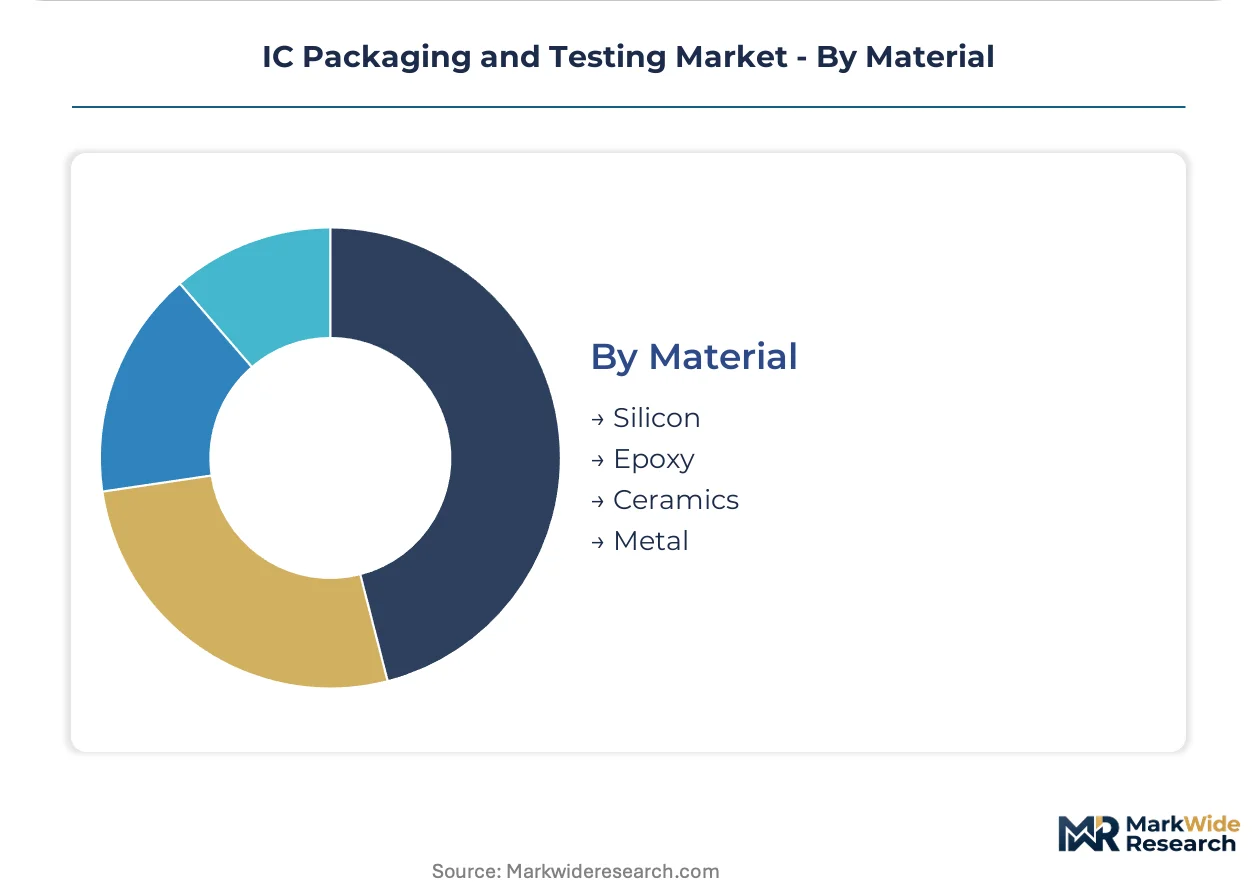
| Segmentation | Packaging Type: Flip Chip, Ball Grid Array, Quad Flat Package, Chip-On-Board Testing Methodology: In-Circuit Testing, Functional Testing, Burn-In Testing, Optical Testing End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Material: Silicon, Epoxy, Ceramics, Metal |
| Companies Covered | Powertech Technology Inc., Siliconware Precision Industries Co., Ltd., ASE Technology, Integra Technologies, ASE Test Limited, Amkor Technology, STATS ChipPAC, Advantest Corporation, JCET Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IC Packaging and Testing Market Trends and Innovations
Active packaging architectures are displacing passive interconnect paradigms as functional integration moves from board-level assembly to wafer-level processing.
Glass core substrates are rewriting thermal and electrical performance boundaries for high-density fan-out applications. Data center operators and AI accelerator designers are piloting glass interposer designs for reduced signal loss at millimeter-wave frequencies. This substrate transition is compressing organic laminate dominance in premium computing segments.
EU Green Deal aligned CSRD reporting requirements and F-Gas Regulation phase-down schedules are mandating fluorinated gas elimination from plasma cleaning and etch processes in European packaging facilities. Assembly houses in Germany and the Netherlands are retrofitting abatement systems and qualifying alternative chemistries. Memory packaging for automotive qualification is experiencing the steepest compliance cost inflation.
Consolidated procurement of packaging and test services is compressing vendor panels at major fabless semiconductor designers. Tier-one smartphone and computing OEMs are reducing qualified supplier lists from six to three partners, prioritizing vertically integrated houses with captive substrate or bumping capacity. This concentration is most pronounced in Taiwan and South Korea, where foundry-packaging-test co-location offers cycle time advantages.
IC Packaging and Testing Market Segmentation
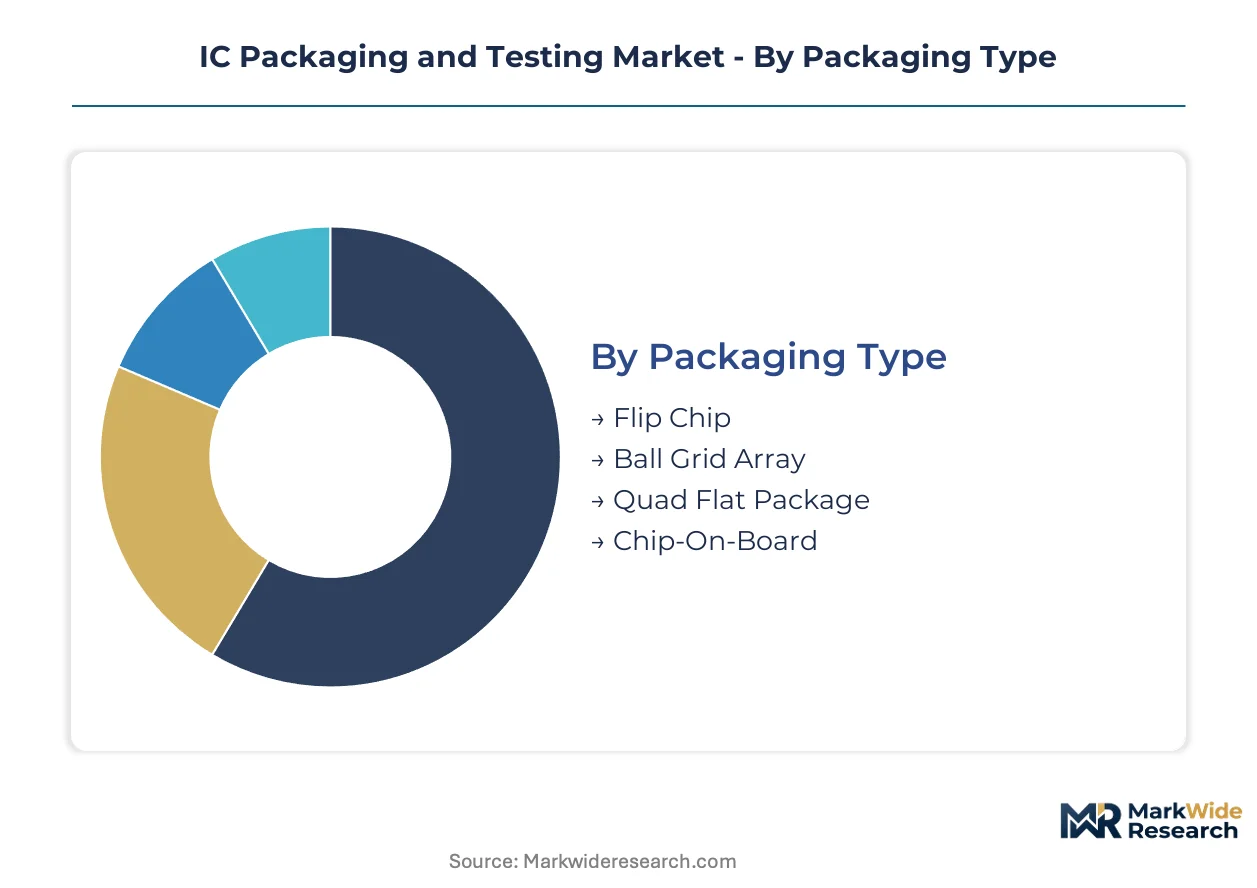
Packaging format selection determines thermal performance ceilings and signal integrity margins for semiconductor die deployment. Testing methodology choices reflect end-use reliability requirements and field failure cost exposure. Material substrate decisions balance electrical properties against regulatory compliance burdens and supply security.
Packaging Type:
Interconnect density and thermal dissipation capacity differentiate formats across computing performance tiers.
- Flip Chip:Solder bumping creates direct electrical pathways between die and substrate, eliminating wire bond inductance for high-frequency signal transmission. AI accelerator designers in Taiwan and South Korea specify flip-chip ball grid array configurations for bandwidth-constrained workloads where interconnect pitch determines system throughput.
- Ball Grid Array:Solder sphere arrays distribute I/O across package bottom surfaces, enabling higher pin counts than perimeter-lead alternatives. Automotive module suppliers in Germany and Japan prioritize ceramic BGA variants for advanced driver-assistance systems requiring thermal cycling resilience under hood temperatures.
- Quad Flat Package:Gull-wing leads extend from package periphery, preserving cost efficiency for legacy consumer electronics with moderate I/O requirements. Chinese fabless designers specify QFP for industrial control applications where board-level reworkability outweighs density demands.
- Chip-On-Board:Bare die attach directly to printed circuit boards eliminates package substrate costs for price-sensitive volume production. LED lighting and basic sensor modules in India leverage COB for domestic electronics manufacturing serving cost-constrained appliance markets.
Ball Grid Array leads on scale; Flip Chip leads on momentum.
Testing Methodology:
Defect screening intensity correlates with end-use failure consequence severity and warranty exposure duration.
- Burn-In Testing:Extended voltage and temperature stress accelerates infant mortality failure mechanisms before shipment. Automotive and telecommunications equipment manufacturers in Japan and Germany mandate burn-in protocols where field replacement costs exceed qualification expenses by orders of magnitude.
- Functional Testing:At-speed pattern validation verifies logical operation across specified voltage and temperature corners. Consumer electronics assemblers in Vietnam and Mexico prioritize functional test throughput for smartphone and tablet volume ramps where cycle time compression determines contract capture.
- In-Circuit Testing:Bed-of-nails fixture contact isolates manufacturing defects at component and solder joint level. Industrial automation OEMs in Switzerland combine ICT with boundary scan for programmable logic controller modules requiring deterministic fault isolation.
- Optical Testing:Machine vision inspection detects cosmetic and dimensional anomalies in package assembly and marking. Medical device semiconductor suppliers in the United States deploy optical validation for FDA-subjected implantable device packaging with extended traceability requirements.
Functional Testing commands volume leadership; Burn-In Testing captures premium expansion.
End User:
Reliability specification divergence creates tiered service pricing across application categories.
- Automotive:Zero-defect qualification protocols govern advanced driver-assistance system semiconductor deployment where functional safety standards apply. AEC-Q100 Grade 0 temperature specifications and ISO 26262 traceability requirements elevate testing intensity for powertrain and chassis control modules.
- Consumer Electronics:Smartphone and wearable device packaging prioritizes form factor miniaturization and cost efficiency over extended temperature range. System-in-package integration enables heterogeneous die stacking for mobile application processors with space-constrained designs.
- Telecommunications:Base station and optical network equipment demand hermetic sealing and thermal cycling resilience for decade-long field service life. Ceramic column grid array formats retain preference for high-frequency RF power amplifiers in 5G infrastructure deployment.
- Industrial Automation:Programmable logic controllers and motor drive inverters specify wide-temperature operation and vibration resistance for factory floor environments. Extended burn-in and environmental stress screening address latent defect risks in multi-year continuous operation scenarios.
Consumer Electronics dominates unit volume; Automotive commands value concentration.
Material:
Substrate electrical and thermal properties determine package performance boundaries and regulatory compliance pathways.
- Silicon:Wafer-level redistribution layers and through-silicon vias enable highest-density interconnect for 3D stacking architectures. Interposer substrates from Taiwan foundries anchor CoWoS and EMIB implementations for AI training accelerators.
- Ceramics:Alumina and aluminum nitride substrates deliver thermal conductivity and coefficient-of-expansion matching for high-power and high-reliability applications. Japanese suppliers concentrate multilayer ceramic capacity for aerospace and defense qualification programs.
- Epoxy:Organic laminate substrates dominate volume production through cost efficiency and established supply chains. ABF film buildup materials from Japanese chemical suppliers face allocation constraints for fine-pitch flip-chip designs.
- Metal:Copper and aluminum lead frames and thermal spreaders manage heat dissipation in power discrete and RF device packaging. Lead-free plating chemistries comply with EU RoHS and China GB standards while maintaining solderability and wire bond integrity.
Epoxy substrates anchor volume leadership; Silicon interposers capture technology premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting outsourced semiconductor assembly and test capacity toward jurisdictions with streamlined environmental compliance and concentrated engineering talent pools. Cost-of-compliance gaps between mature and emerging packaging hubs are accelerating investment migration. Foundry-proximate clustering remains the dominant location logic regardless of geography.
Taiwan
Hsinchu Science Park houses the densest concentration of advanced packaging capacity globally, with ASE Technology and Siliconware Precision Industries operating multi-fab campuses adjacent to TSMC foundry complexes. Environmental regulations under the EPA Taiwan enforce fluorinated gas abatement standards that exceed baseline UNFCCC commitments. Taichung and Tainan science parks are absorbing overflow capacity as Hsinchu land constraints intensify.
China
Jiangsu province anchors domestic packaging demand through JCET Group Co., Ltd. facilities serving fabless designers in Shanghai and Shenzhen. MIIT industrial directives and SAMR-enforced GB standards on packaging material content are elevating qualification costs for lead-free solder and green substrate chemistries. Wuxi and Suzhou industrial zones are consolidating memory packaging specialization under dual carbon-aligned investment incentives.
United States
Arizona and Texas are attracting OSAT investments driven by CHIPS Act fab co-location incentives and EPA-aligned state RoHS enforcement that narrows compliance gaps with Asian suppliers. FDA oversight of medical device semiconductor reliability creates premium qualification demand in Massachusetts and Minnesota clusters. Phoenix and Austin metro areas are emerging as test service hubs for automotive and aerospace qualification programs.
South Korea
Seoul Capital Area packaging houses leverage foundry integration with Samsung and SK Hynix for HBM and AI accelerator module assembly. MFDS medical device regulations and METI-aligned industrial standards enforce traceability requirements that elevate service pricing for implantable electronics. Pyeongtaek and Yongin industrial complexes are expanding fan-out panel-level capacity for system-in-package integration.
Japan
Kyushu and Nagoya industrial corridors retain ceramic substrate specialization for automotive and telecommunications hermetic packaging. JIS standards and METI circular economy directives mandate material recovery rates that preserve domestic supply chain premiums. ABF substrate manufacturing from Japanese chemical suppliers faces allocation constraints, concentrating flip-chip ball grid array capacity in Osaka and Hiroshima prefectures.
IC Packaging and Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated OSATs capturing premium system-in-package volumes while independent test houses serve commodity qualification demand. Market structure concentrates around three to five dominant players controlling advanced packaging capacity, with mid-tier specialists occupying wire bonding and legacy format niches. Strategic archetypes include foundry-captive integrators, geographic diversifiers, and substrate-captive premium specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity constrained by regulatory scrutiny of semiconductor supply chain concentration.
Among Taiwan-based integrated service providers, ASE Technology and Siliconware Precision Industries Co., Ltd. exemplify the foundry-proximate archetype through Hsinchu Science Park clustering. Amkor Technology occupies a position as the geographic diversification specialist with assembly site distribution across multiple regulatory jurisdictions. JCET Group Co., Ltd. represents the domestic market anchor archetype within China's fabless design ecosystem.
| Leading Market Players |
|---|
| Powertech Technology Inc. |
| Siliconware Precision Industries Co., Ltd. |
| ASE Technology |
| Integra Technologies |
| ASE Test Limited |
| Amkor Technology |
| STATS ChipPAC |
| Advantest Corporation |
| JCET Group Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Foundry-captive OSATs with sovereign-backed expansion financing in Taiwan and South Korea anchor supply-side discipline, translating substrate allocation leverage into tiered pricing power across advanced packaging tiers while compressing margins for wire-bonding specialists without captive bumping capacity.
Pricing Analysis
Capacity additions in Taichung and Yongin are reshaping price floors for fan-out panel-level processing, forcing legacy wire-bonding houses toward volume discounts. Pricing stratifies across automotive-grade burn-in qualification, consumer SiP integration, and commodity QFP assembly, with ABF substrate allocation premiums widening spreads between flip-chip and wire-bond tiers. Cost compression in memory packaging intensifies as Chinese domestic substitution investments elevate green material qualification expenses. Automotive module suppliers exhibit lowest price sensitivity due to field failure liability exposure, while Indian appliance OEMs drive hardest bargain on COB formats.
Supply Chain Analysis
ABF film supply rests on Japanese chemical producers including Shin-Etsu and Ajinomoto, with substrate lamination capacity concentrated in Taiwan, South Korea, and Japan. Raw material dependencies span fluorinated gases for plasma etch, high-purity copper for redistribution layers, and ceramic powders for automotive-grade substrates. Single-source vulnerability in ABF resin formulations creates allocation chokepoints for advanced CoWoS implementations. Distribution runs through foundry-direct programs for AI accelerator designers and contract EMS channels for smartphone OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in IC packaging and testing hinges on heterogeneous integration complexity premiums displacing commoditized wire-bonding volumes, with burn-in testing intensity for automotive ADAS modules driving the steepest value capture.
For Market Incumbents: To counter glass core substrate pilots by data center operators, ASE Technology and Amkor Technology should deepen backward integration into captive ABF film supply and expand burn-in cell capacity in Arizona and Texas to capture CHIPS Act co-location incentives. Foundry-proximate clustering in Hsinchu Science Park remains the priority defensive moat against geographic diversification plays. For New Entrants and Emerging Players: Begin with medical device semiconductor reliability services in Massachusetts and Minnesota, where FDA oversight creates extended traceability premiums with limited incumbent specialization. Target implantable device packaging for cardiac and neuromodulation applications, leveraging optical testing investments to meet extended qualification protocols. Pursue hospital procurement committee relationships as the primary go-to-market channel rather than fabless designer direct sales. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier wire-bonding specialists without advanced packaging roadmaps, as chiplet-based heterogeneous integration fragments their core monolithic die service demand. Long-term viability favors substrate-captive OSATs with fan-out panel-level capacity and automotive qualification certifications. Watch for UCIe die-to-die interconnect standard adoption rates as the inflection signal for test program portability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Glass Core Substrate Qualification | Enables millimeter-wave signal integrity for AI training accelerators in Taiwan foundry ecosystems. |
| Fan-Out Panel-Level Capacity Expansion | Captures system-in-package demand from smartphone OEMs reducing qualified supplier lists. |
| Automotive Burn-In Cell Investment | Addresses AEC-Q100 Grade 0 thermal cycling requirements for ADAS powertrain modules. |
| Lead-Free Solder Alloy Development | Complies with EPA-aligned state RoHS and China GB standards for US-bound shipments. |
| Multi-Physics Simulation Talent Acquisition | Resolves electromagnetic-thermal-mechanical co-design scarcity for heterogeneous packages. |
Research Methodology
Coverage spans Taiwan, China, South Korea, Japan, and the United States, with primary inputs from each jurisdiction combining interviews with OSAT operations executives, fabless designer packaging procurement leads, automotive Tier 1 supplier quality directors, and semiconductor test equipment platform engineers. Secondary validation draws from SEC 10-K filings, TSMC technology symposium disclosures, EPA enforcement actions on fluorinated gases, and China MIIT industrial directive publications. Bottom-up capacity utilization models triangulate against top-down fabless design house spend allocations.
Segmentation granularity extends to packaging format interconnect density tiers, testing methodology defect screening intensity levels, end-use reliability specification categories, and material substrate thermal conductivity bands across the projection horizon. CAGRs derive from installed base replacement cycles for wire-bonding equipment, AI accelerator unit shipment trajectories, and automotive semiconductor content-per-vehicle expansion curves. Forecast inputs incorporate foundry capacity expansion timelines, dual carbon policy compliance cost trajectories, and substrate chemical supplier allocation announcements.
Several conditions sit outside the modeled scope, including unforeseen EPA regulatory acceleration on lead-free solder compositions, sudden ABF substrate supply disruptions from seismic events in Japan, and military conflict scenarios affecting Taiwan Strait logistics corridors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
2.5D and 3D Semiconductor Packaging Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Bonding Wire Packaging Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
System in Package (Sip) Technology Market