
 Global MEMS and Sensors Market | 2026-2036
Global MEMS and Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global MEMS and Sensors Market Foresight
Automotive-grade qualification standards is rotating the competitive landscape toward suppliers capable of AEC-Q100 and ISO 26262 certification. Robert Bosch GmbH leverages its captive foundry network in Reutlingen to sustain margins on high-reliability pressure and inertial sensors. STMicroelectronics anchors its position through deep partnerships with European automotive OEMs for LiDAR and motion-sensing modules. Texas Instruments competes on signal-conditioning integration, bundling MEMS front-ends with proprietary ADC and amplifier architectures.
Micro-electromechanical systems and sensors are micron-scale devices that integrate mechanical structures, transducers, and electronic circuits on silicon substrates, typically fabricated through bulk micromachining, surface micromachining, or wafer-level packaging processes with feature resolutions below one micrometer. They convert physical phenomena—acceleration, pressure, thermal gradients, magnetic fields, or optical interference—into electrical signals for real-time monitoring and closed-loop control in industrial, vehicular, and biomedical environments. Capacitive and piezoelectric technologies dominate volume production due to mature CMOS-compatible foundry flows, while optical interferometry and resonant architectures capture premium pricing in aerospace and diagnostic equipment where precision exceeds conventional thresholds. Pressure sensors and gyroscopes occupy the largest revenue pools in automotive and consumer applications, whereas magnetic sensors and optical sensors are expanding fastest as robotics manufacturers and security solution companies adopt position-sensing and spectral-analysis capabilities.
The EPA enforces emissions-monitoring mandates that require automotive OEMs to embed high-accuracy pressure and gas sensors, while the EU Green Deal and REACH restrict hazardous substances in MEMS fabrication chemistries, reshaping material sourcing for European suppliers. FDA and ISO 13485 compliance gates create barriers for medical device entrants, concentrating diagnostic equipment sensor supply among established players with validated quality systems. Stakeholders must track how automotive electrification timelines and evolving semiconductor export controls from the US Department of Commerce and China's MIIT alter cross-border supply availability for advanced sensing components.
Market Dynamics
Automotive electrification timelines and the EU AI Act are compressing sensor qualification cycles while fragmenting procurement across captive foundries and merchant suppliers. Tier-1 integrators now demand simultaneous AEC-Q100 and ISO 26262 certification, forcing mid-scale vendors to choose between capital-intensive compliance exits or strategic partnerships with certified incumbents.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon coolants accelerates demand for refrigerant leak-detection sensors in commercial HVAC and cold-chain logistics across Germany, France, and Italy.
- Electric powertrains:Battery management systems require high-precision current and thermal sensors, with automotive OEMs in Japan and South Korea expanding sensor counts per vehicle by 40-60 units.
- Wafer-level packaging:Cost reduction through 3D integration and through-silicon via processes enables MEMS penetration into disposable medical diagnostics and consumer wearables.
Market Restraints
- Specialty gas supply concentration:Xenon and neon feedstock for deep reactive-ion etching concentrates in Ukrainian and Russian purification facilities, exposing European MEMS foundries to input volatility.
- Photonic substitution:Fiber-optic gyroscopes and chip-scale atomic clocks displace high-end MEMS inertial sensors for navigation-grade aerospace applications.
- REACH substance restrictions:ECHA classification of certain organometallic precursors as Substances of Very High Concern forces reformulation of piezoelectric thin-film deposition chemistries.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor and sensor manufacturing attract packaging and test investments targeting domestic automotive and industrial automation demand.
- Digital health mandates:FDA guidance on continuous glucose monitoring and remote patient monitoring creates regulatory tailwind for wearable biosensor platforms integrating MEMS pressure and thermal elements.
- Edge AI convergence:Integration of MEMS microphones and accelerators with neural processing units enables on-device inference for voice authentication and predictive maintenance in smart buildings.
Industry Challenges
- Functional safety certification backlog:ISO 26262 ASIL-D validation for automotive pressure and inertial sensors requires 18-24 month timelines, constraining new entrant market access.
- Packaging-engineering scarcity:Hermetic sealing and stress-isolation design for harsh-environment sensors outstrips available talent pools in Germany, Japan, and the US.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global MEMS and Sensors Market |
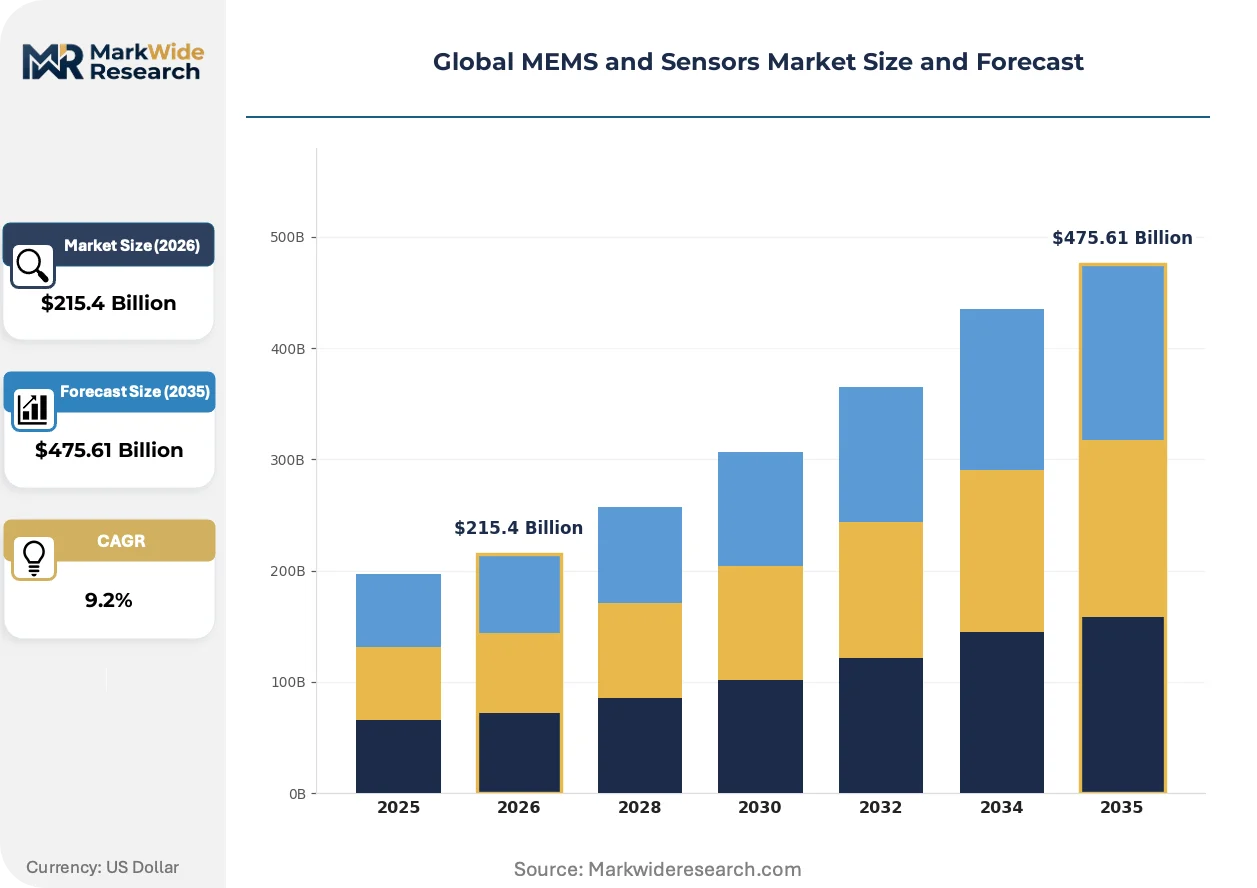
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $475.61 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, Pressure Sensors, Temperature Sensors, Magnetic Sensors, Optical Sensors Technology: Capacitive, Piezoelectric, Resonant, Optical Interferometry, Thermal, Piezoresistive Application: Consumer Electronics, Industrial Automation, Aerospace Systems, Medical Devices, Environmental Monitoring, Smart Home End User Industry: Smartphones & Wearables, Automotive OEMs, Robotics Manufacturers, Diagnostic Equipment Providers, Agriculture Technology Firms, Security Solution Companies |
| Companies Covered | Robert Bosch GmbH, STMicroelectronics, Broadcom Inc., Analog Devices Inc., Invensense Inc. (TDK Corporation), Murata Manufacturing Co., Ltd., Texas Instruments, Qorvo Inc., Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global MEMS and Sensors Market Shifts & Advancements
Silicon photonics and heterogeneous integration are dissolving traditional boundaries between optical, mechanical, and electronic sensing domains. Foundry-service models now extend from CMOS-compatible MEMS through advanced packaging, compressing time-to-market for multi-physics sensor modules.
Monolithic integration of photonic waveguides with MEMS actuators is decomposing the discrete optical bench architectures that previously dominated telecom and LiDAR applications. Automotive LiDAR manufacturers in Germany and Japan are adopting silicon photonic phased arrays to replace macroscopic scanning mechanisms. This convergence collapses assembly steps and thermal management complexity while enabling wafer-scale test economics previously unavailable to optical sensors.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of MEMS release-layer chemistries and lubricant coatings. European foundries in Reutlingen and Grenoble are qualifying fluorine-free alternatives for stiction prevention in accelerometer comb drives. The transition extends qualification timelines by 12-18 months but secures long-term market access for automotive and medical device exports to the EU.
Automotive OEMs are consolidating sensor procurement through direct foundry relationships rather than traditional distributor channels. Tier-1 suppliers in South Korea and the US are establishing multi-year capacity reservations with Reutlingen and Singapore packaging houses. This disintermediation transfers inventory risk downstream while rewarding suppliers with proven AEC-Q100 track records and captive capacity commitments.
Global MEMS and Sensors Market Segmentation
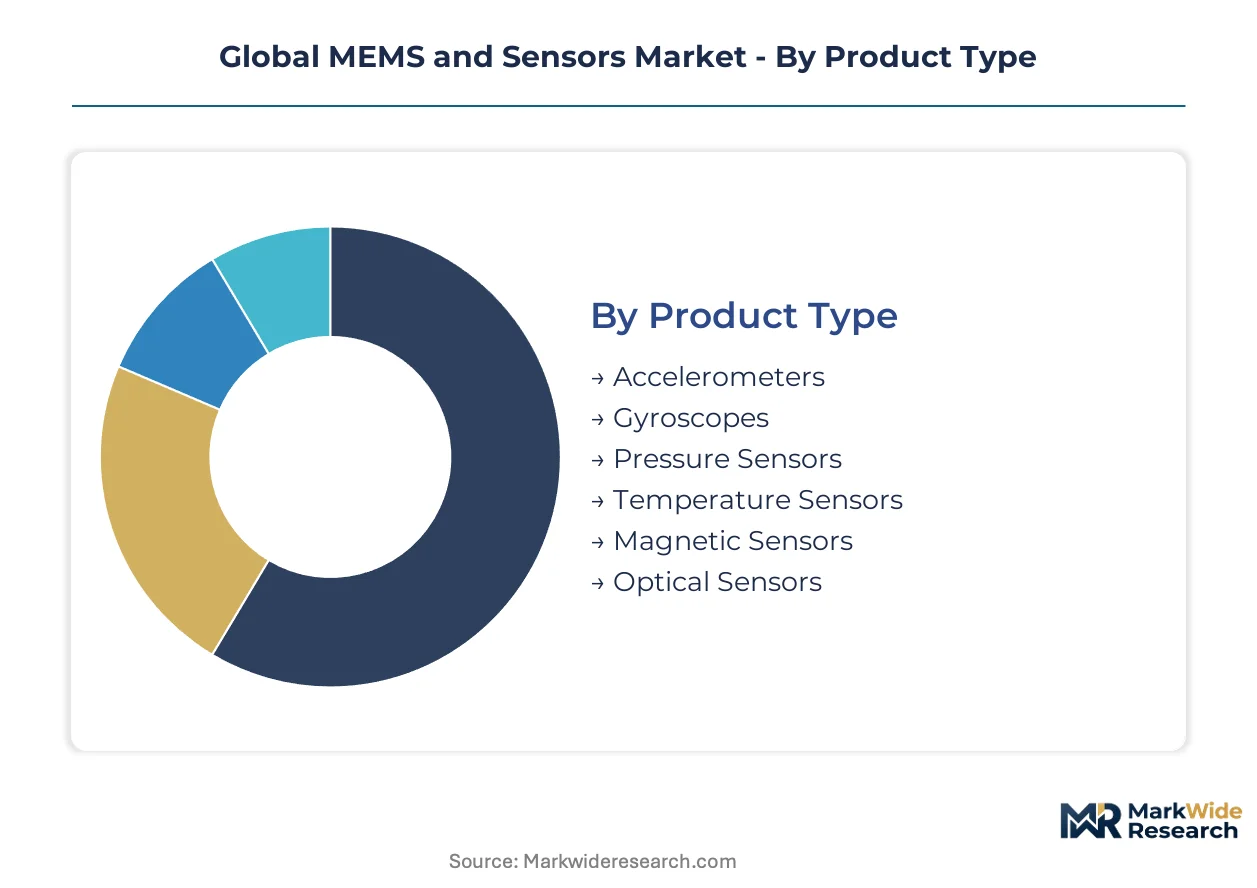
MEMS and sensors fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and qualification barriers. Procurement patterns diverge sharply between automotive-grade reliability requirements and consumer-electronics cost sensitivity.
Product Type:
Photonic substitution pressures vary dramatically across device categories, with inertial sensors facing the most severe displacement threat from fiber-optic alternatives.
- Pressure Sensors:Piezoresistive and capacitive diaphragm structures dominate automotive powertrain and HVAC applications. Demand concentrates in Germany and Japan where OEMs embed 8-12 units per electric vehicle for battery thermal management and refrigerant leak detection under EU F-Gas Regulation mandates.
- Gyroscopes:MEMS Coriolis vibratory architectures capture consumer stabilization and automotive navigation, though ring-laser and fiber-optic alternatives displace them in aerospace-grade applications. South Korean smartphone manufacturers and Japanese automotive Tier-1s drive procurement volumes.
- Accelerometers:Differential capacitive comb-drive designs enable airbag deployment and consumer motion sensing.
- Temperature Sensors:Thermopile and resistive thermal devices monitor battery packs and industrial process control.
- Magnetic Sensors:Hall-effect and magnetoresistive elements support position sensing in robotics and automotive brushless motors.
- Optical Sensors:Photodiode arrays and spectral analyzers expand in environmental monitoring and biometric security.
Pressure sensors retain volume leadership; optical sensors hold the steepest expansion curve.
Technology:
Cost tier stratification separates mature CMOS-compatible flows from premium resonant and interferometric architectures requiring specialized foundry partnerships.
- Capacitive:Comb-drive and parallel-plate transduction dominates accelerometer and gyroscope production through standard surface micromachining. Germany's Reutlingen cluster and Singapore packaging houses serve automotive OEMs demanding AEC-Q100 qualification at million-unit scale.
- Piezoelectric:Aluminum nitride and PZT thin-film deposition enables energy harvesting and high-frequency resonators. Japan's precision ceramics suppliers and South Korea's materials science clusters support industrial automation and diagnostic equipment applications.
- Piezoresistive:Diffused or implanted silicon strain gauges form the backbone of pressure sensing.
- Thermal:Thermopile and hot-wire anemometry address flow and gas sensing.
- Resonant:Quartz and silicon MEMS resonators deliver frequency references.
- Optical Interferometry:Photonic waveguide integration enables LiDAR and spectral analysis at wafer scale.
Capacitive processes anchor production economics; optical interferometry commands the highest value-add per wafer.
Application:
Customer type fragmentation splits procurement between specification-driven industrial buyers and price-sensitive consumer electronics integrators.
- Consumer Electronics:Motion sensing, environmental awareness, and audio capture integrate into smartphones, earbuds, and wearables. South Korean and Chinese OEMs drive annual procurement cycles with 12-18 month product refresh timelines.
- Automotive Systems:ADAS, powertrain monitoring, and cabin environment control require ISO 26262 ASIL-B through ASIL-D certification. European and Japanese OEMs consolidate sourcing through direct foundry relationships rather than distributor channels.
- Industrial Automation:Vibration monitoring, predictive maintenance, and precision positioning support manufacturing digitization.
- Medical Devices:Continuous glucose monitors, blood pressure cuffs, and diagnostic imaging demand FDA and ISO 13485 compliance.
- Environmental Monitoring:Air quality, water quality, and agricultural sensors expand under regulatory monitoring mandates.
- Smart Home:Voice interfaces, occupancy detection, and climate control integrate MEMS microphones and thermal sensors.
Consumer electronics generates the highest unit volumes; medical devices sustain the most rigorous qualification premiums.
End User Industry:
Supply concentration clusters around foundry capacity with proven automotive and medical certification track records.
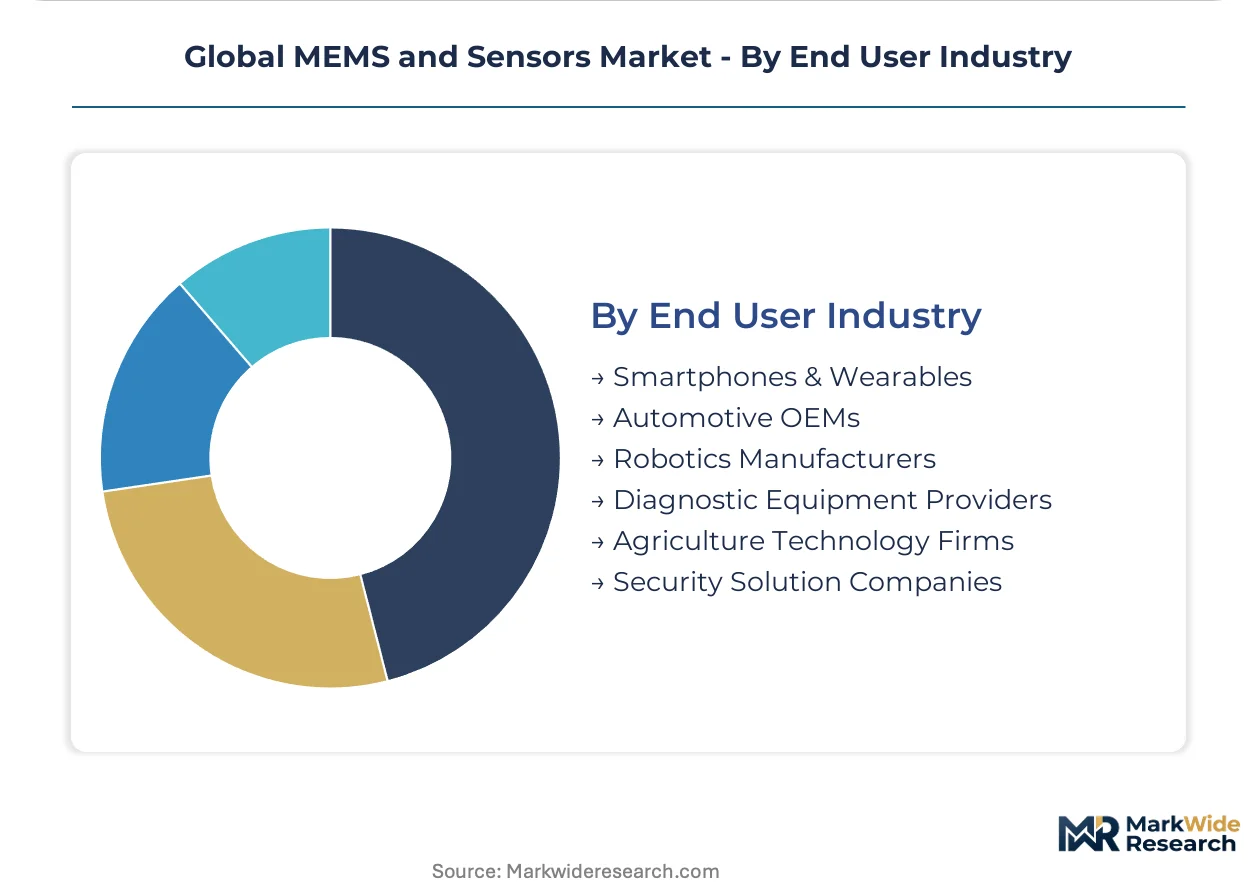
- Automotive OEMs:Electric powertrain electrification expands sensor counts per vehicle from 60-100 units in internal combustion platforms to 140-200 in battery electric architectures. Germany, Japan, and South Korea anchor design-in activity.
- Smartphones & Wearables:Annual device volumes exceeding one billion units drive commoditization pressure on inertial and environmental sensors. Chinese and South Korean OEMs dominate procurement with aggressive cost-down targets.
- Robotics Manufacturers:Force-torque, lidar, and joint-position sensing enable collaborative and mobile robot platforms.
- Diagnostic Equipment Providers:Point-of-care and imaging systems require validated supply chains under FDA and EMA oversight.
- Security Solution Companies:Biometric and perimeter sensing applications expand optical and thermal sensor demand.
- Agriculture Technology Firms:Soil moisture, crop health, and livestock monitoring drive environmental sensor deployment.
Automotive OEMs command the most stringent reliability requirements; robotics manufacturers represent the fastest-expanding design-win opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for specialty gases and precision foundry services tilts the trade balance toward net-importing positions in Europe and Asia, while the United States maintains selective export strength in design-intensive sensor architectures.
Germany
Automotive OEMs in Stuttgart and Munich embed 140-200 sensors per electric vehicle, driving procurement volumes for pressure and inertial modules. The EU F-Gas Regulation mandates refrigerant leak-detection sensors across commercial HVAC systems. The Reutlingen foundry cluster anchors captive production for AEC-Q100 qualified components serving domestic Tier-1 integrators.
Japan
Precision ceramics suppliers in Nagoya and Osaka support piezoelectric thin-film deposition for industrial automation and diagnostic equipment. METI's semiconductor revitalization policies channel funding toward MEMS packaging and test capacity expansion. The Kyushu silicon island hosts multiple 200mm MEMS-dedicated fabrication lines with proven automotive certification track records.
South Korea
Smartphone manufacturers in Seoul and Gyeonggi-do drive annual procurement cycles for motion-sensing and environmental modules with aggressive cost-down targets. The Ministry of Trade, Industry and Energy prioritizes domestic sensor supply chain resilience under national semiconductor strategies. The Busan-Ulsan corridor concentrates advanced packaging investments targeting automotive and robotics applications.
United States
EPA emissions-monitoring mandates require automotive OEMs to embed high-accuracy pressure and gas sensors in powertrain systems. FDA guidance on continuous glucose monitoring creates regulatory tailwind for wearable biosensor platforms. The Pacific Northwest and Greater Boston clusters concentrate design activity for optical interferometry and silicon photonic phased arrays.
India
Domestic automotive and industrial automation demand attracts packaging and test investments under the PLI scheme for semiconductor manufacturing. BIS certification requirements for electronic components shape local quality standards. The Karnataka and Tamil Nadu electronics corridors host emerging MEMS assembly operations serving regional medical device and automotive customers.
Global MEMS and Sensors Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and captive foundry access. The vendor base stratifies into three tiers: integrated conglomerates with captive silicon capacity, fabless design houses dependent on merchant foundries, and regional packaging specialists. Strategic moves concentrate on multi-year capacity reservations with certified packaging houses and direct OEM qualification bypassing traditional distribution channels.
Within the integrated conglomerate tier, Robert Bosch GmbH exemplifies European captive-foundry positioning, while STMicroelectronics anchors fabless-partnership models with deep automotive OEM relationships. Texas Instruments occupies a position emphasizing signal-conditioning integration. These three entities represent divergent approaches to sustaining margin position amid compressing qualification cycles and fragmenting procurement patterns.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| STMicroelectronics |
| Broadcom Inc. |
| Analog Devices Inc. |
| Invensense Inc. (TDK Corporation) |
| Murata Manufacturing Co., Ltd. |
| Texas Instruments |
| Qorvo Inc. |
| Infineon Technologies |
| Others |
Supply & Pricing Matrix
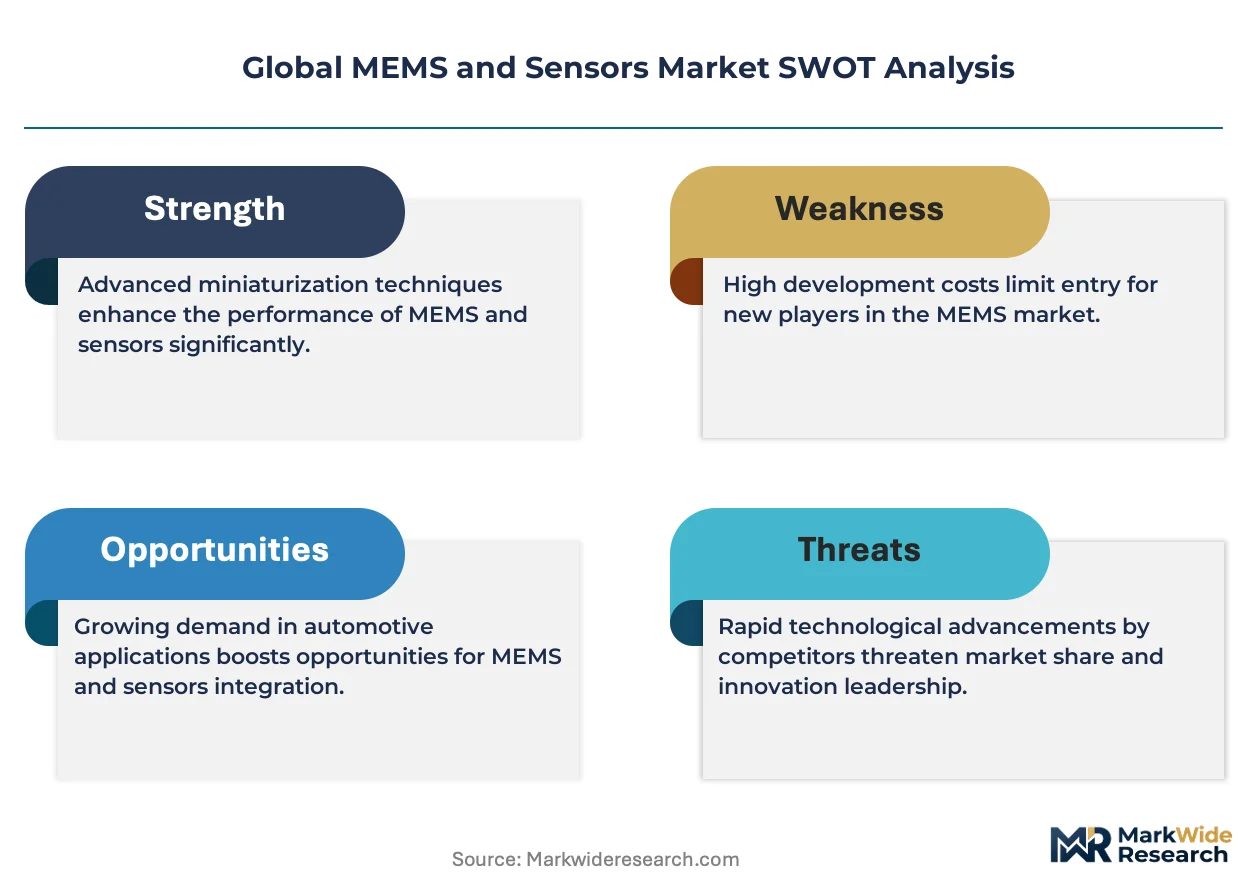
Photonic substitution in aerospace-grade inertial sensing simultaneously redistributes procurement geography toward fiber-optic specialists and compresses pricing power for MEMS vendors in navigation-tier segments. This displacement dynamic forces MEMS suppliers to defend automotive and industrial volumes where silicon economies retain cost advantages.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the MEMS and sensors market. Price differentiation stems from ISO 26262 ASIL certification grade and captive foundry access, with automotive-grade pressure modules commanding sustained premiums against commoditized consumer accelerometers. Cost compression in consumer-tier motion sensors is intensifying because South Korean smartphone manufacturers enforce annual cost-down targets exceeding historical norms. Chinese OEMs exhibit the highest price sensitivity, while German automotive Tier-1s prioritize qualification track records over unit economics.
Supply Chain Analysis
Inventory buffers for specialty gases now stretch 20-30 weeks beyond standard foundry lead times, exposing European MEMS producers to input volatility. Supply concentrates in Germany, Japan, and South Korea, where Reutlingen, Kyushu, and Busan-Ulsan clusters host AEC-Q100 qualified fabrication and packaging capacity. Raw material dependencies center on xenon and neon feedstock for deep reactive-ion etching, aluminum nitride sputtering targets, and fluorine-free release-layer chemistries under REACH reformulation mandates. Single-source vulnerability in Ukrainian and Russian noble gas purification facilities poses structural risk. Distribution runs through direct foundry relationships rather than traditional distributor channels as automotive OEMs consolidate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MEMS and sensors market is entering a cyclical recovery phase driven by automotive electrification timelines that expand sensor counts per vehicle. OEM procurement consolidation creates windows for qualified suppliers to secure multi-year capacity reservations.
For Market Incumbents: Secure captive foundry expansion in Reutlingen or Singapore packaging houses to lock in AEC-Q100 capacity before qualification backlogs extend further. Deepen ISO 26262 ASIL-D certification portfolios to defend against photonic substitution in navigation-grade applications. Channel control through direct OEM relationships transfers inventory risk downstream while sustaining margin position. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for continuous glucose monitoring biosensors open white-space penetration in wearable medical devices. Target India's PLI-supported packaging corridors for automotive and industrial automation demand with lower certification barriers than European markets. A foundry-partnership go-to-market model bypasses capital-intensive captive fabrication investments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless design houses holding automotive qualification track records but lacking captive capacity. Five-to-ten year viability hinges on consolidation into integrated conglomerates with merchant foundry access. The signal to watch is Tier-1 procurement consolidation velocity as OEMs bypass distributors for direct foundry relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Capacity Reservation | Locks AEC-Q100 qualified wafer starts for German automotive OEM electrification programs. |
| ISO 26262 ASIL-D Certification Investment | Opens design-win access for battery management system pressure and thermal sensors. |
| Fluorine-Free Chemistry Qualification | Secures REACH-compliant release-layer processes for EU medical device export eligibility. |
| Silicon Photonic Phased Array Development | Enables wafer-scale LiDAR manufacturing for German and Japanese automotive programs. |
| India PLI Packaging Partnership | Captures cost advantages in Busan-Ulsan corridor for regional automotive demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with MEMS foundry engineering directors, automotive Tier-1 procurement leads, FDA regulatory affairs specialists, and industrial automation OEM technical buyers. Secondary validation drew from EPA emissions-monitoring mandates, EU F-Gas Regulation implementation guidance, FDA 510(k) clearance databases, and METI semiconductor revitalization policy documents. Bottom-up unit economics triangulated against top-down market sizing across product type, technology node, and application segments.
Across the analysis window, volume and value outputs were modeled through segmented demand projection incorporating automotive electrification sensor-per-vehicle trajectories, consumer electronics refresh cycles, and medical device regulatory approval timelines. CAGRs were derived from fitted growth curves adjusted for foundry capacity constraints and specialty gas supply volatility. Forecast inputs included OEM direct procurement consolidation rates, REACH substance restriction implementation schedules, and photonic substitution penetration in aerospace navigation tiers.
Decision-makers should treat outputs as directional under assumptions of sustained automotive electrification investment and stable noble gas supply chains; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Global Smart Biosensors Market