
 Europe Wearable Sensors Market | 2026-2036
Europe Wearable Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wearable Sensors Market Foresight
Healthcare is rebalancing away from fitness-centric applications toward clinical-grade remote monitoring across European hospital networks. Bosch Sensortec leverages its MEMS fabrication depth to supply inertial measurement units for fall-detection wearables deployed in German rehabilitation clinics. Infineon Technologies anchors the NFC secure-element segment, powering contactless health-data authentication in French and Dutch pilot programs. NXP Semiconductors competes on ultra-low-power microcontroller integration, extending battery life for continuous glucose monitoring patches.
Europe wearable sensors are miniature transducers—typically combining accelerometers, gyroscopes, photoplethysmography arrays, and temperature-sensitive thin films—that convert biomechanical and biochemical signals into digital outputs for real-time health analytics. Fabrication relies on silicon-on-insulator wafers and MEMS etching processes to achieve sub-millimeter form factors with milliwatt power budgets. Smartwatches still occupy the largest revenue pool, though health monitors represent the fastest-expanding category as reimbursement codes for remote patient monitoring solidify across EU member states. Bluetooth dominates the technology layer due to its native integration with smartphones and hospital gateway infrastructure, while Zigbee retains niche traction in industrial safety wearables for lone-worker protection.
The EU Medical Device Regulation (MDR) and CE marking framework mandate clinical validation and post-market surveillance for wearable sensors claiming diagnostic utility, raising compliance costs but also creating barriers against low-quality imports. EMA guidance on software-as-a-medical-device further shapes how algorithm-enabled wearables gain market access. Stakeholders must monitor whether the EU AI Act's risk-classification rules will sweep predictive health-analytics algorithms into high-risk categories, forcing additional conformity assessments.
Market Dynamics
EU Medical Device Regulation (MDR) compliance costs are compressing vendor margins while simultaneously erecting barriers against non-EU imports, fundamentally restructuring competitive positioning across the European wearable sensors landscape.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:Germany, France, and the United Kingdom have established dedicated reimbursement codes for continuous glucose monitoring and cardiac telemetry wearables, accelerating hospital procurement cycles.
- Bluetooth Low Energy Integration:Native smartphone compatibility and gateway infrastructure in European hospital systems is reducing deployment friction for connected health monitors.
- EU Green Deal Circular Economy Requirements:Battery-replaceable and recyclable sensor designs are gaining preferential procurement status in Dutch and Scandinavian public health tenders.
Market Restraints
- Silicon-on-Insulator Wafer Supply Concentration:MEMS fabrication depends on concentrated 200mm SOI substrate supply from French and German foundries, creating input vulnerability.
- MDR Clinical Validation Burden:Post-market surveillance obligations and notified body bottlenecks extend time-to-revenue for diagnostic-claim wearables by 18-24 months.
- Photoplethysmography Accuracy Limitations:Skin tone variation and motion artifact persist as unsolved technical constraints limiting clinical-grade adoption in melanin-rich patient populations.
Strategic Opportunities
- Eastern European Hospital Modernization:Poland, Romania, and Czech Republic are deploying EU cohesion funds to digitize rural healthcare infrastructure, creating first-mover openings for remote monitoring vendors.
- EU AI Act High-Risk Algorithm Classification:Predictive health analytics modules face impending conformity assessment requirements, favoring established players with regulatory affairs capabilities.
- Photonic-Electronic Convergence:Integration of silicon photonics with CMOS readout circuits enables multi-analyte biochemical sensing in single wearable patches.
Industry Challenges
- Biomedical Algorithm Validation Talent Scarcity:Clinical data science and regulatory statistics expertise required for MDR technical documentation outstrips European labor pool supply.
- Notified Body Capacity Constraints:CE marking queue times for software-as-a-medical-device wearables stretch beyond 12 months, compressing product launch windows.
- Legacy Hospital Gateway Integration:HL7 FHIR interoperability with entrenched electronic health record systems demands bespoke middleware development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wearable Sensors Market |
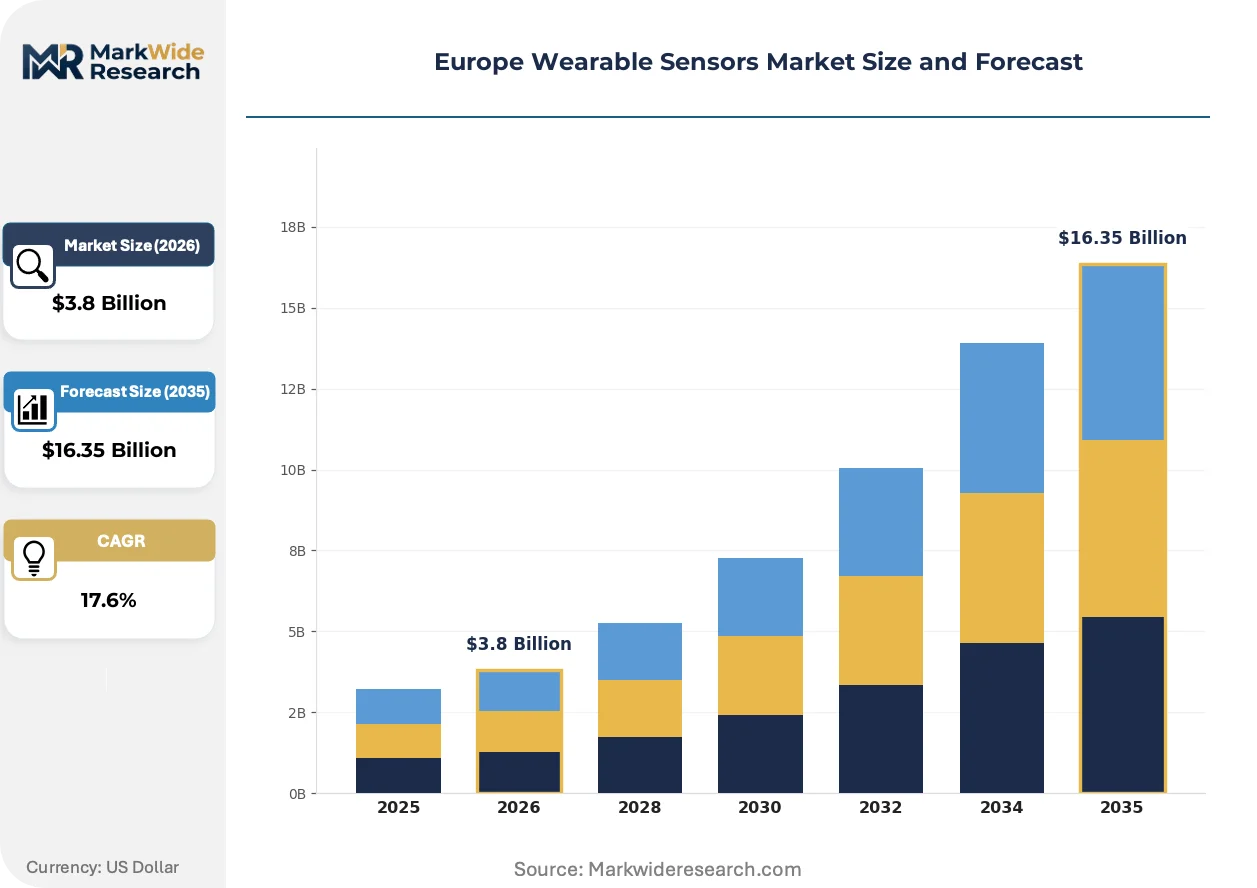
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Health Monitors Technology: Bluetooth, NFC, Wi-Fi, Zigbee Application: Healthcare, Sports, Industrial, Home Automation End User: Consumers, Hospitals, Fitness Centers, Enterprises |
| Companies Covered | STMicroelectronics, Infineon Technologies, Texas Instruments, Analog Devices, Panasonic Corporation, NXP Semiconductors, TE Connectivity, Bosch Sensortec, InvenSense, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wearable Sensors Market Shifts & Advancements
Sensor miniaturization and energy harvesting are converging to enable battery-free continuous monitoring, while regulatory frameworks race to catch up with algorithmic diagnostic capabilities.
Printed electronics on flexible polyimide substrates is electrifying form factor possibilities for epidermal patches. German rehabilitation clinics and French home-care networks are piloting sub-millimeter thickness temperature and strain sensors that conform to skin topography. This convergence of materials science and biocompatibility engineering is compressing the boundary between consumer wellness and clinical-grade devices.
EMA guidance on software-as-a-medical-device is reshaping algorithm deployment architectures. Wearable manufacturers must now maintain technical documentation trails for machine learning model updates, forcing modular cloud-edge partitioning. Cardiac arrhythmia detection wearables face the steepest compliance burden, with Dutch and Belgian notified bodies demanding prospective clinical validation cohorts.
Hospital procurement departments in the United Kingdom and Nordic markets are consolidating vendor relationships around full-stack remote monitoring platforms rather than discrete sensor hardware. National Health Service trusts now specify outcome-based contracts tying sensor deployment fees to measurable reduction in emergency department admissions. This reconfiguration favors integrated solution providers with clinical workflow integration capabilities over component specialists.
Europe Wearable Sensors Market Segmentation
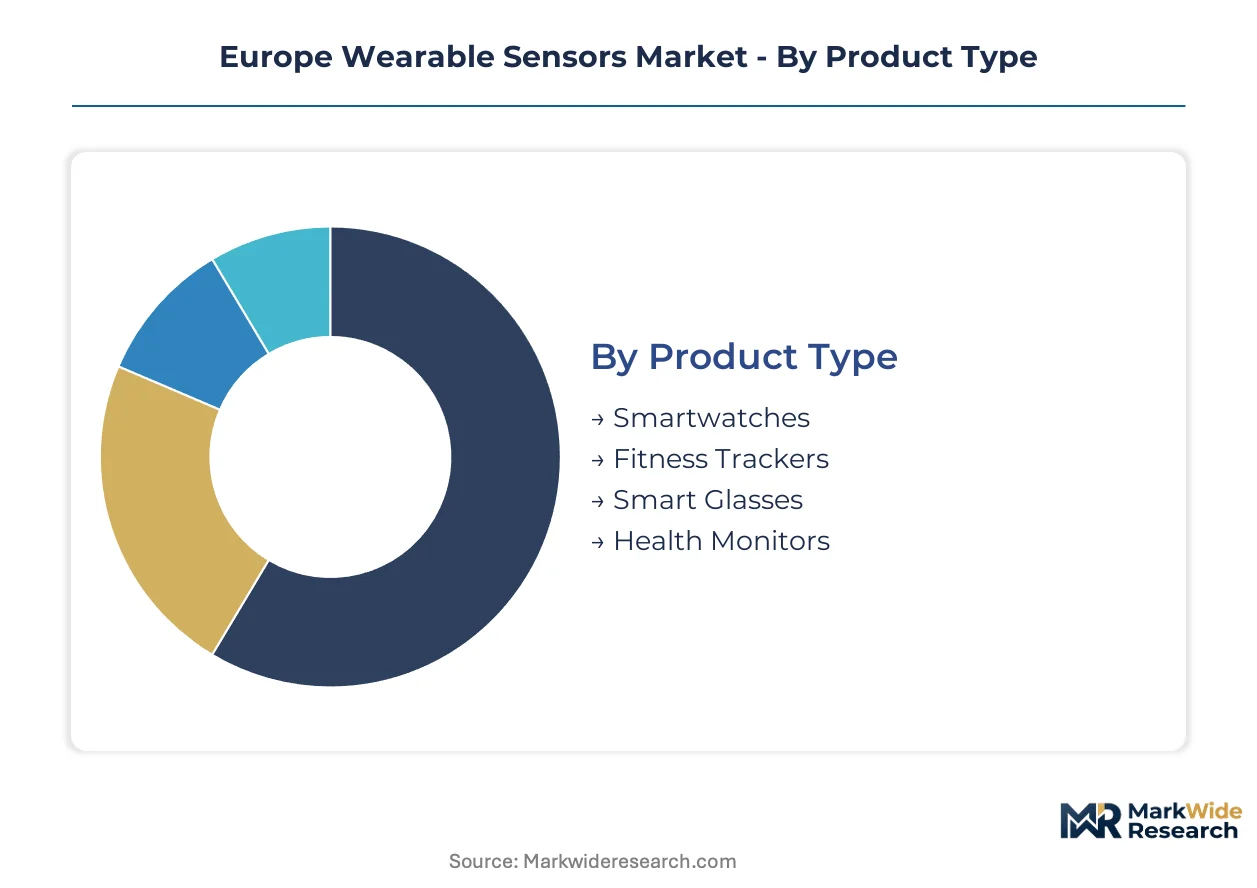
Wearable sensors in Europe fragment across four distinct dimensions that shape procurement priorities and margin structures. Product type determines reimbursement eligibility under national health systems, while technology choice dictates interoperability with existing hospital infrastructure.
Product Type:
Hospital procurement departments weight clinical validation depth differently than consumer electronics retailers.
- Smartwatches:Multi-sensor wrist-worn devices integrating accelerometers, gyroscopes, and photoplethysmography for heart rate and SpO2 monitoring. German and French insurers now reimburse specific models for cardiac telemetry, shifting procurement from retail channels to hospital supply chains.
- Health Monitors:Dedicated single-purpose devices including continuous glucose monitoring patches and fall-detection pendants. United Kingdom NHS trusts specify these for remote patient monitoring programs, with reimbursement codes accelerating deployment in diabetes and geriatric care.
- Fitness Trackers:Activity-focused wristbands with step counting and sleep staging capabilities. Consumer demand concentrates in Netherlands and Scandinavian markets where employer wellness subsidies offset purchase costs.
- Smart Glasses:Head-mounted displays with integrated eye-tracking and environmental sensors. Industrial safety applications in German manufacturing and French logistics drive niche adoption for hands-free workflow guidance.
Smartwatches lead volumes today; health monitors are gaining share fastest.
Technology:
Power budgets and gateway compatibility determine technology selection across European deployment contexts.
- Bluetooth:Low-energy protocol dominating smartphone-native health monitors. Native integration with iOS and Android ecosystems reduces middleware development costs for Dutch and Belgian hospital gateway projects.
- NFC:Near-field communication enabling secure contactless health-data authentication. French and Dutch pilot programs deploy NFC secure elements for patient identity verification in clinical wearables.
- Wi-Fi:Higher-bandwidth connectivity for streaming-rich sensor data in hospital environments. United Kingdom NHS trusts specify Wi-Fi for inpatient monitoring where cellular coverage is unreliable.
- Zigbee:Mesh networking protocol retaining traction in industrial safety wearables. German lone-worker protection systems and Scandinavian oil-platform applications favor Zigbee for extended range without cellular dependency.
Bluetooth captures the largest installed base; NFC is expanding most quickly in clinical authentication use cases.
Application:
Regulatory classification intensity varies sharply across application domains, with healthcare facing the steepest MDR compliance burden.
- Healthcare:Clinical-grade remote patient monitoring including cardiac telemetry, glucose management, and post-surgical recovery tracking. Germany, France, and United Kingdom reimbursement codes now cover continuous monitoring for chronic disease management.
- Sports:Performance optimization and injury prevention for amateur and professional athletes. Nordic markets show concentrated demand for ski and cycling biomechanics sensors.
- Industrial:Worker safety monitoring including fatigue detection, gas exposure alerts, and fall detection. German manufacturing and French construction sectors drive procurement through occupational safety mandates.
- Home Automation:Gesture control and environmental sensing integration with smart home ecosystems. Netherlands and Scandinavian consumer markets favor these for elderly independent living support.
Healthcare commands premium pricing today; industrial safety is climbing the fastest as EU workplace directives tighten.
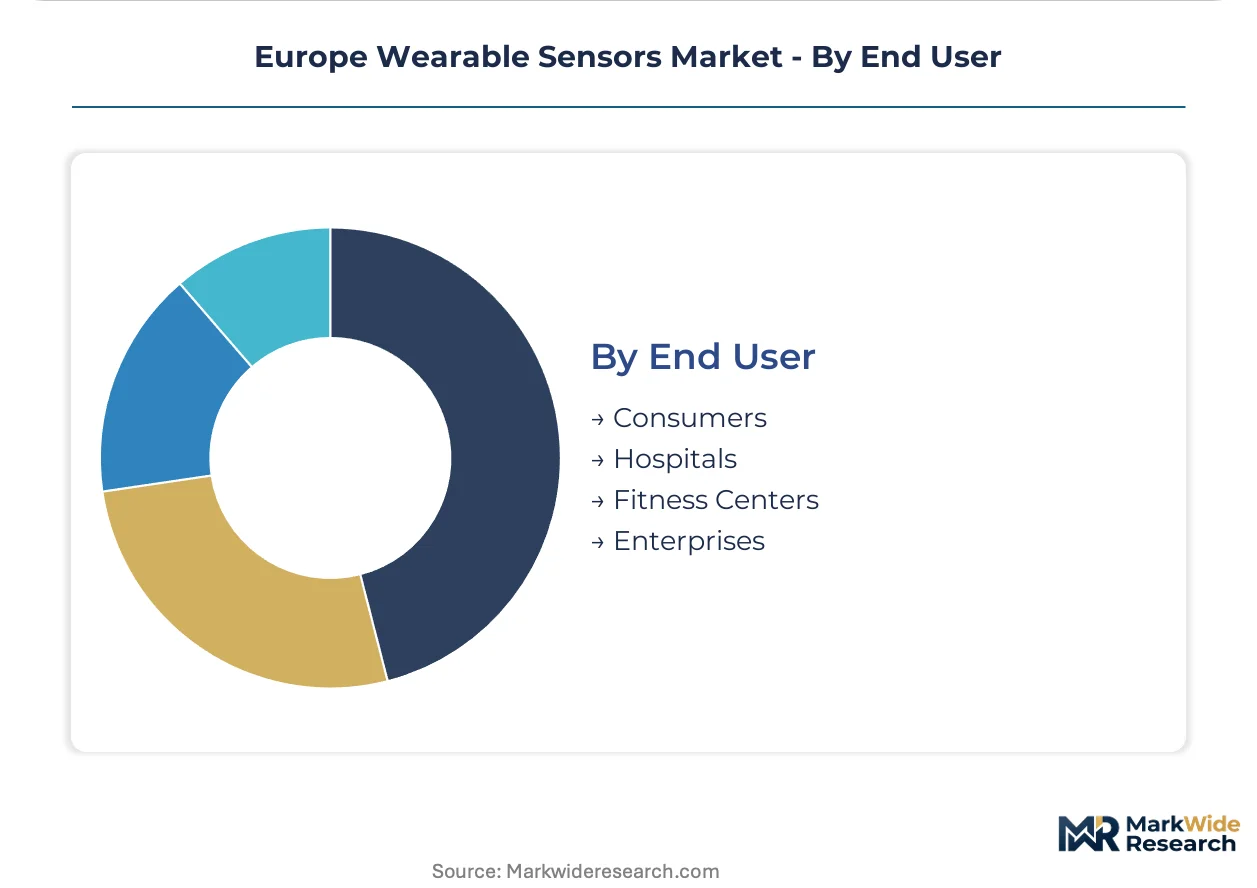
End User:
Budget authority and outcome accountability shape purchasing behavior across user categories.
- Hospitals:Acute care and outpatient clinic systems procuring through centralized tender processes. United Kingdom NHS trusts and German hospital networks now specify outcome-based contracts tying sensor fees to admission reduction metrics.
- Consumers:Individual purchasers through retail and direct-to-consumer channels. French and Italian markets show strong replacement-cycle demand for upgraded health-monitoring capabilities.
- Enterprises:Corporate wellness and occupational safety programs. German automotive manufacturers and French logistics operators deploy wearables for workforce health optimization.
- Fitness Centers:Gyms and sports clubs integrating member tracking into subscription services. Scandinavian boutique fitness chains lead adoption of recovery-monitoring wearables.
Hospitals drive the steepest revenue expansion; enterprises show the strongest volume growth in industrial safety applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German MEMS fabrication clusters anchor European wearable sensor supply chains, with hospital procurement networks in Munich and Stuttgart driving clinical-grade demand for remote patient monitoring devices.
Germany
Bavarian rehabilitation clinics and Stuttgart automotive wellness programs generate concentrated demand for fall-detection and cardiac telemetry wearables. The BfArM medical device regulator enforces MDR compliance timelines that extend product launch cycles by 18-24 months. Dresden and Reutlingen host MEMS foundry clusters supplying silicon-on-insulator substrates for sub-millimeter sensor fabrication.
United Kingdom
NHS trusts specify outcome-based contracts tying sensor deployment fees to emergency department admission reductions. NICE reimbursement guidance now covers continuous glucose monitoring for Type 1 diabetes patients. Cambridge and Oxford medical technology corridors attract wearable sensor startups targeting clinical validation pathways.
France
ANSM oversight of software-as-a-medical-device algorithms reshapes deployment architectures for cardiac arrhythmia detection wearables. The national health insurance system reimburses specific smartwatch models for cardiac telemetry under pilot programs. Paris-Saclay and Grenoble clusters concentrate photonics-electronics convergence research for multi-analyte biochemical sensing patches.
Netherlands
Dutch hospital gateway infrastructure favors Bluetooth Low Energy native integration for smartphone-compatible health monitors. The Health and Youth Care Inspectorate enforces post-market surveillance obligations for diagnostic-claim wearables. Eindhoven's high-tech campus anchors printed electronics development for flexible epidermal temperature and strain sensors.
Poland
EU cohesion fund deployment digitizes rural healthcare infrastructure across Mazovia and Silesian provinces, creating first-mover openings for remote monitoring vendors. The Office for Registration of Medicinal Products aligns national procedures with MDR clinical validation requirements. Krakow and Warsaw medical device distribution networks expand procurement capacity for hospital system modernization.
Europe Wearable Sensors Market Competitive Landscape
MDR compliance capacity expansion dominates the current landscape as vendors absorb notified body bottlenecks and extend technical documentation teams. The vendor base concentrates around semiconductor fabricators with in-house MEMS capabilities and fabless sensor designers outsourcing to European foundries. Two strategic archetypes prevail: integrated component suppliers controlling wafer-to-package fabrication, and modular platform vendors assembling third-party sensors into clinical-grade systems. Competitive moves center on regulatory affairs team scaling and notified body relationship cultivation.
Among European-anchored semiconductor specialists, STMicroelectronics, Infineon Technologies, and NXP Semiconductors exemplify the integrated fabrication archetype. STMicroelectronics occupies a position spanning consumer and clinical sensor markets through MEMS depth. Infineon Technologies anchors the secure-element segment for contactless health-data authentication. NXP Semiconductors represents ultra-low-power microcontroller integration for extended battery life in continuous monitoring applications. Each sits within distinct technology vectors—motion sensing, secure authentication, and power management—rather than direct product overlap.
| Leading Market Players |
|---|
| STMicroelectronics |
| Infineon Technologies |
| Texas Instruments |
| Analog Devices |
| Panasonic Corporation |
| NXP Semiconductors |
| TE Connectivity |
| Bosch Sensortec |
| InvenSense |
| Others |
Supply & Pricing Matrix
Family-owned MEMS fabrication specialists in southern Germany anchor wafer supply for European wearable sensor vendors, translating concentrated substrate ownership into disciplined pricing power that resists commoditization pressure from Asian competitors. Their captive control over silicon-on-insulator etching capacity allows margin defense against notified body cost inflation while shaping procurement terms for Dutch hospital gateway projects.
Pricing Analysis
Distributor margin compression in the United Kingdom and France is forcing vendors toward direct-to-hospital contracting models that bypass traditional medical device wholesalers. Three-tier pricing structure across premium clinical-grade, standard wellness, and economy fitness bands separates MDR-validated diagnostic wearables from consumer lifestyle trackers, with certification tier as the dominant price differentiation driver. Cost compression in the standard wellness segment is intensifying because Bluetooth module commoditization erodes hardware differentiation. Hospital procurement committees exhibit the lowest price sensitivity due to outcome-based contract structures, while fitness-focused consumers in Scandinavian markets show acute elasticity to subscription fee increases.
Supply Chain Analysis
Freight cost volatility from Asia-to-Europe semiconductor lanes is accelerating nearshoring momentum for MEMS packaging operations. Wafer fabrication concentrates in Germany and France, while final sensor assembly draws from Romania and Poland to leverage EU cohesion fund-supported manufacturing zones. Silicon-on-insulator substrates, photonics-grade indium phosphide, and medical-grade polyimide films constitute critical input dependencies. Single-source vulnerability in 200mm SOI wafer supply from Dresden-area foundries threatens production continuity for continuous glucose monitoring patch manufacturers. Distribution runs through specialized medical device logistics providers with cold-chain capabilities for temperature-sensitive biochemical sensors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Wearable Sensors Market functions as a stable compounder underpinned by irreversible hospital digitization mandates that lock in replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin pressure from Chinese module suppliers encroaching on Bluetooth Low Energy connectivity stacks by deepening backward integration into MEMS fabrication capacity in Reutlingen and Dresden clusters. Prioritize notified body relationship cultivation to compress CE marking queue times for software-as-a-medical-device updates. Defend hospital procurement relationships through embedded clinical workflow integration teams that reduce NHS trust switching costs. For New Entrants and Emerging Players: The gap between premium MDR-validated cardiac telemetry wearables and economy fitness bands without clinical claims offers white-space targeting for mid-tier vendors with rapid certification capabilities. Poland and Romania present the most penetrable geographies as EU cohesion fund deployment accelerates rural hospital modernization. Czech Republic distribution partnerships with established medical device wholesalers provide the most efficient go-to-market angle for remote patient monitoring hardware. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless sensor designers lacking in-house regulatory affairs capabilities relative to integrated fabrication specialists with notified body pre-certification. The five-to-ten-year viability framing favors acquisition targets with established EMA technical documentation trails and modular cloud-edge algorithm architectures. Fabless designers with proprietary photoplethysmography artifact correction IP represent the priority acquisition archetype. Watch for EU AI Act high-risk classification implementation timelines as the critical inflection signal for predictive health analytics module compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Compressed notified body queue times unlock 18-month revenue acceleration for cardiac telemetry vendors. |
| Hospital System Partnership | NHS trust outcome-based contracts tie sensor deployment fees to measurable emergency admission reductions. |
| Software Companion Development | EMA-compliant algorithm update trails satisfy MDR post-market surveillance for arrhythmia detection wearables. |
| Backward Integration into MEMS | Captive wafer fabrication in Dresden clusters defends margin against SOI substrate supply concentration. |
| Reimbursement Strategy | Germany BfArM and France ANSM pilot codes shift procurement from retail to hospital supply chains. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and hospital purchasing committees, regulatory filings with EMA and BfArM, and GPO contract databases — were reconciled against MEMS foundry capacity disclosures and Bluetooth module trade flow records. Conversations with Dutch Health and Youth Care Inspectorate officials, French ANSM software-as-a-medical-device reviewers, and United Kingdom NICE reimbursement specialists provided validation of clinical validation pathway timelines. Secondary sources included EMA guidance documents, EU Medical Device Regulation implementation reports, and hospital procurement tender databases. Bottom-up sensor shipment estimates and top-down healthcare IT spending allocations were triangulated to anchor volume projections.
Data-stream reconciliation across product type, technology protocol, application domain, and end-user budget authority dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Modeled inputs included reimbursement code expansion timelines in Germany, France, and the United Kingdom; notified body capacity constraints affecting software-as-a-medical-device queue times; and EU AI Act risk classification implementation for predictive health analytics algorithms.
The model assumes a particular technology adoption path; alternative pathways for photonic-electronic convergence in multi-analyte biochemical sensing would alter the outlook if silicon photonics integration accelerates faster than projected. Forecasts embed assumptions regarding MDR compliance cost absorption and notified body capacity expansion that may revise under sustained regulatory resource constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Artificial Intelligence (AI) Sensor Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Pressure Monitoring Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Anti-Collision Sensor Market