
 CO Gas Sensors Market | 2026-2036
CO Gas Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
CO Gas Sensors Market Outlook
East Asian semiconductor foundries is recalibrating wafer-fab cleanroom monitoring standards, tightening procurement specifications for electrochemical CO sensors. Honeywell International Inc. leverages its distributed building automation channel to anchor commercial HVAC retrofit demand. Siemens AG competes through IoT-enabled sensor architectures that integrate with industrial control networks. Alphasense specializes in compact electrochemical cells for portable safety instrumentation.
CO gas sensors detect carbon monoxide concentrations through electrochemical reaction, metal-oxide resistance change, or infrared absorption at specific wavelengths, typically measuring 0-500 ppm with alarm thresholds set between 35-50 ppm for life-safety applications. Electrochemical sensors dominate residential and industrial safety installations due to proven accuracy at low cost points, while infrared variants capture premium environmental monitoring contracts requiring interference immunity. IoT-enabled technology segments are expanding fastest as facilities managers demand cloud-connected predictive maintenance, though fixed installations still occupy the largest installed base.
OSHA permissible exposure limits and EPA ambient air quality guidelines shape product calibration requirements and replacement intervals in the United States, while EU ATEX directives and CE marking govern sensor deployment in potentially explosive European industrial atmospheres. Japan's METI energy efficiency standards additionally influence smart building sensor integration specifications. Stakeholders must monitor evolving harmonization between regional gas detection standards and emerging connected-device cybersecurity frameworks.
Market Dynamics
Electrochemical sensing miniaturization is compressing form factors while tightening detection thresholds, forcing incumbent suppliers to recalibrate manufacturing lines around MEMS-compatible architectures or cede portable instrumentation contracts to specialized component houses.
Growth Catalysts
- OSHA permissible exposure limits:United States manufacturing facilities face mandated sensor replacement cycles that sustain recurring revenue streams for fixed-installation suppliers.
- Wafer-fab cleanroom monitoring:East Asian semiconductor foundries are tightening procurement specifications for electrochemical CO sensors as contamination control protocols advance.
- Metal-oxide resistance technology:Low-cost variants are penetrating residential smoke-CO combination units in price-sensitive housing markets.
Market Restraints
- Palladium catalyst supply concentration:Russian and South African refining dominance creates input cost volatility for electrochemical cell manufacturers.
- Cross-sensitivity limitations:Hydrogen interference in metal-oxide sensors restricts deployment in battery charging facilities and hydrogen fueling stations.
- EU ATEX certification friction:Explosion-protection compliance timelines extend go-to-market schedules for industrial variants by six to nine months.
Strategic Opportunities
- India building code enforcement:Mandatory CO detection in commercial kitchens and hospitality venues remains underpenetrated relative to installed base potential.
- Predictive maintenance convergence:Cloud-connected electrochemical arrays combined with building management systems enable subscription-based monitoring services.
- Germany smart building retrofits:METI-aligned efficiency standards in Japan and corresponding EU Energy Performance of Buildings directives create synchronized replacement demand.
Industry Challenges
- Electrochemist talent scarcity:Specialized sensor calibration expertise concentrates in aging workforces across industrial gas detection OEMs.
- IEC 60079-29-1 recertification complexity:Evolving performance standards force redundant testing cycles for product lines spanning multiple detector technologies.
- Legacy 4-20mA integration:IoT-enabled sensors face protocol translation friction when retrofitting decades-old distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CO Gas Sensors Market |
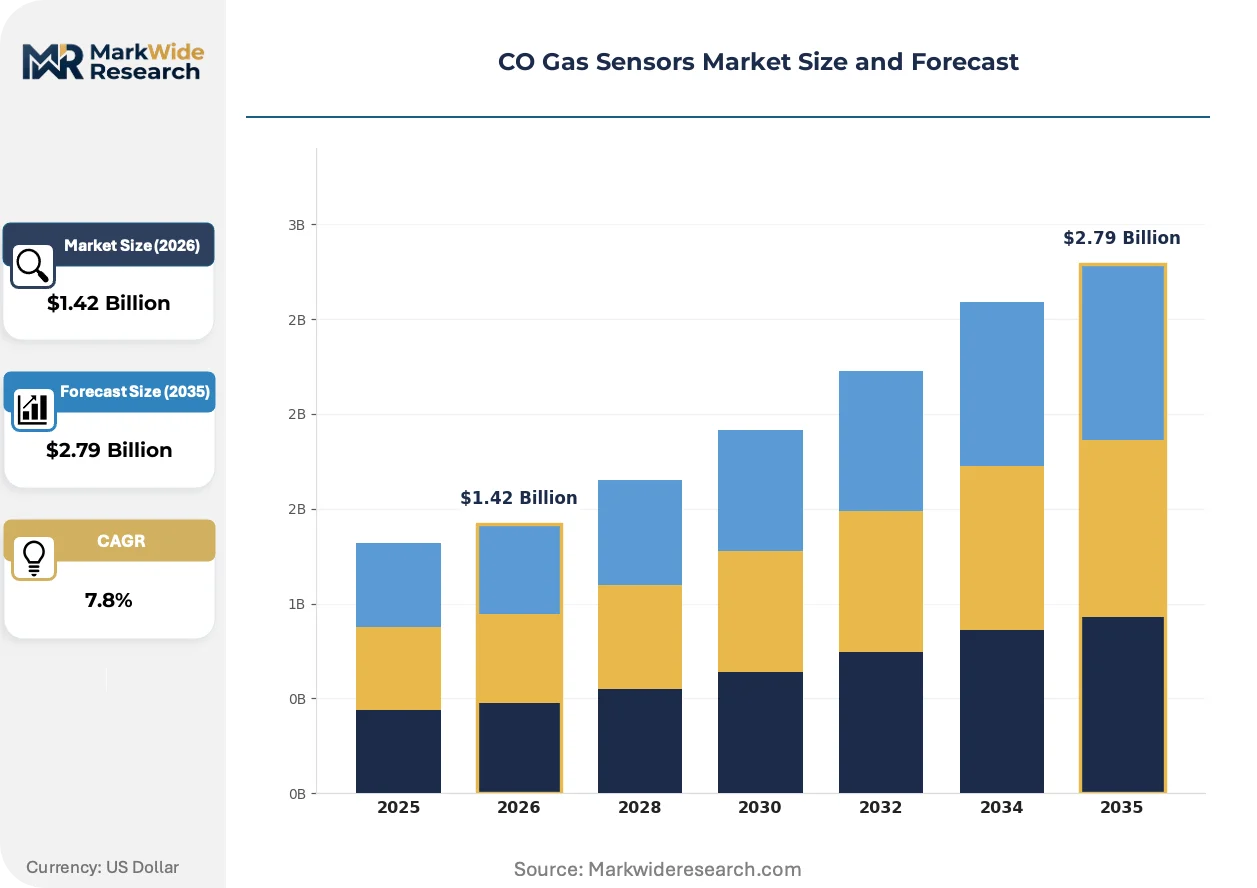
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Metal-Oxide Semiconductor, Infrared, Photoionization Technology: Portable, Fixed, Wireless, IoT-Enabled End User: Residential, Industrial, Commercial, Automotive Application: Indoor Air Quality, Industrial Safety, HVAC, Environmental Monitoring |
| Companies Covered | Aeroqual Ltd, ABB Ltd, Siemens AG, Robert Bosch GmbH, Alphasense, Honeywell International Inc., MSA Safety, Yokogawa Electric Corporation, Dynament Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CO Gas Sensors Market Strategic Shifts
Solid-state and optical detection modalities are encroaching on electrochemical dominance as end-users prioritize calibration intervals and interference immunity over unit cost. This technological rotation is compressing R&D allocation decisions across the supplier base.
Photonic integrated circuits for infrared absorption detection are expanding into pharmaceutical cleanroom applications where ppb-level sensitivity and zero-drift stability justify premium positioning. Aseptic manufacturing facilities in Switzerland and Ireland are piloting fiber-coupled sensors for continuous ambient monitoring. The technology is expanding into environmental monitoring contracts previously captured by gas chromatography reference methods.
Japan's METI has issued technical standards for smart building sensor interoperability that mandate open API architectures for CO detection nodes. Facility managers in Tokyo and Osaka metropolitan zones must now specify devices compatible with centralized energy management platforms. Sensor OEMs are responding by decoupling hardware from proprietary software stacks.
Specification authority has migrated from maintenance departments to corporate ESG officers who bundle CO monitoring into broader indoor air quality dashboards. German industrial conglomerates and US healthcare REITs now procure through integrated facilities management contracts rather than component-level tenders. This concentration is visible most acutely in London and Frankfurt commercial real estate portfolios undergoing BREEAM certification.
CO Gas Sensors Market Segmentation
CO gas sensor procurement patterns diverge sharply across installation contexts. Replacement cycles, calibration burdens, and connectivity requirements reshape how suppliers configure product portfolios for distinct buyer workflows.
Product Type:
Upgrade decisions pivot on detection threshold requirements and total cost of ownership across multi-year deployment horizons.
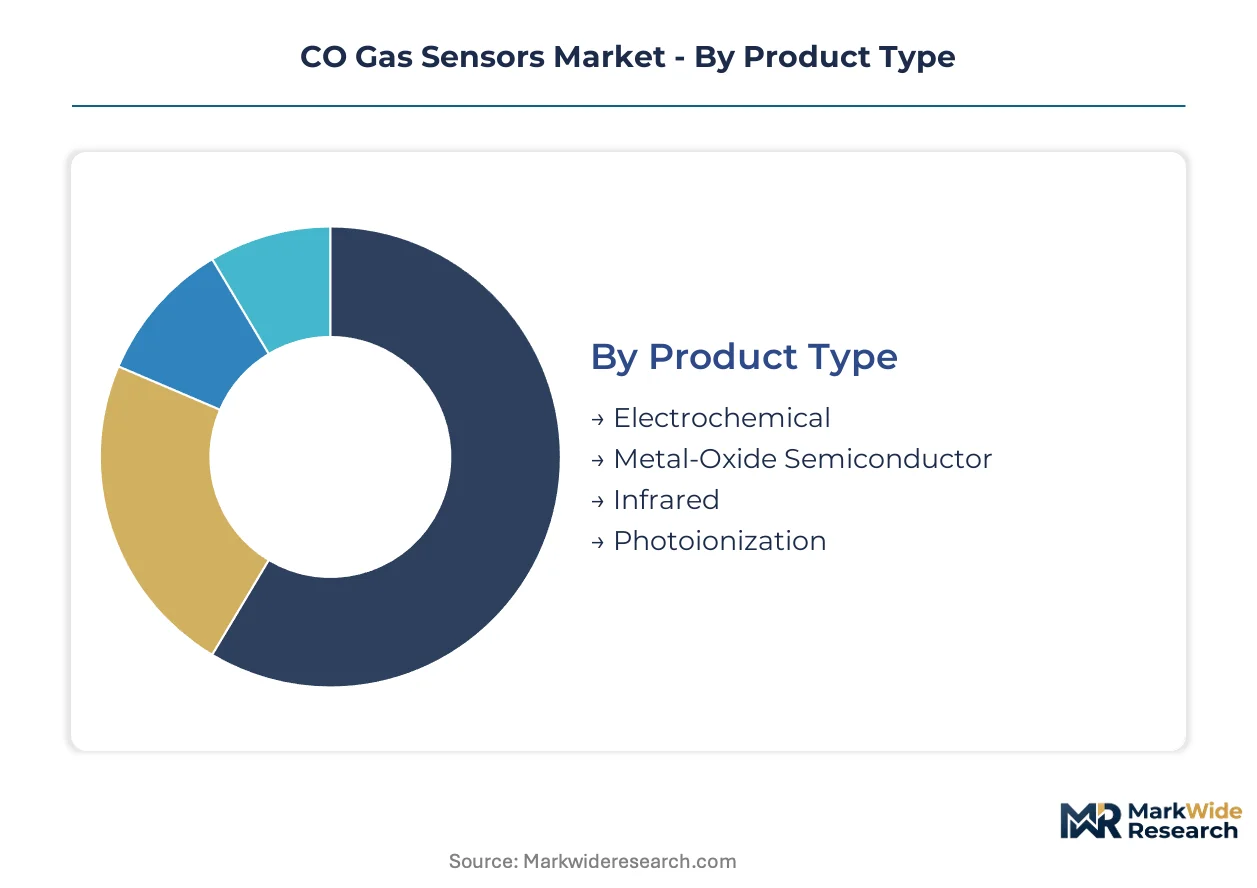
- Electrochemical:Amperometric cells with sulfuric acid electrolyte and platinum working electrodes dominate residential smoke-CO combination units. United States building code enforcement drives replacement volumes as landlords face mandated ten-year sensor lifespans.
- Metal-Oxide Semiconductor:Tin dioxide sensing layers on ceramic substrates offer lower unit costs at the expense of cross-sensitivity to humidity and hydrogen. Price-sensitive housing markets in India absorb these variants for basic residential alerting.
- Infrared:Non-dispersive absorption at 4.6 micrometers eliminates electrolyte degradation concerns. Pharmaceutical cleanrooms in Switzerland specify these for zero-drift stability over extended calibration intervals.
- Photoionization:Ultraviolet lamp excitation extends detection to volatile organic compounds alongside CO. Environmental remediation contractors deploy these for broad-spectrum site characterization.
Volume placements concentrate in Electrochemical; the faster expansion belongs to Infrared.
Technology:
Connectivity architecture determines margin capture through hardware-software bundling versus component-only sales.
- Portable:Handheld units with diffusion-based sampling serve confined-space entry protocols. Industrial safety officers in Germany specify these for maintenance turnaround inspections.
- Fixed:Hardwired installations with 4-20mA or Modbus outputs anchor manufacturing facility perimeter monitoring. OSHA-mandated replacement schedules sustain recurring revenue for established suppliers.
- Wireless:Battery-powered mesh networks eliminate cabling costs in retrofit commercial buildings. METI interoperability standards in Japan accelerate specification for smart building integration.
- IoT-Enabled:Cloud-connected electrochemical arrays feed predictive maintenance algorithms. Facilities management platforms in London commercial real estate bundle these into subscription-based indoor air quality services.
Fixed installations retain the largest installed base; IoT-Enabled configurations are climbing the fastest.
End User:
Buyer sophistication and procurement authority vary dramatically across installation settings.
- Residential:Smoke-CO combination alarms with sealed lithium batteries serve landlord compliance requirements. United States multifamily housing code adoption drives bulk procurement through electrical distributors.
- Industrial:Explosion-proof housings with ATEX certification protect oil refining and chemical processing environments. EU directive compliance extends supplier certification timelines.
- Commercial:Integration with building automation systems dominates hospitality and healthcare specifications. German Energy Performance of Buildings directives synchronize replacement demand across office portfolios.
- Automotive:Cabin air quality sensors with CAN bus interfaces monitor exhaust intrusion in parking structures and tunnels. Japanese OEMs lead integration with HVAC control modules.
Industrial applications generate premium pricing; Commercial segment procurement is gaining share fastest.
Application:
Use case specificity dictates sensor performance specifications and certification requirements.
- Indoor Air Quality:Low-ppm resolution with temperature compensation addresses ventilation optimization in schools and offices. ESG officers in US healthcare REITs bundle these into broader environmental dashboards.
- Industrial Safety:Rapid alarm response below OSHA permissible exposure limits protects workers in steel foundries and battery manufacturing. Replacement intervals are mandated rather than discretionary.
- HVAC:Demand-controlled ventilation sensors modulate fresh air intake based on occupancy-generated CO levels. Honeywell leverages building automation channels for commercial retrofit specifications.
- Environmental Monitoring:Reference-grade accuracy for regulatory compliance reporting in urban air quality networks. Infrared variants displace gas chromatography methods in Swiss and Irish pharmaceutical clusters.
HVAC retrofits drive current volume; Environmental Monitoring applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palladium catalyst refining concentrates in Russian and South African localities, creating input cost volatility that reshapes procurement strategies across manufacturing clusters in Germany, Japan, and the United States.
United States
OSHA-mandated sensor replacement cycles sustain recurring revenue for fixed-installation suppliers serving steel foundries and battery manufacturing plants. EPA ambient air quality guidelines shape calibration requirements for environmental monitoring networks. Houston petrochemical corridors and Pittsburgh industrial zones drive demand for explosion-proof housings with rapid alarm response capabilities.
Germany
EU ATEX directives govern sensor deployment in potentially explosive industrial atmospheres, extending supplier certification timelines by six to nine months. Energy Performance of Buildings directives synchronize replacement demand across commercial office portfolios. Bavarian automotive clusters and Ruhr industrial basins anchor specifications for IoT-enabled architectures that integrate with building management systems.
Japan
METI energy efficiency standards influence smart building sensor integration specifications, mandating open API architectures for CO detection nodes. Tokyo and Osaka metropolitan zones require devices compatible with centralized energy management platforms. Yokohama manufacturing corridors and Nagoya industrial zones specify CAN bus interface sensors for parking structure and tunnel applications.
China
GB standards and MIIT technical regulations shape domestic sensor certification requirements for industrial safety applications. Dual carbon goals accelerate demand-controlled ventilation sensor deployment in commercial buildings. Yangtze River Delta semiconductor foundries and Pearl River Delta electronics manufacturing clusters tighten procurement specifications for cleanroom monitoring applications.
Switzerland
Swissmedic and federal environmental ordinances establish reference-grade accuracy requirements for pharmaceutical cleanroom applications. Aseptic manufacturing facilities in Basel and Zurich metropolitan zones pilot fiber-coupled sensors for continuous ambient monitoring. Swiss pharmaceutical clusters specify infrared variants for ppb-level sensitivity and zero-drift stability over extended calibration intervals.
CO Gas Sensors Market Competitive Environment
Global majors compete with regional champions across electrochemical cell fabrication and IoT-enabled system integration. The supplier base organizes into three tiers: diversified industrial conglomerates with building automation channels, specialized electrochemical component houses, and emerging solid-state technology developers. Consolidation pressures favor players with captive palladium catalyst supply relationships or MEMS-compatible manufacturing architectures. Dominant competitive moves include strategic partnerships with facilities management platforms and backward integration into sensor calibration expertise.
Within the diversified industrial tier, Honeywell International Inc. and Siemens AG exemplify scale-driven positions anchored by distributed automation channels and industrial control network integration. Alphasense occupies a specialist position representing compact electrochemical cell architecture for portable safety instrumentation. Robert Bosch GmbH and Yokogawa Electric Corporation sit within the precision instrumentation archetype, with the latter reflecting Japanese industrial electronics heritage. ABB Ltd and MSA Safety exemplify industrial safety system integrators with established ATEX certification capabilities.
| Leading Market Players |
|---|
| Aeroqual Ltd |
| ABB Ltd |
| Siemens AG |
| Robert Bosch GmbH |
| Alphasense |
| Honeywell International Inc. |
| MSA Safety |
| Yokogawa Electric Corporation |
| Dynament Ltd |
| Others |
Value Chain & Pricing Dynamics
Palladium catalyst costs cascade through electrochemical cell manufacturing into three-tier pricing structures across premium, standard, and economy levels, with Russian and South African refining dominance compressing margins for European and Japanese sensor assemblers while OEMs absorb volatility through long-term offtake contracts.
Pricing Analysis
Warranty bundling and calibration service contracts separate premium-tier suppliers from component-only vendors in the CO gas sensor market. Pricing stratifies across premium, standard, and economy tiers based on ATEX certification grade and after-sales service depth. Cost compression in economy-tier residential units is intensifying because metal-oxide variants from Chinese manufacturers undercut electrochemical alternatives. Industrial safety officers in Germany exhibit lowest price sensitivity due to mandated replacement schedules, while Indian residential distributors face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements for palladium catalysts are forcing electrochemical cell manufacturers to qualify South African and Russian refiners simultaneously despite geopolitical friction. Supply concentrates in Germany for precision instrumentation, Japan for automotive-grade sensors, and China for residential metal-oxide variants. Raw material dependencies span palladium catalysts, sulfuric acid electrolytes, and platinum working electrodes. Single-source vulnerability in palladium refining creates input cost volatility. Distribution runs through building automation channels for commercial HVAC, industrial safety distributors for fixed installations, and electrical wholesalers for residential smoke-CO combinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CO gas sensor market is becoming a vertical-integration race as players pursue captive palladium catalyst supply relationships to insulate margin structures from refining concentration risk.
For Market Incumbents: Deploy MEMS-compatible manufacturing architectures to defend portable instrumentation contracts against specialized component houses. Incumbent suppliers must recalibrate production lines around miniaturized electrochemical cells or cede share to Alphasense-tier specialists. Backward integration into sensor calibration expertise addresses electrochemist talent scarcity. Channel control through building automation partnerships with Honeywell and Siemens-tier distributors reinforces position in commercial HVAC retrofits. For New Entrants and Emerging Players: Solid-state optical detection modalities offer a technology-first wedge against electrochemical incumbents in pharmaceutical cleanroom applications. White-space targets include India building code enforcement for commercial kitchens and hospitality venues. The most penetrable segment is environmental monitoring contracts requiring ppb-level sensitivity where infrared variants displace gas chromatography. A go-to-market angle through integrated facilities management contracts rather than component-level tenders bypasses procurement concentration in London and Frankfurt commercial real estate. For Investors and Strategic Acquirers: Distressed-cycle entries favor MEMS-compatible electrochemical specialists with established ATEX certification capabilities in Germany and Japan. Long-term viability across the analysis window hinges on R&D allocation toward interference-immune solid-state architectures. Acquisition target archetype: mid-cap sensor OEMs with open API architectures aligned to METI interoperability standards. The signal to watch is harmonization between regional gas detection standards and emerging connected-device cybersecurity frameworks triggering replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palladium Catalyst Supply | Captive refining relationships insulate European and Japanese assemblers from Russian supply disruption. |
| MEMS-Compatible Manufacturing Scale-Up | Miniaturized architectures capture portable instrumentation contracts from aging electrochemical incumbents. |
| Open API Architecture Certification | METI-aligned interoperability specifications unlock Tokyo and Osaka smart building procurement channels. |
| Cloud-Connected Predictive Maintenance Platform | Subscription-based monitoring services bundle CO detection into London facilities management contracts. |
| Photonic Integrated Circuit Development | Fiber-coupled infrared sensors penetrate Swiss pharmaceutical cleanrooms with zero-drift stability claims. |
Study Parameters
SEC filings, EU ATEX certification databases, and METI technical standards formed the secondary backbone for this analysis. Primary interviews with industrial safety officers, facilities management platform engineers, electrochemical sensor calibration specialists, and building automation procurement leads combined with secondary validation. Bottom-up and top-down triangulation cross-referenced component-level production data against end-use installation records.
Bottom-up volume modeling aggregated sensor shipments by technology type, connectivity architecture, and end-use application across the projection horizon. Segmentation dimensions included product type, technology tier, end-user vertical, and application specificity. CAGRs were derived from replacement cycle analysis and regulatory mandate timing. Industry-specific forecast inputs incorporated OSHA-mandated replacement schedules and wafer-fab cleanroom procurement specifications from Yangtze River Delta semiconductor foundries.
Several conditions sit outside the modeled scope, including geopolitical disruption to palladium refining, accelerated solid-state technology substitution, and cybersecurity framework harmonization timelines. Forecasts reflect documented assumptions about regulatory enforcement continuity and raw material supply stability. A model refresh is warranted upon material change in EU ATEX certification timelines or METI interoperability standard adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Non-Contact Infrared Thermometer Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Piezoelectric Devices Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Sensor Development Kit Market