
 Americas Sensor Market | 2026-2036
Americas Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Sensor Market Insights
Equipment-as-a-service and operational leasing for sensor networks is reshaping competitive dynamics across the Americas, allowing mid-tier industrial users to access advanced sensing without capital outlay. Honeywell International Inc. leverages its captive financing arm to bundle sensor hardware with long-term service contracts. Texas Instruments Incorporated anchors its position through deep backward integration into MEMS fabrication. NXP Semiconductors specializes in automotive-grade sensors that meet ASIL-D functional safety requirements.
A sensor is a transducer that detects physical, chemical, or biological stimuli and converts them into measurable electrical signals, typically operating across temperature ranges from minus forty to one hundred fifty degrees Celsius and resolution thresholds down to parts per billion for gas detection variants. Its primary commercial purpose is to feed real-time data into control systems for automated decision-making in manufacturing, transportation, and environmental management. Temperature sensors and pressure sensors occupy mature, high-volume positions where margin pools have compressed to commodity levels. Optical sensors and capacitive sensors represent faster-growing technology categories, driven by smartphone biometric integration and electric vehicle battery management systems. Proximity sensors dominate automotive OEM applications for advanced driver-assistance systems.
The US FDA regulates sensors embedded in wearable medical devices through 510(k) premarket notification pathways, while OSHA mandates gas detection and environmental monitoring sensors in hazardous industrial workplaces across the United States. Mexico's national standards body aligns industrial sensor certification with NOM-020 energy efficiency requirements for manufacturing equipment. Brazil's national telecommunications agency governs radio frequency sensors used in smart grid and IoT deployments. Stakeholders must monitor how divergent certification timelines across US, Mexican, and Brazilian regulators affect product launch synchronization and inventory positioning.
Market Dynamics
Equipment-as-a-service financing models are restructuring capital deployment across industrial sensor networks, compressing upfront procurement cycles and embedding vendors into long-term operational relationships.
Growth Catalysts
- US Inflation Reduction Act:Domestic semiconductor manufacturing incentives are expanding captive sensor fabrication capacity for automotive and industrial automation buyers.
- Predictive maintenance adoption:Process industries across Mexico's northern corridor are deploying vibration and thermal sensors to minimize unplanned downtime.
- ASIL-D functional safety mandates:Automotive OEMs are specifying automotive-grade sensors for electric vehicle battery management and advanced driver-assistance systems.
Market Restraints
- MEMS fabrication concentration:Advanced MEMS foundry capacity concentrates among a limited set of integrated device manufacturers, creating supply vulnerability.
- Rare earth magnet dependency:Hall-effect and magnetic sensors face input cost volatility from concentrated rare earth processing in Asia.
- NOM-020 certification timelines:Mexico's energy efficiency certification for industrial equipment creates extended product launch delays versus US market entry.
Strategic Opportunities
- Brazil smart grid deployment:ANATEL-governed radio frequency sensors for utility IoT networks remain underpenetrated relative to North American saturation.
- Optical-biometric convergence:Smartphone and wearable manufacturers are integrating spectral sensors with capacitive touch for multimodal authentication.
- OSHA gas detection mandates:Hazardous workplace monitoring requirements are creating pull for distributed sensor networks in chemical processing and oil & gas.
Industry Challenges
- Cross-border certification synchronization:Divergent FDA 510(k), NOM-020, and ANATEL approval timelines force inventory pre-positioning across multiple regulatory jurisdictions.
- Legacy system integration friction:Brownfield manufacturing facilities face protocol incompatibility when retrofitting digital sensor outputs to analog control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Sensor Market |
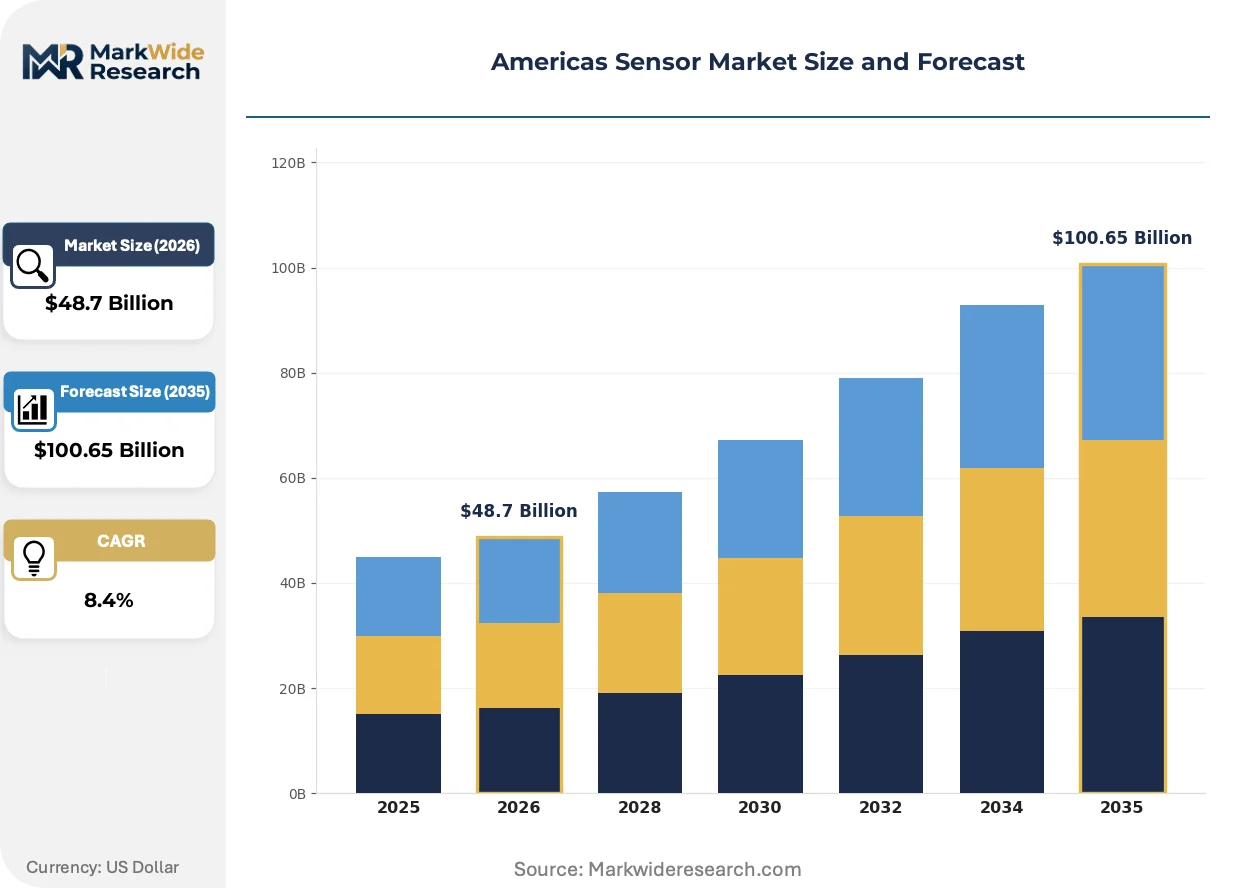
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Flow Sensors Technology: Optical Sensors, Ultrasonic Sensors, Capacitive Sensors, Magnetic Sensors End User: Automotive OEMs, Industrial Automation, Consumer Electronics, Healthcare Providers Application: Smart Home, Environmental Monitoring, Industrial Equipment, Wearable Devices |
| Companies Covered | Honeywell International Inc., Texas Instruments Incorporated, NXP Semiconductors, Siemens AG, ABB Limited, STMicroelectronics, Analog Devices, Inc., Infineon Technologies AG, Emerson Electric Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Sensor Market Trends and Innovations
Silicon photonics and solid-state LiDAR architectures are collapsing cost structures for optical sensing, while regulatory pressure on functional safety and environmental monitoring accelerates specification upgrades across automotive and industrial verticals.
Solid-state LiDAR-on-chip architectures are collapsing the cost and form-factor barriers that previously confined optical ranging to premium automotive and robotics applications. Tier-2 automotive suppliers are now specifying these sensors for mainstream advanced driver-assistance systems. The technology is collapsing the historical segmentation between premium and economy sensor tiers in automotive proximity detection.
Brazil's ANATEL has tightened radio frequency emission standards for smart grid and industrial IoT sensors, forcing module redesigns for equipment previously certified under earlier protocols. The regulation is compressing product lifecycles for imported sensor hardware. Mexican industrial OEMs are responding by accelerating local partnership strategies to navigate certification complexity.
Mid-tier manufacturers are abandoning capital purchase models for sensor hardware in favor of operational leasing bundled with predictive analytics subscriptions. Industrial automation distributors are repositioning as managed service providers. The shift is most visible in US process industries where balance-sheet efficiency now outweighs equipment ownership preferences.
Americas Sensor Market Segmentation
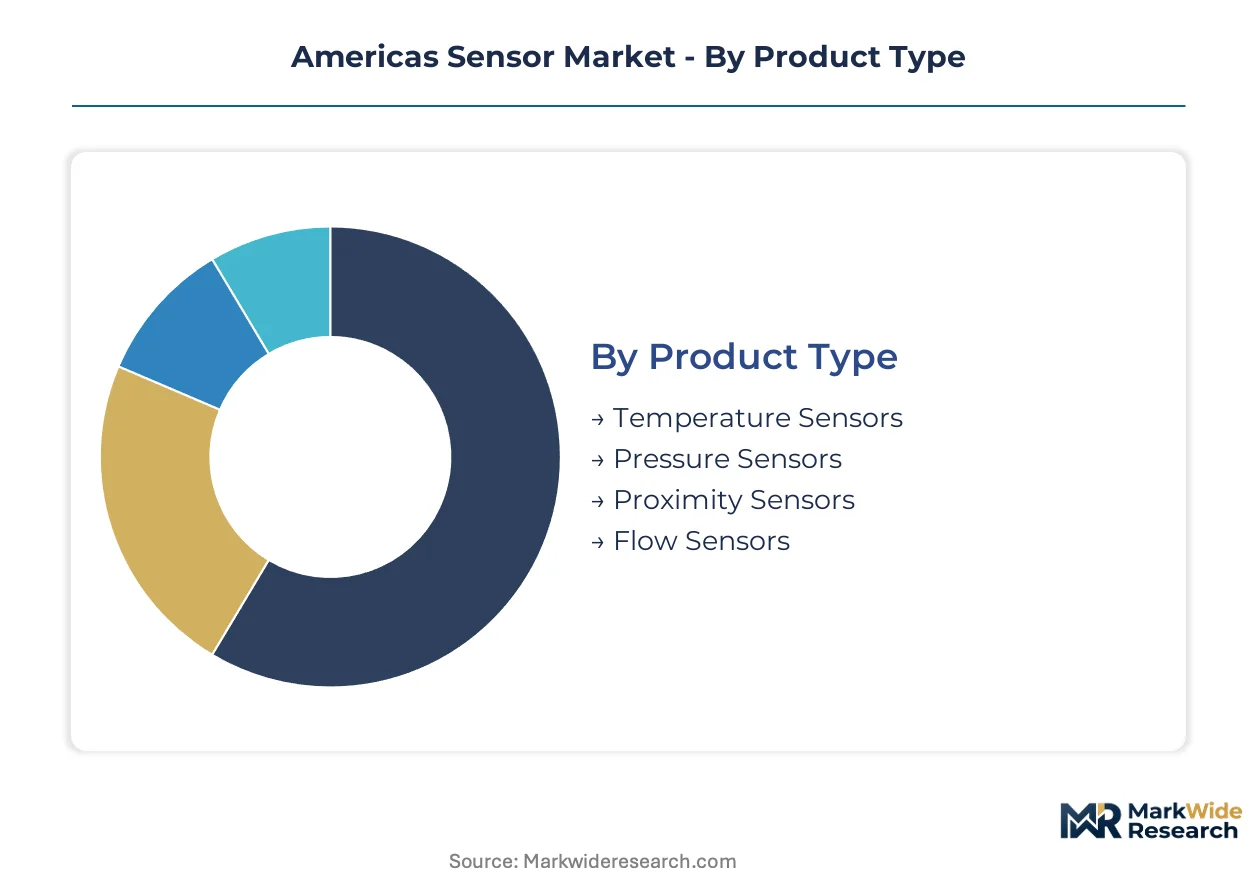
Sensor procurement patterns across the Americas diverge sharply by product physics, integration complexity, and end-use regulatory burden. Understanding these fault lines reveals where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Cost tier stratification separates commodity transducers from precision instrumentation requiring calibration infrastructure and field service networks.
- Temperature Sensors:Thermocouple and RTD variants dominate process control loops across Texas and Louisiana petrochemical corridors. Demand concentrates in predictive maintenance retrofits where thermal anomaly detection prevents unplanned refinery shutdowns. Mexican food processing plants are accelerating NOM-020-compliant temperature monitoring upgrades.
- Pressure Sensors:MEMS-based piezoresistive devices anchor automotive engine management and hydraulic systems. Brazilian offshore pre-salt drilling contractors specify high-pressure transducers for subsea blowout preventer monitoring. Supply constraints in ceramic capacitive elements are extending lead times for industrial-grade specifications.
- Proximity Sensors:Inductive and capacitive variants feed advanced driver-assistance systems in Detroit and Mexico City automotive assembly plants.
- Flow Sensors:Coriolis and ultrasonic meters serve custody transfer applications in Permian Basin oil gathering networks.
Temperature sensors command the established base. The steepest expansion runs through proximity sensors.
Technology:
Application requirements across automotive safety systems and biometric authentication are forcing specification upgrades that favor solid-state architectures over electromechanical predecessors.
- Optical Sensors:CMOS image sensors and spectral detectors integrate fingerprint and facial recognition into smartphones and access control systems. Wearable manufacturers in California and Massachusetts are specifying photoplethysmography modules for continuous glucose and blood oxygen monitoring.
- Capacitive Sensors:Touch controllers and humidity detectors leverage foundry-scale silicon economics. Electric vehicle battery management systems in the US Southeast and northern Mexico are driving demand for high-precision capacitive fuel gauging.
- Ultrasonic Sensors:Time-of-flight ranging modules serve parking assistance and industrial level sensing where optical performance degrades in dusty environments.
- Magnetic Sensors:Hall-effect and magnetoresistive devices face rare earth magnet cost volatility concentrated in Asian processing nodes.
Magnetic sensors retain the largest installed base. Optical sensors are climbing the fastest as biometric integration proliferates.
End User:
Customer type determines procurement modality, with capital-intensive automotive and industrial buyers favoring long-term service contracts while consumer electronics OEMs prioritize component cost minimization.
- Automotive OEMs:ASIL-D functional safety mandates for electric vehicle powertrain and autonomous driving systems specify automotive-grade sensors with traceable calibration chains. Detroit Three and Tesla are qualifying second-source suppliers to reduce dependency on single foundries.
- Industrial Automation:Process manufacturers across the US Gulf Coast and Mexico's Querétaro corridor deploy vibration, thermal, and gas detection sensors for OSHA and STPS regulatory compliance. Equipment-as-a-service financing is restructuring procurement toward operational expenditure models.
- Consumer Electronics:Smartphone and wearable OEMs drive optical and inertial sensor volume with annual specification refresh cycles.
- Healthcare Providers:FDA 510(k) pathways govern wearable medical device sensors, extending certification timelines versus consumer-grade equivalents.
Industrial automation commands the established base. Healthcare providers represent the steepest expansion trajectory as remote patient monitoring reimbursement codes expand.
Application:
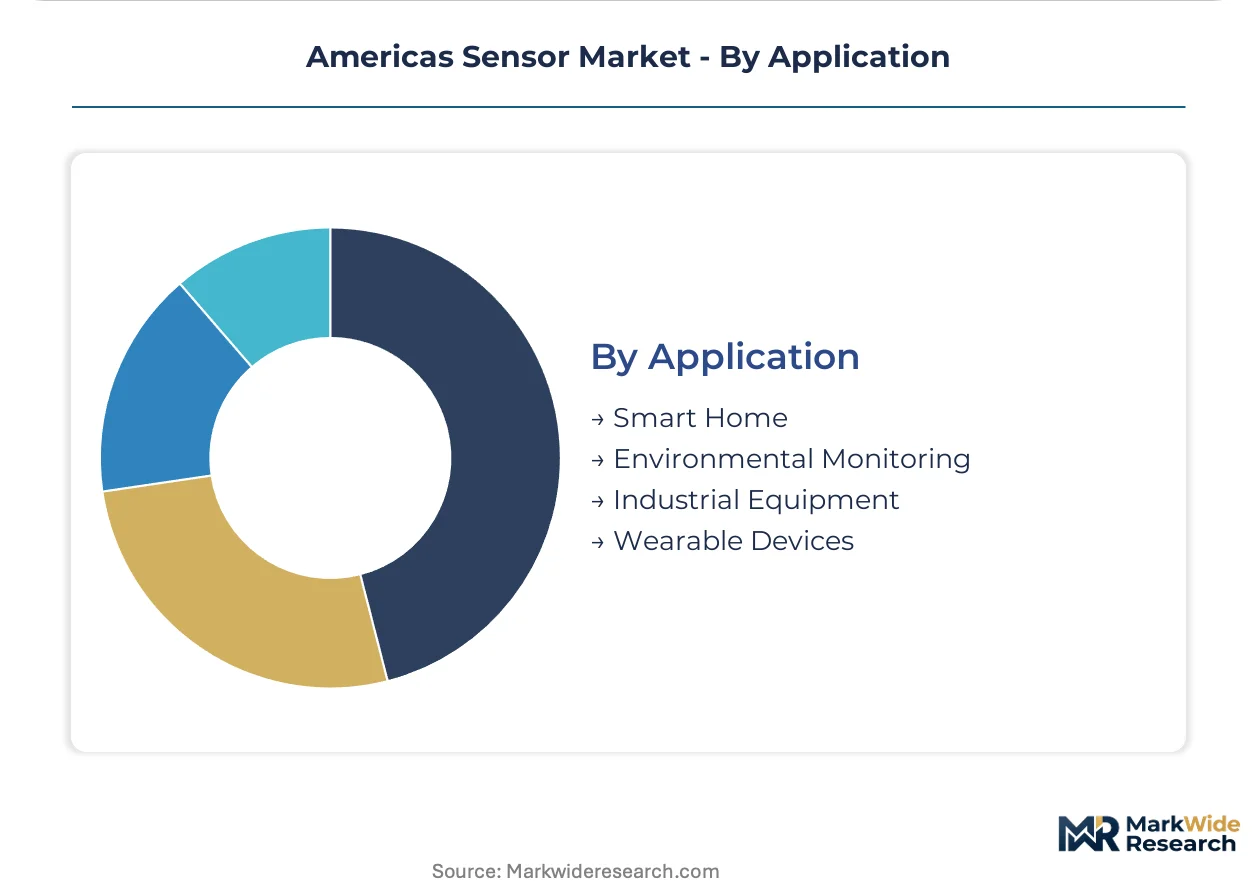
Deployment environment shapes sensor packaging, connectivity protocol, and maintenance regimen across residential, industrial, and personal use contexts.
- Industrial Equipment:Harsh-environment transducers with IP67 sealing and 4-20mA output dominate manufacturing floor retrofits. Brownfield facilities in the US Midwest face protocol friction integrating digital sensor outputs to legacy analog control systems.
- Environmental Monitoring:EPA and state-level air quality networks deploy particulate and gas sensors with parts-per-billion resolution. California South Coast Air Quality Management District mandates are accelerating replacement cycles for obsolete detection technologies.
- Smart Home:Occupancy, air quality, and leak detection sensors integrate with utility demand-response programs in Texas and California deregulated power markets.
- Wearable Devices:Miniaturized biometric sensors face battery life and skin contact reliability constraints in fitness and medical use cases.
Industrial equipment commands the established base. Environmental monitoring is gaining share fastest as regulatory enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Americas sensor trade flows reflect divergent manufacturing capabilities, with the United States running substantial deficits in commodity transducers while Mexico and Brazil build export-oriented capacity in automotive-grade components. Cross-border supply chains concentrate sensor fabrication in northern Mexico for duty-advantaged re-export to US industrial buyers.
United States
Industrial automation buyers in Texas and Louisiana petrochemical corridors drive demand for temperature and pressure transducers. OSHA mandates gas detection sensors in hazardous workplaces across Gulf Coast refineries. Detroit automotive clusters specify ASIL-D certified proximity sensors for electric vehicle battery management systems.
Mexico
Automotive and electronics OEMs deploy sensor-intensive smart factories across the Querétaro and Nuevo León industrial corridors. NOM-020 energy efficiency certification creates extended product launch timelines versus US market entry. Mexico City metro area hosts growing MEMS packaging and test operations serving North American automotive supply chains.
Canada
Oil sands operators in Alberta specify high-pressure transducers for subsea and heavy crude extraction monitoring. Health Canada regulates wearable medical device sensors through premarket notification pathways parallel to FDA frameworks. Ontario manufacturing clusters integrate US-sourced sensors into automotive tier-1 component production.
Brazil
ANATEL governs radio frequency sensors for smart grid and industrial IoT deployments with tightened emission standards forcing module redesigns. Offshore pre-salt drilling contractors specify high-pressure transducers for subsea blowout preventer monitoring. São Paulo industrial districts face certification compression for imported sensor hardware.
Americas Sensor Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated device manufacturers with captive MEMS fabrication and specialized sensor houses dependent on external foundry capacity. Tier-1 automotive suppliers and industrial conglomerates anchor the premium segment, while mid-tier distributors reposition as managed service providers. Dominant competitive moves include equipment-as-a-service financing bundling and backward integration into MEMS process technology.
Within the integrated device manufacturer tier, Honeywell International Inc. and Texas Instruments Incorporated exemplify archetypes combining captive fabrication with long-term service contract structures. NXP Semiconductors occupies a position representing automotive-grade specialization with functional safety certification depth. These three anchors demonstrate how vendor financing arms and backward integration into MEMS process technology separate premium-tier positioning from commodity sensor trading.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Siemens AG |
| ABB Limited |
| STMicroelectronics |
| Analog Devices, Inc. |
| Infineon Technologies AG |
| Emerson Electric Co. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in MEMS foundry capacity across Taiwan and South Korea is compressing wafer pricing and forcing integrated device manufacturers toward captive fabrication or long-term offtake contracts to defend margin structures. This utilization dynamic simultaneously erodes spot-market pricing power for commodity transducers while concentrating premium-tier leverage among vertically integrated suppliers with in-house MEMS process control.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ASIL-D functional safety certification and traceable calibration chains commanding substantial premiums over unqualified alternatives. Price differentiation stems from certification grade and after-sales service bundling, with predictive maintenance analytics subscriptions increasingly embedded in long-term contracts. Cost compression in temperature and pressure sensor tiers is intensifying because foundry-scale silicon economics have commoditized baseline transducer performance. Consumer electronics OEMs exhibit the highest price sensitivity due to annual specification refresh cycles, while automotive OEMs prioritize supply security over unit cost minimization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for Hall-effect and magnetic sensor modules dependent on rare earth magnet processing concentrated in Asian refining nodes. Geographic supply concentration centers on Taiwan for CMOS image sensors, South Korea for MEMS foundry services, and Mexico for automotive-grade packaging and test operations serving North American OEMs. Raw material dependencies include neodymium and dysprosium for magnetic sensors, ceramic substrates for capacitive elements, and specialized epoxy resins for harsh-environment sealing. Single-source vulnerability in advanced MEMS lithography equipment feeds from concentrated tool vendor relationships. Distribution runs through authorized industrial automation distributors repositioning as managed service providers, with direct OEM relationships capturing premium-tier automotive and medical device volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEMs and industrial automation conglomerates pursuing multi-year service contracts, fragmenting the vendor base into integrated device manufacturers and specialized sensor houses competing on financing terms rather than hardware differentiation alone.
For Market Incumbents: Build captive MEMS fabrication moats through backward integration into wafer-level process technology, insulating margin structures from foundry pricing volatility and securing allocation priority during supply constraints. Add packaging and test capacity in Mexico's Querétaro corridor to compress NOM-020 certification timelines and defend against emerging local competitors. The threat of solid-state LiDAR-on-chip architectures displacing electromechanical proximity sensors demands accelerated R&D investment in optical ranging integration. For New Entrants and Emerging Players: Brazil's underpenetrated smart grid sensor deployments relative to North American saturation offer white-space entry with ANATEL-governed radio frequency modules for utility IoT networks. Target OSHA-mandated gas detection networks in US Gulf Coast chemical processing facilities where incumbent service coverage remains patchy. Pursue equipment-as-a-service financing partnerships with regional industrial distributors to bypass capital-purchase barriers among mid-tier manufacturers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor vendors bundling predictive analytics subscriptions with hardware leases, positioning them for premium valuations versus transactional component suppliers. Long-term viability across the analysis window favors acquisition targets with automotive-grade certification depth and established foundry relationships rather than fabless design houses exposed to capacity allocation risk. Monitor ASIL-D qualification timelines at second-source suppliers as the inflection signal for automotive OEM procurement strategy shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Financing Launch | Bundles sensor hardware with predictive maintenance subscriptions, embedding vendors into decade-long operational relationships with industrial buyers. |
| Captive MEMS Foundry Investment | Secures wafer supply priority and process customization capability for automotive-grade sensors facing ASIL-D qualification requirements. |
| NOM-020 Certification Pre-Positioning | Accelerates product launch timelines in Mexico's northern industrial corridor where automotive OEMs are consolidating sensor-intensive smart factory investments. |
| Solid-State LiDAR-on-Chip Integration | Collapses cost barriers for advanced driver-assistance systems, enabling Tier-2 automotive suppliers to specify optical ranging for mainstream vehicle platforms. |
| OSHA Gas Detection Network Expansion | Captures mandated hazardous workplace monitoring demand across Gulf Coast refineries and chemical processing facilities with distributed sensor architectures. |
Research Methodology
Cross-validation between primary interviews with industrial automation procurement directors, MEMS foundry operations managers, automotive OEM platform engineers, and regulatory affairs specialists anchors the qualitative findings, with secondary validation against SEC 10-K filings, ANATEL certification databases, NOM-020 compliance registries, and customs trade data for sensor module flows. Bottom-up sensor shipment estimates by product type and technology triangulate against top-down industrial automation capex forecasts and automotive production schedules.
Calibration against historical capacity utilization rates at major MEMS foundries and automotive OEM sensor content per vehicle trajectories shapes the projection framework across product type, technology, end user, and application dimensions. CAGRs derive from segmented volume and value build-ups normalized against macroeconomic industrial production indices and regional manufacturing investment cycles. Forecast inputs include US Inflation Reduction Act semiconductor incentive disbursement timelines and Brazil ANATEL regulatory amendment implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese MEMS foundries seeking automotive qualification or solid-state LiDAR startups capturing Tier-1 design wins would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Anemometer Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Global Load Cell Market