
 Non-Contact Sensor Market | 2026-2036
Non-Contact Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Contact Sensor Market Analytics
East Asian semiconductor foundries is repositioning capacity toward MEMS-based non-contact sensing elements. Robert Bosch GmbH leverages its automotive tier-one relationships to dominate radar and ultrasonic modules for advanced driver-assistance systems. KEYENCE CORPORATION specializes in high-precision laser displacement sensors for factory automation, sustaining premium positioning through direct sales channels. STMicroelectronics extends its portfolio into time-of-flight optical arrays, competing aggressively in consumer electronics proximity applications.
Non-contact sensors detect physical properties or object presence without mechanical interaction, typically operating through electromagnetic fields, acoustic pulses, or infrared radiation at wavelengths from 700 nm to 14 μm. These devices measure distance, motion, temperature, or material composition while eliminating wear, contamination risk, and mechanical fatigue in continuous industrial processes. Infrared sensors lead product type revenue due to mature thermal imaging supply chains and broad HVAC deployment, though radar technology segments are accelerating fastest as 77-81 GHz automotive modules replace legacy 24 GHz systems. Optical detection occupies the largest technology share through smartphone time-of-flight cameras, while acoustic waves segments serve niche liquid measurement applications in food processing and chemical handling where container penetration remains critical.
FDA electromagnetic compatibility requirements shape medical device proximity sensing specifications in the United States, while REACH and RoHS frameworks in Europe restrict cadmium and lead content in sensor packaging materials. China's SAMR enforces GB standards for industrial electromagnetic emissions, compelling foreign suppliers to establish local calibration laboratories. Stakeholders must monitor evolving frequency allocation decisions by regulators in Germany, Japan, and South Korea, as 60 GHz unlicensed bands and automotive radar harmonization will determine next-generation product roadmaps and certification costs.
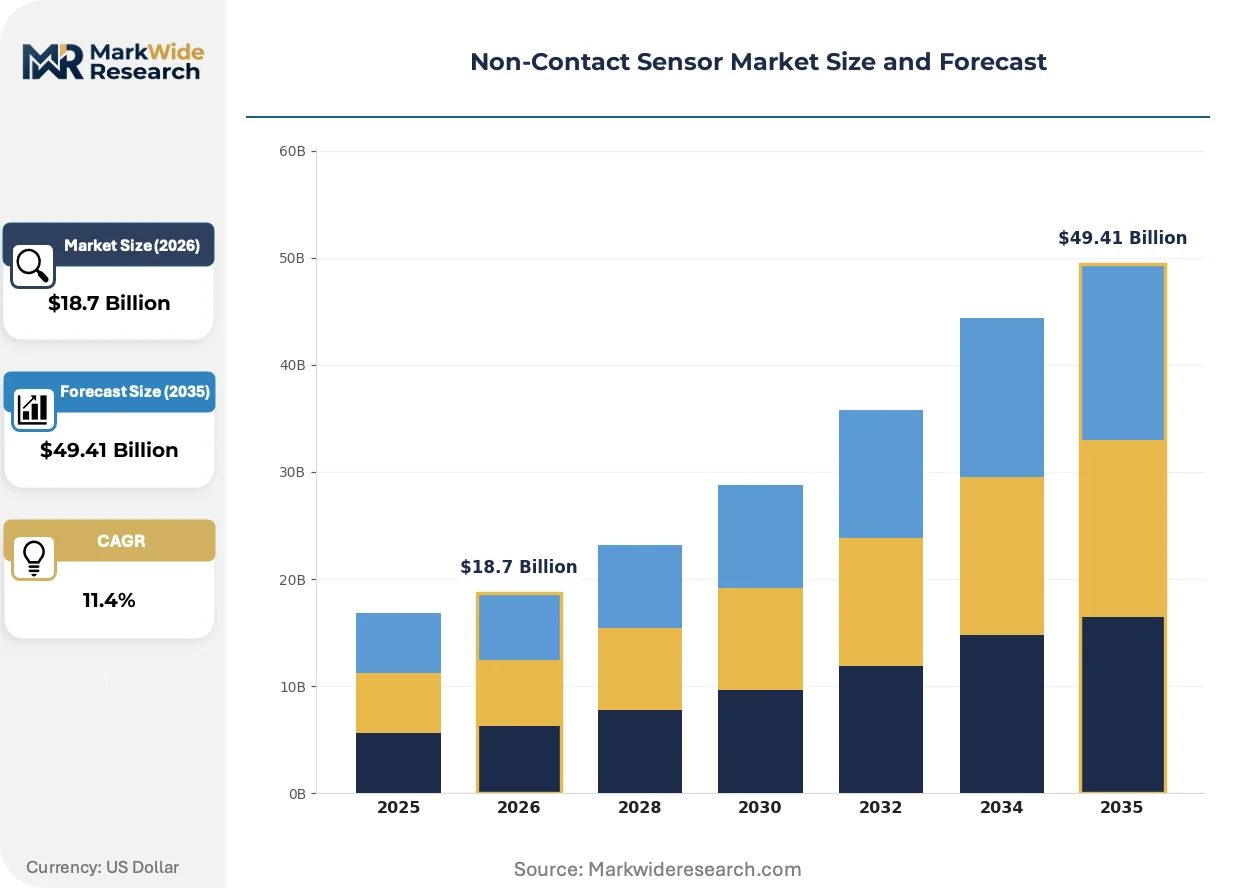
Market Dynamics
Automotive radar harmonization toward 77-81 GHz bands is compressing certification timelines while MEMS foundry capacity constraints in East Asia are creating allocation bottlenecks for capacitive sensing elements.
Growth Catalysts
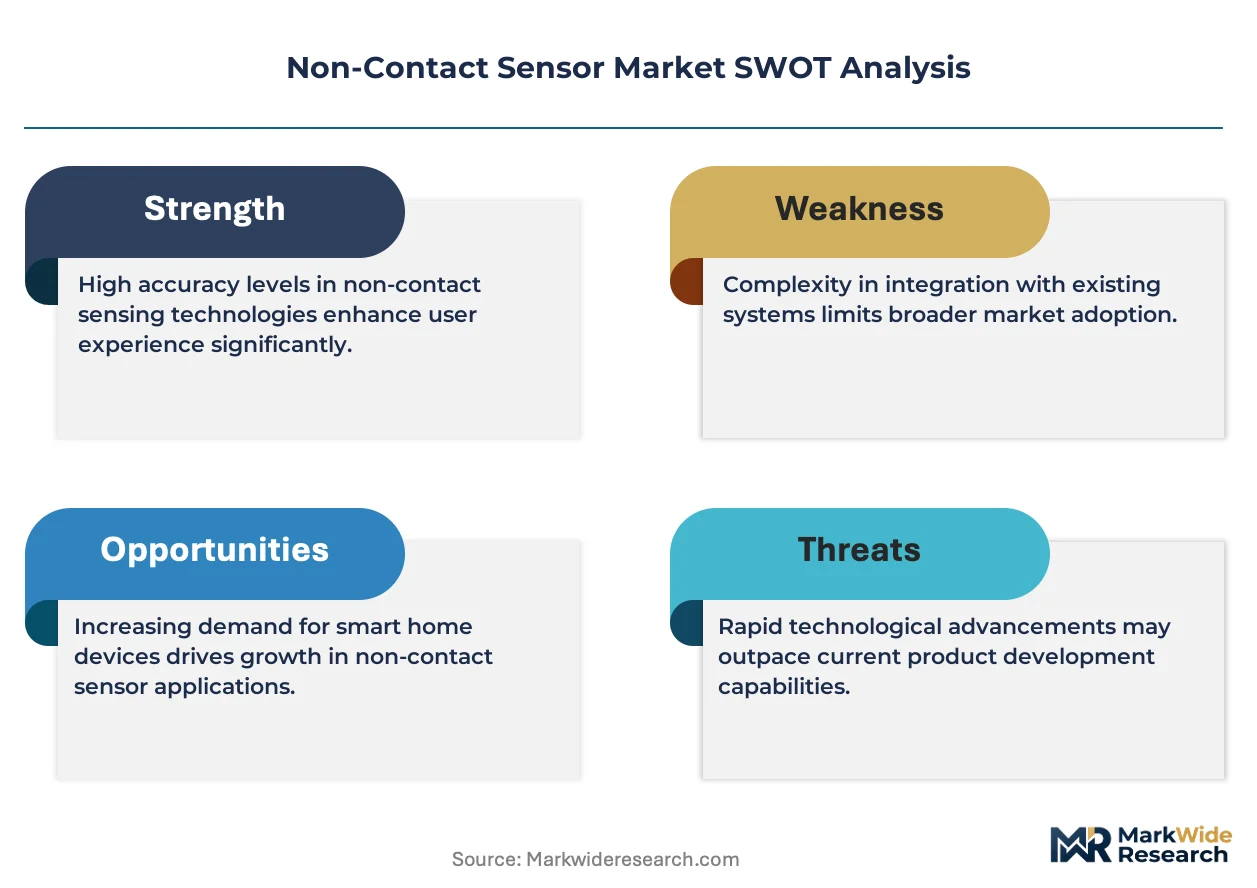
- EU RoHS material restrictions:Hazardous substance limits on cadmium and lead in sensor housings are accelerating conversion to ceramic and polymer alternatives, opening retrofit demand across industrial installed bases.
- Autonomous driving validation protocols:Germany's KBA and Japan's MLIT are mandating redundant proximity sensing for Level 3 autonomy, pulling radar module volumes through tier-one automotive supply chains.
- Semiconductor corridor clustering:South Korea's Pyeongtaek and Yongin MEMS foundries are scaling dedicated non-contact sensing wafer capacity, reducing lead times for industrial automation OEMs.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductive coating inputs for infrared sensor windows depend on Chinese rare earth processing, exposing cost volatility to export quota fluctuations.
- Frequency allocation fragmentation:Divergent 60 GHz unlicensed band rules between FCC, ETSI, and ARIB jurisdictions force redundant hardware variants, inflating SKU complexity.
- Optical time-of-flight range ceilings:Smartphone-originated ToF modules face fundamental photon budget constraints above 10 meters, limiting direct displacement of radar in logistics applications.
Strategic Opportunities
- India BIS certification alignment:The Bureau of Indian Standards is adopting IEC 60947-5-2 proximity switch standards, creating a regulatory pathway for ultrasonic sensor imports into factory automation.
- Acoustic-thermal sensor fusion:Combining ultrasonic level detection with infrared thermal profiling addresses food processing tank monitoring where single-modality systems fail.
- Direct-to-fab procurement channels:Industrial end-users are bypassing distribution to contract MEMS foundries directly, capturing margin and securing allocation during supply crunches.
Industry Challenges
- Multi-physics simulation expertise:Electromagnetic-acoustic coupled modeling for radar-sonar fusion modules requires scarce RF-MEMS co-design talent concentrated in Munich and Seoul.
- Automotive SPICE compliance timelines:ASPICE Level 3 certification for ADAS sensor software stacks extends development cycles 14-18 months, compressing product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Contact Sensor Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Ultrasonic Sensors, Laser Sensors, Capacitive Sensors Technology: Optical Detection, Motion Detection, Radar Technology, Acoustic Waves End User: Automotive Industry, Consumer Electronics, Industrial Automation, Smart Home Application: Occupancy Detection, Gesture Recognition, Proximity Sensing, Liquid Measurement |
| Companies Covered | Robert Bosch GmbH, SICK AG, KEYENCE CORPORATION, OMRON Corporation, Panasonic Corporation, Sensata Technologies, Inc., Honeywell International, Inc., TE Connectivity Ltd., STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Contact Sensor Market Evolving Landscape
Frequency-modulated continuous-wave architectures are displacing legacy pulse-Doppler radar, while regulatory convergence on material safety and electromagnetic emissions is reshaping supplier qualification protocols.
Solid-state beam steering using metamaterial antennas is rewriting automotive radar economics. Tier-one suppliers in Stuttgart and Toyota City are sampling 77 GHz modules with no moving parts for parking assistance. The elimination of mechanical scanning assemblies is compressing unit costs and enabling flush bumper integration previously impossible with motor-driven systems.
China's SAMR enforcement of updated GB 9254 electromagnetic compatibility standards is forcing recalibration of industrial sensor emission profiles. Foreign suppliers must maintain local test laboratories in Shanghai or Shenzhen to achieve conformity assessment. Medical device proximity sensors face the tightest compliance windows, with GB 4824 industrial scientific and medical equipment limits now overlapping FDA EMC requirements.
Sensor-as-a-service contracting is displacing capital purchase models in European packaging machinery. End-users in Bavaria and Emilia-Romagna now pay per validated detection event rather than owning hardware, transferring obsolescence risk to OEMs. This consumption shift concentrates buyer power among multinational food processors with standardized line configurations across multiple plants.
Non-Contact Sensor Market Segmentation
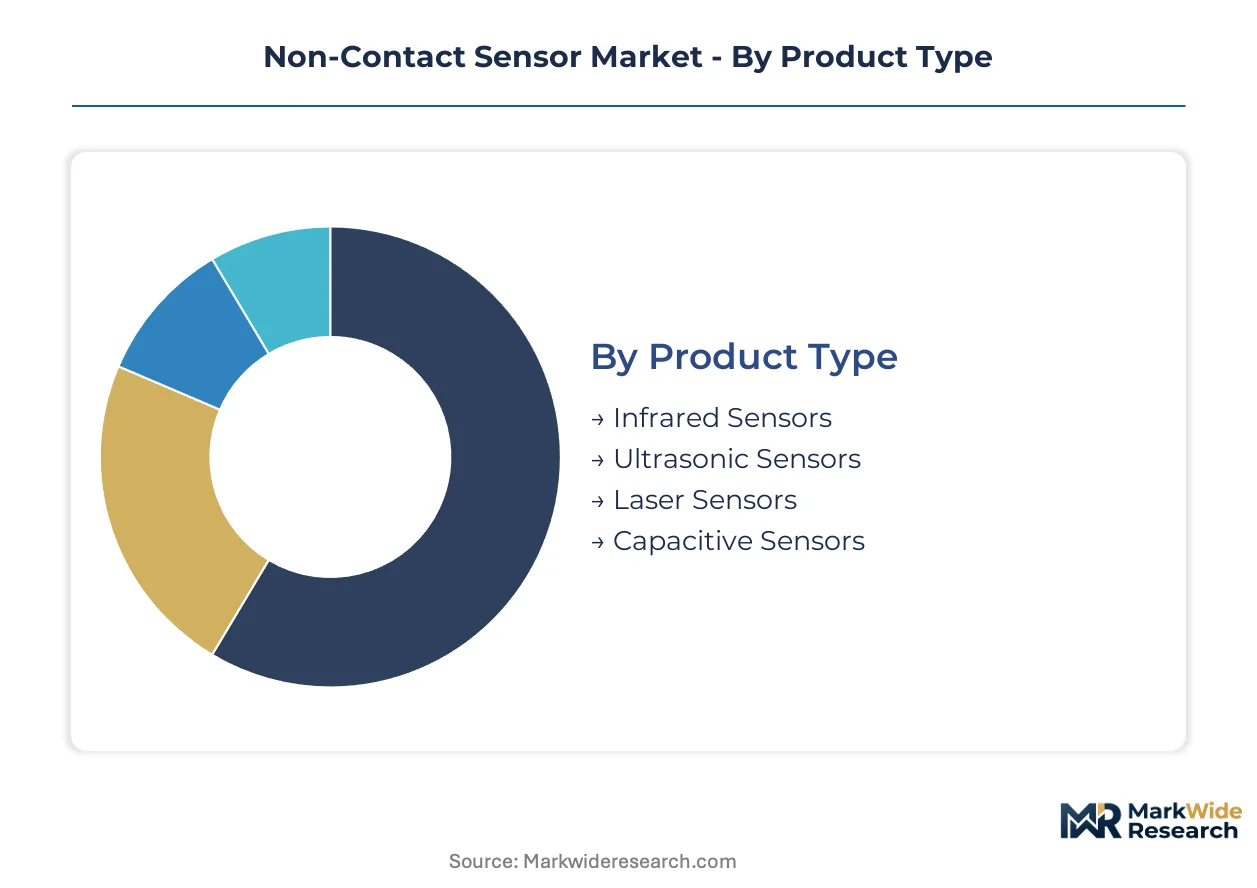
Non-contact sensor architectures diverge sharply across detection physics and integration depth. Specification choices cascade into material requirements, frequency certifications, and foundry partnerships that lock suppliers into multi-year technology roadmaps.
Product Type:
Detection physics determines thermal tolerance, range ceiling, and electromagnetic emission profiles that shape regulatory certification paths.
- Infrared Sensors:These devices operate through thermopile or pyroelectric detection of infrared radiation between 700 nm and 14 μm wavelengths. Demand concentrates in HVAC climate control systems across Germany and Japan where building energy codes mandate occupancy-based ventilation. Mature thermal imaging supply chains in Yokohama and Dresden sustain cost compression despite indium tin oxide coating volatility.
- Ultrasonic Sensors:Piezoelectric transducers emit acoustic pulses above 20 kHz for distance measurement and object detection. South Korean automotive tier-ones in Hwaseong specify these for parking assistance where radar cost exceeds bill-of-materials targets. MEMS foundry bottlenecks in Pyeongtaek constrain capacitive alternative sourcing.
- Laser Sensors:Time-of-flight and triangulation architectures using semiconductor laser diodes achieve sub-millimeter displacement resolution. Industrial automation OEMs in Stuttgart deploy these for robotic guidance where infrared lacks precision.
- Capacitive Sensors:Electric field perturbation detection suits liquid level monitoring and proximity switching in food processing equipment. Chinese packaging machinery builders in Dongguan favor these for washdown environments where acoustic coupling fails.
Mature deployment sits with Infrared Sensors. Newer deployment is concentrated in Laser Sensors.
Technology:
Signal processing architecture separates commodity proximity detection from precision measurement applications commanding premium pricing.
- Optical Detection:Photodiode arrays and CMOS time-of-flight imagers dominate smartphone proximity and ambient light sensing. Consumer electronics assemblers in Zhengzhou and Chennai specify these modules at volumes exceeding industrial applications by an order of magnitude.
- Radar Technology:Frequency-modulated continuous-wave and pulse-Doppler architectures at 24 GHz, 60 GHz, and 77-81 GHz bands enable through-material detection and velocity measurement. German KBA and Japan MLIT validation protocols for Level 3 autonomy are pulling 77-81 GHz module volumes through tier-one supply chains in Stuttgart and Toyota City.
- Motion Detection:Passive infrared and microwave Doppler fusion reduces false triggering in security and lighting control. Smart home device manufacturers in Shenzhen integrate these for battery-powered entry detection.
- Acoustic Waves:Ultrasonic pulse-echo and guided wave methods penetrate container walls for liquid level and flow measurement. Chemical processors in Ludwigshafen specify these where optical transparency cannot be guaranteed.
Volume leadership belongs to Optical Detection. Steepest expansion trajectory is climbing in Radar Technology.
End User:
Industry verticals impose distinct reliability grades, certification requirements, and procurement scale that fragment supplier economics.
- Automotive Industry:ADAS and autonomous driving platforms mandate ISO 26262 functional safety and ASPICE Level 3 software compliance. Radar and ultrasonic module qualification cycles extend 14-18 months, compressing refresh windows for tier-one suppliers.
- Industrial Automation:Factory robotics and process control demand IP67 environmental sealing and SIL 2/3 safety integrity. KEYENCE and SICK direct sales channels dominate this specification-intensive segment.
- Consumer Electronics:Smartphone and wearable integration prioritizes miniaturization and power efficiency over measurement precision. STMicroelectronics and ams OSRAM supply time-of-flight arrays to OEMs in Cupertino and Seoul.
- Smart Home:Connected lighting, security, and climate control applications tolerate wider accuracy tolerances for cost reduction. White-label manufacturers in Shenzhen and Ningbo serve this price-sensitive channel.
Procurement concentration centers on Automotive Industry. Emerging specification intensity is gathering in Industrial Automation.
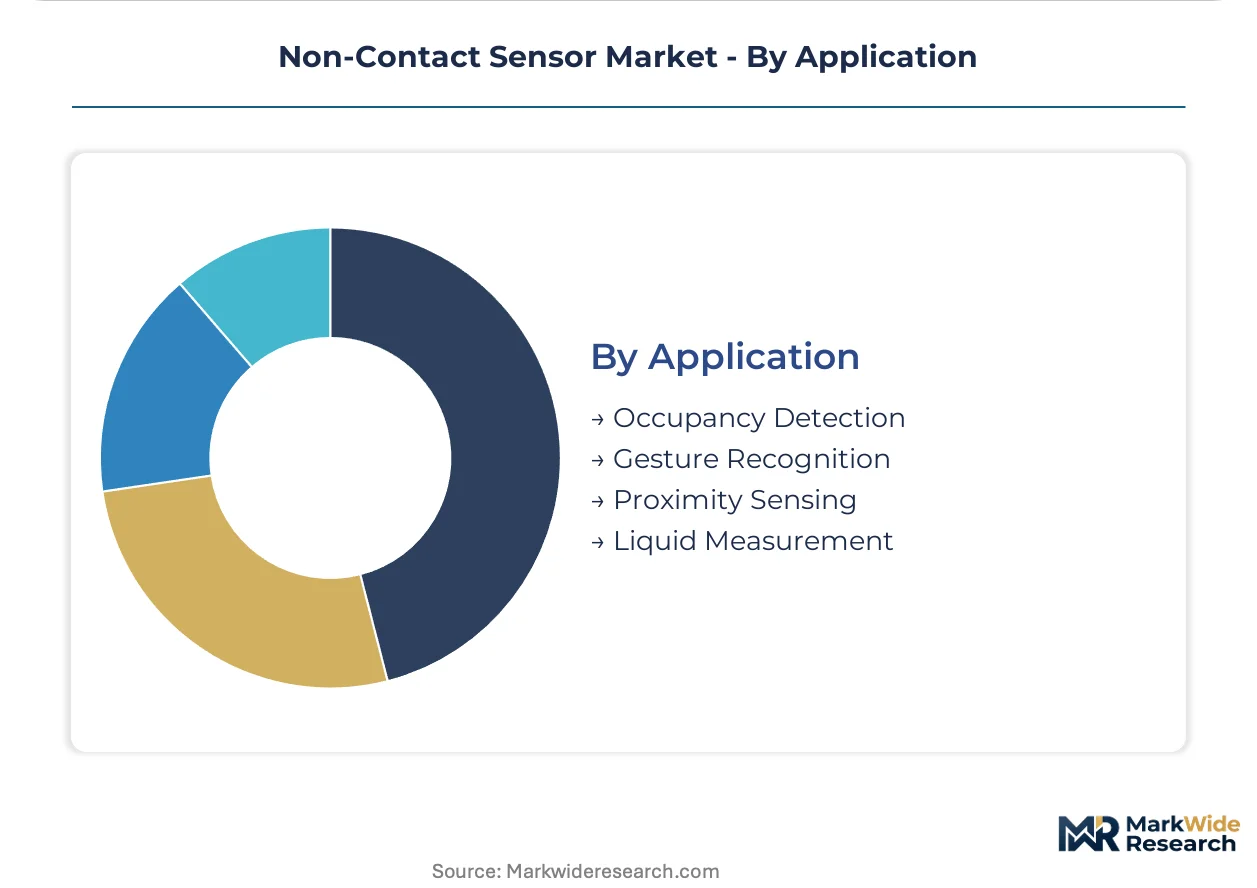
Application:
Use case requirements for range, refresh rate, and environmental immunity drive modality selection and integration complexity.
- Proximity Sensing:Short-range object detection for collision avoidance, touchscreen wake, and presence activation spans infrared, capacitive, and ultrasonic implementations. Automotive bumpers and smartphone displays represent the highest volume deployment.
- Occupancy Detection:Thermal signature and motion pattern recognition for building automation and security systems. EU Energy Performance of Buildings Directive compliance is mandating these sensors in commercial construction across France and Italy.
- Gesture Recognition:Time-of-flight camera arrays and radar micro-Doppler capture hand and body motion for touchless interfaces. Automotive HMI designers in Munich and Tokyo specify these to reduce driver distraction.
- Liquid Measurement:Ultrasonic pulse-echo and radar level detection for tank monitoring in chemical, food, and water processing. Container penetration requirements exclude optical methods in these applications.
Deployment scale favors Proximity Sensing. Technical differentiation is accelerating in Gesture Recognition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium tin oxide processing clusters in Chinese rare earth refining hubs anchor the infrared sensor window supply chain. MEMS foundry capacity concentrates in South Korean semiconductor corridors. German automotive radar validation protocols shape certification requirements for tier-one suppliers.
China
GB 9254 electromagnetic compatibility enforcement by SAMR is recalibrating industrial sensor emission profiles for factory automation deployments. Packaging machinery builders in Dongguan specify capacitive proximity switches for washdown food processing environments. Foreign suppliers now maintain local test laboratories in Shanghai and Shenzhen to achieve conformity assessment.
Germany
KBA validation protocols for Level 3 autonomous driving mandate redundant radar proximity sensing through Stuttgart-based tier-one supply chains. REACH material restrictions on cadmium and lead accelerate ceramic housing conversion across industrial installed bases. Bavarian packaging machinery OEMs in Emilia-Romagna service relationships now contract sensor-as-a-service per validated detection event.
Japan
MLIT autonomous vehicle safety mandates pull 77-81 GHz radar module volumes through Toyota City automotive clusters. JIS standards alignment with IEC 60947-5-2 proximity switch specifications enables ultrasonic sensor integration into factory robotics. Yokohama thermal imaging supply chains sustain infrared sensor cost compression despite coating input volatility.
South Korea
Pyeongtaek and Yongin MEMS foundries scale dedicated non-contact sensing wafer capacity for industrial automation OEMs. MFDS medical device electromagnetic compatibility requirements overlap with FDA specifications for proximity sensing exports. Hwaseong automotive tier-ones specify ultrasonic parking assistance where radar cost exceeds bill-of-materials targets.
United States
FDA electromagnetic compatibility requirements shape medical device proximity sensing specifications for hospital equipment deployments. FCC 60 GHz unlicensed band rules diverge from ETSI and ARIB jurisdictions, forcing redundant hardware variants. NHTSA automotive safety regulations accelerate radar-based ADAS adoption through Detroit-area OEM supply chains.
Non-Contact Sensor Market Competitive Landscape
Global majors compete with regional champions across automotive tier-one relationships and industrial direct sales channels. The vendor base organizes around three tiers: diversified electronics conglomerates with captive semiconductor fabrication, specialized sensor houses with application-specific expertise, and MEMS foundry-dependent module assemblers. Strategic moves concentrate on ASPICE Level 3 software stack certification for ADAS qualification and backward integration into MEMS wafer capacity.
Among diversified industrial technology groups, Robert Bosch GmbH and KEYENCE CORPORATION exemplify contrasting archetypes. Bosch leverages automotive tier-one relationships across Stuttgart and Toyota City supply chains. KEYENCE sustains premium positioning through direct sales channels in factory automation. STMicroelectronics occupies a position bridging consumer electronics volume and industrial specification intensity.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| SICK AG |
| KEYENCE CORPORATION |
| OMRON Corporation |
| Panasonic Corporation |
| Sensata Technologies, Inc. |
| Honeywell International, Inc. |
| TE Connectivity Ltd. |
| STMicroelectronics |
| Others |
Value Network & Pricing Analysis
Frequency-modulated continuous-wave radar architectures are compressing bill-of-materials costs while simultaneously concentrating procurement leverage among automotive tier-ones in Stuttgart and Toyota City. This technology transition redraws supplier economics by eliminating mechanical scanning assemblies and anchoring volume commitments to 77-81 GHz module platforms.
Pricing Analysis
Warranty and calibration service bundling separates premium sensor OEMs from unbundled commodity suppliers in industrial automation. Three-tier pricing structure across premium, standard, and economy levels reflects ASPICE certification grade and MEMS foundry integration depth. Pricing pressure stems from Chinese packaging machinery builders in Dongguan demanding capacitive proximity switches at economy tiers. Automotive tier-ones exhibit lowest price sensitivity due to 14-18 month qualification lock-in, while smart home white-label manufacturers in Shenzhen drive aggressive cost compression.
Supply Chain Analysis
Freight cost volatility from rare earth processing hubs in China to MEMS packaging facilities in South Korea is reshaping inventory positioning strategies. Indium tin oxide coating inputs, MEMS wafer substrates, and 77-81 GHz RF front-end components draw from concentrated East Asian supply bases. Single-source vulnerability sits with Chinese indium tin oxide refining capacity. Distribution runs through tier-one automotive supply chains in Germany and Japan alongside direct sales channels for factory automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-contact sensor market sits in a technology-transition phase where solid-state beam steering displaces motor-driven mechanical scanning. This shift rewards suppliers with metamaterial antenna expertise and captive MEMS fabrication.
For Market Incumbents: Lock in tier-one automotive relationships through ASPICE Level 3 software stack certification before 77-81 GHz radar harmonization completes. Secure MEMS foundry allocation agreements in Pyeongtaek and Yongin to defend against capacitive sensing element shortages. Backward integration into ceramic housing production mitigates REACH cadmium and lead restriction compliance costs. For New Entrants and Emerging Players: Launch via direct-to-fab procurement channels targeting industrial automation OEMs bypassing distribution markups. White-space concentrates in acoustic-thermal sensor fusion for food processing tank monitoring where single-modality systems fail. India BIS certification alignment for ultrasonic sensor imports offers regulatory pathway traction. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial technology groups seeking automotive tier-one access. Long-term viability hinges on MEMS foundry capacity ownership and frequency allocation regulatory intelligence. Watch for 60 GHz unlicensed band harmonization decisions by FCC, ETSI, and ARIB as inflection indicator for SKU consolidation economics.| Strategic Initiative | Industry Significance |
|---|---|
| ASPICE Level 3 Certification | Qualifies radar module suppliers for Stuttgart and Toyota City tier-one ADAS programs. |
| MEMS Foundry Capacity Expansion | Captures allocation priority in Pyeongtaek and Yongin semiconductor corridors. |
| Metamaterial Antenna Development | Enables solid-state beam steering without mechanical scanning assemblies. |
| Local Test Laboratory Establishment | Achieves SAMR GB 9254 conformity assessment in Shanghai and Shenzhen. |
| Sensor-as-a-Service Contracting | Transfers obsolescence risk to OEMs in Bavarian packaging machinery. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with MEMS foundry operations directors, automotive tier-one procurement managers, industrial automation OEM engineers, and medical device regulatory affairs specialists validated demand assumptions. FDA EMC guidance documents, SAMR GB standard publications, KBA validation protocols, and MLIT safety mandates provided secondary regulatory intelligence. Bottom-up sensor shipment modeling and top-down industrial automation capex analysis were cross-triangulated.
Granularity-level modeling deployed detection physics, signal processing architecture, end-use vertical, and application use case as core segmentation dimensions. CAGRs were derived from shipment volume trajectories and average selling price evolution across the analysis window. Frequency allocation decisions by German, Japanese, and South Korean regulators shaped automotive radar demand assumptions. MEMS foundry capacity utilization rates in South Korean semiconductor corridors informed supply-side constraints.
Regulatory harmonization delays, rare earth export quota fluctuations, and automotive qualification timeline extensions are the dominant revision risks to forecast outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Atomic Clock Market