
 Motion Control Encoders Market | 2026-2036
Motion Control Encoders Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Control Encoders Market Foresight
Multi-sourcing from dedicated encoder specialists is expanding as industrial OEMs reduce sole-source dependency for critical feedback components. HEIDENHAIN anchors premium optical encoder supply through captive glass-scale manufacturing in Traunreut. Sensata Technologies leverages magnetic sensing expertise across automotive and factory automation channels. Baumer Group competes on modular encoder platforms that simplify machine builder integration.
Motion control encoders are electromechanical devices that convert mechanical position or velocity into digital signals, typically achieving resolutions below one arc-second in optical configurations through interferometric or photoelectric scanning of precision gratings. These devices enable closed-loop servo control in CNC machine tools, robotic joints, and automated assembly systems where positional accuracy directly determines output quality. Rotary encoders dominate unit volume in motor feedback applications, while linear encoders command premium positioning in semiconductor lithography and metrology equipment. Magnetic technology encroaches on optical strongholds in contaminated environments, though optical maintains margin leadership in sub-micron precision segments. Inductive encoders carve niche positions in safety-critical railway and aerospace actuator systems.
FDA 21 CFR Part 820 quality system requirements shape encoder specifications in surgical robotics and diagnostic imaging equipment sold into US healthcare markets. The EU Machinery Directive and ISO 13849 functional safety standards mandate redundant encoder architectures in collaborative robot joints and automated guided vehicles. China's GB/T standards and MIIT industrial upgrade directives accelerate domestic encoder substitution in high-end CNC controllers. Stakeholders must weigh magnetic versus optical technology bets against evolving safety integrity level requirements and regional supply chain localization mandates.
Market Dynamics
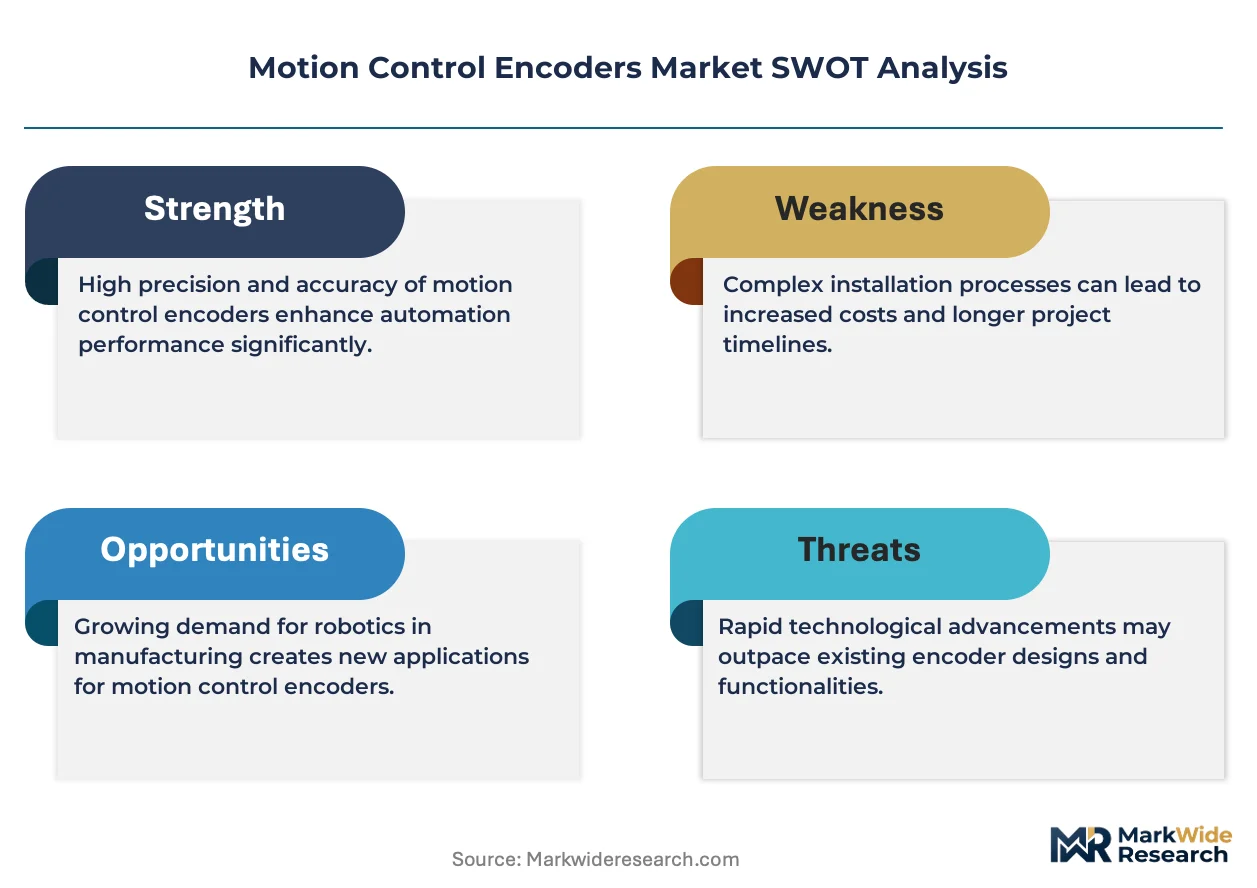
Semiconductor fabrication equipment manufacturers are demanding sub-nanometer positioning precision that strains legacy optical encoder architectures, forcing suppliers to re-engineer interferometric scanning systems and captive glass-scale production capabilities.
Growth Catalysts
- EU Machinery Directive SIL 3 mandates:Collaborative robot joints and automated guided vehicles now require redundant encoder feedback architectures, expanding specification scope for safety-certified motion systems.
- Semiconductor lithography scaling:EUV scanner stage positioning demands below 0.1 nanometer resolution, pulling optical linear encoder technology into next-generation wafer fabrication equipment.
- Germany's industrial automation corridor:Munich and Stuttgart machine tool OEMs concentrate demand for high-resolution rotary encoders in precision motor feedback applications.
Market Restraints
- Borosilicate glass supply concentration:Precision encoder scales require thermally stable glass substrates sourced from limited European and Japanese specialty glass manufacturers.
- Optical contamination vulnerability:Dust, oil mist, and coolant exposure degrades photoelectric scanning reliability in metal-cutting machine tools, limiting deployment in harsh manufacturing environments.
- FDA 21 CFR Part 820 compliance burden:Surgical robotics and diagnostic imaging equipment sold into US healthcare markets demand extensive design history files and process validation documentation.
Strategic Opportunities
- China's MIIT industrial upgrade directives:Domestic substitution mandates in high-end CNC controllers create openings for local encoder suppliers meeting GB/T precision standards.
- Magnetic-optical sensor fusion:Hybrid architectures combining magnetic robustness with optical precision enable encoder deployment in contaminated precision applications previously closed to pure optical solutions.
- Digital incremental interface adoption:BiSS-C and EnDat 2.2 protocols displace analog sine-cosine outputs, simplifying cable routing and reducing commissioning complexity for machine builders.
Industry Challenges
- Interferometric alignment technician scarcity:Sub-arc-second optical encoder assembly requires specialized cleanroom technicians with photolithography-patterning expertise concentrated in Germany and Japan.
- ISO 13849 certification timeline compression:Functional safety validation for collaborative robot encoders demands extended fault-injection testing cycles that delay product launch windows.
- Legacy analog infrastructure integration:Brownfield manufacturing facilities with established 1Vpp sine-cosine cabling resist migration to serial digital interfaces despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Control Encoders Market |
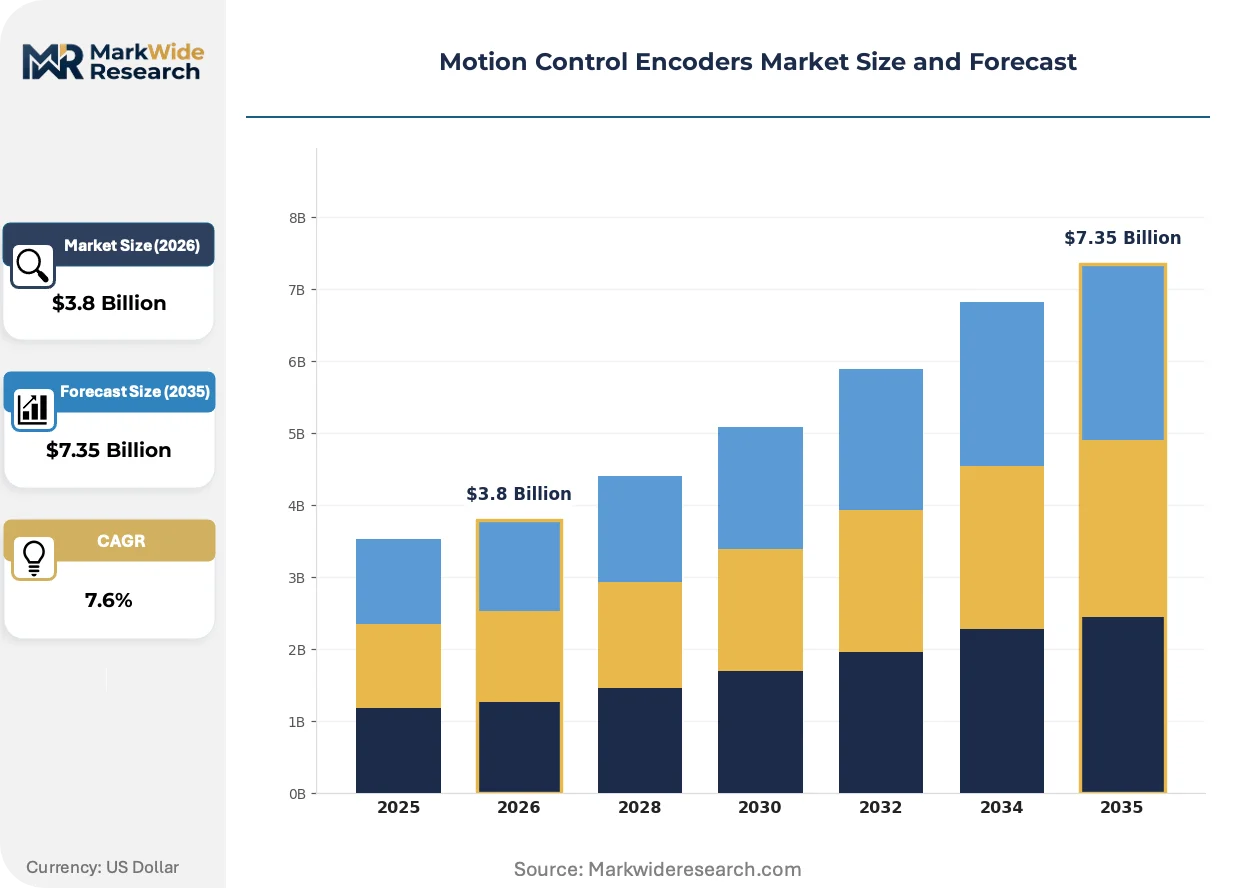
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Rotary, Linear, Incremental, Absolute Technology: Optical, Magnetic, Capacitive, Inductive Application: Robotics, Industrial Automation, Aerospace, Packaging End User: Manufacturing, Automotive, Electronics, Healthcare |
| Companies Covered | Sensata Technologies, Inc., HEIDENHAIN, Renishaw plc, Dynapar Corporation, Rockwell Automation, Inc., TE Connectivity Corporation, Baumer Group, Omron Corporation, Fortive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Control Encoders Market Shifts & Advancements
Encoder architecture is fragmenting along precision-robustness tradeoffs as end-users reject one-size-fits-all feedback solutions. Suppliers are engineering modular platforms that span optical, magnetic, and inductive sensing principles through shared mechanical interfaces and common electrical connectors.
Modular encoder platforms are modularizing across HEIDENHAIN, Sensata, and Baumer product lines, allowing machine builders to specify identical mechanical envelopes with interchangeable sensing cores. Automotive battery assembly and photovoltaic panel production lines adopt these configurable systems to standardize spare parts inventory across diverse motion axes. The approach compresses supplier SKU proliferation while preserving application-specific precision-robustness optimization.
REACH substance restrictions and RoHS recast directives are eliminating hexavalent chromium platings and cadmium-bearing solders from encoder housings and connector systems. European machine tool OEMs now specify nickel-palladium-gold contact finishes and zinc-nickel housing platings in procurement specifications. Asian encoder manufacturers serving EU export markets are retooling plating lines to maintain CE marking eligibility.
Machine builders are unbundling encoder specification from servo motor procurement, selecting feedback components independently based on safety integrity level requirements rather than accepting drive-integrated defaults. This disintermediation is most visible in Germany's packaging machinery sector, where OEMs source encoders directly from HEIDENHAIN or Baumer while purchasing motors from competing suppliers. The pattern fragments historical bundled supply relationships and elevates encoder supplier brand recognition in buyer decision hierarchies.
Motion Control Encoders Market Segmentation
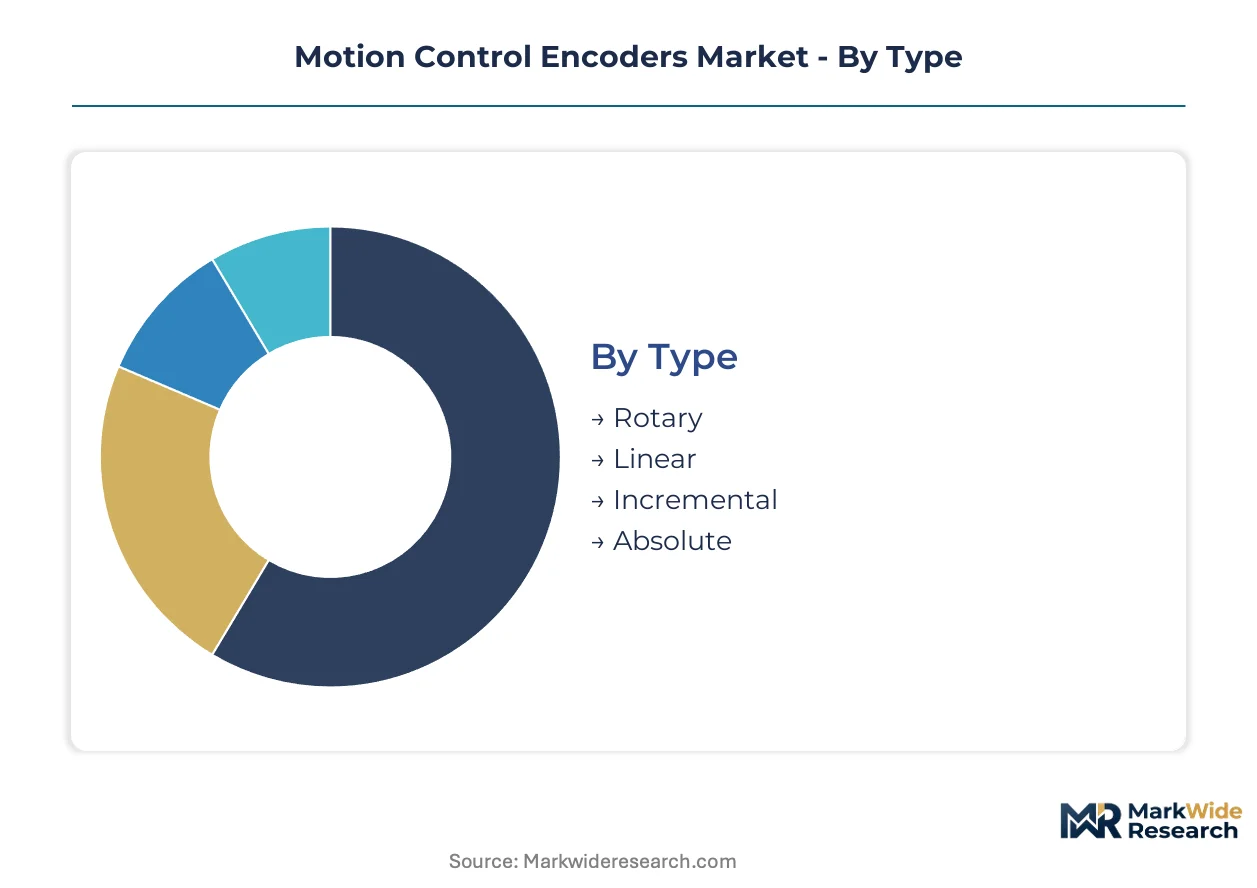
Encoder specification varies sharply across motion control applications. Technology selection determines achievable precision, environmental tolerance, and system integration complexity for end-users.
Type:
Mechanical configuration dictates mounting geometry and signal output architecture for machine builders.
- Rotary:Shaft-mounted devices convert angular position into digital quadrature or absolute codes through disc-based scanning. Motor feedback applications in Germany's Stuttgart machine tool cluster consume high volumes of high-resolution variants for precision servo control.
- Linear:Scale-and-head assemblies track position along straight axes using interferometric or photoelectric scanning. Semiconductor lithography equipment manufacturers specify sub-nanometer variants for EUV scanner stages, straining supplier glass-scale production capabilities.
- Incremental:Position is derived by counting pulses from a reference point, requiring homing sequences at power-up. Cost-sensitive packaging machinery OEMs favor these for simple velocity feedback where absolute position recovery is unnecessary.
- Absolute:Unique position codes eliminate homing requirements, enabling immediate operation after power cycling. Safety-critical collaborative robot joints mandate multi-turn absolute variants under ISO 13849 SIL 3 architectures.
Rotary encoders lead on scale; absolute encoders lead on momentum.
Technology:
Physical sensing principle determines resolution ceiling, contamination immunity, and cost structure for specification engineers.
- Optical:Photoelectric scanning of precision gratings achieves sub-arc-second resolution through interferometric techniques. HEIDENHAIN's captive glass-scale manufacturing in Traunreut anchors premium supply for semiconductor metrology equipment.
- Magnetic:Hall-effect or magnetoresistive sensing detects position via field variation, tolerating dust and coolant exposure. Automotive battery assembly lines adopt these variants where optical contamination vulnerability would trigger excessive maintenance cycles.
- Capacitive:Electrode arrays measure displacement through capacitance change, offering moderate precision in compact packages. MEMS-based variants serve miniature robotics joints where mechanical envelope constraints exclude bulkier alternatives.
- Inductive:Eddy-current or resolver-based detection operates through metallic contamination and extreme temperatures. Railway signaling systems and aerospace actuator manufacturers specify these for functional safety compliance in harsh environments.
Optical technology leads on scale; magnetic technology leads on momentum.
Application:
End-use sector shapes precision requirements, safety integrity levels, and procurement volume patterns.
- Robotics:Collaborative robot joints demand redundant encoder architectures with SIL 3 certification under EU Machinery Directive mandates. KUKA and FANUC integration specifications drive demand for compact, high-resolution motor feedback devices.
- Industrial Automation:CNC machine tools and automated assembly systems require sub-micron positioning repeatability. Munich-area machine tool OEMs concentrate procurement of linear scales for precision axis control.
- Aerospace:Flight control surface actuators and landing gear systems specify inductive or resolver-based feedback for DO-178C software assurance compatibility. Extended temperature ranges and vibration tolerance override pure precision considerations.
- Packaging:High-speed filling and labeling machinery prioritizes cost-optimized incremental encoders with sufficient resolution for velocity loop closure. Standardized mechanical interfaces reduce spare parts proliferation across production lines.
Industrial automation leads on scale; robotics leads on momentum.
End User:
Buyer industry determines regulatory compliance burden, specification authority, and supplier relationship structure.
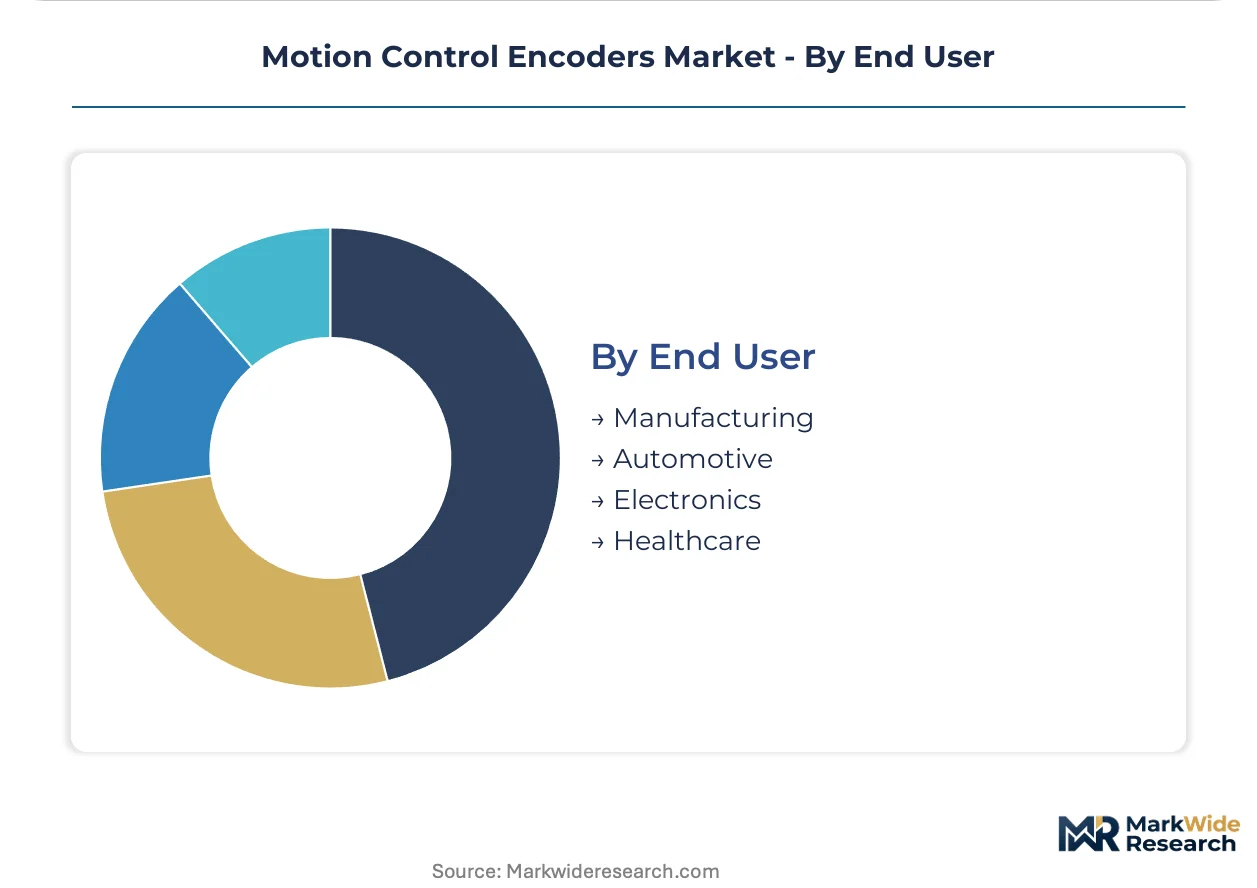
- Manufacturing:Machine tool and factory automation OEMs represent the core volume segment, with German industrial automation corridor buyers driving premium optical encoder specifications.
- Automotive:Battery assembly and electric powertrain manufacturing lines adopt modular encoder platforms to standardize inventory across diverse motion axes.
- Electronics:Semiconductor fabrication equipment manufacturers impose sub-nanometer positioning requirements that pull optical linear encoder technology into next-generation wafer handling systems.
- Healthcare:Surgical robotics and diagnostic imaging equipment sold into US markets demand FDA 21 CFR Part 820 quality system documentation and design history file maintenance.
Manufacturing leads on scale; healthcare leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridor around Munich and Stuttgart anchors encoder procurement concentration, with precision machine tool OEMs driving demand for sub-micron optical linear scales and high-resolution rotary variants.
United States
Surgical robotics manufacturers in Greater Boston and the San Francisco Bay Area require FDA 21 CFR Part 820 quality system documentation for encoder feedback systems. The FDA mandates extensive design history files and process validation for diagnostic imaging equipment. Minneapolis-based factory automation OEMs concentrate procurement of safety-certified encoders for material handling systems.
Germany
EU Machinery Directive SIL 3 mandates force redundant encoder architectures into collaborative robot joints and automated guided vehicles. REACH substance restrictions eliminate hexavalent chromium platings from encoder housings. The Munich-Stuttgart corridor machine tool OEMs specify HEIDENHAIN optical linear scales for precision axis control in CNC equipment.
China
MIIT industrial upgrade directives accelerate domestic encoder substitution in high-end CNC controllers meeting GB/T precision standards. SAMR enforces compliance with national quality certification for industrial automation components. The Yangtze River Delta semiconductor fabrication equipment manufacturers pull optical encoder technology into EUV scanner stage systems.
Japan
METI technology roadmaps prioritize domestic encoder supply chain resilience for precision manufacturing equipment. JIS standards govern mechanical interface compatibility for machine tool feedback systems. Nagoya-area automotive battery assembly lines adopt modular encoder platforms to standardize inventory across electric powertrain production.
South Korea
MFDS medical device regulations shape encoder specifications for surgical robotics and diagnostic imaging equipment sold into domestic healthcare markets. Government semiconductor self-sufficiency programs expand wafer fabrication equipment manufacturing. Seoul Capital Area display panel producers drive demand for sub-micron positioning encoders in OLED deposition systems.
Motion Control Encoders Market Competitive Landscape
Global majors compete with regional champions across technology specialization and captive manufacturing capabilities. The vendor base stratifies into three tiers: premium optical specialists with in-house glass-scale production, diversified sensor conglomerates spanning magnetic and inductive technologies, and modular platform providers targeting cost-optimized machine builder integration. Dominant competitive moves include backward integration into precision substrate manufacturing and strategic partnerships with semiconductor equipment OEMs for co-development of next-generation interferometric systems.
Within the premium optical tier, HEIDENHAIN anchors supply through its Traunreut-based captive glass-scale manufacturing. Sensata Technologies occupies a diversified position across automotive and industrial channels. Baumer Group exemplifies the modular platform approach with interchangeable sensing cores that compress supplier SKU proliferation for machine builders.
| Leading Market Players |
|---|
| Sensata Technologies, Inc. |
| HEIDENHAIN |
| Renishaw plc |
| Dynapar Corporation |
| Rockwell Automation, Inc. |
| TE Connectivity Corporation |
| Baumer Group |
| Omron Corporation |
| Fortive |
| Others |
Supply & Pricing Matrix
Captive glass-scale manufacturing in Traunreut anchors HEIDENHAIN's pricing power across premium optical encoder tiers, insulating premium suppliers from commodity pricing pressure while forcing magnetic and inductive competitors to compete on total cost of ownership metrics.
Pricing Analysis
Borosilicate glass substrate costs pass through directly to optical encoder list prices, with thermally stable glass supply concentration in Germany and Japan creating regional price premiums. Pricing stratifies across SIL 3-certified absolute encoders, standard industrial incremental variants, and economy magnetic sensors serving packaging machinery. Cost compression in economy tiers intensifies because Asian suppliers are scaling magnetic encoder production for automotive battery assembly lines. Semiconductor equipment manufacturers exhibit the lowest price sensitivity, while packaging machinery OEMs drive hard volume negotiations.
Supply Chain Analysis
Dual-sourcing requirements from Munich and Stuttgart machine tool OEMs mandate multi-supplier qualification for critical feedback components, fragmenting order volumes across HEIDENHAIN, Baumer, and Sensata. Manufacturing concentrates in Germany, Switzerland, and Japan for precision optical assemblies, while magnetic encoder production scales in China and South Korea. Supply chains draw from specialty borosilicate glass, rare-earth magnetic materials, and precision photolithography equipment. Single-source vulnerability sits with European and Japanese glass substrate manufacturers. Distribution runs through direct OEM specification channels and industrial distributor networks serving aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motion control encoders market functions as a stable compounder, with EU Machinery Directive safety mandates and semiconductor lithography scaling creating durable specification pull across industrial automation.
For Market Incumbents: Anchor premium positioning through backward integration into captive glass-scale production, mirroring HEIDENHAIN's Traunreut model. Defend against magnetic technology substitution by embedding optical encoders in EUV scanner stage co-development partnerships with ASML and Nikon. Prioritize ISO 13849 SIL 3 certification investment to maintain specification authority in collaborative robot joints. For New Entrants and Emerging Players: Enter via China's MIIT industrial upgrade directives, where domestic substitution mandates create white-space for GB/T-certified encoder suppliers. Target Yangtze River Delta semiconductor equipment manufacturers with sub-nanometer linear scale offerings. Pursue modular platform architectures that allow machine builders to standardize mechanical interfaces while swapping sensing cores. For Investors and Strategic Acquirers: Roll-up economics work for regional magnetic encoder specialists because automotive electrification is standardizing feedback component specifications across battery assembly and powertrain manufacturing. Five-to-ten-year viability hinges on technology portfolio breadth spanning optical, magnetic, and inductive principles. Watch for inflection when domestic Chinese suppliers achieve GB/T precision parity in high-end CNC controller applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass-Scale Manufacturing | Captive substrate production locks in HEIDENHAIN's sub-arc-second precision leadership against magnetic substitutes. |
| SIL 3 Certification Investment | EU Machinery Directive compliance opens specification pathways into KUKA and FANUC collaborative robot joints. |
| Modular Platform Expansion | Baumer's interchangeable sensing cores compress SKU proliferation for automotive battery assembly line builders. |
| China Domestic Substitution Partnership | MIIT-directed CNC controller upgrades create qualified supplier status for GB/T-certified encoder manufacturers. |
| EUV Scanner Stage Co-Development | ASML and Nikon partnerships pull optical linear encoder technology into next-generation wafer fabrication equipment. |
Research Methodology
Bottom-up machine tool and robotics modeling reconciled against top-down semiconductor equipment and automotive manufacturing tracking forms the analytical core. Primary interviews with CNC OEM procurement directors, collaborative robot integration engineers, semiconductor metrology equipment designers, and automotive battery assembly line managers combined with secondary validation from SEC filings, EU Machinery Directive implementation guidance, MIIT industrial upgrade policy documents, and semiconductor capital expenditure disclosures. Trade data from German machinery exports and Japanese precision equipment shipments provided cross-reference points.
Input-output matrices mapped encoder demand across rotary, linear, incremental, and absolute configurations against supply from optical, magnetic, capacitive, and inductive technology producers. Segmentation dimensions modeled include mechanical configuration, sensing principle, end-use application, and regional regulatory cluster. CAGRs were derived from unit volume trajectories and average selling price evolution across the projection horizon. Forecast inputs incorporated EUV lithography stage positioning requirements, SIL 3 safety architecture adoption curves, and China's domestic substitution timeline for high-end CNC controllers.
Inputs from primary fieldwork and regulatory filings were available through the study window; gaps in real-time semiconductor equipment order backlogs and collaborative robot deployment rates introduce uncertainty bands. Forecasts reflect documented assumptions about technology substitution velocity and regional supply chain localization mandates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Italy Digital Thermometer Market