
 Infrared Gas Sensor Market | 2026-2036
Infrared Gas Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Gas Sensor Market Analysis
Silicon-based MEMS is pivoting away from traditional thermopile architectures in mid-range infrared gas sensors, cutting unit costs while preserving selectivity for CO2 and hydrocarbon detection. Amphenol Corporation leverages its vertical integration into optical benches and signal-conditioning electronics to sustain margin control across industrial safety contracts. smartGAS Mikrosensorik GmbH specializes in compact NDIR engines for OEM integration, while Heimann Sensor GmbH anchors the high-volume segment with pyroelectric array production.
An infrared gas sensor detects gas concentration by measuring absorption at specific wavelengths in the mid-infrared spectrum, typically employing a broadband source, gas-specific optical filter, and thermopile or pyroelectric detector with optical path lengths from 2 mm to 100 mm depending on target gas and required detection limit. Fixed Sensors dominate installed base value in petrochemical and offshore oil & gas facilities where continuous monitoring mandates permanent infrastructure. Portable Sensors represent the fastest-growing product category as maintenance crews and emergency responders replace colorimetric tubes with digital, data-logging instruments. Non-Dispersive Infrared technology leads volume shipments due to its maturity and cost structure, though Tunable Diode Laser systems capture premium positioning in emissions compliance and research laboratory end use where parts-per-billion resolution justifies higher instrument cost.
The U.S. EPA enforces leak detection and repair protocols under Clean Air Act amendments that mandate optical gas imaging or equivalent methods for volatile organic compound monitoring at refineries and chemical plants. OSHA confined-space entry standards drive fixed sensor deployment in manufacturing and wastewater treatment facilities. The EU F-Gas Regulation and associated CE marking requirements for gas detection equipment shape product certification pathways for market access. Stakeholders must weigh TDL technology migration against NDIR cost advantages as methane-specific regulations tighten across North American and European jurisdictions.
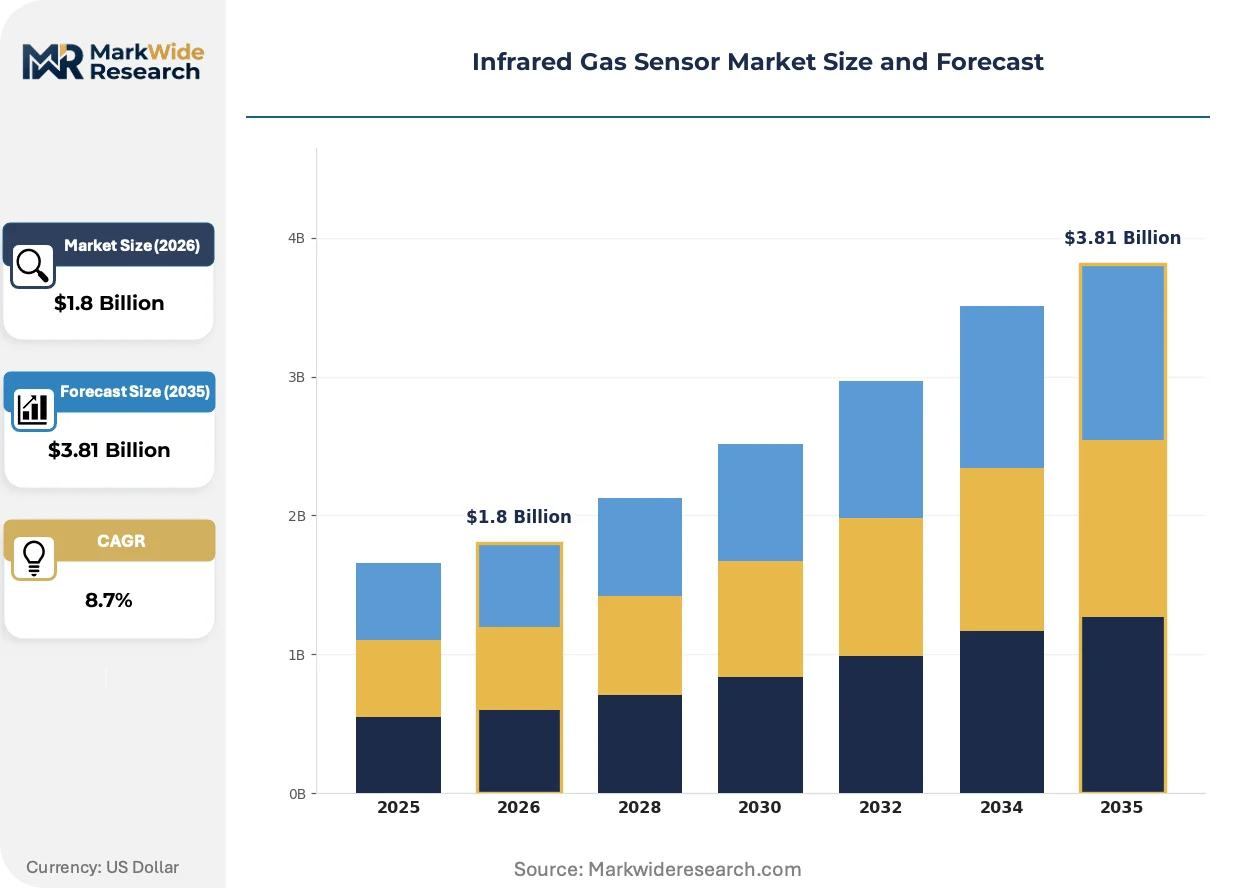
Market Dynamics
Silicon-based MEMS architectures are compressing unit economics in mid-range infrared gas sensors while preserving detection fidelity, forcing incumbents to reconfigure optical bench sourcing and signal-conditioning integration strategies to defend margin structures.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-out of fluorinated greenhouse gases in industrial refrigeration and air conditioning is accelerating replacement of electrochemical and catalytic bead sensors with NDIR alternatives across European chemical processing facilities.
- Methane monitoring mandates:EPA Clean Air Act enforcement at US refineries and natural gas infrastructure is institutionalizing optical gas imaging and fixed-point infrared detection as baseline compliance infrastructure.
- Automotive emissions testing clusters:Germany's concentration of powertrain R&D centers and TÜV certification laboratories is driving specification intensity for CO2 and hydrocarbon measurement precision in vehicle development cycles.
Market Restraints
- Optical component supply concentration:Narrow-band interference filters and IR sources concentrate among German and Japanese specialty glass manufacturers, exposing sensor OEMs to lead-time volatility and minimum order quantity constraints.
- TDL cost floor:Tunable diode laser spectroscopy remains structurally expensive due to single-mode laser diodes and precision temperature control requirements, limiting penetration outside emissions compliance and research laboratory end uses.
- Electrochemical substitution in cost-sensitive applications:Carbon monoxide and hydrogen sulfide detection in residential and light commercial settings still favors lower-cost electrochemical cells, constraining NDIR volume in price-elastic segments.
Strategic Opportunities
- India industrial safety enforcement:Factory Act amendments and state-level pollution control board mandates in Maharashtra and Gujarat are creating first-mover advantage for fixed infrared sensor deployment in petrochemical and textile processing corridors.
- Drone-mounted leak detection:Integration of miniaturized NDIR engines with unmanned aerial platforms is opening channel access through industrial inspection service providers serving pipeline and storage tank operators.
- CE marking pathway expansion:EU machinery directive harmonization for gas detection equipment is reducing certification duplication costs for sensors targeting both industrial safety and environmental monitoring applications.
Industry Challenges
- Optical calibration expertise scarcity:Gas correlation filter design and multi-pass cell alignment require specialized photonics engineering talent that concentrates in German and Austrian research institutes, constraining rapid product development cycles.
- ATEX/IECEx certification timelines:Intrinsic safety approvals for hazardous area deployment in oil and gas facilities typically extend 12-18 months, compressing effective product lifecycles and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Gas Sensor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sensors, Fixed Sensors, Handheld Devices, Continuous Emitters Application: Environmental Monitoring, Industrial Safety, HVAC Systems, Automotive Emissions Technology: Non-Dispersive Infrared, Tunable Diode Laser, Photoacoustic, Gas Chromatography End User: Manufacturing, Oil & Gas, Chemical Processing, Research Laboratories |
| Companies Covered | Heimann Sensor GmbH, Amphenol Corporation, smartGAS Mikrosensorik GmbH, Alphasense Ltd, ABB Group, Senseair AB, Process Sensing Technologies, Honeywell International, Inc., Dragerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Gas Sensor Market Emerging Trajectories
Photonics integration and regulatory instrumentation mandates are converging to reshape competitive positioning across industrial safety and environmental monitoring segments, with technology unification and procurement model evolution as dominant vectors.
Multi-gas NDIR engines are unifying detection channels for CO2, methane, and refrigerants within single optical benches through advanced filter wheel or micro-electromechanical interferometer architectures. Process automation engineers in chemical and food and beverage facilities are specifying these consolidated platforms to reduce panel space and wiring complexity. The structural consequence is compressing demand for discrete single-gas sensors and favoring suppliers with in-house optical design and firmware integration capabilities.
REACH substance restrictions on lead and cadmium in electronic components are forcing redesign of pyroelectric detector ceramics and soldered optical bench assemblies across European-bound product lines. Industrial safety OEMs are qualifying alternative piezoelectric materials and lead-free thermal management substrates to maintain CE marking eligibility. Portable sensor manufacturers face the steepest compliance cost absorption due to higher unit volumes and thinner margin structures.
Sensor-as-a-service contracting is displacing capital purchase models among multinational chemical operators seeking to outsource calibration, replacement, and data analytics overhead. Industrial gas detection distributors in the US Gulf Coast and Rotterdam-Antwerp corridor are restructuring as managed service providers with recurring revenue streams. This shift is most visible in hydrogen economy infrastructure projects where detection point density and uptime guarantees outweigh upfront hardware cost considerations.
Infrared Gas Sensor Market Segmentation
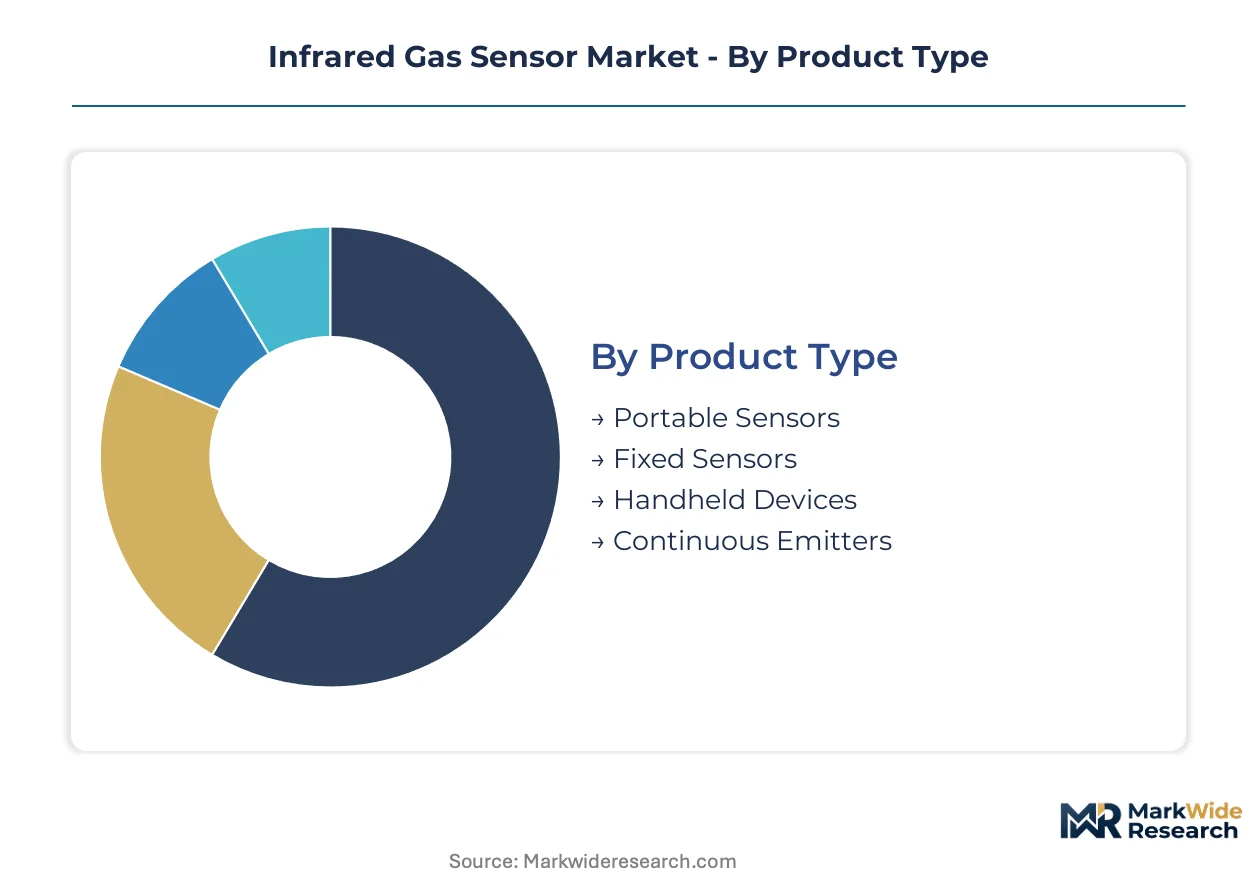
Segmentation in infrared gas sensors reveals how detection specifications, deployment economics, and regulatory mandates fragment demand across industrial safety and environmental monitoring verticals. Technology choices and product form factors carry distinct margin structures and certification requirements that reshape vendor positioning.
Product Type:
Detection range and calibration frequency dictate whether operators favor permanent infrastructure or mobile instrumentation.
- Fixed Sensors:These units integrate into plant distributed control systems with 4-20 mA or Modbus outputs for continuous perimeter monitoring. Petrochemical facilities along the US Gulf Coast and Rotterdam-Antwerp corridor specify these for EPA leak detection mandates and ATEX Zone 1 compliance.
- Portable Sensors:Battery-powered units with data-logging capability replace colorimetric detector tubes for maintenance crews and emergency responders. Demand concentrates in Germany's TÜV certification laboratories and industrial service providers where documentation requirements favor digital instruments.
- Handheld Devices:Single-gas or multi-gas units for spot-check applications in confined-space entry protocols.
- Continuous Emitters:Open-path systems spanning fence-line monitoring at refineries and chemical plants.
Fixed Sensors lead on scale; Portable Sensors lead on momentum.
Application:
Regulatory enforcement intensity and detection limit requirements stratify demand across end-use environments.
- Industrial Safety:Confined-space entry, leak detection, and process area monitoring drive specification for SIL-rated sensors with self-diagnostics. OSHA enforcement at US manufacturing and wastewater treatment facilities mandates fixed-point deployment with documented calibration records.
- Environmental Monitoring:Ambient air quality stations and fence-line monitoring require ppb-level resolution for methane and refrigerant quantification. The EU F-Gas Regulation accelerates NDIR replacement of older technologies at refrigeration service depots across Germany and France.
- HVAC Systems:Demand-side ventilation control and refrigerant leak detection in commercial buildings.
- Automotive Emissions:Powertrain R&D and certification testing in Stuttgart and Munich clusters.
Industrial Safety dominates installed value; Environmental Monitoring gains share fastest.
Technology:
Optical complexity and single-source availability determine cost floors and addressable market breadth.
- Non-Dispersive Infrared:Broadband IR sources with gas-specific interference filters and thermopile detectors deliver CO2 and hydrocarbon detection at unit costs below TDL alternatives. Volume production concentrates with German and Japanese optical component suppliers serving industrial safety OEMs.
- Tunable Diode Laser:Single-mode laser diodes with precision temperature control achieve parts-per-billion resolution for methane emissions compliance. Cost structure limits penetration to research laboratories and regulatory enforcement applications despite superior selectivity.
- Photoacoustic:MEMS microphone detection of pressure waves from gas-specific IR absorption.
- Gas Chromatography:Laboratory-grade separation and identification for complex mixtures.
Non-Dispersive Infrared holds volume leadership; Tunable Diode Laser commands premium positioning.
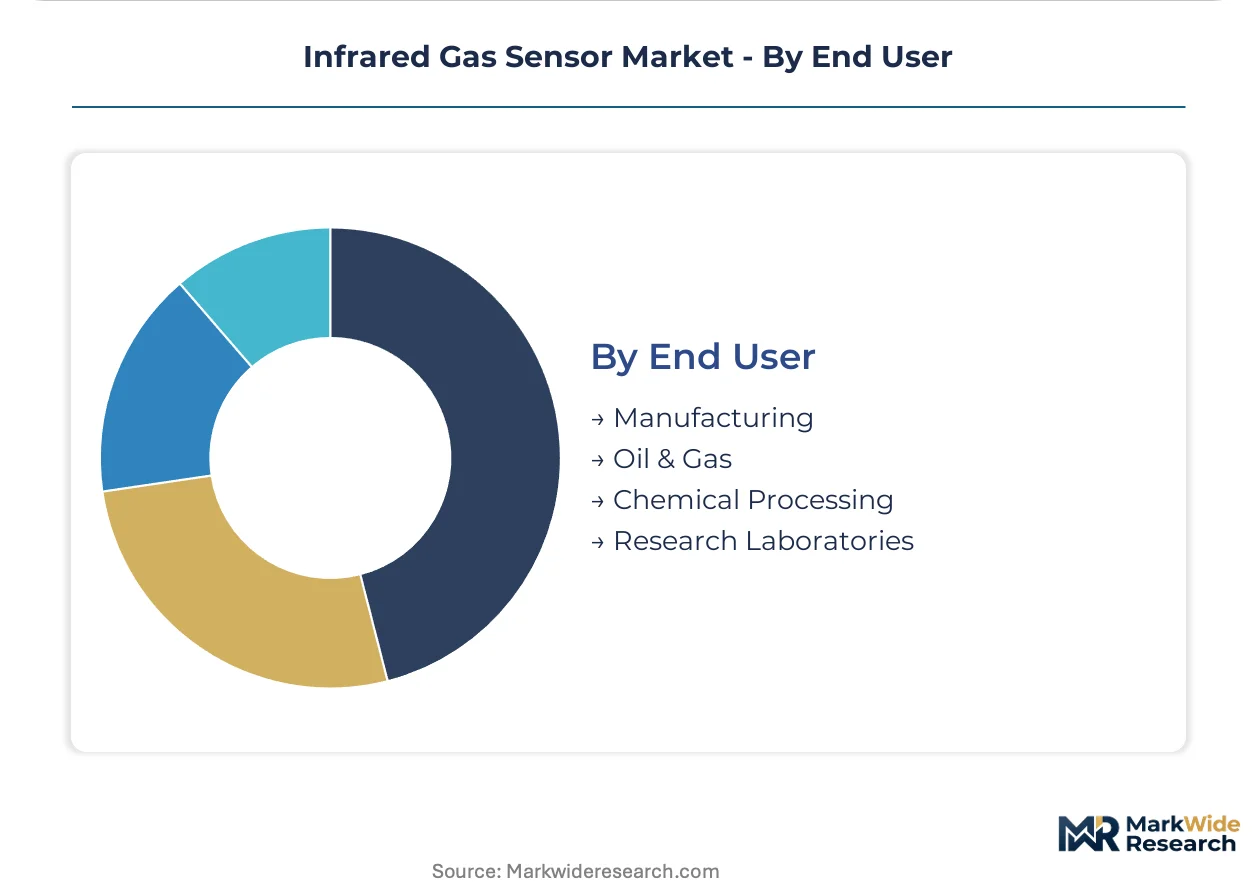
End User:
Capital intensity and hazard classification shape procurement specifications and service attachment rates.
- Oil & Gas:Offshore platforms, pipelines, and storage terminals require ATEX/IECEx certified sensors with 99.9% uptime guarantees. Sensor-as-a-service contracting is displacing capital purchase models among multinational operators in the North Sea and US Permian Basin.
- Chemical Processing:Reactor monitoring, solvent recovery, and fugitive emissions tracking demand multi-gas capability. Factory Act amendments in Maharashtra and Gujarat state pollution control board jurisdictions are creating first-mover deployment opportunities.
- Manufacturing:Welding fume detection and paint booth monitoring in automotive and electronics assembly.
- Research Laboratories:Spectroscopy-grade instrumentation for method development and standard reference materials.
Oil & Gas anchors revenue concentration; Chemical Processing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive emissions testing clusters and industrial automation corridors anchor regional demand intensity for precision gas detection instrumentation.
United States
EPA Clean Air Act enforcement at Gulf Coast refineries and Permian Basin infrastructure mandates optical gas imaging deployment. OSHA confined-space standards drive fixed sensor installation at manufacturing and wastewater treatment facilities. Houston and Baton Rouge petrochemical corridors concentrate procurement for SIL-rated continuous monitoring systems.
Germany
Stuttgart and Munich powertrain R&D centers specify high-precision CO2 and hydrocarbon sensors for vehicle certification cycles. The EU F-Gas Regulation accelerates NDIR replacement of electrochemical detectors at refrigeration service depots. Ruhr industrial automation clusters integrate multi-gas engines into process control architectures.
China
Dual carbon policy enforcement elevates methane monitoring requirements at coal mine ventilation and natural gas pipeline networks. GB standards for industrial safety equipment shape certification pathways for fixed-point detection systems. Yangtze River Delta chemical processing corridors drive specification for ATEX-equivalent sensor platforms.
India
Maharashtra and Gujarat Factory Act amendments create first-mover deployment opportunities in petrochemical and textile processing corridors. State pollution control board mandates institutionalize continuous emissions monitoring at hazardous waste facilities. Mumbai-Pune industrial belt concentrates demand for portable instrumentation with data-logging capability.
Japan
METI hydrogen economy roadmaps drive detection point density requirements at fueling station and storage infrastructure. JIS standards for gas detection equipment shape product certification for semiconductor fabrication facility suppliers. Kansai region chemical manufacturers specify pyroelectric arrays for process area monitoring.
Infrared Gas Sensor Market Vendor Landscape
Global majors compete with regional champions across optical component sourcing and certification pathway navigation. The vendor base stratifies between vertically integrated industrial conglomerates and specialized photonics engineering houses. Three archetypes dominate: captive optical bench producers, MEMS foundry partners, and calibration service integrators. M&A activity concentrates on filter wheel technology acquisitions and ATEX certification portfolio expansion.
Within the German engineering cluster, Heimann Sensor GmbH, smartGAS Mikrosensorik GmbH, and Amphenol Corporation occupy distinct tier positions. Heimann Sensor GmbH exemplifies high-volume pyroelectric array production. smartGAS Mikrosensorik GmbH represents compact NDIR engine specialization for OEM integration. Amphenol Corporation anchors the tier of diversified electronics manufacturers with backward integration into signal-conditioning electronics.
| Leading Market Players |
|---|
| Heimann Sensor GmbH |
| Amphenol Corporation |
| smartGAS Mikrosensorik GmbH |
| Alphasense Ltd |
| ABB Group |
| Senseair AB |
| Process Sensing Technologies |
| Honeywell International, Inc. |
| Dragerwerk AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Multinational oil and gas operators in the North Sea and US Permian Basin anchor pricing power through sensor-as-a-service contracting models that bundle hardware, calibration, and uptime guarantees into recurring revenue structures rather than transactional unit sales.
Pricing Analysis
Input-cost pass-through from narrow-band interference filters and IR sources governs sensor OEM margin structures. Pricing stratifies across premium, standard, and economy tiers based on ATEX/IECEx certification grade and detection limit performance. Cost compression in standard-tier NDIR engines is intensifying because silicon-based MEMS architectures reduce optical bench assembly labor. Residential and light commercial segments exhibit highest price sensitivity, while offshore oil and gas facilities prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Photonics-grade substrate supply rests on German and Japanese specialty glass manufacturers that dominate narrow-band filter production. Pyroelectric detector ceramics and thermopile MEMS wafers draw from Austrian foundry partners and Japanese precision ceramic producers. Single-source vulnerability concentrates in gas correlation filter design expertise anchored in German and Austrian research institutes. Distribution runs through industrial safety distributors in the US Gulf Coast and Rotterdam-Antwerp corridor that are restructuring as managed service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as methane-specific regulations and SIL-rated specification requirements shift procurement toward premium-tier detection platforms with documented calibration pedigree.
For Market Incumbents: Deepen captive supply of optical benches and signal-conditioning electronics to defend margin structures against MEMS-based cost compression. Accelerate ATEX/IECEx certification portfolio expansion to shorten revenue recognition timelines for hazardous area deployment. Prioritize multi-gas engine development to capture panel-space consolidation demand from process automation engineers.
For New Entrants and Emerging Players: Drone-mounted miniaturized NDIR integration offers a technology-first wedge into pipeline inspection service channels underserved by fixed-point infrastructure incumbents. Target Maharashtra and Gujarat industrial corridors where Factory Act amendments create first-mover deployment windows without entrenched vendor relationships. Pursue OEM supply agreements with unmanned aerial platform manufacturers rather than direct end-user sales.
For Investors and Strategic Acquirers: Diversified industrial electronics manufacturers are the most active acquirer in this space, seeking optical design and firmware integration capabilities to complete gas detection portfolios. Five-to-ten year viability hinges on regulatory instrumentation mandates hardening across methane monitoring and refrigerant leak detection. Watch for EU F-Gas Regulation enforcement intensity as the inflection indicator for NDIR replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Gas Engine Development | Process automation engineers in chemical facilities specify consolidated platforms to reduce panel space and wiring complexity. |
| MEMS Foundry Partnership | Silicon-based architectures compress unit economics while preserving selectivity for CO2 and hydrocarbon detection. |
| ATEX Certification Expansion | Intrinsic safety approvals for oil and gas facilities compress effective product lifecycles and delay revenue recognition. |
| Sensor-as-a-Service Restructuring | Industrial distributors in Rotterdam-Antwerp corridor transform capital purchase models into recurring revenue streams. |
| Drone Platform Integration | Miniaturized NDIR engines open channel access through inspection service providers serving pipeline operators. |
Methodological Framework
Bottom-up industrial safety and environmental monitoring modeling reconciled against top-down optical component production tracking forms the analytical core of this study. Primary interviews with plant engineers at petrochemical facilities, procurement leads at industrial gas detection distributors, technical R&D directors at sensor OEMs, and aftermarket service heads at calibration providers combined with secondary validation from EPA enforcement databases, EU F-Gas Regulation implementation reports, SEC filings of listed industrial electronics manufacturers, and customs trade data for IR source and filter imports. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of detection technology substitution patterns and regulatory instrumentation mandate adoption curves informs the projection framework. The model segments by product type, application, technology, and end user, with additional dimensioning by certification tier and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year installed base estimates and replacement cycle assumptions. Industry-specific inputs include methane monitoring mandate enforcement timelines and REACH substance restriction compliance cost absorption rates.
The model holds under steady regulatory enforcement intensity and stable optical component supply availability; deviation in EU F-Gas Regulation phase-out acceleration or German-Japanese filter supply disruption would shift volume and value trajectories. Forecasts reflect documented assumptions about technology substitution elasticity and procurement model evolution. A small set of named triggers—methane-specific regulation tightening, MEMS cost compression rates, and drone platform certification pathways—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
China PV Monitoring Systems Market