
 Global Smart Biosensors Market | 2026-2036
Global Smart Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Biosensors Market Foresight
Asset-light leasing models for continuous glucose monitoring hardware is narrowing the capital barrier for new entrants in the smart biosensor space. Abbott Laboratories leverages vertical integration across electrochemical strip manufacturing to sustain cost advantages in diabetes management. Medtronic anchors its position through deep R&D intensity in closed-loop insulin delivery systems. Roche Diagnostics differentiates via optical biosensor specialization for high-throughput diagnostic laboratories.
Smart biosensors integrate biological recognition elements with transducer systems capable of detecting analytes at picomolar concentrations, converting biochemical signals into quantifiable electrical or optical outputs for real-time health and environmental surveillance. Electrochemical biosensors occupy the largest revenue pool due to their cost efficiency and glucose monitoring dominance, while optical biosensors represent the fastest-expanding category as surface plasmon resonance platforms displace legacy immunoassays in pharmaceutical quality control. Nanotechnology-enabled architectures command premium positioning where graphene and quantum dot functionalization enhance sensitivity thresholds beyond conventional electrode designs.
The FDA's Software as a Medical Device framework and the EU's Medical Device Regulation impose divergent validation burdens on AI-integrated diagnostic platforms, forcing manufacturers to maintain dual compliance architectures. China's NMPA accelerates local market access through streamlined innovation pathways for Class II connected monitoring devices. Stakeholders must monitor regulatory convergence around cybersecurity standards for wireless biosensor networks as a determinant of future market access costs.
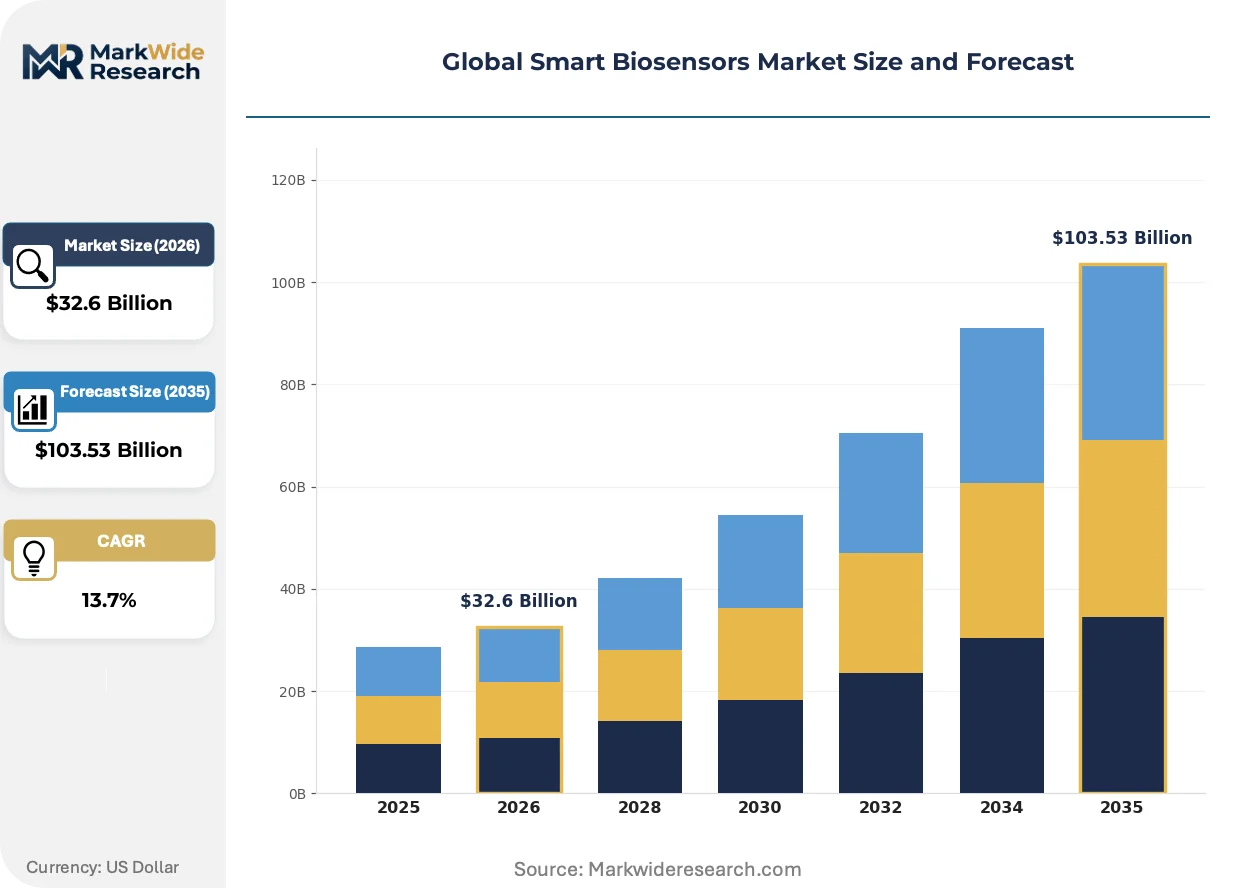
Market Dynamics
The FDA's Software as a Medical Device framework and the EU's Medical Device Regulation are forcing dual compliance architectures on AI-integrated diagnostic platforms, reshaping how manufacturers validate algorithmic outputs across transducer systems.
Growth Catalysts
- Continuous Bioprocess Monitoring:Pharmaceutical manufacturers deploy connected electrochemical platforms for real-time metabolite tracking during cell culture operations, replacing offline sampling with in-line glucose and lactate measurement.
- German MEMS Commercialization:Fraunhofer institutes and industrial clusters in Baden-Württemberg accelerate surface micromachining scale-up for mass-producible transducer arrays, lowering unit economics for wearable form factors.
- NMPA Innovation Pathways:China's streamlined Class II connected device approval routes compress regulatory timelines for wireless cardiac and metabolic monitors, accelerating market access for domestic and foreign platform developers.
Market Restraints
- Palladium Electrode Volatility:Electrochemical sensor fabrication depends on palladium catalyst layers, with price swings in PGM markets compressing gross margins for strip and electrode manufacturers.
- FDA-EU Validation Divergence:The Software as a Medical Device framework and the EU AI Act impose non-overlapping algorithmic transparency requirements, forcing redundant clinical validation studies for cross-border deployment.
- Optical Platform Substitution:Surface plasmon resonance systems displace legacy immunoassay workflows in pharmaceutical QC labs, stranding capital in older ELISA infrastructure and reagent inventories.
Strategic Opportunities
- Indian Preventive Diagnostics:Underpenetrated rural health networks create whitespace for low-cost electrochemical point-of-care platforms targeting HbA1c and lipid panel screening outside tertiary hospital systems.
- AI-Optical Convergence:Machine learning interpretation of spectral plasmon shift data enables multiplexed analyte detection from single sensor sites, opening metabolic panel applications beyond single-analyte glucose tracking.
- EU Green Deal Procurement Mandates:Public healthcare tenders increasingly require circular economy compliance for disposable sensor components, rewarding redesigns toward biodegradable substrates and closed-loop reagent systems.
Industry Challenges
- MEMS Process Engineer Scarcity:Cleanroom fabrication of piezoelectric and capacitive transducers requires specialized expertise in thin-film deposition and photolithography, with talent concentrated in semiconductor hubs outside biosensor clusters.
- Cybersecurity Certification Burden:Wireless biosensor networks must demonstrate IEC 62304 software lifecycle compliance alongside ISO 27001 information security management, extending product development timelines for connected diagnostic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Biosensors Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $103.53 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical Biosensors, Optical Biosensors, Thermal Biosensors, Piezoelectric Biosensors, Magnetic Biosensors Technology: Nanotechnology, Microfluidics, MEMS, Artificial Intelligence, Wireless Connectivity Application: Medical Diagnostics, Environmental Monitoring, Food Quality Analysis, Bioprocess Control, Biotechnology Research End User: Hospitals, Diagnostic Laboratories, Pharmaceutical Companies, Agricultural Research Institutes, Academic Institutions |
| Companies Covered | Abbott Laboratories, Medtronic, Roche Diagnostics, Siemens Healthineers, Dexcom, Philips Healthcare, Biosensors International Group, Bio-Rad Laboratories, Acon Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Biosensors Market Shifts & Advancements
Electrochemical transduction architectures are yielding ground to optical and nanomaterial-enabled platforms as sensitivity requirements tighten and pharmaceutical quality control demands multiplexed detection capabilities.
Graphene-functionalized electrode designs are migrating from academic prototype to commercial glucose and lactate monitors, with Abbott Laboratories and Roche Diagnostics integrating CVD-grown monolayers into mass-manufactured test strips. Pharmaceutical bioprocess divisions adopt these architectures for picomolar-scale metabolite detection in perfusion cell culture. The technology is migrating from diabetes management into upstream biomanufacturing, compressing the addressable market for legacy platinum-carbon electrodes.
REACH restrictions on perfluorinated substances are forcing reformulation of hydrophobic membrane materials in enzymatic glucose sensors, with manufacturers substituting fluorine-free polymers in electrode coatings. The EU's Chemicals Strategy for Sustainability accelerates substance evaluation timelines, affecting sensor component suppliers across the value chain. German and Swiss component manufacturers are responding fastest, leveraging existing green chemistry R&D pipelines to maintain CE marking continuity.
Hospital procurement committees are unbundling sensor hardware from reagent supply contracts, separating capital equipment purchasing from consumable vendor lock-in. Diagnostic laboratories in France and the Netherlands lead this shift, negotiating multi-source reagent agreements for surface plasmon resonance platforms. The trend concentrates negotiating leverage with large hospital networks, compressing margins for integrated platform suppliers while opening aftermarket opportunities for third-party reagent manufacturers.
Global Smart Biosensors Market Segmentation
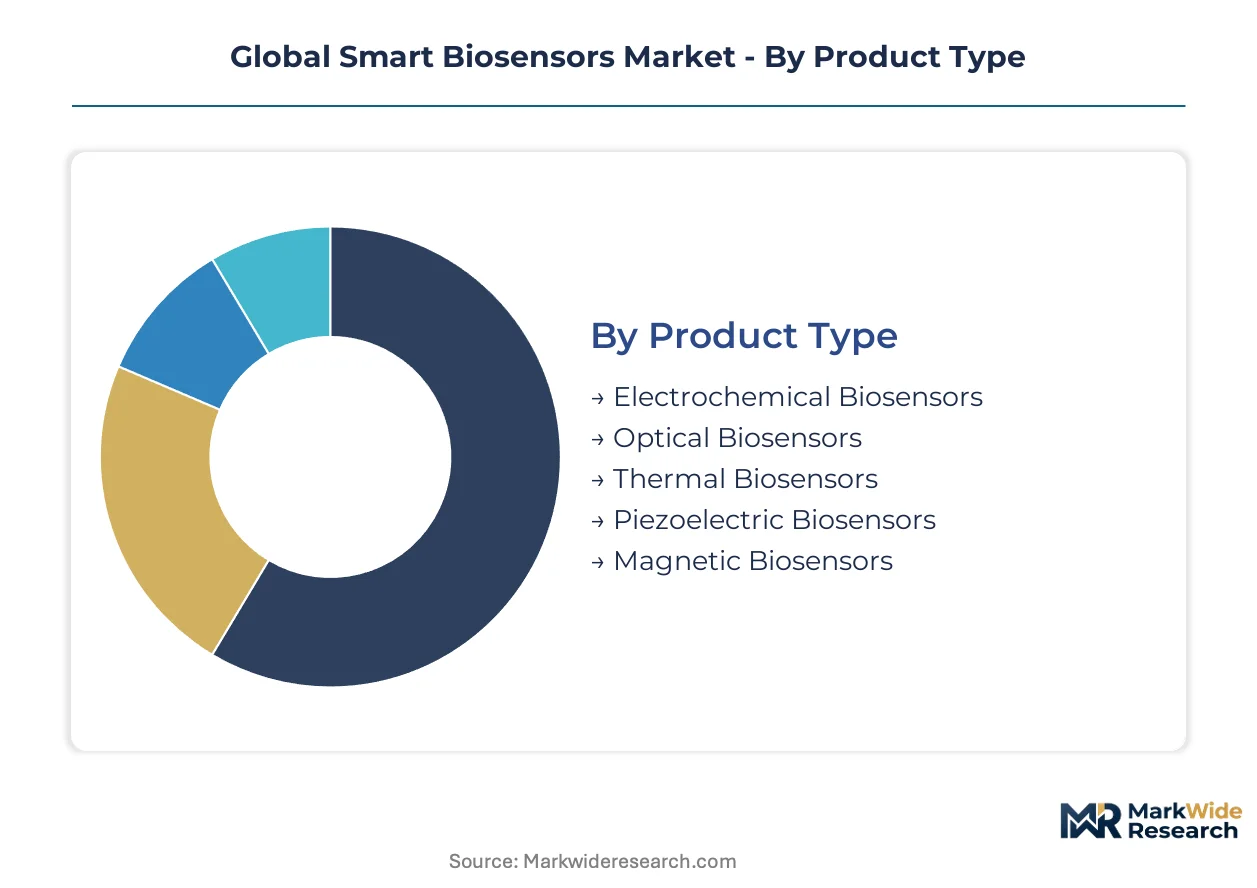
Segmentation in the smart biosensor market reveals divergent commercial rhythms. Product categories range from mature glucose strips with 18-month replacement cycles to optical platforms with decade-long validation timelines. Understanding these turnover velocities shapes capital allocation and partnership strategies for component suppliers and system integrators.
Product Type:
Cycle times stretch from rapid consumables turnover to decade-long capital equipment amortization, with electrochemical strips turning every 12-18 months against optical platform lifecycles exceeding seven years.
- Electrochemical Biosensors:Enzyme-functionalized electrodes convert biochemical signals into current or potential changes, with glucose oxidase immobilization dominating diabetes management strips. Demand concentrates in German and Swiss diagnostic manufacturing clusters where automated reel-to-reel coating lines achieve million-unit daily throughput. Palladium price volatility compresses margins for electrode catalyst layers.
- Optical Biosensors:Surface plasmon resonance and fluorescence-based architectures detect refractive index shifts from biomolecular binding events. Pharmaceutical QC laboratories in Basel and Boston drive displacement of legacy ELISA workflows, demanding multiplexed analyte detection from single sensor sites.
- Thermal Biosensors:Calorimetric detection measures heat from enzymatic reactions, finding niche deployment in food safety screening where thermal stability matters.
- Piezoelectric Biosensors:Quartz crystal microbalance platforms detect mass changes from antigen-antibody binding, serving environmental monitoring networks in Japan.
- Magnetic Biosensors:Giant magnetoresistance elements detect magnetically labeled biomarkers, emerging in point-of-care sepsis diagnostics.
Electrochemical biosensors anchor the volume base while optical biosensors gain share at the steepest rate.
Technology:
Cost tiers separate commoditized wireless modules from premium nanomaterial functionalization, with MEMS fabrication occupying the mid-tier capital intensity band.
- Nanotechnology:Graphene and quantum dot functionalization push detection limits to picomolar concentrations. Fraunhofer institutes in Germany accelerate CVD-grown monolayer transfer from academic prototype to glucose monitor manufacturing.
- Microfluidics:Laminated polymer cartridges integrate sample preparation with detection chambers, dominating point-of-care infectious disease testing in Indian rural health networks.
- MEMS:Surface micromachining produces mass-producible transducer arrays for wearable form factors, with Baden-Württemberg industrial clusters lowering unit economics through shared foundry access.
- Artificial Intelligence:Machine learning interpretation of spectral plasmon shift data enables metabolic panel applications beyond single-analyte tracking, though FDA-EU validation divergence forces redundant clinical studies.
- Wireless Connectivity:Bluetooth Low Energy and NFC modules transmit encrypted biometric data, with IEC 62304 software lifecycle compliance extending development timelines.
Wireless connectivity commands the lowest margin tier while nanotechnology functionalization captures the highest value-add per unit.
Application:
Customer maturity separates regulated medical diagnostics from exploratory biotechnology research, with bioprocess control occupying the fastest-expanding intermediate zone.
- Medical Diagnostics:Continuous glucose monitors and cardiac biomarker assays dominate revenue, with asset-light leasing models narrowing capital barriers for diabetes management hardware.
- Environmental Monitoring:Heavy metal and pesticide detection networks deploy electrochemical and optical platforms across watershed monitoring stations in China.
- Food Quality Analysis:Pathogen and allergen screening drives thermal and piezoelectric sensor adoption in European dairy processing facilities.
- Bioprocess Control:Real-time metabolite tracking during perfusion cell culture replaces offline sampling, with pharmaceutical manufacturers in Massachusetts and Bavaria leading in-line glucose and lactate measurement deployment.
- Biotechnology Research:Surface plasmon resonance platforms support drug discovery binding kinetics, though academic procurement cycles lag industrial adoption by 24-36 months.
Medical diagnostics anchors installed base value while bioprocess control expands most quickly.
End User:
Procurement authority concentrates negotiating leverage differently across settings, with hospital networks unbundling hardware from reagent contracts while pharmaceutical companies retain integrated platform preferences.
- Hospitals:French and Dutch hospital procurement committees increasingly separate capital equipment purchasing from consumable vendor lock-in, compressing margins for integrated suppliers.
- Diagnostic Laboratories:High-throughput facilities in Germany and Switzerland drive optical biosensor specialization, negotiating multi-source reagent agreements for surface plasmon resonance platforms.
- Pharmaceutical Companies:Bioprocess divisions demand connected electrochemical platforms with validated algorithmic outputs for GMP-compliant manufacturing.
- Agricultural Research Institutes:Soil and crop monitoring applications favor low-cost electrochemical point-of-care platforms for nutrient analysis.
- Academic Institutions:Research-grade optical platforms support publication-driven procurement, with longer sales cycles and price sensitivity to grant funding fluctuations.
Diagnostic laboratories concentrate volume demand while pharmaceutical companies drive the steepest technology upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in smart biosensors tilt toward net-importing markets with advanced healthcare infrastructure, while manufacturing hubs in Germany and China supply electrochemical strips and MEMS components to diagnostic device assemblers worldwide.
United States
FDA Software as a Medical Device guidance accelerates validation requirements for AI-integrated diagnostic tools, pulling venture capital toward Boston and San Francisco Bay Area startups developing closed-loop insulin delivery algorithms. Pharmaceutical bioprocess divisions in Massachusetts deploy connected electrochemical platforms for real-time metabolite tracking during perfusion cell culture.
Germany
Fraunhofer institutes and industrial clusters in Baden-Württemberg drive MEMS-based sensor commercialization through shared foundry access that lowers unit economics for wearable form factors. EU Medical Device Regulation imposes algorithmic transparency requirements that force redundant clinical studies for cross-border deployment. Surface micromachining scale-up concentrates in Stuttgart and Freiburg for mass-producible transducer arrays.
China
NMPA streamlined innovation pathways for Class II connected monitoring devices compress regulatory timelines for wireless cardiac and metabolic monitors, accelerating market access for domestic platform developers. Environmental monitoring networks deploy electrochemical and optical platforms across watershed stations in the Yangtze River Delta. Shanghai and Suzhou house the largest concentration of glucose oxidase electrode coating lines outside Europe.
Switzerland
Swissmedic maintains stringent premarket authorization timelines that favor established players with validated quality management systems, reinforcing Basel's dominance in pharmaceutical QC laboratory equipment. REACH restrictions on perfluorinated substances force rapid reformulation of hydrophobic membrane materials among component suppliers. Roche Diagnostics anchors optical biosensor specialization for high-throughput diagnostic laboratories from its Mannheim and Rotkreuz facilities.
India
CDSCO regulatory harmonization with IMDRF standards accelerates import licensing for electrochemical point-of-care platforms targeting underpenetrated rural health networks. PLI scheme incentives for medical device manufacturing attract glucose strip assemblers to Gujarat and Karnataka special economic zones. Hyderabad and Bengaluru clusters develop microfluidic cartridges for HbA1c and lipid panel screening outside tertiary hospital systems.
Global Smart Biosensors Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated electrochemical strip manufacturers and optical platform specialists with captive pharmaceutical QC relationships. Three strategic archetypes dominate: diabetes-focused hardware-leasing operators, pharmaceutical bioprocess control integrators, and nanomaterial-enabled sensor component suppliers. Competitive intensity centers on backward integration into palladium catalyst supply chains and geographic expansion through regulatory sandbox partnerships in Asian markets.
Among US-based diversified health technology conglomerates, Abbott Laboratories and Medtronic exemplify contrasting archetypes within diabetes management, while Roche Diagnostics anchors the European optical specialization tier. Abbott's vertical integration across electrochemical strip manufacturing sustains cost advantages in high-volume glucose monitoring consumables. Medtronic occupies a position defined by deep R&D intensity in closed-loop therapeutic systems. Roche represents the pharmaceutical QC laboratory vector where surface plasmon resonance platforms displace legacy immunoassay workflows.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Roche Diagnostics |
| Siemens Healthineers |
| Dexcom |
| Philips Healthcare |
| Biosensors International Group |
| Bio-Rad Laboratories |
| Acon Laboratories |
| Others |
Supply & Pricing Matrix
Palladium catalyst suppliers in South Africa and Russia anchor cost structures for electrochemical glucose strips, concentrating margin pools with electrode manufacturers who maintain long-term offtake agreements against spot market volatility. This upstream concentration forces downstream pricing discipline among diagnostic device assemblers competing on consumable unit economics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in electrochemical biosensor procurement. Price differentiation hinges on FDA clearance tier and volume scale commitments, with pharmaceutical bioprocess divisions least sensitive and Indian rural health networks most price-responsive. Pricing pressure stems from palladium spot volatility compressing strip margins, while optical platform vendors resist discounting through captive reagent lock-in.
Supply Chain Analysis
Extended payment terms from German MEMS foundries to Swiss diagnostic OEMs illustrate supply-chain finance facilities deepening working capital ties across the value chain. Manufacturing concentrates in Germany, China, and Switzerland for transducer arrays, glucose oxidase electrodes, and optical platform assembly respectively. The chain draws from palladium catalysts, CVD-grown graphene monolayers, and fluorine-free polymer membranes. Single-source vulnerability concentrates in South African PGM supply. Distribution runs through hospital procurement committees and pharmaceutical GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-leasing models for continuous glucose monitors are expanding service-attach revenue faster than device sales, positioning recurring consumable and algorithm-subscription streams as the primary value capture mechanism.
For Market Incumbents: Entrench position through backward integration into palladium catalyst supply chains and captive MEMS foundry capacity in Baden-Württemberg. Optical platform substitution by surface plasmon resonance systems threatens legacy ELISA-anchored revenue; defend through multi-source reagent agreements with French and Dutch hospital networks. FDA-EU validation divergence demands redundant clinical study investment as table stakes for cross-border deployment. For New Entrants and Emerging Players: Indian rural health networks outside tertiary hospital systems represent the most penetrable entry point for low-cost electrochemical HbA1c and lipid panel platforms. Microfluidic cartridge partnerships with Hyderabad and Bengaluru clusters offer localized manufacturing scale without cleanroom capital intensity. Target CDSCO regulatory harmonization as the go-to-market accelerant for import licensing speed. For Investors and Strategic Acquirers: Capital is best deployed toward nanomaterial-enabled sensor component suppliers with CVD graphene transfer capabilities and validated pharmaceutical QC relationships. Long-term viability rests on differentiation beyond commodity electrode manufacturing. Watch NMPA innovation pathway expansion for domestic Chinese platform developers as an inflection signal for Western market access compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palladium Supply | Captive catalyst sourcing insulates Abbott and Roche from PGM spot volatility in strip manufacturing. |
| MEMS Foundry Capacity Expansion | Baden-Württemberg cluster scale-up lowers unit economics for wearable glucose monitor transducer arrays. |
| FDA Software as Medical Device Submission | AI-integrated diagnostic platforms require accelerated validation timelines for closed-loop insulin algorithms. |
| Multi-Source Reagent Agreement | French hospital procurement committees unbundle hardware from consumable vendor lock-in, compressing integrated supplier margins. |
| Biodegradable Substrate Redesign | EU Green Deal procurement mandates reward circular economy compliance for disposable sensor components. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital procurement managers, pharmaceutical bioprocess directors, and GPO contracts specialists and refined through secondary validation against FDA 510(k) filings, EMA medical device registrations, NMPA innovation pathway approvals, and hospital procurement database trends. Bottom-up modeling of electrochemical strip volumes and top-down triangulation against pharmaceutical QC equipment expenditure anchored value estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning transducer architecture, application maturity, and regional regulatory cluster. CAGRs derived from installed base turnover velocity and technology substitution curves incorporated bioprocess control adoption rates and wireless cardiac monitor deployment in NMPA streamlined pathways.
Practitioners should monitor palladium price volatility, REACH substance restriction timelines, and cybersecurity standard convergence for early signals of forecast revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Smart Temporal Thermometer Market