
 Global Medium Molecular Weight Polyisobutylene Market | 2026-2036
Global Medium Molecular Weight Polyisobutylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medium Molecular Weight Polyisobutylene Market Intelligence
The capital-intensity divergence between integrated petrochemical giants and specialized polymer modifiers is collapsing as medium-scale producers acquire proprietary catalyst systems. BASF SE leverages its Ludwigshafen integrated site to sustain backward integration into high-purity isobutylene feedstock. ExxonMobil Chemical Company anchors its position through Baton Rouge manufacturing scale and channel control across North American lubricant blenders. Kraton Corporation differentiates via hydrogenated styrenic block copolymer synergies and positions its polyisobutylene grades for medical and personal care applications.
Medium molecular weight polyisobutylene denotes a synthetic hydrocarbon polymer with number-average molecular weight typically ranging from 40,000 to 120,000 g/mol, produced via cationic polymerization of isobutylene using Lewis acid catalysts such as aluminum chloride or boron trifluoride. Its saturated backbone delivers oxidative stability, low moisture permeability, and permanent tack, making it indispensable in pressure-sensitive adhesives, engine oil viscosity modifiers, and moisture-barrier sealants. The adhesives and sealants application segment leads current volume absorption due to construction and automotive assembly demand, while personal care represents the fastest-growing structural pocket as formulators replace mineral oil with polymer-derived film formers. Lubricants remains a mature margin pool where INEOS and Chevron Phillips Chemical Company compete on technical service relationships with multinational blender networks.
The EPA regulates volatile organic compound emissions from adhesive and coating formulations under 40 CFR Part 59, directly limiting solvent-borne polyisobutylene deployment and accelerating water-based system development. REACH registration requirements under ECHA mandate full substance characterization for import volumes exceeding one tonne annually, elevating compliance costs for non-European suppliers accessing German and French downstream markets. Japan's METI chemical substance control law imposes additional polymer notification thresholds that Tosoh Corporation and ENEOS Corporation navigate through domestic manufacturing presence. Stakeholders must monitor regulatory divergence between EPA solvent restrictions, EU polymer registration timelines, and Asian green chemistry roadmaps when allocating capacity expansion capital.
Market Dynamics
REACH registration timelines and EPA solvent restrictions are compressing formulation flexibility while catalyzing water-based polyisobutylene system development across adhesive and sealant applications.
Growth Catalysts
- Automotive sealant demand:Electric vehicle battery enclosure sealing requirements are expanding medium molecular weight polyisobutylene consumption in thermal management gaskets and moisture barriers.
- REACH compliance premiums:Full substance characterization mandates under ECHA registration are elevating pricing power for European manufacturers with established dossiers.
- Personal care substitution:Formulators in Japan and South Korea are replacing mineral oil with polymer-derived film formers in sun care and color cosmetics.
Market Restraints
- High-purity isobutylene supply concentration:Captive feedstock control by integrated petrochemical operators in Germany and the United States limits independent producer margin expansion.
- Cationic polymerization catalyst costs:Boron trifluoride and aluminum chloride procurement volatility elevates production economics for medium-scale modifiers.
- Silicone sealant substitution:Room-temperature-vulcanizing silicone formulations are capturing high-temperature automotive gasket applications previously served by polyisobutylene.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO-regulated blister pack moisture barriers represent underpenetrated demand for medium molecular weight grades with low extractables profiles.
- EU Green Deal chemistry:Bio-based isobutylene feedstock qualification under EU taxonomy criteria creates first-mover positioning for certified polymer producers.
- Medical device convergence:Hydrogenated styrenic block copolymer blending with polyisobutylene is opening transdermal patch and wound dressing applications.
Industry Challenges
- Catalyst handling expertise scarcity:Lewis acid polymerization process safety and effluent management skills are concentrating at legacy production sites in Baton Rouge and Ludwigshafen.
- Multi-jurisdiction registration synchronization:Staggered ECHA, EPA, and METI notification timelines delay new grade commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medium Molecular Weight Polyisobutylene Market |
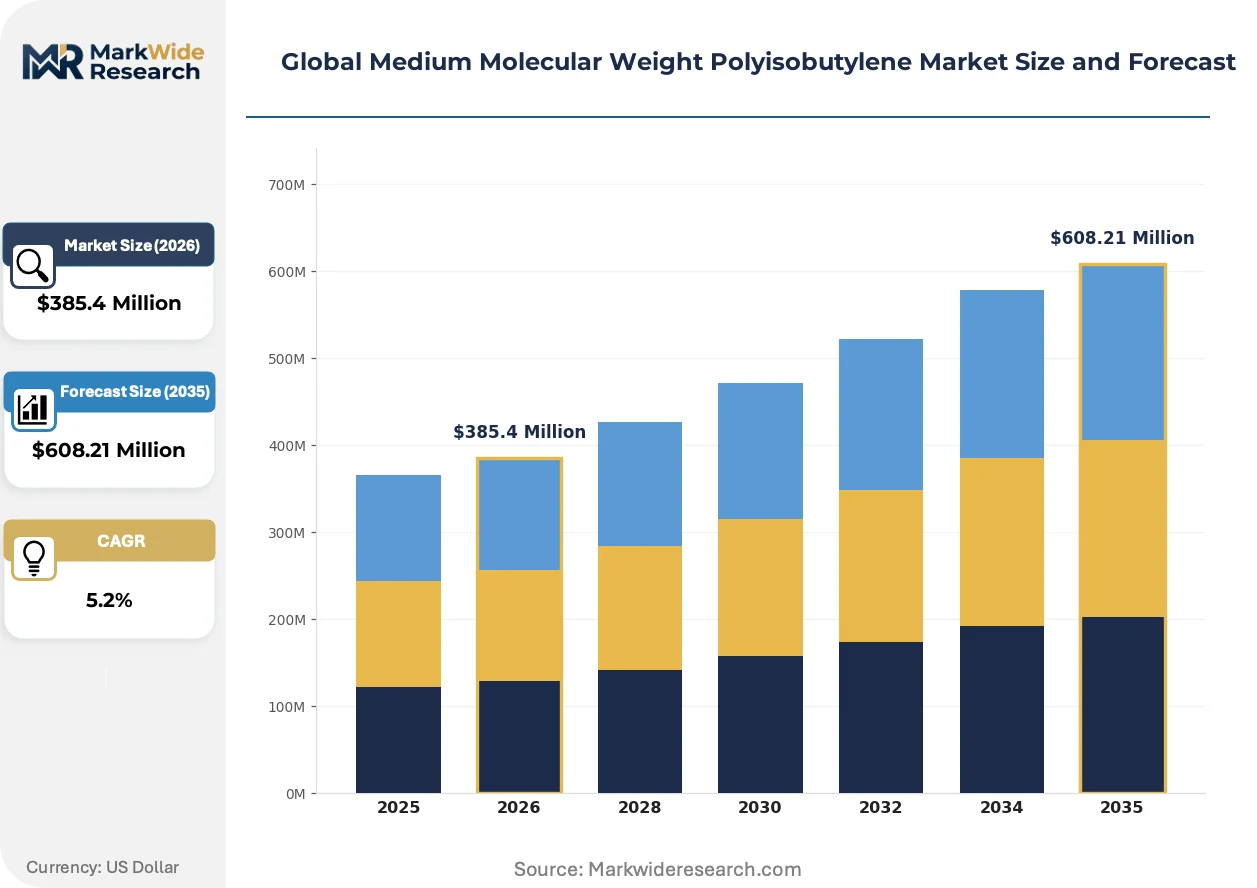
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Molecular Weight, Medium Molecular Weight, High Molecular Weight, Ultra-High Molecular Weight Application: Adhesives, Sealants, Lubricants, Personal Care, Coatings, Paper Additives End User Industry: Packaging Manufacturers, Chemical Producers, Automotive Suppliers, Consumer Goods, Electronics Fabricators Packaging Type: Bulk Bags, Drums, Intermediate Bulk Containers, Totes, Carboys, Pails |
| Companies Covered | BASF SE, ExxonMobil Chemical Company, Lubrizol Corporation, TPC Group, INEOS, Kraton Corporation, Chevron Phillips Chemical Company, Tosoh Corporation, ENEOS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medium Molecular Weight Polyisobutylene Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward water-borne and reactive systems as regulatory pressure on solvent emissions intensifies across German automotive assembly and Japanese electronics manufacturing.
Water-based polyisobutylene emulsion technology is displacing solvent-borne hot-melt formulations in pressure-sensitive adhesive tapes. Tape converters in South Korea and Taiwan are adopting these systems to meet brand-owner sustainability procurement criteria. The shift is compressing traditional solvent-based capacity utilization while expanding emulsion polymerization equipment investments.
EPA 40 CFR Part 59 volatile organic compound limits are tightening adhesive formulation allowances in US automotive assembly plants. The regulation is forcing reformulation of seam sealers and underbody coatings toward exempt solvent or water-based polyisobutylene carriers. Tier-1 suppliers in Michigan and Ohio are qualifying new grade specifications to maintain OEM supply contracts.
Direct mill-base supply contracts are consolidating lubricant additive procurement relationships. Multinational blenders in Rotterdam and Singapore are bypassing traditional distributors to secure technical service directly from polymer modifiers. The pattern concentrates volume with integrated producers capable of custom viscosity grade development and just-in-time delivery.
Global Medium Molecular Weight Polyisobutylene Market Segmentation
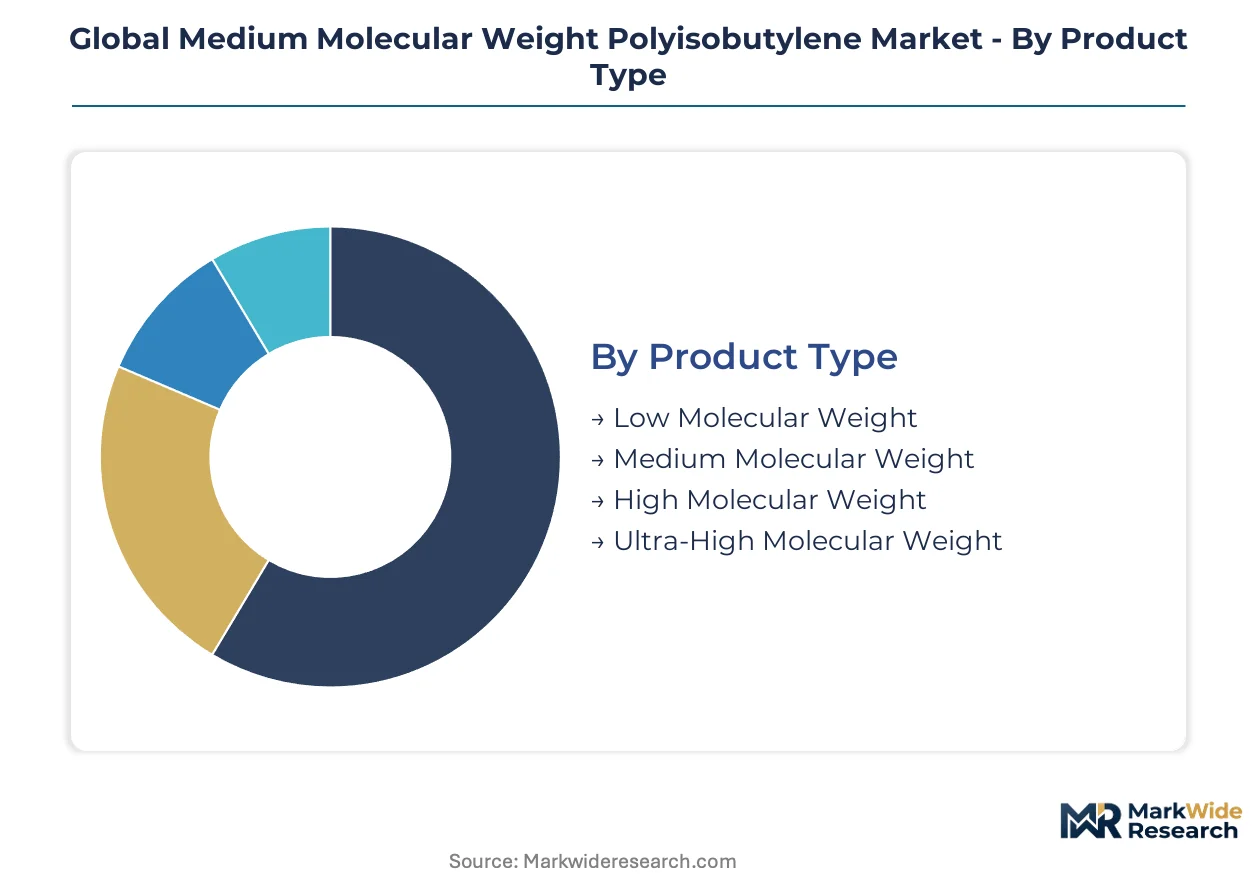
Segmentation in medium molecular weight polyisobutylene reveals how molecular architecture, formulation chemistry, and procurement logistics create distinct margin architectures. Each dimension governs access to different end-use value pools and regulatory compliance requirements.
Product Type:
Margin pools concentrate in specialty grades where catalyst control and molecular weight distribution precision command formulation premiums.
- Medium Molecular Weight:Number-average molecular weight of 40,000-120,000 g/mol delivers the oxidative stability and permanent tack that automotive sealant formulators specify. Demand concentrates in German automotive assembly plants where thermal management gasket specifications are tightening. REACH dossier completeness separates European producers from import competitors.
- Low Molecular Weight:Shorter chain lengths below 40,000 g/mol function as viscosity modifiers and plasticizers in adhesive compounding. Japanese electronics manufacturers specify these grades for temporary bonding applications in semiconductor packaging where low residue is critical.
- High Molecular Weight:Chains exceeding 120,000 g/mol provide enhanced mechanical strength for roofing membrane and heavy-duty tape applications.
- Ultra-High Molecular Weight:Extreme chain length polymers serve specialized medical device and pharmaceutical packaging films requiring maximum barrier properties.
The dominant share belongs to Medium Molecular Weight, while Personal Care substitution trends are expanding Low Molecular Weight volumes fastest.
Application:
Application-driven segmentation tracks how regulatory pressure on solvent emissions is redistributing volume across water-borne versus hot-melt formulation technologies.
- Adhesives:Pressure-sensitive tape and label formulations consume the largest volume share of medium molecular weight grades. South Korean converters are adopting water-based emulsion systems to meet brand-owner sustainability procurement criteria, compressing traditional solvent-borne capacity.
- Personal Care:Polymer-derived film formers are displacing mineral oil in Japanese and South Korean sun care and color cosmetics. METI chemical substance notification requirements favor domestic polymer producers with established compliance pathways.
- Sealants:Moisture-barrier formulations for construction and automotive assembly require specific tack and elongation properties.
- Lubricants:Viscosity index improvers for engine oils represent a mature margin pool where technical service relationships govern procurement.
- Coatings:Protective and corrosion-resistant layers incorporate polyisobutylene for moisture impermeability.
- Paper Additives:Sizing and barrier coatings for food packaging leverage low moisture permeability.
Adhesives holds the largest volume position, though Personal Care is climbing the fastest as clean beauty formulations accelerate polymer substitution.
End User Industry:
Customer concentration patterns reflect how downstream formulation capabilities cluster near specialty chemical manufacturing hubs.
- Automotive Suppliers:Tier-1 manufacturers in Michigan, Ohio, and Stuttgart specify medium molecular weight grades for electric vehicle battery enclosure sealing. EPA 40 CFR Part 59 VOC limits are forcing reformulation of seam sealers toward exempt solvent or water-based carriers.
- Packaging Manufacturers:Pharmaceutical blister pack producers in India are qualifying medium molecular weight grades with low extractables profiles under CDSCO regulations. Moisture barrier specifications for tropical climate distribution are expanding specification testing.
- Chemical Producers:Polymer modifiers and compounders blend polyisobutylene into specialty adhesive and sealant formulations.
- Consumer Goods:Personal care and household product formulators specify cosmetic-grade polymer derivatives.
- Electronics Fabricators:Semiconductor and display manufacturers use precision-grade materials for temporary bonding and protection.
Automotive Suppliers command the highest volume absorption, while Packaging Manufacturers are gaining share fastest on pharmaceutical export growth.
Packaging Type:
Packaging configuration directly determines logistics economics and contamination risk profiles for polymer supply chains.
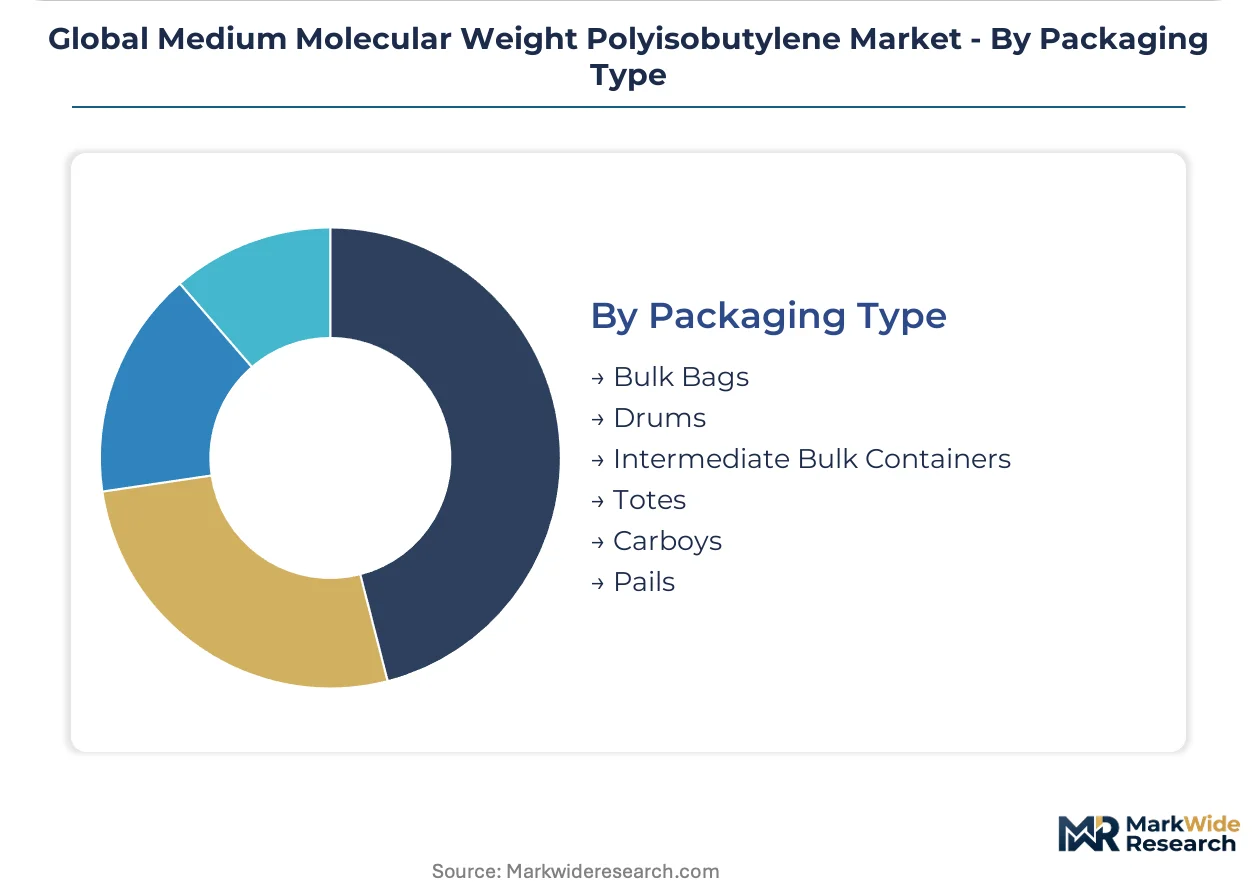
- Drums:Standard 200-liter steel and plastic drums dominate lubricant additive and adhesive compounder procurement. Rotterdam and Singapore blenders are consolidating direct mill-base contracts, bypassing distributors for just-in-time drum deliveries.
- Intermediate Bulk Containers:IBC totes of 1,000-liter capacity serve high-volume automotive sealant manufacturers in Baton Rouge and Ludwigshafen where integrated sites enable pipeline-fed production.
- Bulk Bags:Flexible intermediate bulk containers suit powder or pelletized formulations for construction adhesive compounders.
- Totes:Rigid polyethylene containers provide intermediate volumes for specialty chemical producers.
- Carboys:Smaller glass or plastic vessels serve laboratory and pilot-scale formulation development.
- Pails:Five-gallon containers target maintenance-repair-operations and small-batch compounders.
Drums retain the dominant procurement share, while Intermediate Bulk Containers are expanding fastest as direct supplier relationships concentrate volume with integrated producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and South Korea demonstrate the lowest price elasticity, accepting premiums for cosmetic-grade polymer film formers, while Indian pharmaceutical packaging converters remain highly sensitive to landed cost differentials.
United States
Electric vehicle battery enclosure sealing specifications at Michigan and Ohio assembly plants are expanding medium molecular weight grade consumption. EPA 40 CFR Part 59 VOC limits are forcing reformulation of automotive seam sealers toward exempt solvent carriers. Baton Rouge manufacturing clusters anchor North American supply through integrated petrochemical sites with pipeline-fed production.
Germany
Thermal management gasket requirements at Stuttgart automotive plants are tightening purity specifications for sealant-grade polymers. REACH dossier completeness under ECHA mandates separates domestic producers from import competitors facing registration delays. The Ludwigshafen chemical cluster sustains backward integration into high-purity isobutylene feedstock through integrated refining-polymerization operations.
Japan
Sun care and color cosmetics formulators in Tokyo and Osaka are replacing mineral oil with polymer-derived film formers. METI chemical substance notification thresholds favor domestic producers with established compliance pathways. The Kanto and Kansai manufacturing belts concentrate hydrogenated styrenic block copolymer blending capabilities for medical device applications.
South Korea
Tape converters in Seoul and Busan are adopting water-based polyisobutylene emulsion systems to meet brand-owner sustainability procurement criteria. The country's green chemistry roadmap accelerates solvent-borne capacity displacement. Domestic electronics manufacturers specify precision-grade materials for semiconductor packaging temporary bonding applications.
India
Pharmaceutical blister pack producers in Mumbai and Hyderabad are qualifying medium molecular weight grades with low extractables profiles under CDSCO regulations. Moisture barrier specifications for tropical climate distribution are expanding specification testing protocols. Import dependency on European and East Asian supply creates landed cost volatility for domestic converters.
Global Medium Molecular Weight Polyisobutylene Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated petrochemical giants commanding feedstock economics while specialized polymer modifiers capture formulation premiums. The market structure concentrates around three tiers: multinational chemical conglomerates with backward integration, mid-scale modifiers with catalyst expertise, and regional compounders serving niche applications. Strategic archetypes include captive-feedstock operators, hydrogenation specialists, and custom viscosity-grade developers. Dominant competitive moves center on direct mill-base supply contract consolidation and water-based emulsion technology licensing.
Among integrated petrochemical operators, BASF SE and ExxonMobil Chemical Company occupy positions exemplifying captive-feedstock control through major European and North American manufacturing sites. Kraton Corporation represents the specialized modifier archetype, sitting within the hydrogenated styrenic block copolymer synergy segment that serves medical and personal care applications. These three companies anchor the competitive spectrum from commodity-scale supply to premium-grade formulation technology.
| Leading Market Players |
|---|
| BASF SE |
| ExxonMobil Chemical Company |
| Lubrizol Corporation |
| TPC Group |
| INEOS |
| Kraton Corporation |
| Chevron Phillips Chemical Company |
| Tosoh Corporation |
| ENEOS Corporation |
| Others |
Cost & Logistics Intelligence
Mineral oil replacement by polymer-derived film formers in Japanese and South Korean personal care formulations is simultaneously redrawing raw material sourcing maps and compressing margin structures for traditional sealant-grade suppliers. This substitution dynamic concentrates pricing power with domestic producers holding METI-compliant dossiers while forcing import-dependent compounders to absorb higher landed costs.
Pricing Analysis
After-sales technical service contracts and formulation support agreements drive lifetime value capture for polymer modifiers serving multinational lubricant blenders. Three-tier pricing structure across REACH-certified premium, standard industrial, and economy grades separates European producers with complete ECHA dossiers from import competitors facing registration delays. Cost compression in the economy tier is intensifying because Indian pharmaceutical packaging converters negotiate aggressively on landed cost differentials. Automotive suppliers in Michigan and Ohio demonstrate the lowest price sensitivity, accepting premiums for EV battery enclosure sealing specifications.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam are elevating inbound logistics costs for non-integrated polymer modifiers sourcing catalyst systems. Manufacturing concentrates in Germany, the United States, and Japan where integrated petrochemical sites control high-purity isobutylene feedstock. Production rests on boron trifluoride and aluminum chloride catalyst procurement, plus hydrogenated styrenic block copolymer blending capabilities for medical applications. Single-source vulnerability from captive feedstock control by BASF's Ludwigshafen and ExxonMobil's Baton Rouge sites threatens independent producer margins. Distribution runs through direct mill-base contracts consolidating volume with integrated producers capable of just-in-time drum and IBC deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
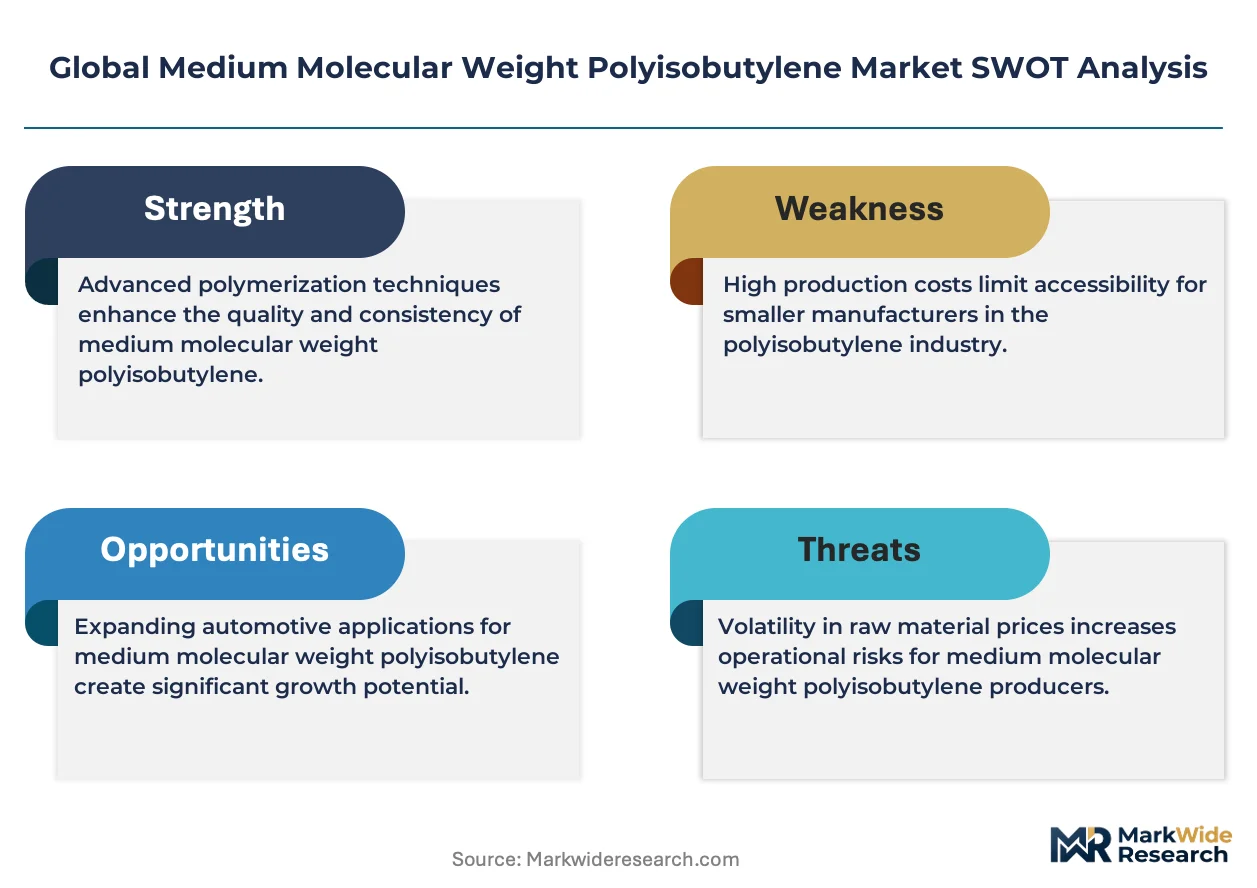
This market demands substitution defense as room-temperature-vulcanizing silicone sealants capture high-temperature automotive gasket applications previously served by polyisobutylene. Incumbents must navigate this material threat while preserving formulation relationships.
For Market Incumbents: Shield adhesive grade market share by accelerating water-based emulsion technology licensing to South Korean tape converters facing brand-owner sustainability procurement criteria. Deepen backward integration into high-purity isobutylene feedstock through pipeline-fed production investments at legacy sites. Secure REACH dossier completeness ahead of staggered ECHA notification timelines to maintain pricing power over import competitors.
For New Entrants and Emerging Players: Differentiate on low-extractables pharmaceutical grades targeting CDSCO-regulated blister pack moisture barriers in Mumbai and Hyderabad. Capture white-space opportunity in Indian pharmaceutical packaging where import dependency creates specification gaps for tropical climate distribution. Pursue direct technical service relationships with domestic converters bypassing European distributor markups.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors hydrogenated styrenic block copolymer synergy specialists with medical device application pipelines. Long-term viability hinges on bio-based isobutylene feedstock qualification under EU taxonomy criteria creating first-mover positioning. Watch for ECHA registration timeline acceleration as inflection indicator for import competitor market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Emulsion Technology Licensing | South Korean tape converters adopt systems to meet brand-owner sustainability procurement criteria. |
| Backward Integration into High-Purity Isobutylene | BASF's Ludwigshafen site sustains captive feedstock control through integrated refining-polymerization operations. |
| REACH Dossier Completion Investment | ECHA registration mandates separate domestic producers from import competitors facing 18-24 month delays. |
| Direct Mill-Base Supply Contract Consolidation | Rotterdam and Singapore blenders bypass distributors for just-in-time drum deliveries from integrated modifiers. |
| Bio-Based Feedstock Qualification | EU taxonomy criteria create first-mover positioning for certified polymer producers in personal care applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at integrated petrochemical sites, procurement leads at automotive Tier-1 suppliers, technical R&D directors at adhesive compounders, and distribution channel partners in Rotterdam and Singapore. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical producers, ECHA registration databases, and industry association reports from ACC and Cefic. Bottom-up volume modeling triangulated against top-down value estimates derived from downstream formulation demand.
Across the projection horizon, the analytical framework segmented volume and value by molecular weight tier, end-use industry cluster, packaging format configuration, and regional production hub concentration. CAGRs were derived from regression analysis of historical demand patterns against electric vehicle production forecasts, pharmaceutical export growth trajectories, and personal care formulation substitution rates. Forecast inputs incorporated EPA 40 CFR Part 59 VOC limit enforcement timelines and METI chemical substance notification threshold adjustments.
Decision-makers should treat outputs as directional under assumptions of stable catalyst procurement costs and sustained REACH registration timelines; material deviation would warrant model refresh. Specific risks that could revise projections include accelerated silicone sealant substitution in high-temperature automotive applications, ECHA registration deadline compression, and bio-based isobutylene feedstock cost parity achievement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
PA66 Market
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market