
 Polydicyclopentadiene (Pdcpd) Market | 2026-2036
Polydicyclopentadiene (Pdcpd) Market Size, Share, and Industry Trends Forecast 2026-2036
Polydicyclopentadiene (Pdcpd) Market Analytics
Multi-source resin procurement is realigning as compounders seek supply security for dicyclopentadiene feedstock. RIMTEC Corporation leverages captive metathesis technology to sustain cost advantages across Asian manufacturing bases. Metton anchors North American demand through specialized reaction injection molding capacity. Materia Inc. differentiates via catalyst-controlled polymer architectures that compete on performance metrics against epoxy alternatives.
Polydicyclopentadiene is a thermoset polymer synthesized through ring-opening metathesis polymerization of dicyclopentadiene monomer, yielding cross-linked networks with exceptional chemical resistance and impact strength at low density. The material serves primarily as a metal replacement in structural components requiring corrosion immunity and dimensional stability under thermal cycling. Thermosetting grades dominate current volume owing to established automotive and marine tooling ecosystems, while thermoplastic variants represent the fastest-expanding category as recyclability protocols tighten across European manufacturing. Aerospace applications command premium positioning due to flame-retardant certification requirements and long qualification cycles that protect incumbent suppliers.
EPA emissions standards and REACH substance restrictions are converging to disqualify legacy vinyl ester formulations in open-mold processes, redirecting specification engineers toward Pdcpd systems. Japan's METI maintains JIS certification pathways that govern material acceptance in railway and infrastructure applications. Stakeholders must monitor regulatory divergence between EU F-Gas Regulation phase-downs and US state-level low-VOC mandates to anticipate formulation reformulation cycles.
Market Dynamics
Automotive OEM lightweighting mandates are compressing qualification cycles for Pdcpd structural components, forcing resin suppliers to pre-certify formulations against multiple regulatory regimes simultaneously rather than sequential market entry.
Growth Catalysts
- EPA Tier 3 Emissions Standards:Open-mold vinyl ester processes face disqualification in US heavy-truck manufacturing, redirecting specification engineers toward Pdcpd reaction injection molding systems with near-zero VOC profiles.
- Railway Infrastructure Renewal:Japan's METI JIS certification pathway governs material acceptance in Shinkansen and urban transit applications, creating anchored demand for flame-retardant Pdcpd grades in undercarriage and interior structural modules.
- Marine Corrosion Resistance:DNV GL hull certification requirements for commercial vessels position Pdcpd as the specified replacement for steel in seawater-exposed superstructure components across Baltic and North Sea shipyards.
Market Restraints
- Dicyclopentadiene Feedstock Concentration:Steam cracker co-product availability concentrates in US Gulf Coast and Northeast Asian petrochemical complexes, exposing compounders to force majeure risk from ethylene demand cyclicality.
- Thermoset Recyclability Friction:Cross-linked network structures resist mechanical or chemical recycling under EU Waste Framework Directive protocols, triggering extended producer responsibility cost allocations in German and French manufacturing.
- Epoxy Interpenetrating Network Competition:Hybrid epoxy-Pdcpd formulations capture aerospace qualification slots due to established FAA flammability certification databases, delaying pure Pdcpd adoption in premium cabin interior segments.
Strategic Opportunities
- India PLI Scheme for Advanced Materials:Production-linked incentive allocations for automotive composites manufacturing create first-mover positioning for Pdcpd reaction injection molding cell deployment in Tamil Nadu and Gujarat industrial corridors.
- Offshore Wind Nacelle Housings:Dimensional stability under thermal cycling and salt spray resistance position Pdcpd as the specified material for 15+ MW turbine enclosures in North Sea and Baltic development zones.
- EU F-Gas Regulation Phase-Down:Blowing agent restrictions in polyurethane structural foam redirect cold-chain equipment manufacturers toward Pdcpd insulated panels with comparable R-values and simplified end-of-life handling.
Industry Challenges
- Ring-Opening Metathesis Polymerization Expertise Scarcity:Catalyst handling and process window control require specialized chemical engineering profiles concentrated in legacy polyolefin and synthetic rubber industries, constraining greenfield plant staffing.
- Multi-Regime Certification Parallel Processing:Simultaneous EPA, REACH, and METI dossier preparation stretches regulatory affairs teams at mid-scale compounders, delaying commercial launch timelines by 18-24 months relative to single-market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polydicyclopentadiene (Pdcpd) Market |
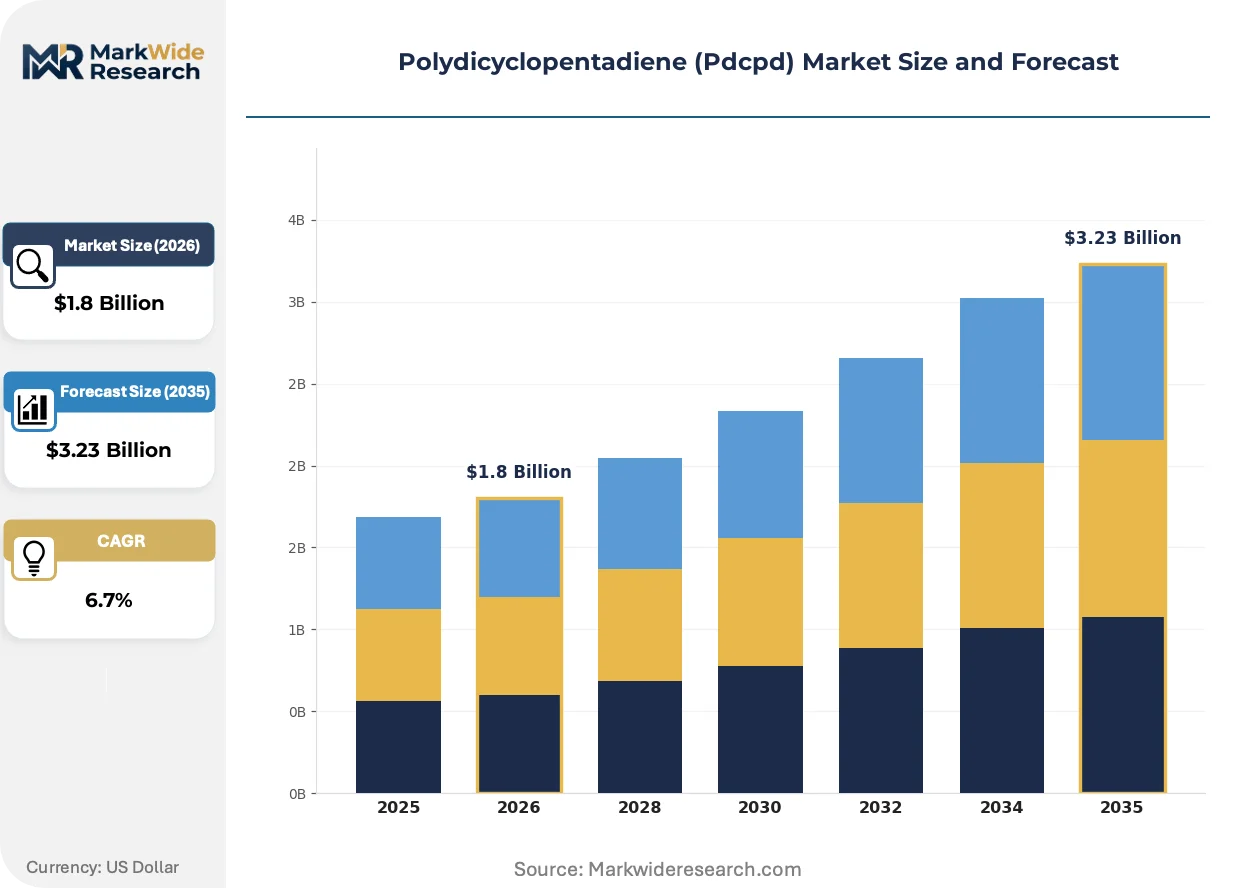
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exothermic, Endothermic, Thermoplastic, Thermosetting Application: Aerospace, Automotive Components, Electrical Insulation, Marine End User: Aerospace Manufacturers, Automotive OEMs, Electrical Industries, Marine Suppliers Form: Liquid, Solid, Powder, Granules |
| Companies Covered | RIMTEC Corporation, Metton, Materia Inc., Sojitz Corporation, ExxonMobil Chemicals, The Dow Chemical Company, Osborne Industries Inc., Core Molding Technologies, Polynt Composites USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polydicyclopentadiene (Pdcpd) Market Evolving Landscape
Catalyst architecture advances and regulatory convergence are compressing the traditional thermoset-thermoplastic hierarchy, enabling Pdcpd to capture applications previously locked into epoxy or metal stamping ecosystems.
Thermoplastic-compatible Pdcpd variants incorporating controlled molecular weight distributions are absorbing tooling investment from automotive OEMs seeking closed-loop material recovery under extended producer responsibility frameworks. BMW and Volvo manufacturing engineering groups have accelerated pilot line evaluations for bumper beam and underbody shield applications, with the technology absorbing capital allocation previously directed toward long-fiber thermoplastic polypropylene compounds. The structural consequence is a compression in traditional reaction injection molding equipment supplier margins as hybrid process technology licensing fragments the incumbent vendor base.
REACH Annex XIV authorization requirements for legacy phthalate-based plasticizers are forcing reformulation cycles across European open-mold composite shops. ECHA substance restriction proposals targeting styrene emissions in unsaturated polyester processes are redirecting tooling investment toward closed-mold Pdcpd reaction injection systems in German wind blade and French agricultural equipment manufacturing clusters. Marine and corrosion-protection segments exhibit the most pronounced specification migration, with shipyard engineering departments embedding Pdcpd alternatives into standard material selection databases ahead of formal regulatory effective dates.
Specification authority is migrating from tier-two compounders toward captive resin production units at major automotive OEMs. Ford and Stellantis materials engineering groups have established internal Pdcpd formulation capabilities, displacing traditional merchant resin procurement relationships. This concentration of formulation knowledge within Detroit and Turin engineering centers compresses pricing leverage for independent compounders and accelerates proprietary grade development cycles. The shift is most visible in North American heavy truck and European electric vehicle platform programs where vertical integration protects supply continuity against dicyclopentadiene feedstock volatility.
Polydicyclopentadiene (Pdcpd) Market Segmentation
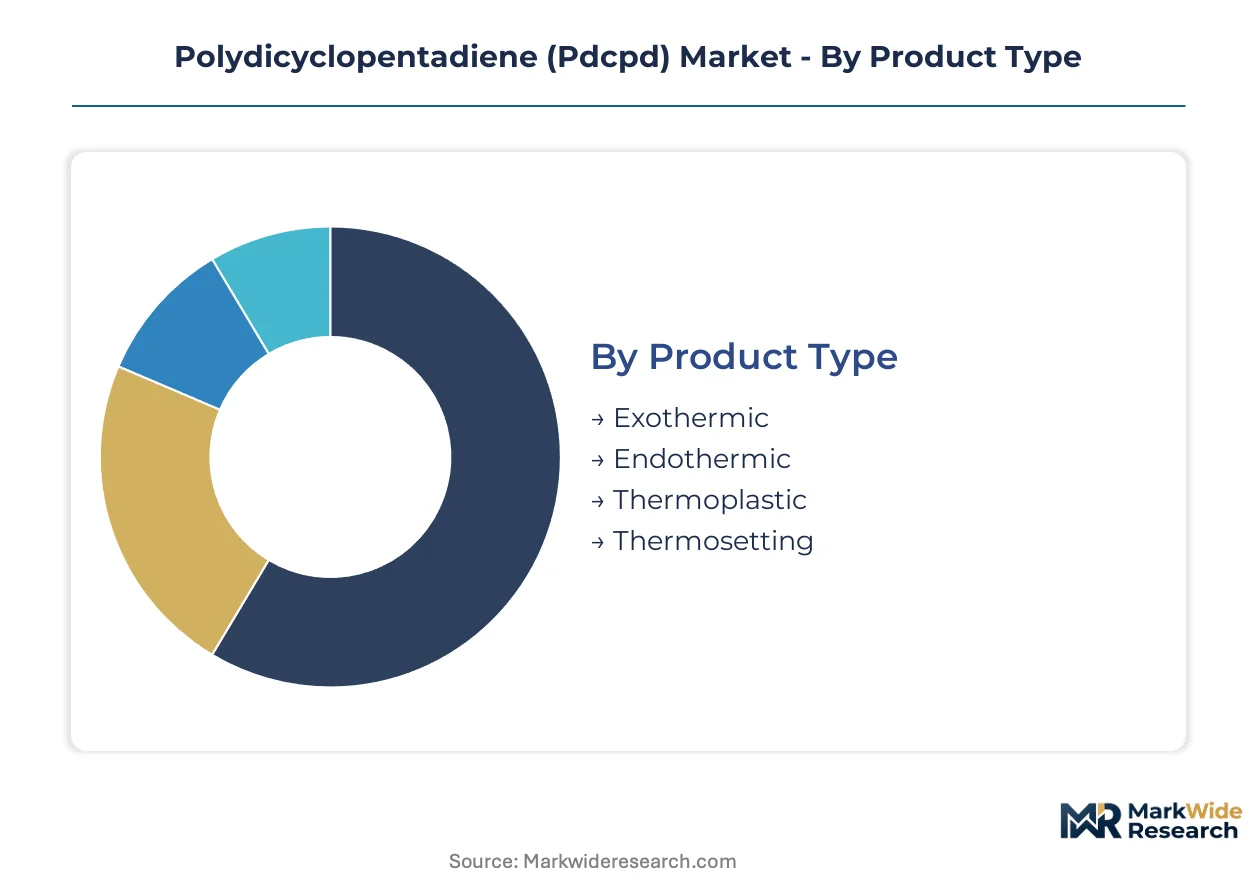
Pdcpd market segmentation reflects divergent technical requirements across reaction injection molding versus thermoforming processes, with each category commanding distinct catalyst architectures and regulatory compliance burdens. Specification engineers navigate trade-offs between cross-link density, processing temperature windows, and end-of-life handling protocols when selecting grade categories.
Product Type:
Cost tier differentiation separates commodity reaction molding grades from specialty controlled-architecture variants serving aerospace qualification pathways.
- Exothermic:These grades release substantial heat during ring-opening metathesis polymerization, enabling rapid cycle times in high-throughput automotive bumper beam production. Demand concentrates in Detroit and Turin manufacturing corridors where Ford and Stellantis internal compounding operations specify exothermic systems for underbody shield applications facing EPA Tier 3 VOC compliance deadlines.
- Thermosetting:Cross-linked network structures deliver dimensional stability under thermal cycling and chemical exposure, anchoring current volume in established marine tooling ecosystems. German and French shipyards specify thermosetting grades for DNV GL-certified hull components replacing steel in Baltic superstructure applications.
- Endothermic:Controlled heat absorption profiles suit thick-section molding without thermal runaway, serving electrical insulation housings requiring uniform cure through cross-sections.
- Thermoplastic:Reversible melt processing enables closed-loop recovery under EU Waste Framework Directive extended producer responsibility protocols, with BMW and Volvo pilot lines evaluating bumper beam applications.
Volume sits with thermosetting grades; growth tilts toward thermoplastic variants.
Application:
Application selection hinges on flame-retardant certification requirements and exposure severity, with aerospace and marine commanding premium positioning against automotive commodity specifications.
- Automotive Components:Structural reinforcement modules, bumper beams, and underbody shields exploit Pdcpd density advantages against steel and long-fiber thermoplastic polypropylene alternatives. Japan's METI JIS certification for railway applications is compressing automotive qualification cycles as resin suppliers pre-certify formulations across multiple regulatory regimes.
- Marine:Seawater corrosion immunity positions Pdcpd as specified replacement for steel in commercial vessel superstructures under DNV GL hull certification. North Sea and Baltic shipyards have embedded Pdcpd alternatives into standard material selection databases ahead of formal regulatory effective dates.
- Aerospace:Long FAA flammability qualification cycles and established epoxy certification databases protect hybrid epoxy-Pdcpd formulations in premium cabin interior segments.
- Electrical Insulation:Dielectric stability and thermal endurance serve transformer housings and switchgear components facing REACH Annex XIV phthalate plasticizer restrictions.
Marine anchors current revenue; automotive components are expanding most quickly.
End User:
Customer type determines formulation authority concentration, with captive resin production displacing merchant procurement relationships at volume manufacturers.
- Automotive OEMs:Vertical integration of formulation capabilities at Ford and Stellantis engineering centers has compressed pricing leverage for independent compounders. Internal Pdcpd development protects supply continuity against dicyclopentadiene feedstock volatility concentrated in US Gulf Coast steam cracker complexes.
- Marine Suppliers:Shipyard engineering departments specify Pdcpd for corrosion-critical superstructure components, with Baltic and North Sea yards leading specification migration from vinyl ester systems.
- Aerospace Manufacturers:Established epoxy interpenetrating network databases delay pure Pdcpd adoption despite catalyst-controlled polymer architecture advantages.
- Electrical Industries:Cold-chain equipment manufacturers redirect procurement toward Pdcpd insulated panels as EU F-Gas Regulation phase-downs restrict polyurethane blowing agents.
Procurement authority concentrates at automotive OEMs; specification migration accelerates fastest among marine suppliers.
Form:
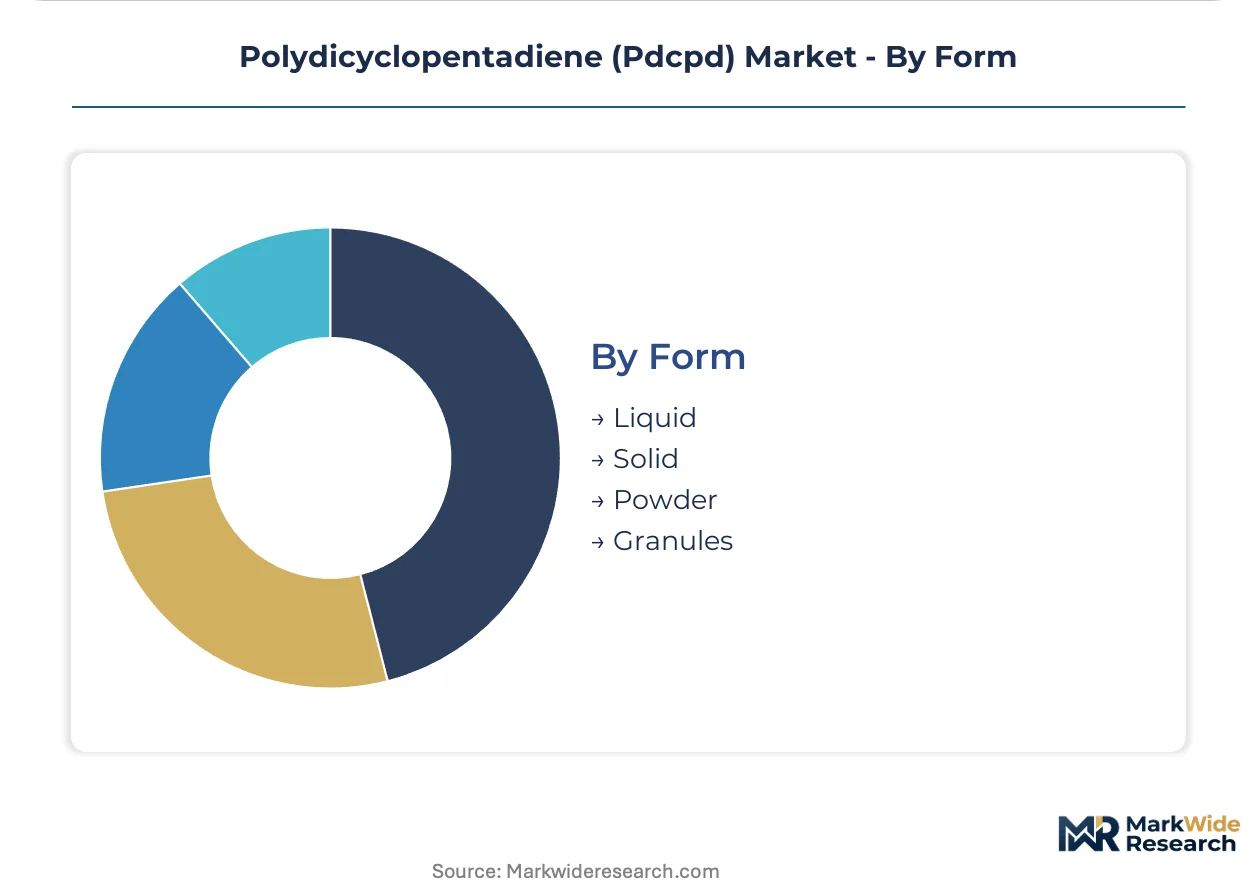
Physical form selection maps directly to process technology investment, with liquid grades dominating reaction injection molding and solid forms serving compression molding retrofits.
- Liquid:Low-viscosity dicyclopentadiene monomer formulations enable closed-mold reaction injection molding with near-zero VOC profiles, qualifying under EPA Tier 3 and REACH styrene emission restrictions.
- Solid:Pre-polymerized blocks and sheets suit compression molding and machining operations in prototype and repair applications.
- Powder:Finely divided grades serve rotational molding and powder coating processes for corrosion protection linings.
- Granules:Controlled particle size distributions feed twin-screw extrusion compounding lines for thermoplastic Pdcpd alloy development.
Liquid forms command installed process base; granule demand is climbing the fastest on thermoplastic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dicyclopentadiene feedstock availability concentrates in US Gulf Coast steam cracker complexes and Northeast Asian petrochemical corridors, anchoring Pdcpd manufacturing geography. Automotive OEM lightweighting mandates and marine corrosion standards are redirecting specification flows toward regional compounding hubs.
United States
Heavy-truck manufacturers face EPA Tier 3 emissions deadlines that disqualify open-mold vinyl ester processes. Detroit engineering centers at Ford and Stellantis have internalized Pdcpd formulation capabilities. The Gulf Coast petrochemical corridor supplies dicyclopentadiene monomer from ethylene co-production, though force majeure exposure persists from cracker demand cyclicality.
Germany
DNV GL hull certification requirements position Pdcpd as specified steel replacement for Baltic shipyard superstructures. ECHA REACH Annex XIV restrictions on phthalate plasticizers force reformulation cycles across wind blade manufacturing clusters. Hamburg and Bremerhaven shipyards have embedded Pdcpd alternatives into standard material selection databases ahead of formal regulatory effective dates.
Japan
METI JIS certification pathways govern material acceptance in Shinkansen undercarriage and urban transit interior modules. Nagoya and Osaka industrial corridors anchor reaction injection molding capacity for railway infrastructure renewal. The country's synthetic rubber industry legacy concentrates ring-opening metathesis polymerization expertise that constrains greenfield plant staffing elsewhere.
China
Northeast Asian steam cracker complexes supply dicyclopentadiene feedstock, though merchant availability remains tethered to ethylene demand cycles. Yangtze River Delta manufacturing bases evaluate Pdcpd for automotive bumper beam applications as domestic OEMs accelerate lightweighting programs. MIIT industrial standards for advanced composites are tightening material specifications in parallel with European REACH convergence.
India
PLI scheme allocations for automotive composites manufacturing create first-mover positioning for reaction injection molding cell deployment. Tamil Nadu and Gujarat industrial corridors attract capital as global compounders seek supply security outside concentrated Northeast Asian feedstock zones. BIS certification pathways for railway and infrastructure applications remain under development relative to mature METI and EPA regimes.
Polydicyclopentadiene (Pdcpd) Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders secure dicyclopentadiene feedstock access across multiple geographies simultaneously. The vendor base separates into three tiers: petrochemical majors with captive monomer supply, specialized reaction injection molding technology licensors, and automotive-integrated formulation developers. Strategic archetypes include upstream-integrated resin producers, process technology specialists, and OEM-captive compounding operations. Technology licensing and backward integration into metathesis catalyst production represent the dominant competitive vectors.
Among specialized technology developers, RIMTEC Corporation, Metton, and Materia Inc. occupy distinct positioning archetypes. RIMTEC exemplifies the Asian-based process licensor model with captive metathesis capabilities. Metton anchors North American demand through established reaction injection molding infrastructure. Materia represents the catalyst-architecture specialist tier competing on controlled polymer performance metrics. These three entities illustrate how technology differentiation fragments what would otherwise concentrate around petrochemical feedstock control.
| Leading Market Players |
|---|
| RIMTEC Corporation |
| Metton |
| Materia Inc. |
| Sojitz Corporation |
| ExxonMobil Chemicals |
| The Dow Chemical Company |
| Osborne Industries Inc. |
| Core Molding Technologies |
| Polynt Composites USA Inc. |
| Others |
Value Network & Pricing Analysis
Automotive OEM captive resin production is compressing merchant compounder margins and forcing supply chain reconfiguration toward feedstock-integrated producers. This procurement shift concentrates pricing power with Gulf Coast and Northeast Asian petrochemical complexes that control dicyclopentadiene monomer availability.
Pricing Analysis
Warranty and technical service bundling separates premium catalyst-controlled formulations from commodity reaction injection molding grades. Three-tier pricing structure across aerospace-qualified, automotive-specified, and industrial-standard levels reflects certification burden and formulation complexity. Cost compression in automotive commodity tiers is intensifying because Ford and Stellantis internal compounding operations displace merchant procurement. Marine and aerospace segments exhibit lowest price sensitivity due to DNV GL and FAA qualification timelines that protect incumbent suppliers.
Supply Chain Analysis
Freight costs for liquid dicyclopentadiene monomer concentrate procurement leverage around US Gulf Coast steam cracker complexes and Northeast Asian petrochemical corridors in Japan and South Korea. Manufacturing draws from ethylene co-product streams, ruthenium-based metathesis catalysts, and specialized reaction injection molding equipment. Single-source vulnerability runs through concentrated dicyclopentadiene feedstock zones exposed to ethylene demand cyclicality. Distribution runs through captive OEM supply chains, merchant compounder networks, and marine shipyard direct specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around feedstock-integrated producers as dicyclopentadiene availability constraints force smaller compounders toward acquisition or exit. Regulatory compliance burden and catalyst expertise scarcity accelerate this pressure.
For Market Incumbents: Anticipate specification authority migration by securing captive monomer supply through backward integration into Gulf Coast or Northeast Asian steam cracker networks. Accelerate multi-regime certification parallel processing capabilities to compress 18-24 month EPA-REACH-METI dossier timelines that currently delay commercial launches against integrated OEM competitors.
For New Entrants and Emerging Players: The price-point gap between aerospace-qualified premium grades and automotive commodity specifications creates entry space for mid-tier performance positioning. Target thermoplastic Pdcpd variants for European automotive OEMs facing EU Waste Framework Directive extended producer responsibility costs. Pursue process technology licensing rather than greenfield manufacturing to bypass ring-opening metathesis polymerization expertise scarcity.
For Investors and Strategic Acquirers: The window for entry favors catalyst-architecture specialists and regional reaction injection molding technology licensors with established METI or EPA certification databases. Mid-scale compounders without feedstock integration represent distressed acquisition targets as automotive OEM vertical integration accelerates. Monitor BIS certification pathway development in India as signal for PLI scheme allocation effectiveness and first-mover positioning validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dicyclopentadiene Feedstock | Captive monomer supply insulates against Gulf Coast ethylene cyclicality and force majeure exposure. |
| Multi-Regime Certification Parallel Processing | Simultaneous EPA-REACH-METI dossier preparation compresses commercial launch timelines against sequential entrants. |
| Thermoplastic Variant Development | Closed-loop recovery capability captures BMW and Volvo capital allocation under EU extended producer responsibility frameworks. |
| India PLI Scheme Manufacturing Deployment | Tamil Nadu and Gujarat reaction injection molding cells establish supply security outside concentrated Northeast Asian zones. |
| Metathesis Catalyst Architecture Licensing | Technology licensing fragments incumbent equipment vendor margins and enables greenfield entry without expertise scarcity constraints. |
Research Methodology
Multi-period observation of automotive OEM lightweighting procurement patterns, marine shipyard specification migrations, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with resin formulation directors, reaction injection molding plant managers, and automotive Tier 1 procurement leads. Secondary validation drew from EPA Tier 3 compliance databases, ECHA REACH Annex XIV restriction proposals, METI JIS certification registries, and ACC chemical trade flow data. Bottom-up volume estimates from grade-level production capacity triangulated against top-down demand aggregation across end-use segments.
Input-output matrix modeling connected dicyclopentadiene feedstock availability, catalyst cost structures, and reaction injection molding equipment utilization to volume and value outputs across the analysis window. Segmentation dimensions included product architecture tier, application severity grade, end-user procurement authority concentration, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity commissioning schedules. Forecast inputs incorporated automotive platform lightweighting content targets and offshore wind nacelle housing specification shifts.
Underlying measurement precision varies by segment; thermosetting grade volume estimates carry tighter precision than emerging thermoplastic variant projections due to established automotive tooling ecosystem visibility. Forecasts reflect assumptions about regulatory convergence timelines and feedstock availability continuity that dicyclopentadiene co-production economics or force majeure events could materially revise. Stakeholders should weight assumptions against their own operating context and supply security requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
North America Polyamide Market