
 American Epoxy Adhesives Market | 2026-2036
American Epoxy Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
American Epoxy Adhesives Market Outlook
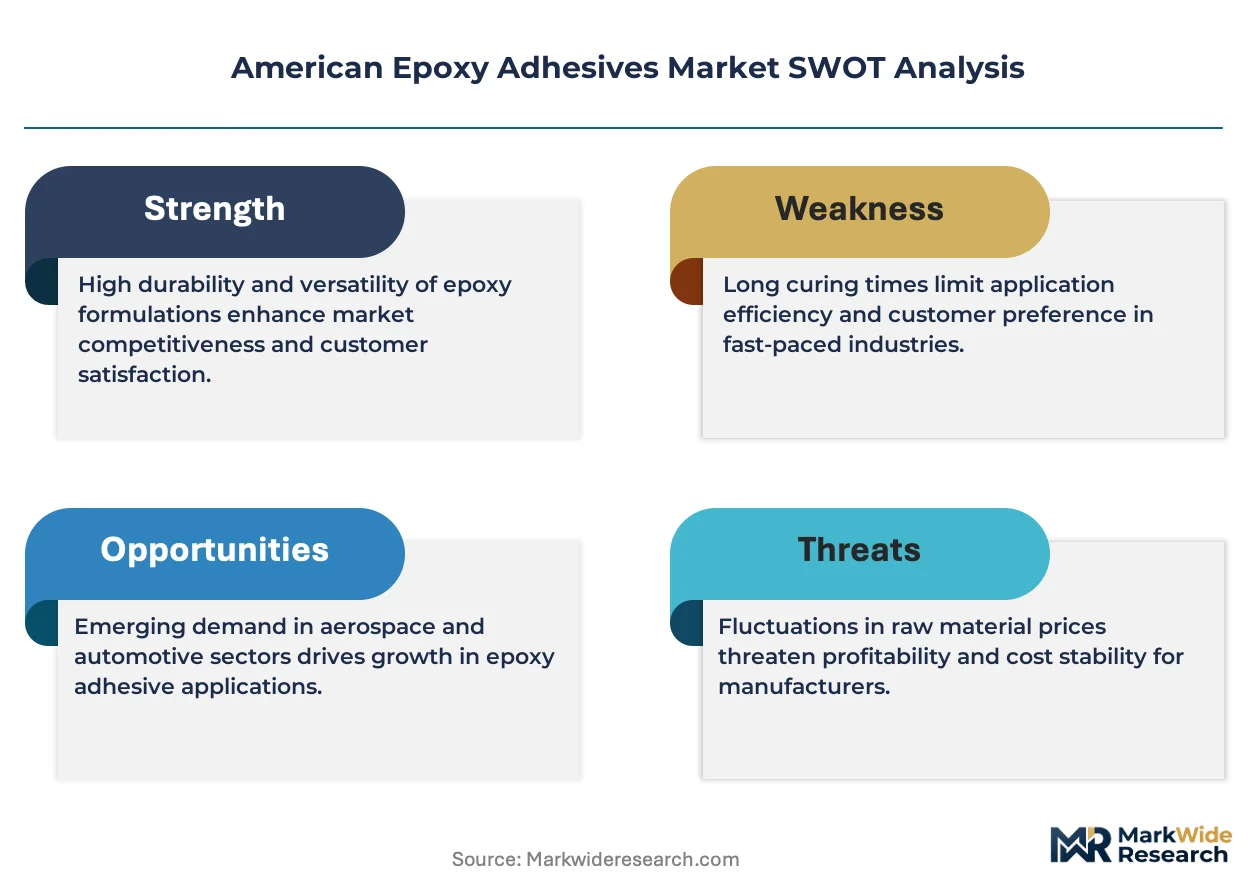
ASTM D2095 qualification for tensile strength of adhesives is unwinding the competitive landscape, favoring suppliers with certified testing infrastructure. Henkel AG & Co. KGaA leverages its North American laboratory network to maintain batch-to-batch consistency for aerospace clients. 3M sustains technology leadership in electrically conductive epoxy formulations for semiconductor packaging. Dow anchors its position through backward integration into specialty epoxy resin production, securing feedstock access across the Gulf Coast.
American epoxy adhesives are thermosetting polymers formed from epichlorohydrin and bisphenol-A condensation, cured with amine or anhydride hardeners to achieve lap-shear strengths exceeding 2,000 psi in structural assemblies. The liquid form dominates volume shipment due to ease of automated dispensing in automotive body shops and electronics assembly lines. Structural bonding commands premium pricing in aerospace airframe applications where metal-to-composite joints must withstand cyclic loading, while flexible formulations are gaining ground in automotive crash structures requiring energy absorption.
EPA VOC regulations and OSHA permissible exposure limits for amine hardeners are tightening formulation requirements, pushing manufacturers toward low-HAP curing agents and closed-loop application systems. FAA certification standards for structural adhesives in commercial aircraft repair create barrier-to-entry conditions for suppliers without Nadcap-accredited testing facilities. Stakeholders must monitor how California's Safer Consumer Products regulations and pending updates to LEED v5 material transparency credits reshape specification criteria across construction and transportation end uses.
Market Dynamics
EPA VOC emission standards under the Clean Air Act are forcing reformulation across solvent-based curing systems, compressing margins for suppliers without low-HAP alternatives while advantaging Texas and California manufacturers with captive specialty resin production.
Growth Catalysts
- Aerospace lightweighting mandates:FAA certification requirements for structural bonding in composite airframes are pulling high-performance epoxy procurement from Texas-based defense contractors and California commercial aviation clusters.
- LEED v5 material transparency credits:Pending updates to the green building certification framework are accelerating specification of low-emission adhesives in commercial construction across Florida and New York.
- Electric vehicle battery module assembly:Thermal management requirements for lithium-ion pack bonding are driving amine-cured epoxy volume through Michigan and Ohio automotive supplier networks.
Market Restraints
- Epichlorohydrin feedstock concentration:Gulf Coast petrochemical complex disruptions expose formulators to input cost volatility and force majeure risk from integrated resin producers.
- Amine hardener OSHA exposure limits:Permissible exposure ceiling reductions are forcing capital expenditure on closed-loop dispensing systems and automated mixing equipment.
- Polyurethane structural adhesive substitution:Flexible formulations for automotive crash structures are capturing energy-absorption applications previously epoxy-dominated.
Strategic Opportunities
- Offshore wind blade manufacturing:Massachusetts and Rhode Island port infrastructure investments are creating demand for vacuum-infusion compatible low-viscosity systems in 50-meter-plus rotor bonding.
- 5G infrastructure thermal interface materials:Electrically conductive formulations for base station heat dissipation represent unpenetrated volume in Arizona and Texas telecom equipment fabrication.
- California Safer Consumer Products regulations:The state's chemical prioritization framework is creating first-mover advantage for suppliers with pre-registered bisphenol-F alternatives.
Industry Challenges
- Nadcap-accredited testing facility scarcity:FAA structural adhesive qualification requires specialized environmental conditioning and fatigue testing infrastructure concentrated at fewer than twelve North American sites.
- Legacy two-part mixing system integration:Automated dispensing retrofit in established automotive body shops faces downtime constraints and technician retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | American Epoxy Adhesives Market |
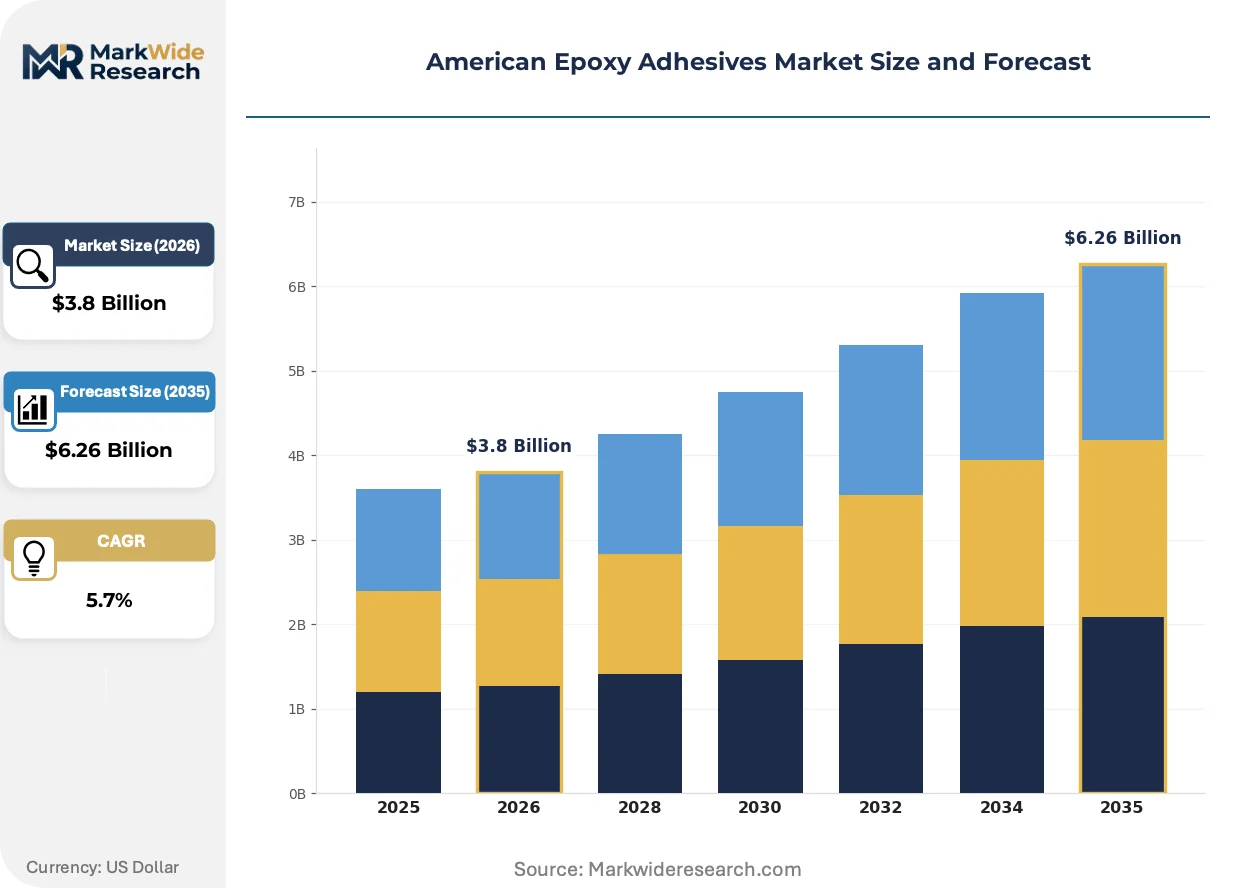
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Automotive, Electronics, Construction Form: Liquid, Paste, Solid, Powder End User: Manufacturers, Contractors, Retailers, Distributors Bonding Type: Structural, Non-structural, Flexible, Rigid |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Sika AG, Dow, Huntsman International LLC, H.B. Fuller Company, Ashland, Arkema Group, Permabond LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
American Epoxy Adhesives Market Strategic Shifts
Formulation chemistry and application automation are converging to compress curing cycles while expanding service temperature windows. Three developments are restructuring competitive positioning.
Bio-based epichlorohydrin derived from glycerol feedstock is decomposing the petroleum-origin raw material lock-in that has defined supply contracts for four decades. Wisconsin and Minnesota agricultural processors are scaling epoxidized soybean oil intermediates for Minnesota-based adhesive compounders serving furniture and panel manufacturing. This feedstock diversification is enabling price hedging against naphtha-cracker volatility while compressing carbon intensity disclosure advantages for LEED-specified projects.
EPA's 2024 National Emission Standards for Hazardous Air Pollutants (NESHAP) amendments are tightening volatile organic compound capture requirements for adhesive manufacturing facilities above 25,000 pounds annual throughput. Industrial consequence includes mandatory thermal oxidizer installation or aqueous-curing system conversion for mid-volume formulators without grandfathered permits. Southern California air quality management districts are enforcing accelerated compliance timelines, pushing regional production toward Nevada and Arizona transfer facilities.
Specification authority is migrating from plant-level purchasing to corporate sustainability offices with Science Based Targets initiative commitments. Tier-one automotive suppliers in Michigan and Ohio now require Environmental Product Declarations and Health Product Declarations as standard bid documentation, displacing historical price-per-gallon evaluation. This credential-driven selection is most visible in commercial construction where general contractors face owner-mandated embodied carbon accounting.
American Epoxy Adhesives Market Segmentation
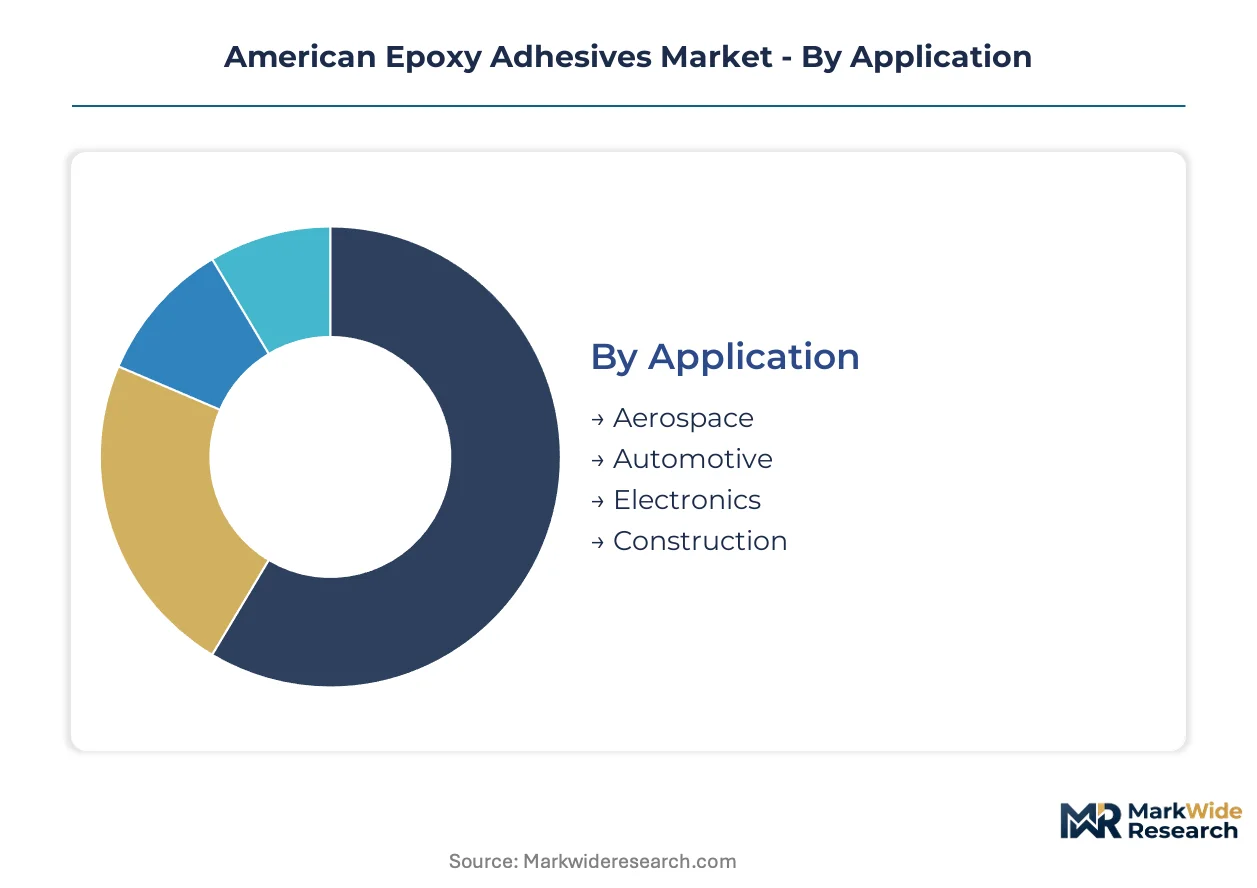
Epoxy adhesive procurement patterns diverge sharply across application contexts, with aerospace and automotive buyers demanding certified batch consistency while construction and electronics segments prioritize volume throughput and automated dispensing compatibility. Formulation chemistry and curing specifications fragment further by end-user procurement authority, creating distinct competitive arenas for specification-driven versus price-sensitive segments.
Application:
Domestic demand concentrates in Texas and California manufacturing clusters, while export-oriented aerospace procurement flows through defense contractors with Nadcap-accredited supply chains.
- Aerospace:FAA-certified structural formulations for composite airframe bonding command premium positioning, with procurement anchored at Texas defense contractors and California commercial aviation facilities facing lightweighting mandates. Cyclic loading specifications and fatigue resistance requirements create barrier-to-entry conditions for suppliers without environmental conditioning infrastructure.
- Automotive:Michigan and Ohio supplier networks drive volume for battery module thermal management and crash-structure energy absorption, with amine-cured systems displacing mechanical fasteners in electric vehicle platforms. Flexible formulations are gaining ground as polyurethane substitutes in frontal impact applications.
- Electronics:Semiconductor packaging and printed circuit board assembly in Arizona and Texas facilities specify electrically conductive formulations with precise viscosity control for automated dispensing.
- Construction:Commercial building applications in Florida and New York respond to LEED v5 material transparency credits, with low-emission curing systems specified for high-occupancy structures.
Aerospace holds the largest share; momentum sits with automotive as electric vehicle production scales.
Form:
Cost tiering separates automated dispensing-compatible liquids from manual-application pastes and specialty solid formulations.
- Liquid:Dominates volume shipment through automated dispensing systems in automotive body shops and electronics assembly lines, with low-viscosity variants specified for vacuum-infusion processes in offshore wind blade manufacturing at Massachusetts and Rhode Island port facilities.
- Paste:Thixotropic formulations enable vertical application in construction and repair contexts where sag resistance determines specification, with gap-filling grades specified for marine and industrial maintenance.
- Solid:Film adhesives and preforms serve aerospace pre-preg consolidation and specialty lamination where precise resin content control outweighs processing speed considerations.
- Powder:Emerging formulations for powder coating integration and specialty composite manufacturing, with limited current penetration outside experimental aerospace applications.
Liquid commands volume leadership; powder formulations are climbing the fastest as processing technology matures.
End User:
Customer type determines specification authority, with corporate sustainability offices displacing plant-level purchasing in tier-one automotive and construction procurement.
- Manufacturers:OEM direct procurement in aerospace and automotive segments demands Environmental Product Declarations and Health Product Declarations as standard bid documentation, with batch-to-batch consistency requirements enforced through supplier quality agreements.
- Contractors:Commercial construction general contractors face owner-mandated embodied carbon accounting, with specification migrating to low-emission and bio-based alternatives for LEED-credited projects.
- Retailers:Consumer and light industrial segments through hardware and specialty distribution, with limited specification complexity and price-per-unit sensitivity.
- Distributors:Technical distribution serves mid-volume formulators and job shops with mixed product portfolios, consolidating logistics for multi-manufacturer procurement.
Manufacturers hold the largest share; specification authority is concentrating fastest with corporate sustainability offices.
Bonding Type:
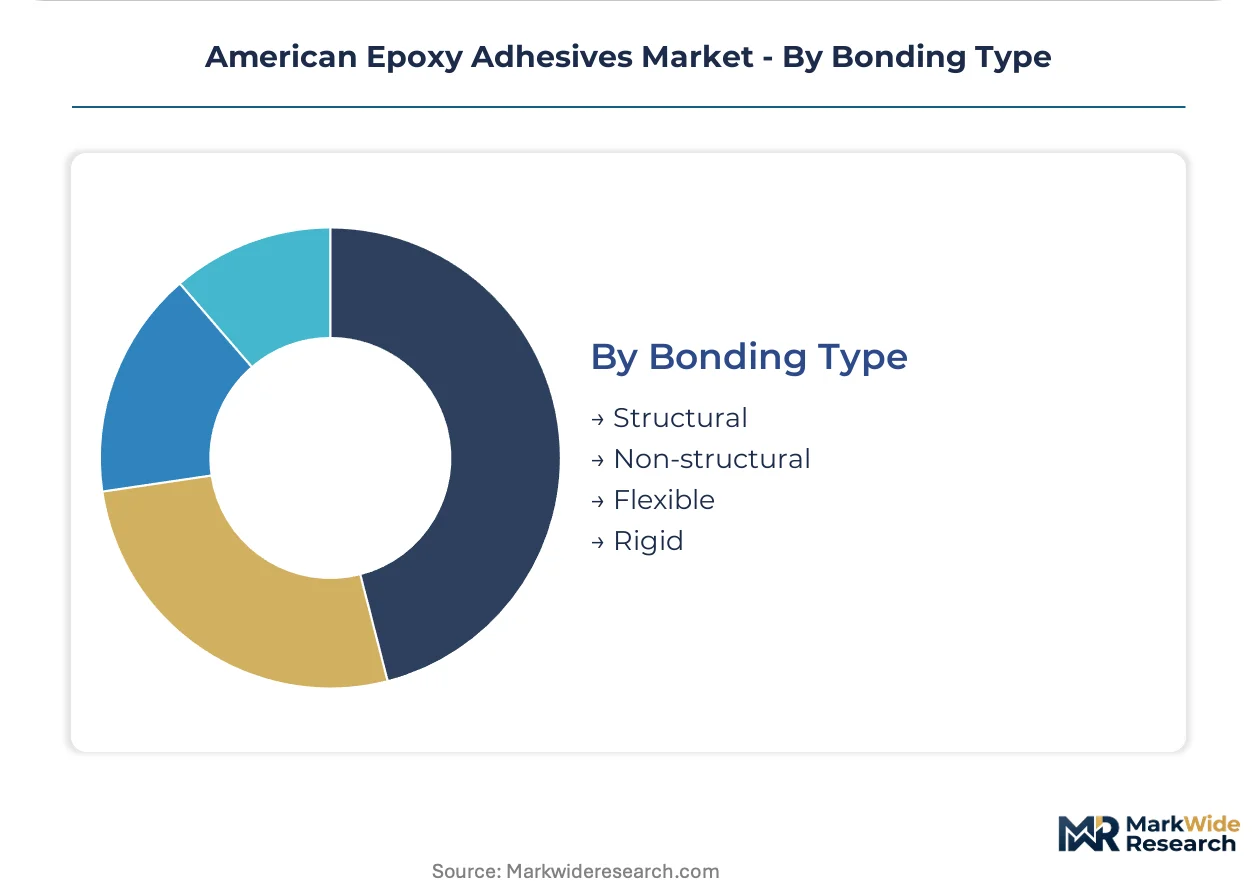
Performance tiering separates structural aerospace grades from flexible automotive formulations and general-purpose non-structural applications.
- Structural:Lap-shear strengths exceeding 2,000 psi qualify for primary load-bearing aerospace and automotive assemblies, with FAA certification creating concentrated supply relationships with Nadcap-accredited testing facilities.
- Non-structural:General assembly, potting, and sealing applications in electronics and consumer goods where mechanical fastening provides primary load path.
- Flexible:Modified formulations with enhanced elongation for automotive crash structures and vibration-damping applications, capturing energy-absorption segments from polyurethane competitors.
- Rigid:High-modulus systems for tooling, jigs, and dimensional stability applications in composite manufacturing and precision assembly.
Structural holds the largest share; flexible formulations are gaining share fastest as automotive lightweighting intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate in defense contractors, commercial aviation manufacturers, and tier-one automotive suppliers clustered along the Gulf Coast and Pacific seaboard. These procurement networks anchor volume flows while EPA and OSHA regulatory enforcement shapes formulation requirements state-by-state.
Texas
Defense contractors in the Dallas-Fort Worth corridor drive FAA-certified structural epoxy procurement for composite airframe bonding. EPA Region 6 enforcement of Clean Air Act VOC standards pressures formulators toward low-HAP curing systems. The Houston petrochemical complex supplies captive specialty resin feedstock to integrated adhesive producers along the Gulf Coast.
California
Commercial aviation manufacturers in Los Angeles and San Diego counties pull high-performance formulations for lightweighting mandates. South Coast Air Quality Management District rules accelerate compliance timelines beyond federal NESHAP baselines. Sacramento's Safer Consumer Products regulations prioritize bisphenol-A alternatives, creating specification advantage for pre-registered compounders.
Michigan
Tier-one automotive suppliers in Detroit and Flint specify amine-cured epoxies for electric vehicle battery module thermal management. OSHA Michigan consultation programs enforce permissible exposure limit reductions for hardener handling. Ann Arbor-area engineering centers validate automated dispensing system integration for body shop retrofit programs.
Ohio
Crash-structure fabricators in Toledo and Cleveland adopt flexible epoxy formulations for energy-absorption applications. The state's environmental protection agency aligns VOC permitting with federal standards while offering technical assistance for aqueous-curing conversions. Cincinnati-based distribution hubs consolidate logistics for Midwest automotive supplier networks.
Massachusetts
Offshore wind blade manufacturers at New Bedford and Fall River port facilities specify vacuum-infusion compatible low-viscosity systems. Massachusetts Department of Environmental Protection permitting supports marine coating and adhesive production with streamlined air quality review. Boston-area composite engineering firms validate 50-meter-plus rotor bonding processes for Atlantic Coast wind farm deployments.
American Epoxy Adhesives Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive resin production and specialized adhesive compounders with Nadcap-accredited testing infrastructure. The vendor base separates into three strategic archetypes: Gulf Coast petrochemical majors with backward integration into epichlorohydrin feedstock, European-headquartered multinationals with North American laboratory networks, and domestic mid-volume formulators serving regional automotive clusters. Dominant competitive moves include capacity expansion at Texas and Louisiana resin complexes and strategic partnerships between compounders and automated dispensing equipment manufacturers.
Within the integrated chemical tier, Dow anchors feedstock security across Gulf Coast operations while Henkel AG & Co. KGaA exemplifies the laboratory-network archetype for aerospace batch consistency. Among specialized compounders, Permabond LLC occupies a position serving mid-volume formulators with mixed product portfolios. These three represent distinct competitive positions: captive supply control, certification infrastructure depth, and technical distribution flexibility respectively.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Sika AG |
| Dow |
| Huntsman International LLC |
| H.B. Fuller Company |
| Ashland |
| Arkema Group |
| Permabond LLC |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day epichlorohydrin order lead times from Gulf Coast petrochemical complexes concentrate pricing power among integrated resin producers while squeezing compounders without captive feedstock access. This inventory compression dynamic amplifies margin volatility for mid-volume formulators facing EPA NESHAP compliance capital requirements.
Pricing Analysis
Cost-plus contracts indexed to propylene and benzene spot benchmarks dominate raw material pass-through structures. Three-tier pricing stratifies across FAA-certified aerospace grades, automotive qualified formulations, and general industrial tiers. Cost compression in mid-volume construction segments intensifies as aqueous-curing system conversions absorb capital budgets. Retail distributors exhibit highest price sensitivity; defense contractors with Nadcap-accredited supply chains demonstrate lowest.
Supply Chain Analysis
Houston Ship Channel transit capacity underwrites domestic epichlorohydrin availability, with disruptions cascading through Texas and Louisiana resin complexes. Feedstock draws from integrated Gulf Coast petrochemical producers, specialty amine hardener manufacturers, and bio-based glycerol processors in Minnesota. Single-source vulnerability concentrates in epichlorohydrin supply from integrated producers. Distribution runs through technical distributors consolidating multi-manufacturer portfolios for Midwest automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority migration toward corporate sustainability offices creates platform-economics inflection as Environmental Product Declaration interoperability becomes table stakes for tier-one procurement. This credential standardization rewards compounders with pre-registered disclosure frameworks.
For Market Incumbents: Consolidate Nadcap-accredited testing infrastructure through strategic facility acquisitions in Texas and California defense corridors. Deepen backward integration into specialty amine hardener production to hedge OSHA exposure limit compliance costs. Prioritize automated dispensing system partnerships to lock in automotive body shop retrofit cycles before polyurethane substitution accelerates. For New Entrants and Emerging Players: Automated dispensing technical service gaps in legacy two-part mixing system integration present white-space entry points. Target Ohio and Michigan mid-volume automotive suppliers with retrofit-focused application engineering. Lead with closed-loop dispensing system bundling to differentiate from established compounders. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification credential scarcity concentrates among fewer than twelve North American Nadcap-accredited facilities. Target compounders with pre-registered bisphenol-F alternatives under California Safer Consumer Products regulations. Watch for FAA certification backlog clearance rates as inflection indicator for aerospace procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive epichlorohydrin access insulates margin from Gulf Coast feedstock volatility. |
| Nadcap Accreditation Investment | FAA structural adhesive qualification creates barrier-to-entry defense in aerospace procurement. |
| Automated Dispensing Partnership | Closed-loop system bundling locks in automotive retrofit cycles ahead of polyurethane substitution. |
| Bio-Based Feedstock Transition | Epoxidized soybean oil intermediates enable carbon intensity disclosure advantages for LEED-specified projects. |
| Aqueous-Curing System Conversion | EPA NESHAP compliance preserves operating permits in South Coast Air Quality Management District enforcement zones. |
Study Parameters
Initial hypotheses were tested against primary input from adhesive compounder plant managers, aerospace procurement leads at defense contractors, automotive Tier 1 supplier quality directors, and technical distribution channel partners and refined through secondary validation against EPA NESHAP regulatory filings, American Chemistry Council trade data, SEC 10-K disclosures from integrated chemical producers, and customs import records. Bottom-up volume estimates from end-use application modeling were triangulated against top-down market sizing from feedstock consumption analysis.
Variance decomposition across application segments, formulation chemistry tiers, end-user procurement authority levels, and regional regulatory clusters structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation with cross-validation against macroeconomic drivers. Electric vehicle production scaling assumptions and offshore wind blade manufacturing capacity buildouts served as automotive and construction segment forecast anchors.
Material uncertainties — Gulf Coast petrochemical disruption frequency, California Safer Consumer Products regulatory expansion timelines, FAA certification backlog clearance rates — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EPA Region 6 enforcement intensity and LEED v5 adoption velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market