
 Malaysia Lubricants Market | 2026-2036
Malaysia Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Lubricants Market Foresight
Malaysia's B5 biodiesel mandate is recalibrating the cost-of-entry calculus for lubricant blenders, forcing reformulation investments that favor well-capitalized participants. PETRONAS Lubricants International anchors its position through captive feedstock access and nationwide distribution infrastructure. Shell leverages its synthetic-grade portfolio to capture premium segments in the Klang Valley automotive corridor. FUCHS specializes in industrial oil formulations tailored to Malaysia's palm oil processing and electronics manufacturing sectors.
Malaysia lubricants are formulated hydrocarbon-based fluids engineered with viscosity grades ranging from ISO VG 32 to VG 100 and additive packages containing detergents, dispersants, and anti-wear compounds such as zinc dialkyldithiophosphate, designed to reduce friction, dissipate heat, and prevent corrosion in engines and industrial machinery. Engine Oil dominates volume flows through the automotive aftermarket channel, where service intervals and OEM specifications drive repeat purchases. Synthetic-grade lubricants represent the fastest-growing grade category as manufacturing plants and automotive OEMs prioritize extended drain intervals and thermal stability under tropical operating conditions. Marine lubricants serve a mature but stable niche linked to Port Klang and Tanjung Pelepas shipping traffic.
The Department of Environment Malaysia enforces waste oil disposal regulations under the Environmental Quality Act, while SIRIM Berhad administers product certification and labeling standards that shape market access for imported formulations. BIS-equivalent alignment and ASEAN harmonization pressures are tightening compliance requirements for both domestic blenders and multinational suppliers. Stakeholders must monitor enforcement intensity around extended producer responsibility frameworks and decide whether to invest in local blending capacity or rely on regional import hubs.
Market Dynamics
Malaysia's Euro 5 emission standards are compressing formulation flexibility for lubricant blenders, forcing additive package redesigns and base oil upgrades that favor technical specialists over commodity traders.
Growth Catalysts
- Automotive Aftermarket Channel:Rising vehicle ownership across Peninsular Malaysia extends service intervals and drives repeat lubricant purchases through authorized workshops and independent service stations.
- Euro 5 Standards:The Department of Environment Malaysia mandates cleaner-burning formulations, pushing blenders toward Group II/III base stocks and advanced detergent chemistry.
- Klang Valley Manufacturing Cluster:Concentrated industrial activity around Port Klang and Shah Alam generates sustained demand for hydraulic fluids and metalworking lubricants.
Market Restraints
- Base Oil Import Dependency:Malaysia lacks domestic Group II/III refining capacity, exposing blenders to Singapore and South Korea supply volatility and freight cost swings.
- B5 Biodiesel Mandate:Palm oil methyl ester compatibility requirements add formulation complexity and filter-clogging risks that increase warranty claim exposure.
- SIRIM Certification Timelines:Product registration and labeling compliance stretches 4-6 months, delaying new formulation launches against faster ASEAN import competitors.
Strategic Opportunities
- East Malaysia Penetration:Sabah and Sarawak remain underserved by national distribution networks, creating first-mover advantages for localized blending investments.
- Synthetic-Grade Conversion:OEM service fill specifications and tropical heat degradation concerns accelerate demand for PAO and ester-based formulations in commercial fleets.
- Extended Producer Responsibility:Anticipated waste oil collection mandates under Environmental Quality Act amendments position reverse-logistics operators for regulatory capture.
Industry Challenges
- Formulation Chemist Scarcity:Malaysian universities produce limited lubricant science graduates, forcing blenders to recruit from Singapore or India at premium compensation.
- Legacy Equipment Retrofit Costs:Existing blending plants require tank cleaning and piping upgrades to handle synthetic base oils, straining mid-capitalization participants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Lubricants Market |
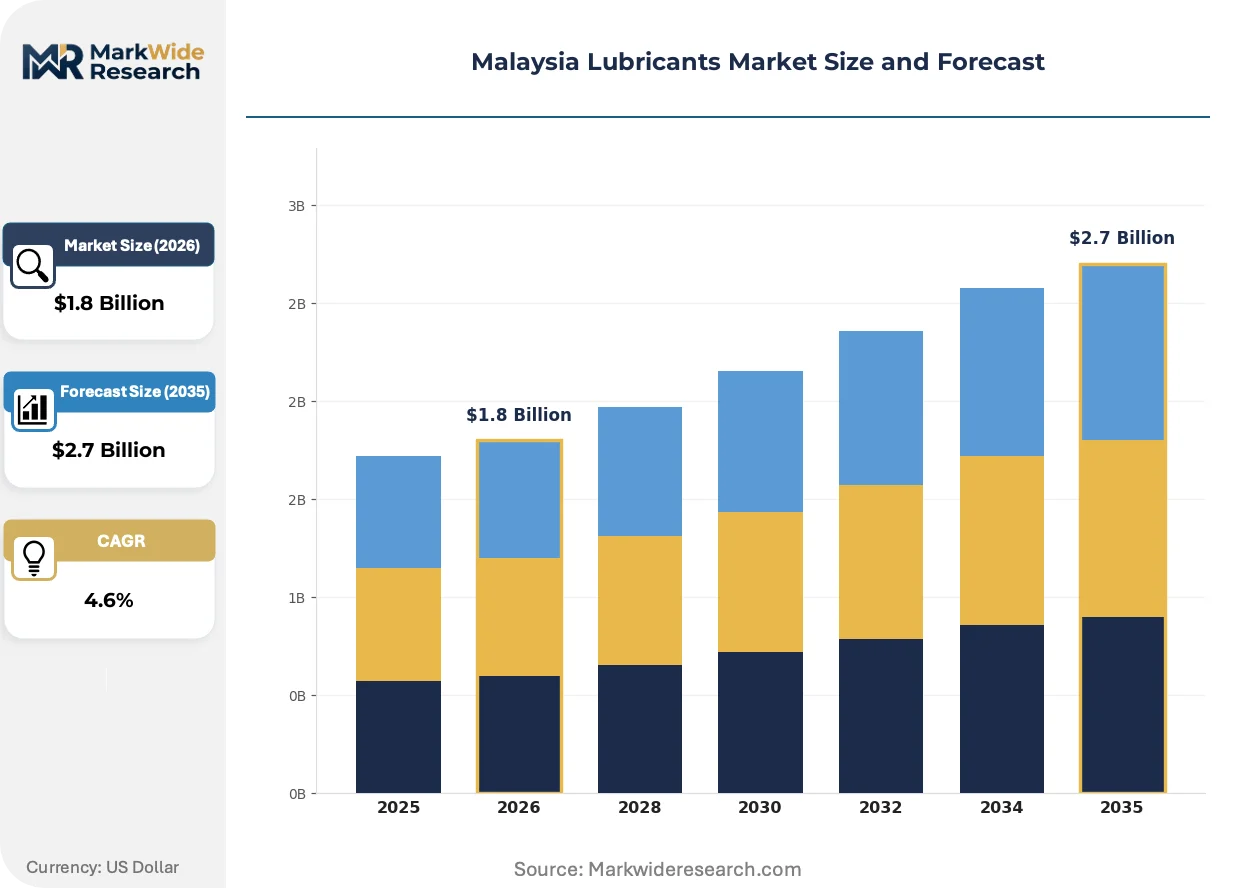
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Industrial Oil, Marine Lubricants, Transmission Fluids Application: Automotive, Machinery, Power Generation, Marine End User: Automotive OEMs, Aftermarket Providers, Manufacturing Plants, Transportation Grade: Synthetic, Mineral, Semi-Synthetic, Others |
| Companies Covered | BP (Castrol), TotalEnergies, PETRONAS Lubricants International, Idemitsu Kosan, FUCHS, Shell, Chevron Corporation, Petron Corporation, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Lubricants Market Shifts & Advancements
Reformulation pressures and distribution digitization are reshaping how lubricants reach Malaysian end-users, with technology and policy acting as dual levers of competitive differentiation.
Group III and synthetic base stocks are decentralizing the technical advantage previously held by multinational suppliers with captive Singapore refining. Domestic blenders in Selangor and Johor are adopting these higher-performance inputs to meet Euro 5 and OEM fill specifications. This shift compresses the quality gap between regional independents and global majors, enabling local players to bid on fleet maintenance contracts previously closed to them.
Malaysia's Environmental Quality Act amendments are tightening waste oil disposal and extended producer responsibility frameworks. The Department of Environment Malaysia now requires documented chain-of-custody for used lubricant collection, increasing compliance overhead for smaller distributors. Industrial accounts in the Klang Valley are responding by consolidating procurement toward blenders with certified reverse-logistics capabilities.
Fleet operators and manufacturing plants are unbundling lubricant supply from full-service maintenance contracts, preferring direct material sourcing with separate technical advisory. This pattern disrupts the traditional integrated service model dominant in Malaysian commercial vehicle channels. The disaggregation is most visible in Peninsular Malaysia's logistics corridors, where large transport companies negotiate base oil-plus-additive packages separately from drain interval monitoring services.
Malaysia Lubricants Market Segmentation
Malaysia's lubricants market fragments along technical specification lines, with base oil chemistry and OEM certification requirements determining margin capture and customer stickiness. Each segmentation axis reveals distinct competitive dynamics between multinational suppliers with captive refining and domestic blenders leveraging import flexibility.
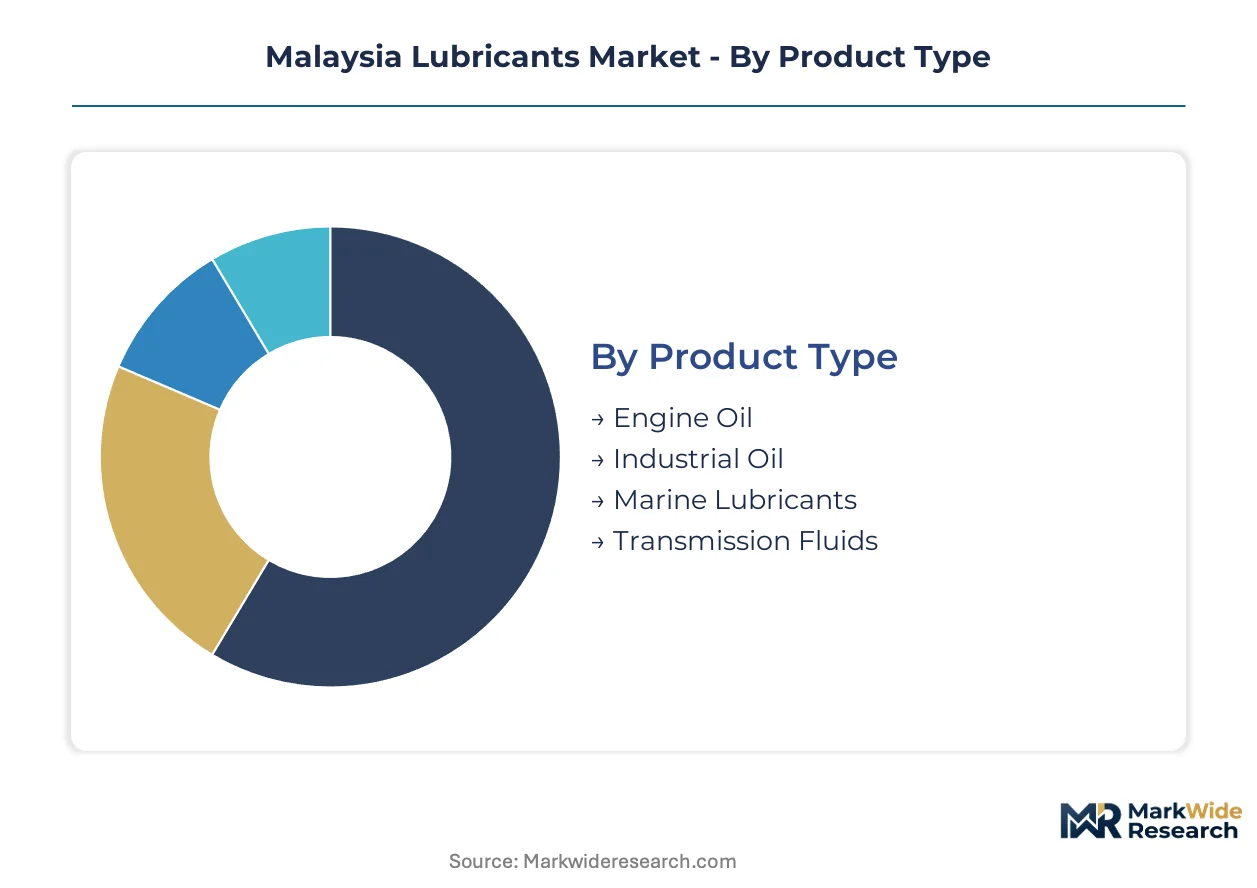
Product Type:
Base oil viscosity grades and additive package complexity separate commodity formulations from premium technical products in Malaysian distribution channels.
- Engine Oil:Formulated with Group II/III base stocks and detergent-dispersant additive packages meeting API SP and ILSAC GF-6 specifications. Demand concentrates in the Klang Valley automotive corridor where independent workshops and authorized dealers service rising vehicle ownership with OEM-mandated drain intervals.
- Industrial Oil:Hydraulic fluids, compressor oils, and metalworking lubricants formulated for tropical operating conditions with oxidation inhibitors and anti-wear compounds. Manufacturing plants in Shah Alam and Port Klang industrial zones specify ISO VG 32-68 grades for continuous process equipment, driving volume through direct procurement contracts.
- Marine Lubricants:High-BN cylinder oils and system lubricants for two-stroke diesel engines operating on residual fuel. Port Klang and Tanjung Pelepas shipping traffic sustains demand through bunker supply chains and vessel agency networks.
- Transmission Fluids:ATF and gear oil formulations with friction modifiers and shear-stable viscosity index improvers. Commercial fleet operators in Peninsular Malaysia specify OEM-fill grades for extended warranty compliance.
Engine Oil leads on scale; Industrial Oil leads on momentum.
Application:
Operating environment severity and equipment criticality determine formulation investment and service interval economics across Malaysian end-use sectors.
- Automotive:Passenger cars, commercial vehicles, and motorcycles requiring crankcase lubricants, gear oils, and greases. Service stations across Peninsular Malaysia generate repeat purchase cycles through OEM-specified maintenance schedules.
- Machinery:Construction equipment, agricultural implements, and factory automation systems demanding hydraulic fluids and way lubricants. Selangor and Johor manufacturing clusters specify premium grades to minimize unplanned downtime.
- Power Generation:Gas turbine, diesel engine, and combined-cycle plants requiring thermal stability and oxidation resistance. Independent power producers and utility-scale operators in the Klang Valley prioritize long-drain formulations.
- Marine:Deep-sea vessels, coastal shipping, and offshore support operations with IMO-compliant lubricant specifications. Malaysian-flagged fleets and international liners calling at Port Klang drive demand for high-performance cylinder and system oils.
Automotive dominates volume throughput; Machinery is gaining share fastest on industrial expansion.
End User:
Procurement sophistication and technical specification authority separate price-sensitive spot buyers from contract-locked strategic accounts.
- Automotive OEMs:Proton, Perodua, and multinational assemblers specifying factory-fill and service-fill lubricants for warranty compliance. captive supply agreements and technical collaboration requirements favor suppliers with local blending infrastructure.
- Aftermarket Providers:Independent workshops, quick-lube chains, and parts retailers serving vehicle owners outside dealer networks. Price competition intensifies in this channel as domestic blenders gain SIRIM certification for synthetic-grade alternatives.
- Manufacturing Plants:Palm oil processing, electronics assembly, and general industrial operations with bulk fluid management programs. Extended producer responsibility requirements under Environmental Quality Act amendments are consolidating procurement toward certified reverse-logistics operators.
- Transportation:Fleet operators, logistics companies, and public transit authorities managing total cost of ownership through lubricant selection. Commercial vehicle fleets in Peninsular Malaysia are unbundling supply from maintenance contracts to negotiate direct material sourcing.
Aftermarket Providers lead on transaction frequency; Manufacturing Plants lead on contract value.
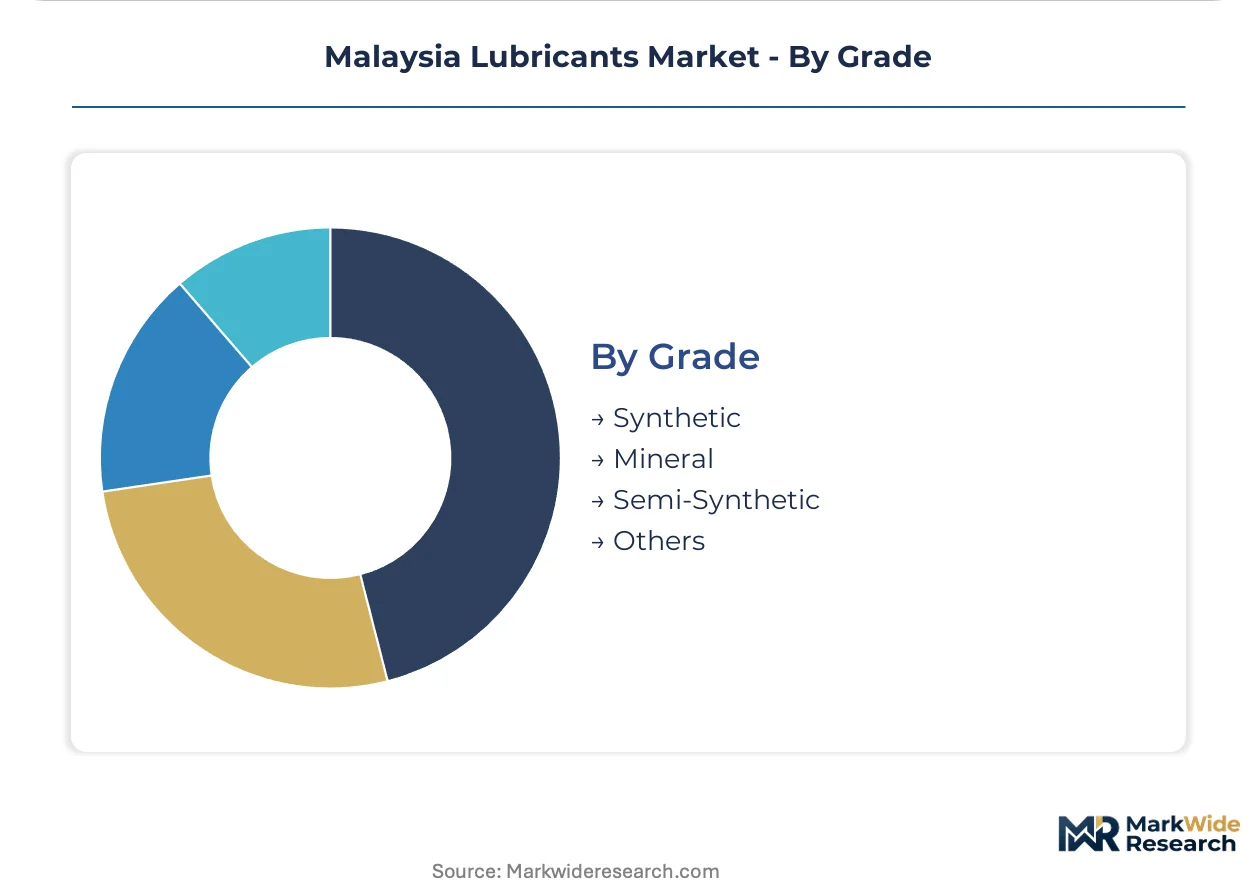
Grade:
Base oil group classification determines thermal performance, oxidation stability, and drain interval extension in tropical Malaysian operating conditions.
- Synthetic:PAO, ester, and Group III+ formulations engineered for extreme temperature stability and extended service intervals. OEM service fill specifications and tropical heat degradation concerns accelerate demand from commercial fleets and manufacturing plants prioritizing equipment uptime.
- Mineral:Group I base stocks refined from crude oil with conventional additive packages meeting legacy equipment specifications. Price-sensitive applications and older vehicle populations sustain volume in rural Peninsular Malaysia and East Malaysia.
- Semi-Synthetic:Blended formulations combining Group I/II base stocks with synthetic components for mid-tier performance positioning. Independent workshops use these products to bridge customer upgrade paths from mineral to full synthetic.
- Others:Bio-based lubricants, re-refined base stocks, and specialty formulations including food-grade and NSF-registered products. Niche applications in food processing and environmentally sensitive operations drive limited but stable demand.
Mineral leads on volume penetration; Synthetic shows the steepest expansion trajectory on OEM specification convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's lubricant formulation talent concentrates in the Klang Valley industrial corridor, where PETRONAS and multinational blenders operate technical centers. This workforce density shapes regional demand patterns and regulatory compliance capabilities across Peninsular and East Malaysia.
Selangor
Automotive service stations and manufacturing plants drive lubricant consumption across Shah Alam and Port Klang industrial zones. The Department of Environment Malaysia enforces waste oil disposal documentation under Environmental Quality Act amendments. Blending facilities cluster in Shah Alam to supply hydraulic fluids and metalworking lubricants to electronics assembly and palm oil processing operations.
Kuala Lumpur
Commercial fleet operators and quick-lube chains generate high-frequency transactions through the capital's dense vehicle population. SIRIM Berhad administers product certification and labeling standards that shape market access for imported formulations. Authorized workshops in the Klang Valley automotive corridor specify OEM-mandated synthetic-grade engine oils for warranty compliance.
Johor
Logistics hubs and cross-border trade with Singapore sustain demand for heavy-duty diesel engine oils and transmission fluids. The B5 biodiesel mandate requires palm oil methyl ester compatibility testing for all new formulations. Industrial parks around Pasir Gudang host manufacturing plants specifying ISO VG 32-68 hydraulic grades for continuous process equipment.
Sabah
Palm oil estates and coastal shipping operations create specialized demand for marine lubricants and agricultural machinery fluids. Extended producer responsibility frameworks under anticipated Environmental Quality Act amendments will mandate documented used oil collection chains. Kota Kinabalu serves as the distribution node for East Malaysia penetration strategies, though national blending networks remain underdeveloped.
Sarawak
Offshore support vessels and timber processing equipment require high-BN cylinder oils and extreme-pressure gear lubricants. The state's industrial development corridors attract manufacturing investments that will expand hydraulic fluid demand. Miri and Bintulu anchor marine lubricant supply chains for oil and gas operations, with local blending capacity limited compared to Peninsular Malaysia.
Malaysia Lubricants Market Competitive Landscape
The competitive structure tilts toward national oil company dominance through captive feedstock access and infrastructure scale. PETRONAS Lubricants International leverages vertical integration into base oil supply and nationwide distribution networks. Multinational majors compete on synthetic-grade portfolios and OEM technical collaboration. Strategic moves concentrate on SIRIM certification acceleration, East Malaysia distribution expansion, and reverse-logistics capability building for extended producer responsibility compliance.
Within the state-affiliated tier, PETRONAS Lubricants International anchors domestic supply through integrated refining and blending operations. Shell and BP (Castrol) occupy positions among multinational majors competing on premium synthetic formulations and service fill specifications. FUCHS sits within the industrial specialist archetype, with TotalEnergies and Chevron representing additional global suppliers navigating SIRIM certification timelines and B5 biodiesel compatibility requirements.
| Leading Market Players |
|---|
| BP (Castrol) |
| TotalEnergies |
| PETRONAS Lubricants International |
| Idemitsu Kosan |
| FUCHS |
| Shell |
| Chevron Corporation |
| Petron Corporation |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
Fleet operator procurement unbundling is compressing margins on bundled service contracts and forcing blenders to price base oils and technical advisory as separate line items. This disaggregation rewards suppliers with standalone synthetic-grade portfolios and certified reverse-logistics capabilities while squeezing commodity traders dependent on full-service contract structures.
Pricing Analysis
The bundled-versus-unbundled service split now defines margin capture across Malaysian distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates PAO-based synthetics from Group II/III formulations and legacy Group I mineral stocks. Price differentiation hinges on SIRIM certification tier and OEM service-fill authorization. Cost compression in the mineral tier is intensifying because domestic blenders with Singapore import flexibility are undercutting established distributors. Aftermarket providers and independent workshops exhibit highest price sensitivity; automotive OEMs and certified fleet operators demonstrate lowest sensitivity due to warranty compliance requirements.
Supply Chain Analysis
Direct-to-industrial channels handle manufacturing plant demand through bulk fluid management programs, while authorized workshop networks and quick-lube chains distribute to automotive end-users. Geographic supply concentrates in Singapore, South Korea, and Thailand as sources for Group II/III base stocks and additive packages. Raw material dependencies include palm oil methyl ester for B5 biodiesel compatibility, zinc dialkyldithiophosphate anti-wear compounds, and viscosity index improvers. Single-source vulnerability around Singapore refining capacity exposes blenders to freight cost swings and regional supply disruptions. Distribution runs through PETRONAS captive infrastructure, multinational distributor networks, and emerging regional import hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's lubricants market functions as a stable compounder anchored by mandatory vehicle service intervals and industrial equipment maintenance cycles that generate predictable replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Acquire East Malaysia distribution infrastructure to preempt first-mover entrants in Sabah and Sarawak. Secure SIRIM certification acceleration capabilities to compress new formulation launch timelines against ASEAN import competitors. Invest in reverse-logistics assets ahead of Environmental Quality Act extended producer responsibility amendments. Backward integration into Singapore base oil supply contracts mitigates freight cost volatility threatening mid-tier blenders. For New Entrants and Emerging Players: Synthetic-grade formulation expertise offers entry into fleet maintenance contracts previously closed to regional independents. Target East Malaysia manufacturing corridors in Kota Kinabalu, Miri, and Bintulu where national blending networks remain underdeveloped. Pursue direct procurement relationships with palm oil processing and electronics manufacturing plants seeking to unbundle lubricant supply from integrated service contracts. Lead with PAO and ester-based products certified for tropical operating conditions and OEM extended drain specifications. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic blenders possessing SIRIM certification and synthetic-grade production capability but lacking East Malaysia distribution reach. Long-term viability over a multi-year horizon rests on regulatory capture around waste oil collection mandates and biodiesel compatibility testing requirements. Monitor enforcement intensity around Environmental Quality Act amendments as the primary inflection indicator for reverse-logistics valuation premiums. Acquisition candidates should demonstrate technical collaboration relationships with Proton, Perodua, or multinational OEM assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| East Malaysia Blending Capacity Expansion | Localized production in Sabah and Sarawak reduces freight costs and captures underserved industrial demand. |
| Synthetic-Grade Portfolio Conversion | PAO and ester formulations meet OEM specifications for extended drain intervals in tropical conditions. |
| Reverse-Logistics Capability Buildout | Certified used oil collection chains position operators for Environmental Quality Act mandate compliance. |
| SIRIM Certification Acceleration Investment | Compressed product registration timelines enable faster response to formulation specification changes. |
| Direct Industrial Procurement Relationships | Unbundled supply contracts with manufacturing plants bypass traditional integrated service intermediaries. |
Research Methodology
Multiple input streams — blending plant technical directors, procurement leads at palm oil processing and electronics manufacturing operations, aftermarket distributor channel partners, and automotive fleet maintenance managers — were reconciled against trade flow databases, Department of Environment Malaysia regulatory filings, SIRIM certification records, and base oil import customs data. Bottom-up volume estimates from end-use sector consumption patterns were cross-validated against top-down supply-side capacity assessments across Peninsular and East Malaysia.
Historical consumption trajectories were cross-referenced against panel input from industry participants to establish baseline demand patterns. The analytical framework segments by product type, application, end user, and base oil grade across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points including Euro 5 implementation and anticipated extended producer responsibility mandates. Forecast inputs incorporate vehicle ownership growth rates, manufacturing capacity expansion in the Klang Valley corridor, and biodiesel mandate compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to base oil import cost volatility, SIRIM certification processing delays, and enforcement intensity around waste oil disposal documentation. Periodic stress-testing of base assumptions against Singapore refining capacity utilization and B5 biodiesel formulation compatibility trends is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
South America Lubricants Market
Lubricants
Mexico Automotive Engine Oils Market
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Kenya Lubricants Market
Lubricants
Egypt Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Turkey Marine Lubricants Market
Lubricants
Argentina Lubricants Market