
 Linear Low Density Polyethylene Lldpe Market | 2026-2036
Linear Low Density Polyethylene Lldpe Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Low Density Polyethylene Lldpe Market Intelligence
Buyer concentration in flexible packaging is recalibrating as e-commerce fulfillment networks fragment demand across regional converters while multinational food brands consolidate supplier rosters. Dow Chemical Company leverages its gas-phase technology leadership to sustain high-volume supply agreements with North American retail chains. ExxonMobil Corporation anchors its position through backward integration into ethane feedstock, while SABIC competes on scale from its Middle Eastern cost base.
Linear low density polyethylene is a copolymer of ethylene with alpha-olefins such as butene, hexene, or octene, produced at densities between 0.915 and 0.925 g/cm³ via gas-phase or solution polymerization to deliver superior tensile strength and puncture resistance in thin-gauge films. Its primary purpose centers on flexible packaging, agricultural films, and stretch wraps where downgauging reduces material usage without sacrificing performance. Film-grade resin dominates volume demand across food packaging and plastic bag applications, while injection-molded segments occupy narrower but higher-margin niches in caps and closures. The gas-phase technology segment leads capacity additions due to lower capital intensity, though supercritical processes are gaining traction for specialty grades with narrower molecular weight distribution.
REACH registration requirements in Europe and FDA food-contact notification standards in the United States constrain additive packages and catalytic residue limits, directly shaping formulation R&D priorities and import compliance costs. China's GB standards and evolving MEE environmental enforcement on volatile organic compound emissions further condition plant licensing and product certification pathways for both domestic producers and importers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capacity investments.
Market Dynamics
Gas-phase technology maturation is compressing capital barriers for new LLDPE entrants while REACH and FDA food-contact standards simultaneously elevate purity thresholds, creating a bifurcation between commodity volume players and specialty-grade specialists.
Growth Catalysts
- E-commerce fulfillment networks:Regional distribution centers across the United States and China are multiplying demand nodes for stretch wrap and protective film applications. Downgauging specifications from major retailers are pulling higher-performance resin grades.
- REACH registration tiers:ECHA's substance evaluation protocols are accelerating substitution away from legacy LDPE in European food-contact applications. Compliance-driven reformulation is opening specification windows for hexene and octene copolymers.
- Supercritical polymerization:Narrower molecular weight distribution from advanced solution processes is enabling thinner agricultural films without puncture failure. Adoption is accelerating among greenhouse operators in Spain and the Netherlands.
Market Restraints
- Ethane feedstock volatility:North American crackers dependent on Appalachian and Permian ethane supply face margin compression during winter heating-demand spikes. Price swings transmit directly to film-grade resin quotations.
- Middle Eastern supply concentration:SABIC and regional state-linked producers control disproportionate low-cost export volumes. European and Asian buyers remain exposed to single-source disruption risk from Gulf capacity.
- Mechanical recycling contamination:Post-consumer film streams carry multi-layer laminates and adhesive residues that degrade mechanical properties. Food-contact approval barriers for recycled content limit circular feedstock adoption.
Strategic Opportunities
- Indian flexible packaging conversion:Domestic polymer processing capacity is expanding in Gujarat and Maharashtra to serve organized retail growth. Local LLDPE compounding for high-clarity food wraps remains underdeveloped relative to demand trajectory.
- Bio-based alpha-olefin integration:Renewable butene and hexene from agricultural waste streams are converging with conventional gas-phase infrastructure. Early pilot agreements between biotech developers and polymer producers are forming in Brazil and the Netherlands.
- EU Green Deal packaging mandates:The Packaging and Packaging Waste Regulation is accelerating minimum recycled content thresholds for plastic films. Producers with advanced mechanical and chemical recycling capabilities can capture premium positioning in German and French supply chains.
Industry Challenges
- Catalytic residue analytics:FDA food-contact notification requirements demand increasingly sensitive detection of titanium and chromium traces below 10 parts per million. Laboratory certification timelines for new catalyst systems now extend 18-24 months.
- Multi-site quality harmonization:Brand owners consolidating supplier rosters require identical melt index and dart impact specifications across geographically dispersed production. Variance in gas-phase reactor control between facilities creates batch rejection risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Low Density Polyethylene Lldpe Market |
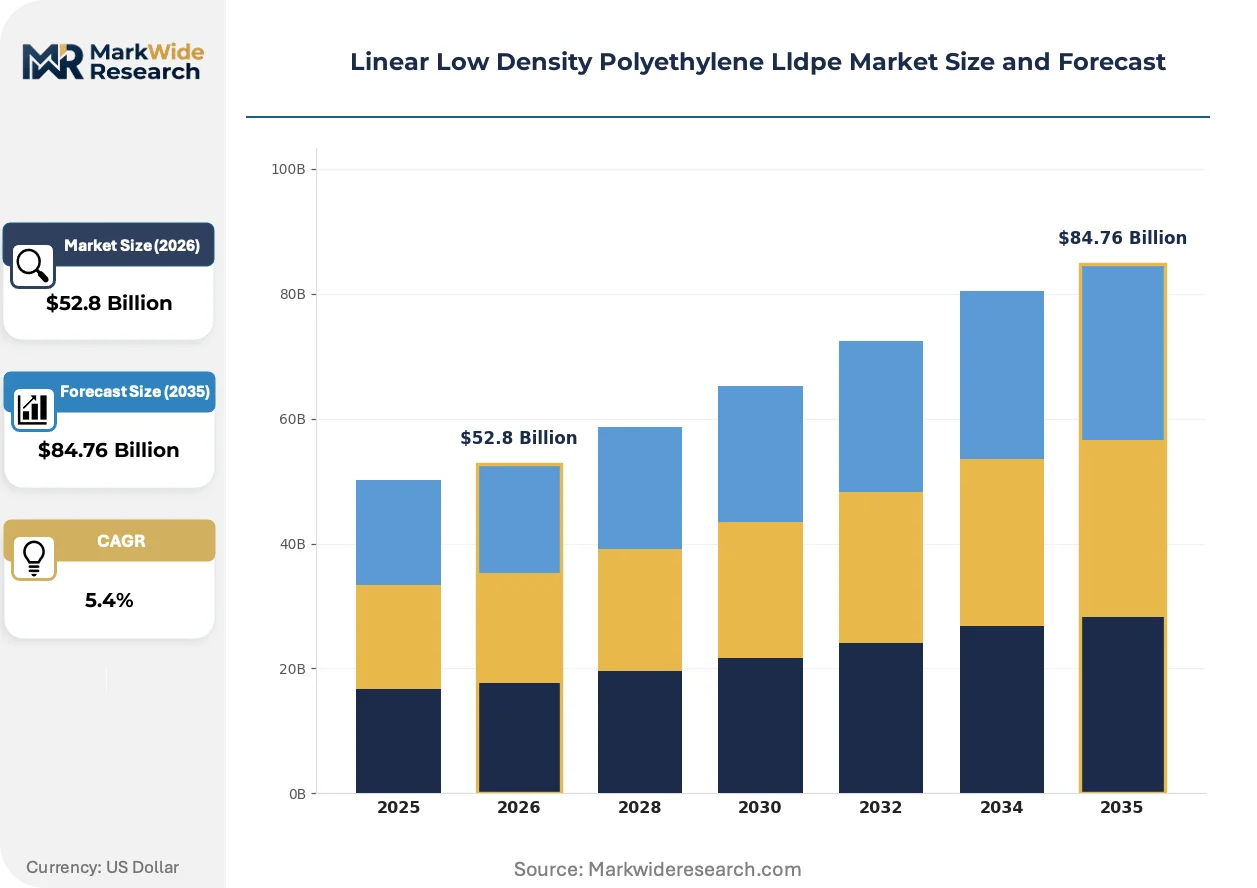
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
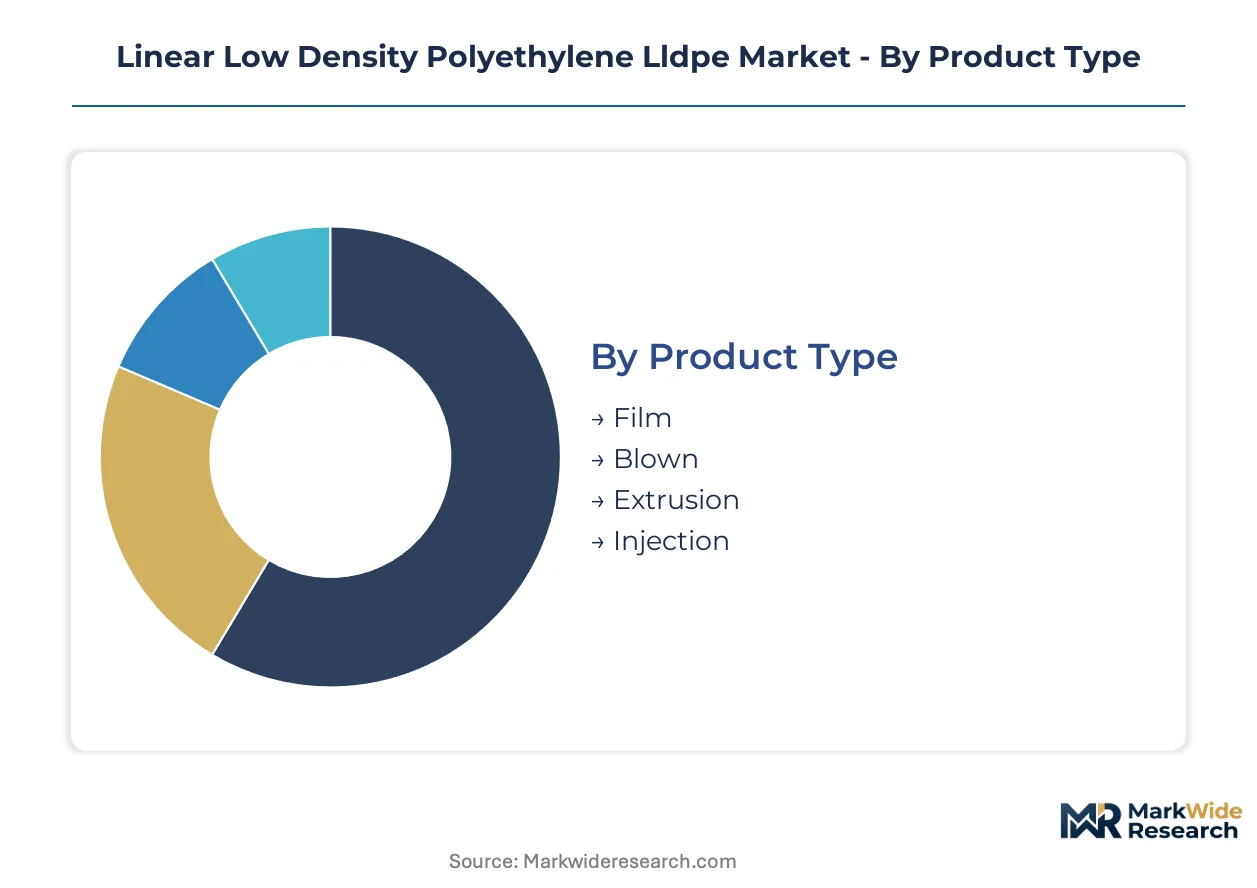
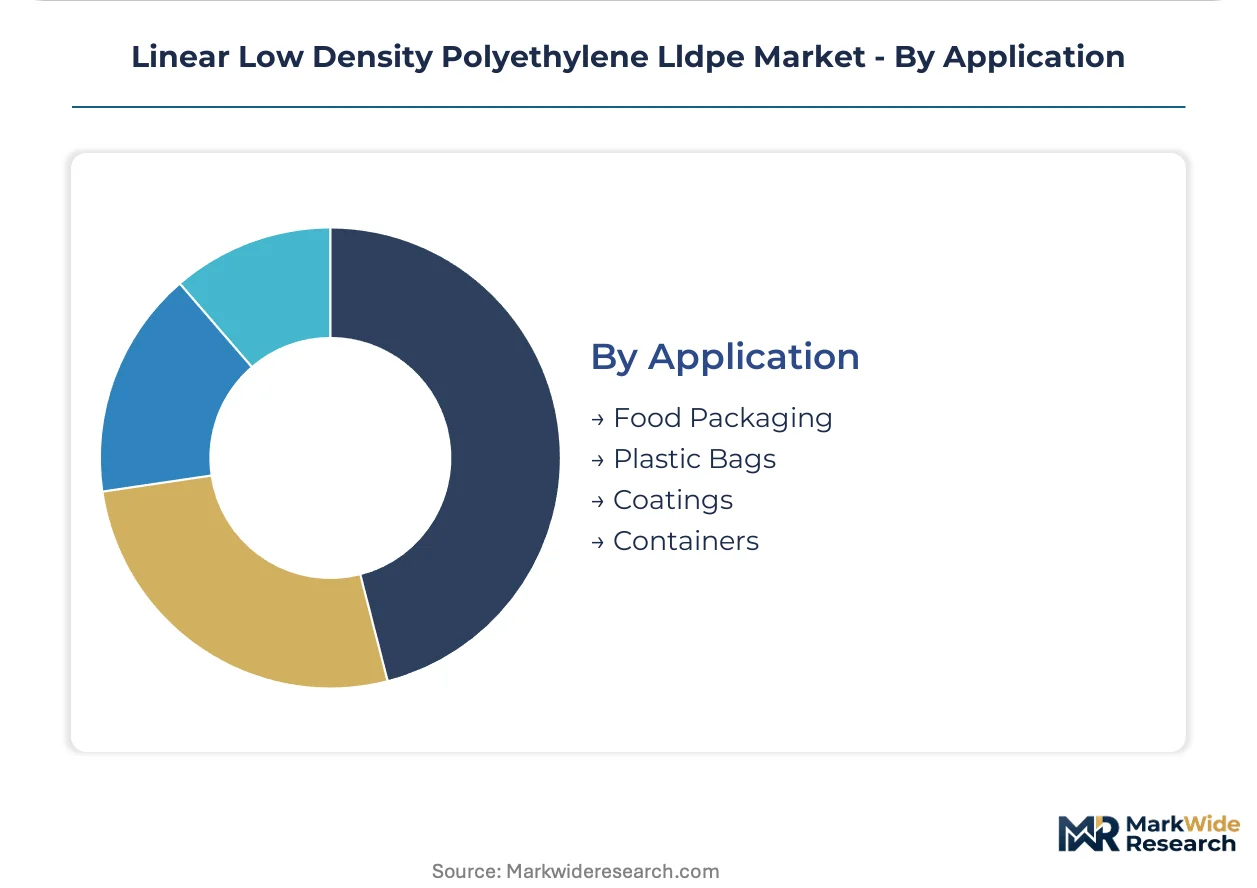
| Segmentation | Product Type: Film, Blown, Extrusion, Injection End Use Industry: Packaging, Automotive, Construction, Agriculture Technology: Gas Phase, Slurry Process, Solution, Supercritical Application: Food Packaging, Plastic Bags, Coatings, Containers |
| Companies Covered | Dow Chemical Company, ExxonMobil Corporation, SABIC, LyondellBasell Industries Holdings B.V., Borealis AG, Chevron Phillips Chemical Company, Reliance Industries Limited, INEOS, Sinopec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Low Density Polyethylene Lldpe Market Strategic Shifts & Innovations
Process intensification and regulatory precision are simultaneously reshaping competitive positioning. Technology convergence, compliance automation, and demand fragmentation are the three forces restructuring how value is captured across the LLDPE value chain.
Metallocene catalyst systems are enabling precise control over short-chain branching distribution in octene copolymers. Food packaging converters in Germany and Japan are adopting these grades for high-speed form-fill-seal lines demanding consistent heat-seal initiation temperatures. Metallocene LLDPE is converging with conventional Ziegler-Natta production economics as catalyst productivity improvements compress unit costs.
REACH authorization requirements for substances of very high concern are expanding to cover specific phthalate-derived additives and certain antioxidant packages used in film-grade resins. ECHA's 2024-2026 substance evaluation roadmap is forcing reformulation investments across European compounders. Agricultural film producers are responding fastest, pivoting to metal-deactivator-free stabilizer systems to maintain greenhouse film durability claims.
Direct procurement relationships between polymer producers and e-commerce fulfillment operators are displacing traditional distributor intermediaries in North American stretch wrap supply. Amazon, Walmart, and regional logistics platforms are negotiating multi-year resin offtake agreements indexed to ethane rather than naphtha benchmarks. This channel compression is most visible in the United States, where centralized distribution networks concentrate volume with fewer specification variants.
Linear Low Density Polyethylene Lldpe Market Segmentation
LLDPE demand fragments across processing methods and end-use specifications that dictate molecular weight distribution, comonomer selection, and additive packages. Buyers prioritize puncture resistance and seal integrity thresholds that vary sharply between agricultural mulch films and pharmaceutical blister packaging. Understanding these segment boundaries clarifies where formulation R&D investments generate measurable returns.
Product Type:
Volume buyers in retail and logistics channels select product types based on gauge requirements and line speed compatibility rather than resin chemistry alone.
- Film:Cast and blown film grades dominate flexible packaging with densities between 0.918 and 0.922 g/cm³ optimized for downgauging. Supermarket chains in the United States and Germany are specifying thinner gauge specifications for produce bags and shrink wrap to meet EU Green Deal packaging reduction mandates.
- Blown:Tubular film extrusion delivers superior tear resistance in stretch wrap applications for palletized e-commerce shipments. Amazon fulfillment centers in Texas and Ohio are consolidating blown film specifications to reduce resin inventory complexity across regional distribution nodes.
- Extrusion:Profile and sheet extrusion serves geomembrane and pond liner applications requiring broader molecular weight distribution for weldability.
- Injection:Molded caps and closures demand higher melt flow rates with narrow polydispersity for thin-wall filling cycles.
Film leads on scale; blown leads on momentum.
End Use Industry:
Regulatory exposure varies dramatically across end uses, with food-contact compliance costs concentrating in packaging while construction faces volatile infrastructure spending cycles.
- Packaging:Flexible food packaging absorbs the largest resin volumes, driven by form-fill-seal automation in retail and direct-to-consumer channels. FDA food-contact notification requirements and ECHA REACH substance evaluations are forcing additive reformulation across European and North American converter networks.
- Automotive:Underhood applications and interior trim utilize LLDPE for impact-modified compounds and fuel tank layers. OEMs in Germany and Japan are specifying lower-emission resin grades to meet interior air quality protocols.
- Construction:Geomembranes, vapor barriers, and pipe coatings serve infrastructure and building envelope applications with long-duration performance requirements.
- Agriculture:Greenhouse films and mulch films demand UV stabilizer packages optimized for latitude-specific solar exposure. Spanish and Dutch growers are adopting supercritical-process grades for extended season durability.
Packaging commands the largest volume base; agriculture is climbing the fastest on greenhouse expansion.
Technology:
Capital efficiency and product slate flexibility determine technology selection, with gas-phase economics favoring commodity volumes while advanced processes capture specialty premiums.
- Gas Phase:Fluidized bed reactors deliver the lowest capital intensity per ton of capacity, anchoring North American and Middle Eastern export supply. Dow Chemical Company and regional producers in Saudi Arabia leverage this technology for high-volume film-grade supply agreements with retail chains.
- Supercritical:Solution polymerization in supercritical propane enables precise molecular weight control for premium film grades with narrower distribution. Dutch and Japanese converters are adopting these resins for high-speed packaging lines requiring consistent heat-seal initiation.
- Slurry Process:Loop reactors with isobutane diluent serve medium-density copolymer production with intermediate capital requirements.
- Solution:Homogeneous catalysis in solvent systems produces specialty grades with controlled short-chain branching for medical and optical applications.
Gas phase dominates installed capacity; supercritical is gaining share fastest on performance differentiation.
Application:
Application selection correlates directly with regulatory jurisdiction, as food-contact approvals in the United States, Europe, and China impose divergent purity and documentation requirements.
- Food Packaging:Primary contact films for meat, dairy, and produce require compliance with FDA 21 CFR, EFSA migration limits, and China's GB standards simultaneously. Multinational food brands are consolidating supplier rosters to reduce qualification burden across these regulatory regimes.
- Plastic Bags:Retail carryout and trash bag applications face divergent single-use plastic bans across California, New York, and European member states. Downgauging specifications are accelerating demand for hexene and octene copolymers with higher tear resistance.
- Coatings:Extrusion coatings for paper and board laminations serve beverage cartons and flexible pouch structures.
- Containers:Injection and blow-molded containers for household and industrial chemicals utilize LLDPE for impact resistance and stress-crack resistance.
Food packaging anchors volume demand; plastic bags face steepest regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes more LLDPE resin than any other nation, yet the United States retains decisive influence over technology licensing and feedstock economics. This divergence shapes investment patterns across four critical production zones.
United States
E-commerce fulfillment networks in Texas and Ohio multiply demand nodes for stretch wrap and protective films. EPA enforcement on ethane extraction emissions conditions Appalachian and Permian Basin supply reliability. Dow Chemical Company leverages gas-phase technology leadership from its Gulf Coast facilities to anchor high-volume supply agreements with Walmart and Amazon distribution centers.
China
Domestic polymer conversion capacity expansion in Zhejiang and Jiangsu provinces outpaces regional resin production. MEE environmental enforcement on volatile organic compound emissions tightens plant licensing for both domestic producers and importers. Yangtze River Delta converters are consolidating supplier rosters to reduce qualification burden across GB standards, FDA, and REACH regimes simultaneously.
Germany
Food packaging converters in Bavaria adopt metallocene grades for high-speed form-fill-seal lines demanding consistent heat-seal initiation temperatures. ECHA REACH substance evaluation protocols accelerate substitution away from legacy LDPE in food-contact applications. Frankfurt-Rhine-Main logistics corridors concentrate demand for downgauged stretch films serving pan-European distribution networks.
Saudi Arabia
SABIC and state-linked producers command disproportionate low-cost export volumes from Gulf Coast petrochemical complexes. SFDA alignment with FDA food-contact standards enables seamless pharmaceutical and food packaging resin exports to Western markets. Jubail Industrial City hosts the densest concentration of ethane-fed LLDPE capacity outside North America.
India
Organized retail growth in Maharashtra and Gujarat expands domestic polymer processing capacity for flexible food wraps. BIS certification requirements for food-contact plastics create compliance barriers for imported resin grades. Mundra and Hazira port clusters are emerging as conversion hubs serving both domestic consumption and Middle East re-export markets.
Linear Low Density Polyethylene Lldpe Market Key Industry Players
Middle Eastern producers anchor one tier through ethane feedstock economics; North American specialists hold technology leadership through gas-phase process maturation. The vendor base stratifies between scale-driven commodity suppliers and formulation-focused grade specialists. Three archetypes dominate: integrated petrochemical majors with captive ethane supply, technology licensors monetizing process patents, and regional compounders serving niche specification windows. Capacity expansion and backward integration into feedstock represent the dominant competitive moves.
Within the integrated major tier, Dow Chemical Company and ExxonMobil Corporation exemplify North American producers leveraging Gulf Coast ethane access and technology licensing revenue streams. SABIC represents Middle Eastern state-linked capacity competing on delivered cost to Asian and European buyers. These three anchors illustrate how feedstock geography and process ownership determine competitive position in film-grade resin supply.
| Leading Market Players |
|---|
| Dow Chemical Company |
| ExxonMobil Corporation |
| SABIC |
| LyondellBasell Industries Holdings B.V. |
| Borealis AG |
| Chevron Phillips Chemical Company |
| Reliance Industries Limited |
| INEOS |
| Sinopec |
| Others |
Cost & Logistics Intelligence
Multinational food brand procurement consolidation is compressing price discovery into long-term offtake agreements indexed to ethane benchmarks rather than naphtha spot markets. This buyer concentration shifts pricing power toward producers with backward integration into Appalachian and Permian Basin feedstock supply.
Pricing Analysis
Capacity additions in the United States Gulf Coast are reshaping price floors for film-grade resin as gas-phase technology maturation compresses capital barriers for new entrants. Three-tier pricing structure across metallocene premium, hexene-copolymer standard, and butene economy levels reflects divergent performance specifications for downgauging applications. Pricing pressure stems from Middle Eastern export volumes undercutting European and Asian spot quotations during demand troughs. Small regional converters exhibit highest price sensitivity, while multinational food brands prioritize specification consistency over unit cost.
Supply Chain Analysis
REACH registration and FDA food-contact notification requirements function as certification gates that fragment supplier qualification across European and North American buyer networks. Production concentrates in Saudi Arabia, the United States, and China, with ethane-fed Gulf Coast and Jubail Industrial City complexes anchoring low-cost export supply. Feedstock draws from Appalachian shale ethane, Permian Basin wet gas, and Middle Eastern associated gas streams. Single-source vulnerability persists for European and Asian buyers dependent on Gulf export volumes. Distribution runs through direct procurement relationships with e-commerce fulfillment operators displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on metallocene catalyst productivity improvements compressing premium-grade production economics toward commodity parity.
For Market Incumbents: Deploy metallocene catalyst system upgrades to capture specification premiums from German and Japanese food packaging converters demanding consistent heat-seal initiation temperatures. Consolidate supplier roster relationships with Amazon and Walmart distribution networks to secure multi-year offtake visibility. Counter SABIC's ethane cost advantage through technology licensing revenue streams and gas-phase process optimization. For New Entrants and Emerging Players: The premium-to-economy tier price gap in Indian flexible packaging conversion offers white-space entry for domestic compounding operations serving Gujarat and Maharashtra organized retail growth. Target underdeveloped high-clarity food wrap segments where BIS certification barriers filter import competition. Pursue bio-based alpha-olefin pilot agreements with Brazilian and Dutch biotech developers to differentiate feedstock positioning. For Investors and Strategic Acquirers: Chemical recycling technology specialists are the most active acquirer category in this space as EU Green Deal packaging mandates accelerate minimum recycled content thresholds. Position for five-to-ten year viability around advanced mechanical and chemical recycling capabilities capturing premium positioning in German and French supply chains. Monitor ECHA substance evaluation roadmap acceleration as inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethane Feedstock | ExxonMobil's Appalachian supply control insulates margin compression during winter heating-demand spikes. |
| Metallocene Catalyst Productivity Investment | Dow Chemical's gas-phase technology leadership sustains high-volume agreements with North American retail chains. |
| EU Green Deal Compliance Positioning | Advanced recycling capabilities capture premium supply chain positioning in German and French markets. |
| Direct E-commerce Fulfillment Procurement | Amazon and Walmart negotiate multi-year resin offtake agreements indexed to ethane benchmarks. |
| Bio-based Alpha-olefin Pilot Agreements | Brazilian and Dutch biotech developers converge renewable feedstocks with conventional gas-phase infrastructure. |
Research Approach
Direct dialogue with polymer plant managers, procurement leads at flexible packaging converters, distribution channel partners, and technical R&D directors grounded qualitative assessments in operational reality. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings, and EPA enforcement disclosures on ethane extraction emissions. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across film, blown, extrusion, and injection product types.
Top-down macroeconomic drivers and bottom-up grade-specific demand curves converged across the analysis window. Segmentation dimensions modeled include technology tier, end-use industry, comonomer selection, and regional production hub. CAGRs were derived from ethylene feedstock cost trajectories, e-commerce fulfillment network expansion rates, and regulatory compliance cost escalations. Forecast inputs incorporated REACH substance evaluation timelines and MEE environmental enforcement intensity on volatile organic compound emissions.
Caveats apply where ethane feedstock volatility, Middle Eastern supply disruption, or mechanical recycling contamination breakthroughs could materially shift the outlook. Forecasts reflect assumptions around gas-phase technology diffusion rates and metallocene catalyst adoption curves. A model refresh is warranted upon material change in ECHA authorization requirements or FDA food-contact notification processing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
High-Density Polyethylene (HDPE) Resins Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market