
 Cosmetic Grade CI 77491 Market | 2026-2036
Cosmetic Grade CI 77491 Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Grade CI 77491 Market Insights
Prestige makeup is expanding its share of CI 77491 offtake as clean beauty positioning drives pigment purity requirements upward. Kolortek anchors its position through backward integration into iron oxide calcination, while Clariant differentiates via surface-treated grades that disperse efficiently in anhydrous lipstick bases. Sensient Technologies competes through ISO-certified manufacturing sites that supply multinational brands with regulatory documentation packages.
Cosmetic Grade CI 77491 is a refined iron oxide pigment with controlled particle size distribution and heavy metal limits below 20 ppm for lead and arsenic, produced through controlled precipitation and calcination of ferrous salts to achieve hue stability in cosmetic matrices. The powder form dominates current volume due to its compatibility with dry blending operations in pressed powder and eyeshadow manufacturing, while liquid dispersions are gaining traction in skincare tinting where cold-process emulsions require pre-dispersed colorants to prevent agglomeration. Specialty Stores and online retail channels are pulling differentiated grades as indie beauty brands bypass traditional mass merchandiser gatekeepers.
REACH in Europe, FDA color additive regulations in the United States, and China's GB standards for cosmetic raw materials collectively determine which CI 77491 variants achieve market access, with heavy metal testing protocols now mandatory for import clearance across all three jurisdictions. ECHA's ongoing restriction proposals for microplastics and persistent pigments are forcing reformulators to validate CI 77491 biodegradation profiles in rinse-off applications. Stakeholders must monitor evolving purity specifications and pre-approval notification requirements before committing to capacity expansions or new supplier qualifications.
Market Dynamics
REACH compliance tightening impurity thresholds is compressing supplier margins while accelerating procurement from specialty chemical producers with certified calcination capabilities.
Growth Catalysts
- Clean beauty certification mandates:Premium formulators in Germany's Rhine-Ruhr cluster now require heavy metal limits below 20 ppm, pulling volume toward backward-integrated pigment producers.
- Surface treatment advances:Hydrophobic coating technologies enable CI 77491 dispersion in anhydrous lipstick bases without agglomeration, expanding addressable SKU count.
- Cold-process skincare expansion:Pre-dispersed liquid CI 77491 variants bypass heat-intensive manufacturing, aligning with energy-conscious emulsion production.
Market Restraints
- Iron ore feedstock volatility:Ferrous salt precursor costs fluctuate with steel industry demand cycles, compressing pigment producer margins during raw material spikes.
- Calcination capacity concentration:Controlled precipitation and high-temperature processing infrastructure clusters in China's Jiangsu province, creating single-source vulnerability.
- Biodegradation validation requirements:ECHA's microplastics restriction proposals force rinse-off formulators to document CI 77491 environmental fate, extending product development timelines.
Strategic Opportunities
- Indie beauty channel bypass:Specialty stores and direct-to-consumer platforms enable smaller pigment batches with customized hue specifications outside mass-merchandiser procurement gates.
- ISO-certified documentation packages:Multinational brands require complete regulatory files for FDA, REACH, and GB standard compliance, favoring suppliers with integrated testing laboratories.
- Pressed powder automation:Dry-blending compatibility with high-speed manufacturing lines creates demand for precisely milled powder grades with narrow particle size distribution.
Industry Challenges
- Batch-to-batch color consistency:Foundation and lip product lines require tight hue tolerance, demanding spectrophotometric validation at multiple production stages.
- Heavy metal testing protocol fragmentation:Import clearance procedures differ across FDA, ECHA, and SAMR jurisdictions, multiplying analytical certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Grade CI 77491 Market |
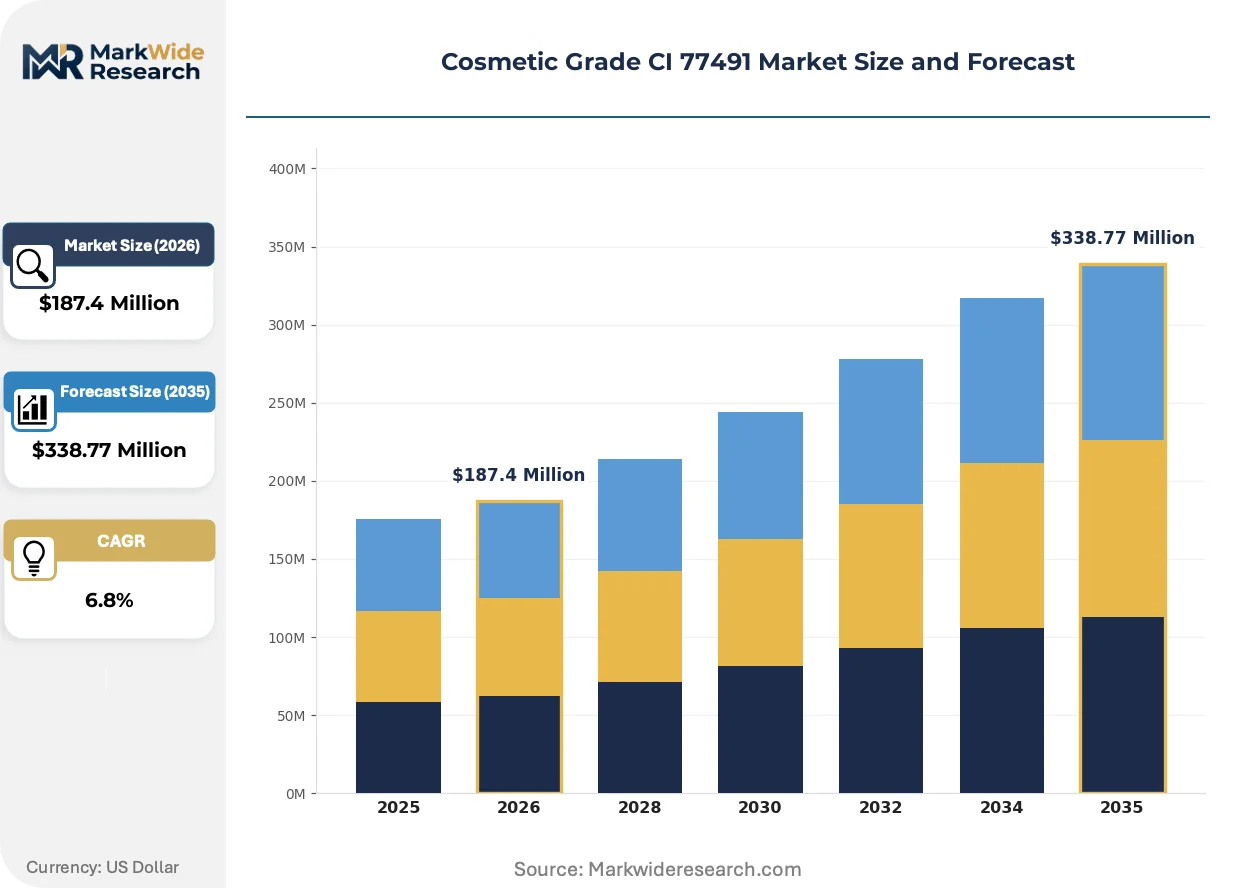
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Makeup, Skincare, Haircare, Fragrance Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Direct Sales Form: Powder, Liquid, Gel, Cream End User: Consumers, Manufacturers, Retailers, Brands |
| Companies Covered | Dechen Chemical, Kolortek, Soujanya, Sensient Technologies, Clariant, Symrise, Koel Colours, BASF, Changzhou Energetic & Reliable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Grade CI 77491 Market Trends and Innovations
Digital color matching platforms and automated dispersion systems are compressing formulation cycles while raising purity requirements across cosmetic pigment supply chains.
Pre-dispersed liquid CI 77491 is decentralizing colorant procurement by enabling skincare manufacturers to bypass in-house milling infrastructure. Mid-sized emulsion producers in South Korea and Brazil now specify cold-process-compatible dispersions, eliminating capital expenditure on particle size reduction equipment. This technology is decentralizing pigment sourcing decisions from centralized procurement teams to individual plant engineers.
REACH authorization procedures for iron oxide impurities are tightening heavy metal thresholds below historical cosmetic-grade norms. ECHA's 2024 guidance documents now require arsenic and lead testing at sub-10 ppm levels for foundation products marketed to sensitive-skin segments. German specialty chemical producers have responded by installing inductively coupled plasma mass spectrometry systems for real-time impurity monitoring.
Direct-to-consumer sampling programs are fragmenting bulk pigment orders into smaller, SKU-specific batches. Indie beauty brands in California and London now request 50-kilogram minimums with custom hue adjustments, displacing traditional 500-kilogram standard-grade commitments. This pattern concentrates in premium color cosmetics where limited-edition releases demand rapid color turnaround without inventory carry risk.
Cosmetic Grade CI 77491 Market Segmentation
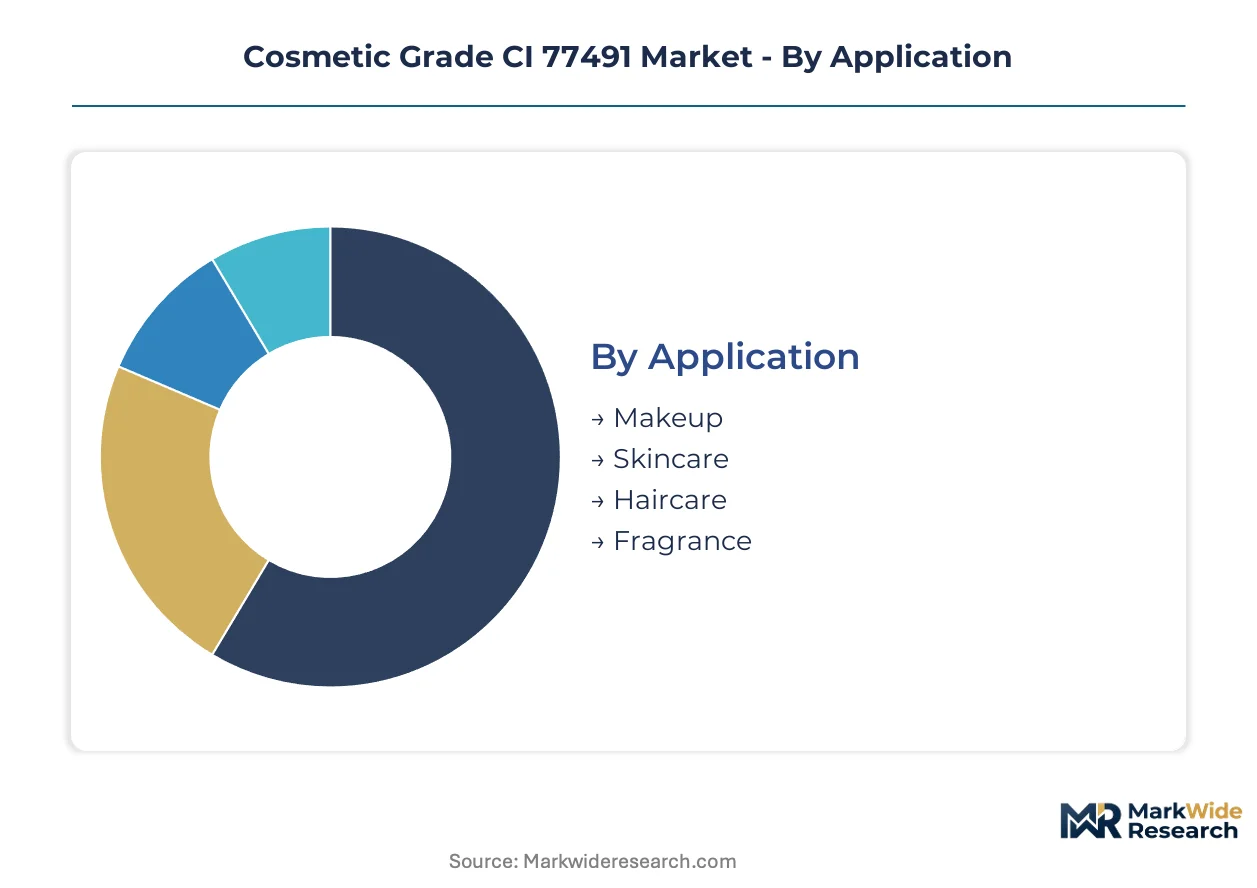
Segmentation in cosmetic-grade iron oxide pigments reveals how purity specifications and formulation requirements fragment procurement decisions across distinct buyer profiles. Each category captures divergent technical priorities that reshape supplier qualification criteria and channel economics.
Application:
Makeup formulators prioritize batch-to-batch hue stability, while skincare manufacturers emphasize cold-process compatibility and heavy metal documentation.
- Makeup:Foundation and lip product lines drive volume concentration in Germany's Rhine-Ruhr cluster, where REACH-compliant producers serve prestige brands with sub-20 ppm heavy metal guarantees. Tight spectrophotometric tolerance requirements compress supplier margins while rewarding backward-integrated pigment calciners.
- Skincare:Tinted moisturizers and SPF formulations specify pre-dispersed liquid variants for cold-process emulsion manufacturing. South Korean and Brazilian mid-sized producers now bypass in-house milling infrastructure by specifying energy-compatible dispersions.
- Haircare:Shampoos and conditioners with color-depositing properties require rinse-off biodegradation validation under ECHA microplastics proposals.
- Fragrance:Decorative colorants in limited-edition packaging demand small-batch custom hue adjustments with rapid turnaround.
Makeup leads volumes today; skincare is gaining share fastest.
Distribution Channel:
Channel selection determines minimum order quantities, documentation depth, and speed of color customization for pigment buyers.
- Online Retail:Direct-to-consumer platforms enable indie beauty brands in California and London to procure 50-kilogram minimums with SKU-specific hue adjustments, displacing traditional 500-kilogram commitments.
- Specialty Stores:Curated beauty retailers pull differentiated grades with complete FDA, REACH, and GB regulatory files, favoring suppliers with integrated testing laboratories.
- Mass Merchandisers:High-volume standardized procurement gates concentrate volume toward certified calcination producers with batch-to-batch consistency guarantees.
- Direct Sales:Beauty advisors and multi-level marketing channels require portable sampling formats with stable colorant dispersion in travel-sized packaging.
Mass merchandisers dominate procurement volume; online retail channels are climbing the fastest.
Form:
Physical state dictates manufacturing equipment requirements and energy intensity in final formulation processes.
- Powder:Dry iron oxide with controlled particle size distribution dominates pressed powder and eyeshadow manufacturing through compatibility with high-speed blending operations. German specialty chemical producers supply precisely milled grades with narrow distribution for automation.
- Liquid:Pre-dispersed aqueous and anhydrous dispersions enable cold-process skincare manufacturing without capital expenditure on particle size reduction equipment.
- Gel:Suspension systems for transparent color cosmetics require rheology-matched dispersion to prevent syneresis in tube packaging.
- Cream:Pigment concentrates in emollient bases serve anhydrous lipstick manufacturing where hydrophobic surface treatments prevent agglomeration.
Powder form leads current volume; liquid dispersions are expanding most quickly.
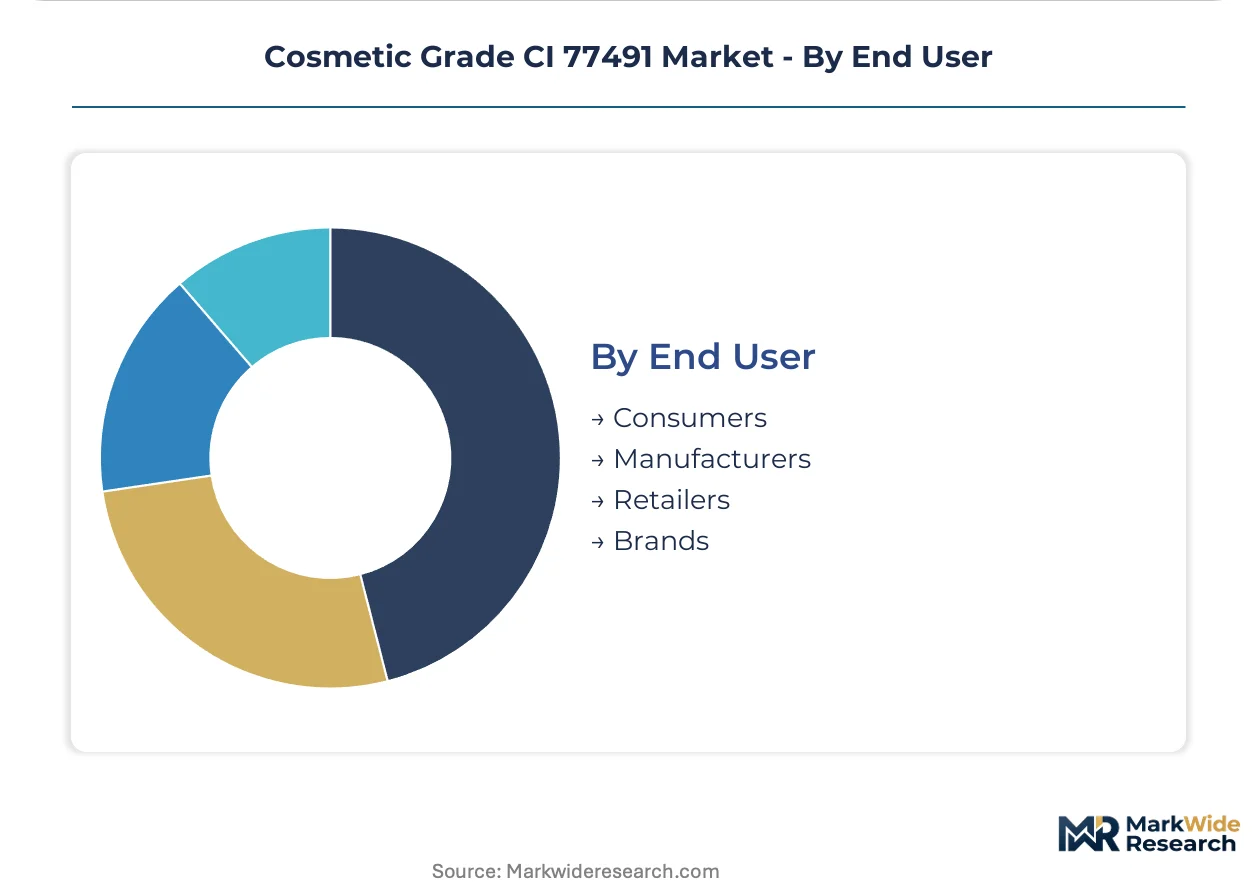
End User:
End-user type determines regulatory documentation burden and technical support intensity required from pigment suppliers.
- Consumers:DIY beauty formulators and small-scale artisans purchase through repackaged retail channels with basic safety documentation.
- Manufacturers:Contract manufacturers serving multinational brands require ISO-certified manufacturing sites with complete import clearance packages for FDA, ECHA, and SAMR jurisdictions.
- Retailers:Private-label beauty chains specify custom hue libraries with exclusive colorant formulations differentiated from national brand equivalents.
- Brands:Prestige and indie beauty companies drive clean beauty certification mandates, pulling procurement toward producers with real-time inductively coupled plasma mass spectrometry monitoring.
Manufacturers represent the largest procurement volume; brands are driving the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping pigment production geography as calcination capacity migrates toward jurisdictions with lower compliance-cost structures, while formulation demand clusters in markets with tightening purity mandates.
Germany
Rhine-Ruhr specialty chemical producers serve prestige makeup brands demanding sub-20 ppm heavy metal guarantees. ECHA's REACH authorization procedures now require arsenic testing at sub-10 ppm levels for sensitive-skin foundation lines. Düsseldorf-based formulators anchor procurement volume through backward-integrated supply relationships with certified calciners.
United States
California and New York indie beauty brands drive fragmentation toward 50-kilogram minimum orders with SKU-specific hue adjustments. FDA color additive regulations mandate complete import documentation packages for iron oxide pigments. Los Angeles direct-to-consumer platforms bypass traditional mass-merchandiser procurement gates with rapid color-turnaround requirements.
China
Jiangsu province concentrates controlled precipitation and high-temperature calcination infrastructure, creating single-source vulnerability for global supply. SAMR's GB standards for cosmetic raw materials now align heavy metal testing protocols with REACH and FDA benchmarks. Shanghai specialty chemical zones supply multinational brands with integrated regulatory documentation packages.
South Korea
Mid-sized emulsion producers in Seoul Capital Area specify cold-process-compatible liquid dispersions, eliminating capital expenditure on particle size reduction equipment. MFDS cosmetic safety regulations require pre-market notification for new pigment formulations. Busan-Ulsan manufacturing corridors import pre-dispersed CI 77491 variants for skincare tinting applications.
Brazil
São Paulo contract manufacturers serving Latin American prestige brands demand ISO-certified manufacturing sites with ANVISA import clearance documentation. Local formulators navigate fragmented heavy metal testing protocols that differ from FDA and ECHA requirements. Rio Grande do Sul industrial clusters specialize in pressed powder automation compatible with precisely milled powder grades.
Cosmetic Grade CI 77491 Market Competitive Landscape
Backward integration into iron oxide calcination dominates the current landscape as specialty chemical producers defend margin position against feedstock volatility. The vendor base stratifies across three tiers: multinational pigment houses with certified manufacturing sites, regional specialists with surface-treatment capabilities, and commodity traders sourcing standardized powder grades. Two strategic archetypes command attention—producers with captive upstream ferrous salt supply and formulators with integrated spectrophotometric validation laboratories. Capacity expansion in China's Jiangsu province and strategic partnerships for regulatory documentation services represent the dominant competitive vectors.
Among the backward-integrated tier, Kolortek anchors pigment calcination capabilities while Clariant occupies a position exemplifying surface-treated grade specialization. Sensient Technologies represents the ISO-certified manufacturing archetype with integrated testing infrastructure. These three entities collectively illustrate how purity documentation and dispersion technology differentiate procurement decisions across premium color cosmetics supply chains.
| Leading Market Players |
|---|
| Dechen Chemical |
| Kolortek |
| Soujanya |
| Sensient Technologies |
| Clariant |
| Symrise |
| Koel Colours |
| BASF |
| Changzhou Energetic & Reliable |
| Others |
Pricing and Supply Chain Analysis
Iron ore futures volatility cascades through ferrous salt precursor markets into three-tier pricing stratification across premium REACH-certified, standard cosmetic-grade, and economy industrial-purity tiers. German specialty chemical producers command premium positioning through real-time inductively coupled plasma mass spectrometry monitoring, while Jiangsu province calcination facilities anchor economy tier supply.
Pricing Analysis
Distributor margin compression in mass-merchandiser channels intensifies as REACH compliance costs concentrate procurement toward certified producers. Price differentiation hinges on heavy metal certification grade and volume scale, with sub-10 ppm arsenic guarantees commanding substantial premiums over standard sub-20 ppm grades. Pricing pressure stems from iron ore feedstock cyclicality squeezing calciner margins. Indie beauty brands in direct-to-consumer channels exhibit highest price sensitivity; prestige makeup houses demonstrate lowest sensitivity due to clean beauty positioning requirements.
Supply Chain Analysis
Dual-sourcing mandates from multinational brands now require qualification of secondary calcination suppliers outside China's Jiangsu province. Geographic supply concentration centers on China, Germany, and the United States for controlled precipitation infrastructure. Raw material dependencies include ferrous sulfate precursors, high-purity iron ore, and surface-treatment coating chemicals. Single-source vulnerability in Jiangsu calcination capacity represents the dominant structural risk. Distribution runs through specialty chemical distributors serving formulators with integrated regulatory documentation packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between ECHA's tightening REACH authorization costs in Western Europe and China's SAMR-aligned GB standard compliance infrastructure, where calcination capacity expansion carries lower regulatory overhead per ton.
For Market Incumbents: Hedge against Jiangsu province concentration risk by qualifying secondary calcination partnerships in Germany's Rhine-Ruhr cluster or South Korea's Busan-Ulsan corridor. Invest in inductively coupled plasma mass spectrometry infrastructure to defend premium positioning as ECHA proposes sub-10 ppm arsenic thresholds for sensitive-skin segments. Channel control through direct technical service relationships with prestige makeup houses anchors pricing power against feedstock volatility. For New Entrants and Emerging Players: Capture fragmented indie beauty procurement in California and London through 50-kilogram minimum order capabilities with SKU-specific hue adjustments. The online retail channel presents the most penetrable entry point, bypassing mass-merchandiser volume gates that favor incumbent scale. A go-to-market angle emphasizing cold-process liquid dispersion compatibility targets South Korean and Brazilian mid-sized emulsion producers seeking to eliminate capital expenditure on particle size reduction equipment. For Investors and Strategic Acquirers: Consolidation pressure builds where backward-integrated calcination capabilities overlap with ISO-certified documentation infrastructure serving multinational brand procurement requirements. Long-term viability in this market hinges on regulatory compliance cost absorption capacity rather than commodity scale. Acquisition targets should demonstrate captive ferrous salt supply or integrated spectrophotometric validation laboratories. The signal to watch is ECHA's final microplastics restriction implementation timeline, which would force biodegradation validation investments across rinse-off formulator supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iron Oxide Calcination | Kolortek's captive ferrous salt supply insulates margin position against steel industry demand cycles. |
| Surface Treatment Technology Investment | Clariant's hydrophobic coating patents enable premium positioning in anhydrous lipstick dispersion applications. |
| ISO-Certified Manufacturing Site Expansion | Sensient Technologies' integrated testing laboratories satisfy multinational brand documentation package requirements. |
| Cold-Process Liquid Dispersion Development | Pre-dispersed variants target South Korean emulsion producers eliminating in-house milling capital expenditure. |
| Dual-Sourcing Partnership Qualification | Secondary supplier validation outside Jiangsu province mitigates single-source concentration risk for REACH compliance. |
Research Methodology
Multiple input streams — primary interviews with specialty chemical procurement directors, plant managers at calcination facilities, and regulatory affairs leads at multinational beauty brands; secondary validation through ECHA guidance documents, FDA color additive regulations, SAMR GB standards, and customs trade flow data; plus SEC filings from listed pigment producers — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments of REACH compliance cost pass-through and clean beauty certification adoption rates. Segmentation dimensions modeled include application type, physical form, distribution channel, and end-user category across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating iron ore price cyclicality and calcination capacity expansion timelines. Industry-specific forecast inputs included ECHA microplastics restriction proposal status and MFDS pre-market notification processing rates.
Iron ore price spikes, ECHA authorization timeline acceleration, and SAMR enforcement intensity variations are the dominant revision risks to the outlook. Deviation in ECHA's final microplastics restriction implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
North America Jojoba Oil Market