
 Europe Anti-Piracy Protection Market | 2026-2036
Europe Anti-Piracy Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Anti-Piracy Protection Market Insights
European cybersecurity vendor capacity is restructuring around forensic watermarking and real-time stream monitoring. Red Points Solutions S.L. leverages automated takedown workflows across e-commerce and social platforms. Irdeto B.V. anchors conditional access and DRM integration for satellite and IPTV operators. Synamedia competes through AI-driven credential-sharing detection deployed by tier-one broadcasters.
Anti-piracy protection encompasses technical systems that identify, track, and neutralize unauthorized content distribution through watermark embedding, encryption protocols, and automated monitoring algorithms. These systems serve rights holders by preserving revenue integrity across streaming, broadcast, and physical media channels. Cloud-based deployment models are gaining preference as media companies abandon capital-intensive on-premises infrastructure. AI Detection technology leads growth velocity among technology segments due to its capacity for real-time pattern recognition across fragmented piracy vectors. Monitoring services sustain the largest revenue pool within service types, reflecting recurring subscription structures tied to content release calendars.
The EU Digital Services Act, GDPR, and CE marking requirements for encryption products collectively shape vendor product roadmaps and client procurement criteria. EMA and national regulators in France and Germany are intensifying scrutiny of cross-border content licensing compliance. Stakeholders must weigh interoperability investments against the fragmentation of national enforcement protocols as the regulatory perimeter hardens.
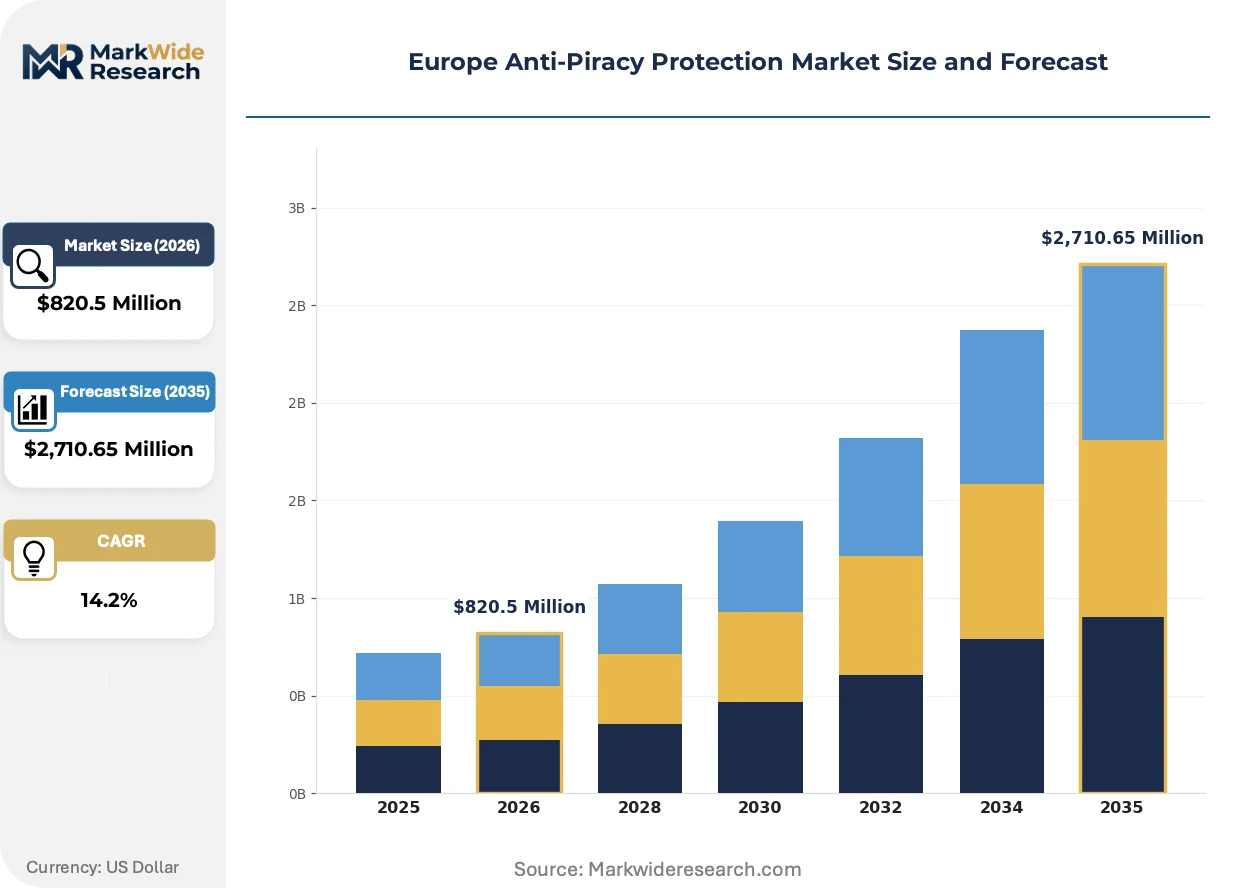
Market Dynamics
Streaming platform operators across Germany and France are restructuring procurement around real-time forensic watermarking as live sports piracy erodes subscription revenue integrity. The EU Digital Services Act is compressing compliance timelines for content distributors.
Growth Catalysts
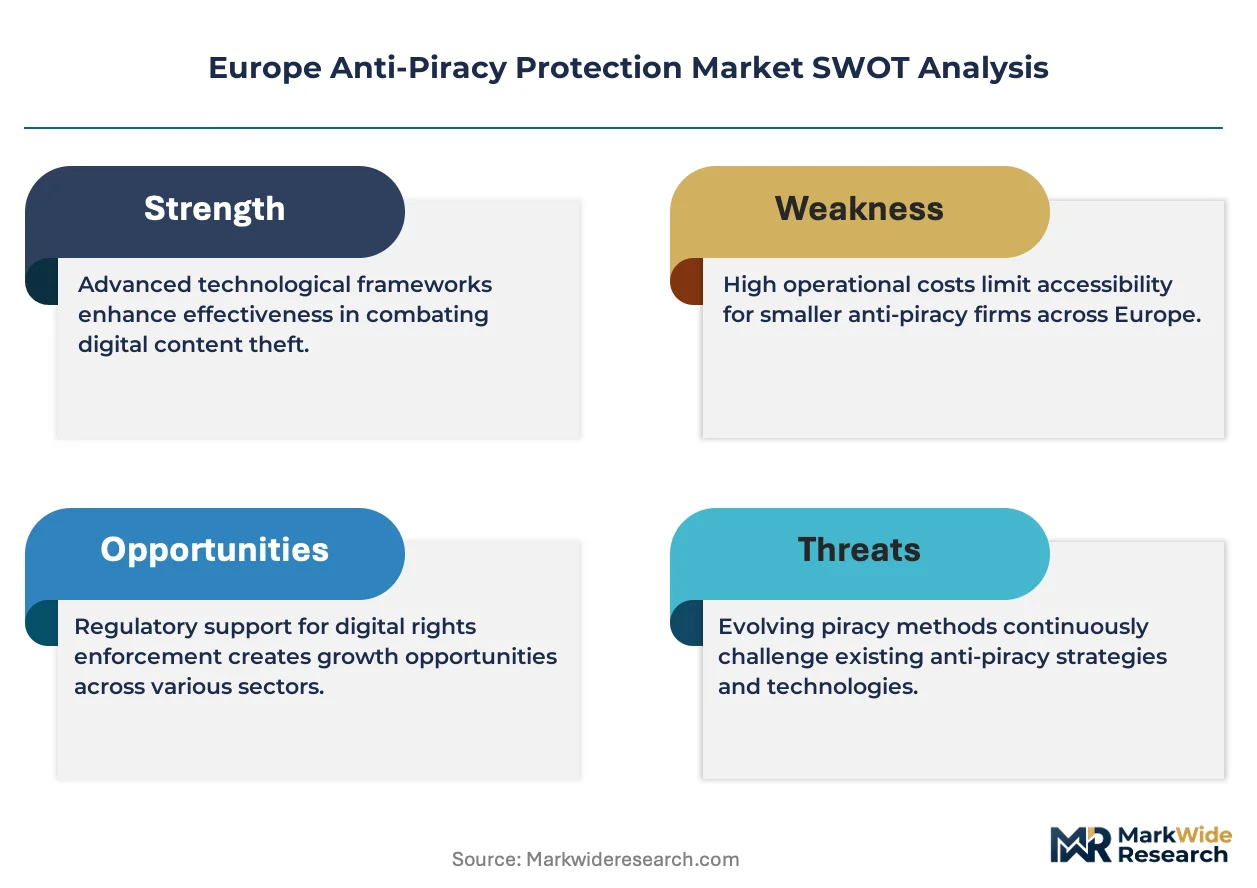
- EU Digital Services Act enforcement:Takedown mandates for illegal content are accelerating vendor procurement of automated monitoring systems by broadcasters and streaming platforms.
- Live sports streaming:Premium rights holders in the United Kingdom and Nordic markets are deploying AI-driven credential-sharing detection to protect pay-per-view revenue.
- Forensic watermarking:Cloud-based embedding technologies are replacing on-premises DRM infrastructure as media companies prioritize operational flexibility.
Market Restraints
- Cross-border enforcement fragmentation:Divergent national interpretations of copyright directives create compliance friction for vendors serving multiple EU member states.
- Encryption product certification:CE marking requirements and GDPR data residency rules extend sales cycles for conditional access system providers.
- Open-source circumvention tools:Widely available decryption software reduces the effective lifespan of proprietary DRM deployments.
Strategic Opportunities
- Eastern European markets:Poland and Czech Republic streaming platforms are underinvested in anti-piracy infrastructure relative to Western European peers.
- Social platform integration:Automated takedown workflows for user-generated content platforms represent an adjacent service expansion path.
- EU AI Act alignment:Compliance frameworks for algorithmic content filtering create demand for explainable AI detection systems.
Industry Challenges
- Forensic analyst talent scarcity:Specialized skills in watermark extraction and signal analysis concentrate in London and Paris, limiting vendor scaling.
- Legacy broadcast infrastructure:Satellite and cable operators face integration complexity when overlaying cloud-native monitoring onto conditional access systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Anti-Piracy Protection Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $2,710.65 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Monitoring, Legal Action, Digital Rights Management, Consultation Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Content Creators, Industry Associations, Corporations, Government Agencies Technology: Blockchain, AI Detection, Watermarking, Encryption |
| Companies Covered | Red Points Solutions S.L., Irdeto B.V., Synamedia, Verimatrix, Castlabs GmbH, Friend MTS Limited, Kudelski Group, Brightcove, Inc., Digimarc Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Anti-Piracy Protection Market Trends and Innovations
Artificial intelligence detection architectures are compressing response windows for unauthorized stream identification. Vendors are racing to embed real-time pattern recognition across fragmented piracy vectors.
Forensic watermarking is expanding into live streaming workflows through frame-accurate embedding algorithms. Tier-one broadcasters in the United Kingdom and Germany are adopting these systems for premier sports events. The technology is expanding into subscriber-level tracing, enabling rights holders to identify and suspend accounts engaged in credential sharing.
The EU Digital Services Act is mandating proactive content filtering obligations for platforms exceeding threshold user bases. Illegal streaming links must be removed within hours of notification. Streaming operators in France and Germany are restructuring vendor contracts to include guaranteed takedown service levels.
Subscription fatigue is compressing buyer tolerance for credential-sharing enforcement. Consumers in Nordic markets are resisting account monitoring as invasive. Platforms are responding with graduated warning systems rather than immediate suspension, balancing revenue protection against churn risk.
Europe Anti-Piracy Protection Market Segmentation
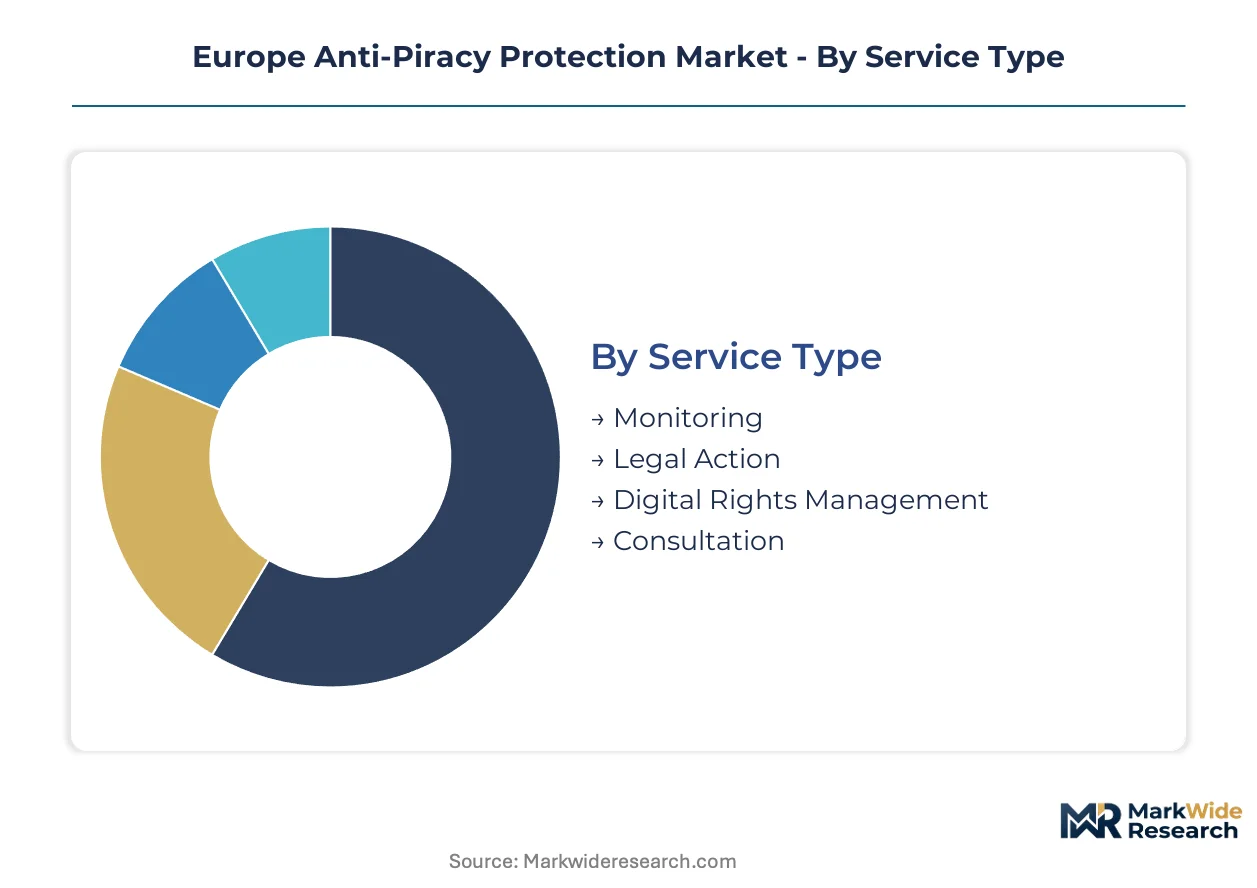
Anti-piracy procurement across Europe fragments across four distinct axes. Service delivery models, infrastructure deployment choices, client organizational types, and underlying detection technologies each reshape vendor competitive positioning and contract value.
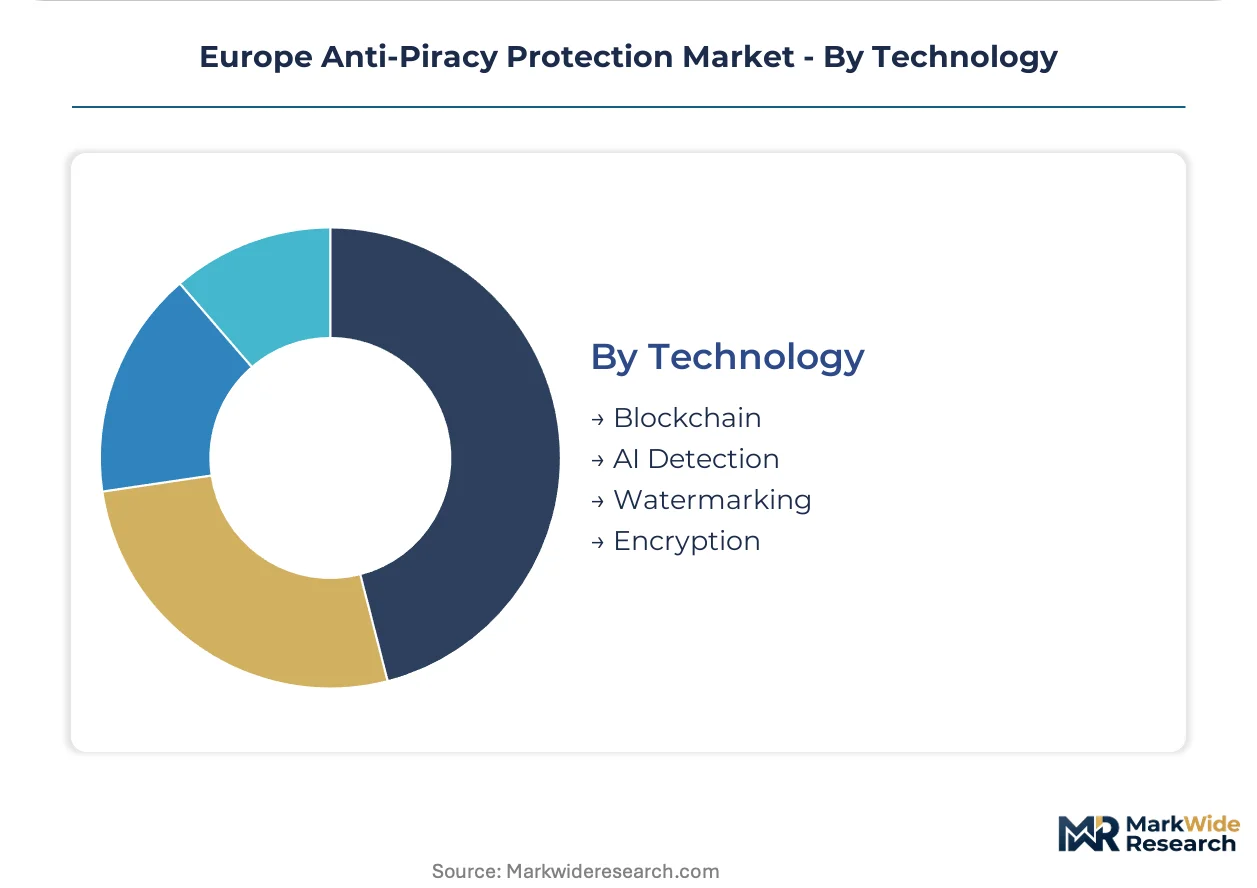
Technology:
Technical capabilities differentiate vendor offerings across forensic identification, automated detection, and cryptographic protection layers.
- AI Detection:Machine learning architectures process streaming content in real-time to identify unauthorized redistribution patterns. Broadcasters in the United Kingdom and Nordic markets deploy these systems against live sports piracy, where detection latency directly correlates with revenue loss per minute.
- Watermarking:Forensic embedding technologies insert imperceptible identifiers at the frame or subscriber level, enabling post-distribution tracing. German and French streaming operators are replacing legacy DRM with cloud-native watermarking for operational flexibility across multi-CDN workflows.
- Encryption:Conditional access systems protect content in transit through cryptographic protocols. Satellite and IPTV operators maintain these deployments despite pressure from open-source circumvention tools.
- Blockchain:Distributed ledger applications verify content provenance and licensing chain integrity. Rights registry pilots are emerging among collective management organizations in France and Germany.
Mature deployment sits with Encryption. Newer deployment is concentrated in AI Detection.
Service Type:
Commercial contracts organize around recurring monitoring subscriptions versus discrete legal and advisory engagements.
- Monitoring:Continuous surveillance of web, social, and streaming platforms for unauthorized content distribution. Tier-one broadcasters structure these contracts around content release calendars, with takedown service levels mandated by EU Digital Services Act compliance timelines.
- Digital Rights Management:Technical infrastructure deployment and license management for content protection. Cloud migration is displacing on-premises DRM installations as media companies abandon capital-intensive hardware refresh cycles.
- Legal Action:Enforcement services spanning cease-and-desist workflows, litigation support, and cross-border coordination. National court fragmentation across EU member states complicates vendor service standardization.
- Consultation:Advisory engagements on compliance architecture, vendor selection, and regulatory alignment. GDPR and CE marking requirements extend procurement cycles for encryption product certification.
Revenue concentration favors Monitoring. Legal Action contracts are expanding most quickly as rights holders pursue direct enforcement.
Deployment Model:
Infrastructure location decisions balance data sovereignty requirements against operational agility and cost structure.
- Cloud-Based:Vendor-hosted platforms with subscription pricing and elastic capacity scaling. GDPR data residency rules shape provider selection criteria, with French and German broadcasters preferring EU-sovereign cloud regions.
- Hybrid:Split architectures combining on-premises conditional access with cloud-native monitoring layers. Satellite operators adopt this model to preserve legacy encryption hardware while adding AI detection capabilities.
- On-Premises:Client-managed infrastructure with full operational control. Public broadcasters and government agencies maintain these deployments for security classification reasons.
- Managed Services:Outsourced operations where vendors assume full technical and staffing responsibility. Mid-tier streaming platforms in Poland and Czech Republic favor this model to access specialized forensic analyst skills.
Hybrid architectures dominate incumbent broadcaster transitions. Cloud-Based deployments are gaining share fastest among new market entrants.
End User:
Demand concentration varies by organizational scale, content volume, and regulatory exposure.
- Content Creators:Studios, production companies, and individual rights holders protecting original intellectual property. Independent filmmakers in the United Kingdom leverage automated takedown workflows across social platforms.
- Industry Associations:Collective management organizations and trade groups coordinating multi-stakeholder enforcement. French and German music and film collectives pool resources for cross-border legal action.
- Corporations:Enterprises with internal media libraries, training content, or branded video assets. Broadcasting and telecommunications firms represent the largest contract values within this category.
- Government Agencies:Public bodies with cultural heritage content, educational media, or regulatory enforcement mandates. National film institutes and public broadcasters deploy watermarking for archive protection.
Corporations command the largest average contract size. Content Creators represent the broadest addressable base with highest fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's clustering of forensic analyst talent anchors European anti-piracy capability development. Rights holders across the continent source specialized watermarking and stream monitoring expertise from this technical hub.
United Kingdom
Tier-one broadcasters deploy AI-driven credential-sharing detection against live sports piracy during Premier League and Six Nations fixtures. Ofcom enforces platform accountability under the Online Safety Bill timeline. London's forensic analyst concentration supports real-time watermark extraction for subscriber-level tracing.
Germany
Streaming operators restructure procurement around cloud-native forensic watermarking for multi-CDN operational flexibility. CE marking requirements and GDPR data residency rules extend sales cycles for encryption product certification. Berlin and Munich host vendor development centers for conditional access system integration.
France
Premium rights holders pursue automated takedown workflows mandated by EU Digital Services Act compliance timelines. The CNIL scrutinizes algorithmic content filtering under GDPR algorithmic decision-making provisions. Paris anchors collective management organization pilots for blockchain-based rights registry verification.
Italy
Broadcasters face elevated credential-sharing abuse across Serie A streaming subscriptions. ANSA coordination with EU copyright enforcement directives shapes vendor contract structures. Milan's media technology cluster supports hybrid deployment architectures combining on-premises conditional access with cloud-native monitoring layers.
Nordic Region
Subscription fatigue compresses buyer tolerance for invasive account monitoring in Sweden and Norway. National regulators align with EU AI Act explainability requirements for detection algorithm deployment. Stockholm and Copenhagen streaming platforms balance graduated warning systems against immediate suspension protocols to manage churn risk.
Europe Anti-Piracy Protection Market Competitive Landscape
Global majors compete with regional champions across forensic watermarking and real-time stream monitoring capabilities. The vendor base organizes around three tiers: integrated conditional access providers, cloud-native AI detection specialists, and legal enforcement services firms. Strategic differentiation concentrates on M&A activity targeting credential-sharing detection capabilities and strategic partnerships for social platform takedown integration.
Within the integrated protection tier, Irdeto B.V. and Synamedia occupy positions exemplifying conditional access and DRM integration archetypes. Red Points Solutions S.L. represents the automated enforcement specialist model across e-commerce and social platform vectors. These three anchors illustrate distinct competitive positioning: broadcast infrastructure heritage, AI-native detection architecture, and cross-platform takedown workflow automation respectively.
| Leading Market Players |
|---|
| Red Points Solutions S.L. |
| Irdeto B.V. |
| Synamedia |
| Verimatrix |
| Castlabs GmbH |
| Friend MTS Limited |
| Kudelski Group |
| Brightcove, Inc. |
| Digimarc Corporation |
| Others |
Pricing and Supply Chain Analysis
Cloud-native watermarking premium versus on-premises encryption commodity tier divergence manifests in both pricing power and supply chain configurations across European anti-piracy procurement. German and French broadcasters pay service premiums for elastic capacity while satellite operators absorb hardware refresh costs, with GDPR data residency rules and CE marking timelines reshaping vendor sourcing geography.
Pricing Analysis
Warranty-bundled takedown service levels versus unbundled software licensing structures dominate European anti-piracy contracts. Three-tier pricing structure across premium, standard, and economy levels separates tier-one broadcasters with guaranteed response times from mid-tier streaming platforms on subscription SaaS tiers and government agencies on perpetual licenses. Price differentiation rests on forensic analyst availability in London and Paris versus automated-only service tiers. Pricing pressure stems from open-source circumvention tools compressing DRM effective lifespan. Mid-tier streaming platforms in Poland and Czech Republic exhibit highest price sensitivity; tier-one UK broadcasters show lowest.
Supply Chain Analysis
GDPR data residency mandates and EU AI Act algorithmic transparency requirements are reshaping vendor sourcing toward EU-sovereign cloud regions. Forensic analyst talent concentrates in the United Kingdom, France, and Germany, with watermarking algorithm development anchored in Berlin and Munich. Cloud infrastructure draws from Ireland, Netherlands, and Germany data center clusters. Supply chain risk centers on single-source vulnerability for specialized signal analysis hardware. Distribution runs through direct vendor relationships with tier-one broadcasters and channel partners serving mid-tier streaming platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forensic analyst scarcity in London and Paris props pricing power for vendors with captive talent pools, constraining market capacity expansion.
For Market Incumbents: To counter open-source circumvention tools eroding DRM value, Irdeto and Synamedia should deepen backward integration into watermarking algorithm development and secure exclusive forensic analyst pipelines through London and Paris university partnerships. Capacity addition in Berlin and Munich development centers strengthens conditional access integration capabilities against cloud-native challengers. For New Entrants and Emerging Players: Capture underinvested streaming platforms in Poland and Czech Republic through managed services packaging that bridges forensic analyst skill gaps. The most penetrable segment is mid-tier Eastern European broadcasters lacking in-house security operations. Go-to-market through channel partners with existing GDPR compliance consulting relationships accelerates contract velocity. For Investors and Strategic Acquirers: Re-rating potential sits with AI-native detection specialists given EU AI Act explainability requirements creating compliance-driven demand inflection. Long-term viability favors vendors with hybrid cloud-on-premises architectures serving incumbent broadcaster transitions. The signal to watch is tier-one broadcaster contract restructuring around guaranteed takedown service levels.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI Detection Specialist | EU AI Act compliance creates demand for explainable algorithmic filtering systems. |
| Cloud-Native Watermarking Platform Launch | German and French broadcasters prioritize multi-CDN operational flexibility over legacy DRM. |
| Social Platform Takedown Partnership | EU Digital Services Act mandates accelerate automated enforcement workflow procurement. |
| Eastern European Market Expansion | Poland and Czech Republic streaming platforms lag Western peers in anti-piracy infrastructure. |
| Forensic Analyst Talent Pipeline Investment | London and Paris skill concentration limits vendor scaling without captive university relationships. |
Research Methodology
Document review covered vendor technical documentation, EU regulatory filings including Digital Services Act implementation guidance and GDPR enforcement decisions, and broadcast industry procurement disclosures, complemented by interviews with anti-piracy technology directors at tier-one broadcasters, streaming platform security operations leads, forensic watermarking engineers, collective management organization legal enforcement heads, and EU regulatory affairs specialists. Secondary validation drew from EMA cross-border licensing coordination records, CE marking certification databases, and national copyright enforcement directive transposition documents. Bottom-up contract value aggregation and top-down market sizing triangulation anchored the analytical framework.
Market value outputs reflect segment-level modeling across technology type, service delivery model, deployment architecture, and end-user organizational category, with AI Detection, Watermarking, Encryption, and Blockchain segments tracked separately across the projection horizon. CAGRs were derived from technology adoption curve analysis weighted against regulatory compliance deadline clustering. Forecast inputs incorporated streaming subscriber growth trajectories in the United Kingdom and Nordic markets, live sports rights inflation patterns, and EU AI Act implementation timeline uncertainty.
The model holds under steady regulatory enforcement intensity and sustained streaming platform investment cycles; deviation in open-source circumvention tool proliferation velocity or cross-border copyright directive harmonization would shift vendor competitive positioning and contract value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Door and Window Alarm Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Explosive Detection Kit Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market