
 Global Alarm Monitoring Market | 2026-2036
Global Alarm Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alarm Monitoring Market Foresight
Buyer consolidation across commercial real estate portfolios is restructuring procurement patterns for alarm monitoring services. Johnson Controls International Plc leverages its building automation footprint to bundle monitoring with HVAC and access control contracts. ADT Corporation anchors its position through professional installation networks and recurring revenue models in the residential segment. Honeywell International Inc. differentiates via in-house sensor manufacturing and backward integration into fire detection hardware.
Alarm monitoring encompasses the continuous surveillance of sensor networks—detecting intrusion, fire, environmental hazards, or equipment faults—and the automated routing of alerts to human operators or emergency responders, typically requiring sub-30-second signal transmission and 99.995% uptime reliability. Video surveillance and cloud-based solutions are capturing disproportionate investment as enterprises shift from on-premise storage to centralized, AI-augmented analysis platforms. Wireless systems and Internet of Things connectivity are displacing legacy wired infrastructure in retrofit applications, though wired systems sustain dominance in new industrial construction where electromagnetic interference tolerance matters.
The US FCC governs radio frequency allocations for wireless alarm transmitters, while Europe's ETSI standards and GDPR constrain cross-border data flows from cloud-monitored premises. India's BIS certification requirements for electronic safety equipment create compliance hurdles for imported monitoring hardware. Stakeholders must weigh regional certification timelines against the accelerating shift toward software-defined monitoring architectures that decouple hardware from service delivery.
Market Dynamics
Commercial real estate portfolios are consolidating vendor relationships around integrated platforms that bundle alarm monitoring with building automation, compressing procurement cycles and reshaping competitive positioning toward full-stack providers.
Growth Catalysts
- Insurance-mandated monitoring:US property insurers now require continuous professional monitoring for commercial policies, accelerating replacement cycles in legacy buildings.
- Europe's Cyber Resilience Act:Baseline security requirements for connected alarm devices are forcing hardware upgrades and creating compliance-driven refresh demand.
- Smart building retrofits:Wireless IoT connectivity is penetrating aging commercial infrastructure where wired installation costs previously blocked adoption.
Market Restraints
- Semiconductor supply concentration:Sensor chip fabrication concentrates in East Asian foundries, exposing monitoring hardware makers to geopolitical disruption risk.
- Cellular module cost volatility:LTE and 5G radio modules for wireless alarm transmitters face input cost swings tied to rare earth mineral markets.
- Legacy protocol fragmentation:Proprietary signaling formats from 1990s-era panels persist in installed bases, complicating cloud migration paths.
Strategic Opportunities
- India's BIS certification gap:Domestic certification requirements for electronic safety equipment create localized production incentives for compliant hardware.
- AI-augmented video verification:Machine learning convergence with cloud storage is opening subscription revenue streams beyond traditional alarm response.
- Edge computing architectures:On-premise inference chips are enabling latency-sensitive detection without full cloud dependency, appealing to data-sensitive verticals.
Industry Challenges
- Cybersecurity talent scarcity:Embedded systems security expertise remains scarce among monitoring service operators adapting to connected device threats.
- Multi-protocol integration complexity:Merging Z-Wave, Zigbee, and proprietary wireless stacks into unified monitoring platforms demands specialized engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alarm Monitoring Market |
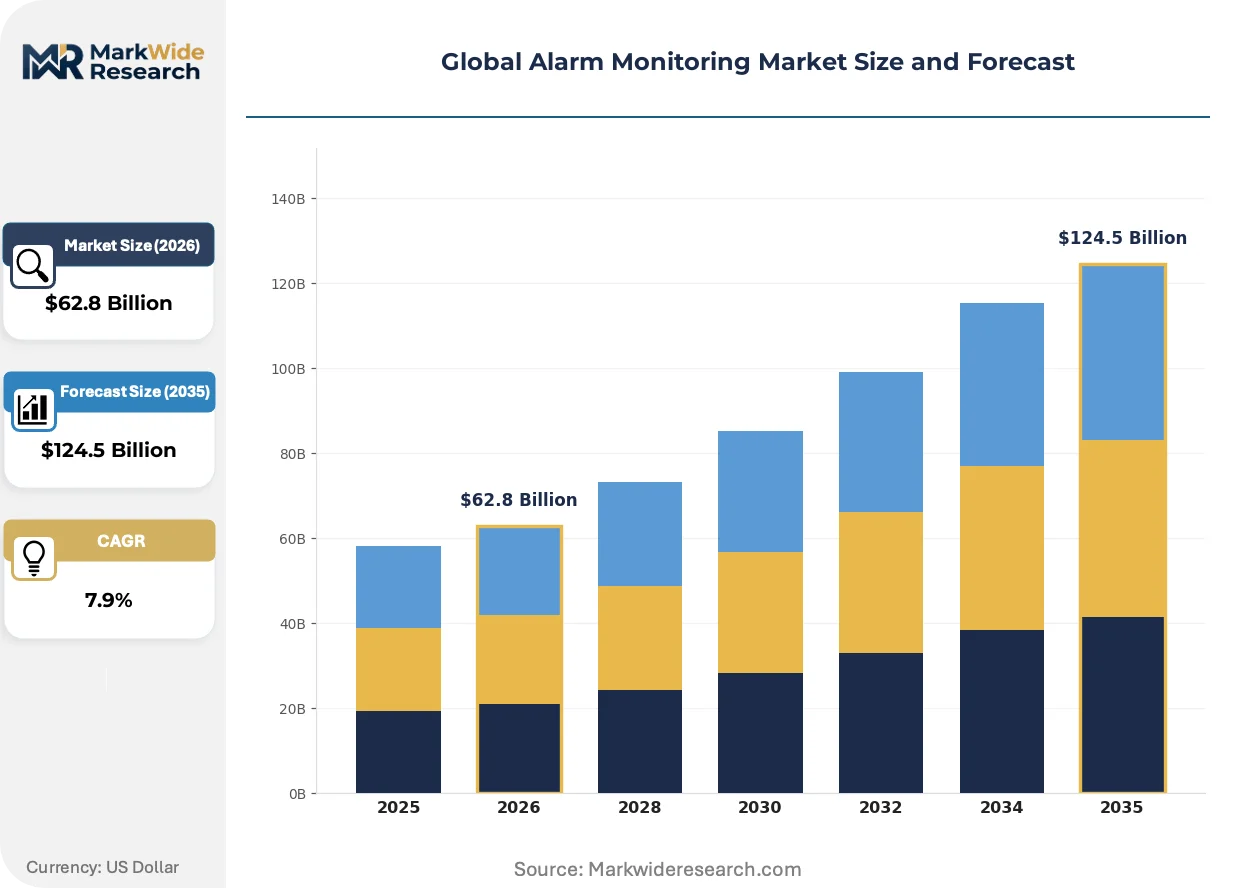
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $124.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Alarm Systems, Intrusion Detection, Video Surveillance, Access Control Technology: Wireless Systems, Wired Systems, Internet of Things, Cloud-Based Solutions End User: Residential, Commercial, Industrial, Government Installation Type: On-site Installations, Remote Monitoring Services, DIY Systems, Professional Services |
| Companies Covered | Honeywell International Inc., ADT Corporation, Johnson Controls International Plc, Siemens AG, ABB Ltd., Schneider Electric SE, Rockwell Automation Inc., Tyco International Plc, Diebold Nixdorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alarm Monitoring Market Shifts & Advancements
Software-defined architectures are decoupling hardware from service delivery, enabling subscription-based monitoring models that scale independently of sensor deployment cycles.
Cloud-native video management systems is overtaking on-premise network video recorders in enterprise deployments. Multi-site retailers and logistics operators are migrating surveillance storage to centralized platforms within eighteen-month windows. This shift is compressing capital equipment sales cycles while expanding recurring software revenue pools for platform providers.
Europe's GDPR and the Cyber Resilience Act are mandating encrypted data flows and breach notification protocols for connected alarm devices. Hardware manufacturers must redesign firmware architectures to satisfy cross-border data constraints. Commercial installations across Germany, France, and the Netherlands are prioritizing EU-hosted cloud instances to maintain compliance.
Facility managers are consolidating vendor relationships under single-source building technology contracts. Traditional alarm monitoring contracts are unbundling from standalone security providers and attaching to HVAC and access control agreements. This pattern is most visible in US Class A office portfolios undergoing ESG-driven operational efficiency overhauls.
Global Alarm Monitoring Market Segmentation
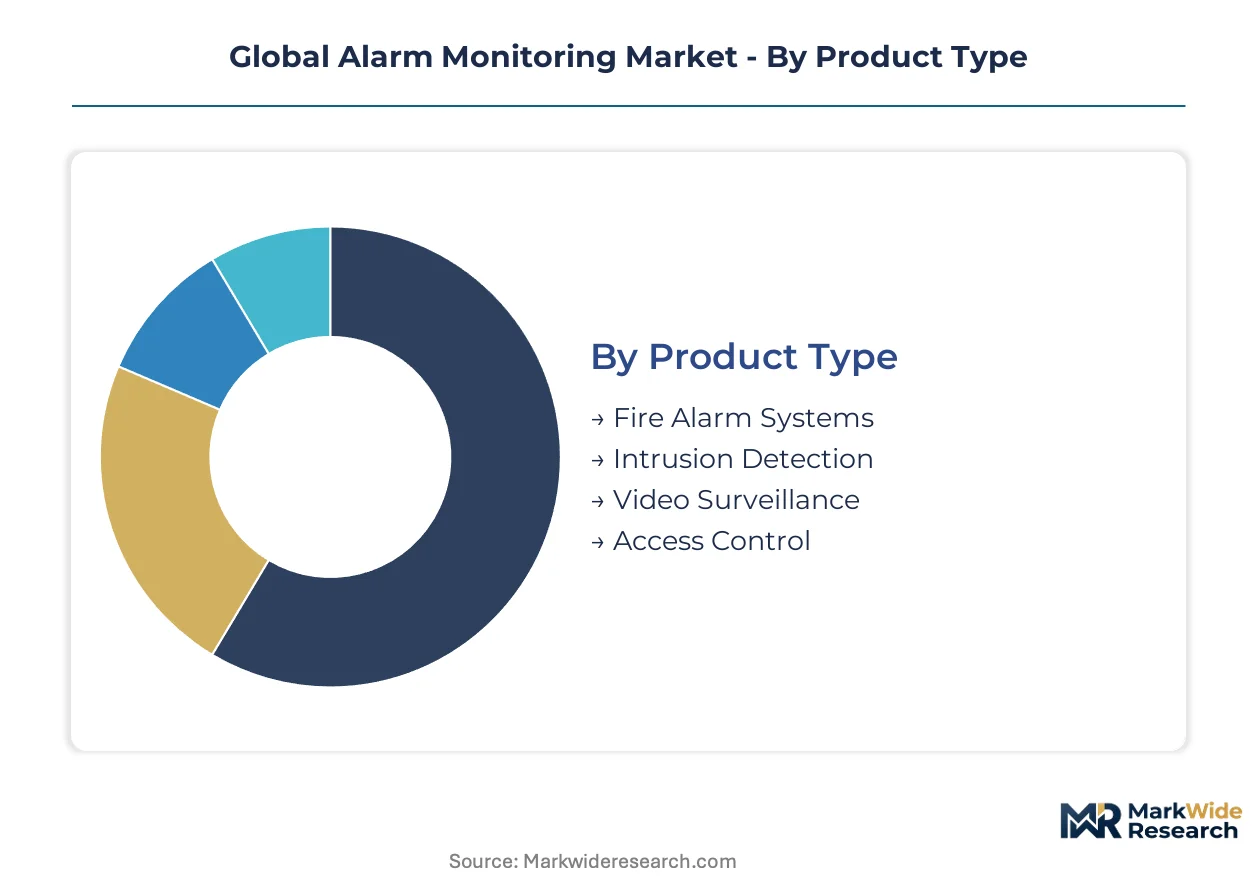
Alarm monitoring markets fragment across hardware, connectivity, and service delivery models. Procurement patterns diverge sharply between integrated building automation contracts and standalone security installations. Understanding these segment boundaries clarifies where vendor consolidation pressures concentrate versus where specialist providers retain pricing power.
Product Type:
Fire alarm systems anchor code-mandated infrastructure with the deepest integration into building management platforms. Video surveillance and intrusion detection operate more often as modular add-ons with shorter replacement cycles.
- Fire Alarm Systems:Hardwired smoke, heat, and gas detection arrays tied to central station monitoring via dedicated signaling paths. Demand clusters in US commercial real estate undergoing insurance-mandated upgrades, with European facilities facing Cyber Resilience Act compliance deadlines for connected detector firmware.
- Intrusion Detection:Perimeter sensors, motion detectors, and glass-break monitors transmitting via cellular or IP pathways. German industrial facilities and US warehousing operations are refreshing legacy panels to meet insurer requirements for continuous professional oversight.
- Video Surveillance:Camera networks with cloud or edge-based analytics for real-time threat verification.
- Access Control:Credential-based entry systems with audit logging and intrusion correlation.
Fire alarm systems lead volumes today; video surveillance is gaining share fastest.
Technology:
Connectivity architecture determines deployment economics across retrofit versus greenfield construction. Wireless and IoT modalities unlock penetration in aging buildings where conduit installation was cost-prohibitive.
- Wireless Systems:Cellular, mesh, and proprietary radio transmitters eliminating structured cabling. US smart building retrofits and Indian commercial expansions favor these for speed of installation, though FCC and TRAI spectrum allocations constrain frequency choices.
- Cloud-Based Solutions:Centralized alarm processing, video storage, and AI analytics delivered via subscription. Multi-site retailers in France and logistics operators in the Netherlands are migrating NVR infrastructure to EU-hosted instances within GDPR-compliant frameworks.
- Wired Systems:Hardwired sensor loops with supervised signaling paths for high-reliability environments.
- Internet of Things:IP-connected sensors enabling predictive maintenance and environmental monitoring beyond security.
Wired systems retain margin leadership in new industrial construction; cloud-based solutions are expanding most quickly.
End User:
Customer scale and regulatory exposure shape service tier selection and contract duration. Residential buyers prioritize monthly cost; commercial and government segments demand uptime guarantees and compliance documentation.
- Commercial:Office, retail, and hospitality portfolios consolidating vendor relationships under integrated building technology contracts. US Class A properties bundle monitoring with HVAC and access control through Johnson Controls and similar full-stack providers.
- Industrial:Manufacturing, warehousing, and energy facilities requiring EMI-tolerant hardwired systems and 24/7 response protocols. German automotive plants and US Gulf Coast petrochemical sites maintain captive monitoring contracts with sub-30-second transmission requirements.
- Residential:Single-family and multi-family dwellings with professional or self-monitoring options.
- Government:Federal, state, and municipal facilities with classified or critical infrastructure designation.
Commercial applications dominate contract value; industrial segments command the steepest pricing premiums.
Installation Type:
Service delivery models are bifurcating between professional integration and consumer-direct channels. This split restructures go-to-market economics and customer lifetime value calculations.
- Remote Monitoring Services:Central station operators receiving alarm signals and dispatching responders. ADT and similar providers anchor recurring revenue through professional installation networks in the US residential base.
- Professional Services:Engineered system design, commissioning, and maintenance contracts. European commercial portfolios favor these for Cyber Resilience Act documentation and GDPR-aligned data handling.
- On-site Installations:Local alarm panels with audible notification and limited off-site connectivity.
- DIY Systems:Self-installed wireless kits with optional professional monitoring subscriptions.
Remote monitoring services capture the largest recurring revenue pools; professional services show the strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates replacement demand through insurance mandates while Germany enforces hardware compliance deadlines; both markets outpace installation growth in emerging economies where wireless retrofits lag regulatory development.
United States
Commercial real estate portfolios bundle monitoring with HVAC and access control contracts. FCC radio frequency allocations govern wireless alarm transmitters nationwide. Class A office properties in Manhattan, Chicago, and Los Angeles consolidate vendor relationships under single-source building technology agreements.
Germany
Industrial facilities require EMI-tolerant hardwired systems with sub-30-second transmission reliability. GDPR and the Cyber Resilience Act mandate encrypted data flows and breach notification protocols for connected devices. Automotive plants in Stuttgart, Wolfsburg, and Munich maintain captive monitoring contracts with 24/7 response guarantees.
India
Commercial expansions favor wireless installation speed over structured cabling costs. BIS certification requirements for electronic safety equipment create compliance hurdles for imported hardware. Mumbai, Bangalore, and Delhi-NCR clusters drive localized production incentives for certified monitoring systems.
France
Multi-site retailers migrate surveillance storage to centralized platforms within compressed timelines. GDPR-aligned data handling requires EU-hosted cloud instances for enterprise deployments. Logistics operators in the Île-de-France and Lyon metropolitan areas prioritize compliant cloud-native video management systems.
Netherlands
Enterprise facilities prioritize EU-hosted cloud instances to maintain cross-border data compliance. ETSI standards constrain radio frequency choices for wireless alarm transmitters. Rotterdam and Amsterdam port complexes drive demand for integrated environmental hazard detection alongside traditional intrusion monitoring.
Global Alarm Monitoring Market Competitive Landscape
North American producers anchor the integrated platform tier; European specialists hold compliance-driven hardware positions. The vendor base structures around three tiers: full-stack building automation providers, professional installation networks, and component manufacturers with captive sensor production. Two dominant competitive moves are reshaping positioning: portfolio bundling that attaches monitoring to HVAC and access control contracts, and backward integration into fire detection hardware that captures margin from sensor manufacturing.
Within the full-stack provider tier, Johnson Controls International Plc and Honeywell International Inc. exemplify archetypes that combine building automation footprints with monitoring service delivery. ADT Corporation occupies a position in the professional installation network segment. These three entities represent distinct strategic postures: integrated platform bundling, in-house hardware production, and recurring revenue models through installation density.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ADT Corporation |
| Johnson Controls International Plc |
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Rockwell Automation Inc. |
| Tyco International Plc |
| Diebold Nixdorf |
| Others |
Supply & Pricing Matrix
Insurance-mandated professional monitoring in US commercial real estate is compressing procurement cycles and forcing supply chains to absorb volume spikes without corresponding price elasticity, tightening margins across hardware tiers.
Pricing Analysis
Capacity additions in China's sensor chip foundries are reshaping price floors for intrusion detection hardware while premium fire alarm systems with Cyber Resilience Act certification maintain pricing power. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified panels from CE-marked mid-tier units and uncertified economy imports. Cost compression in cellular-connected wireless systems is intensifying because LTE module input costs swing with rare earth mineral markets. Residential DIY buyers exhibit highest price sensitivity; German automotive plants with captive monitoring contracts show least.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns for alarm hardware fulfillment. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, exposing monitoring device makers to single-source vulnerability for sensor chips. Raw material dependencies span gallium arsenide for radio modules, lithium for battery backups, and copper for wired system infrastructure. Distribution runs through authorized dealer networks for professional installations and direct-to-consumer channels for wireless DIY kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
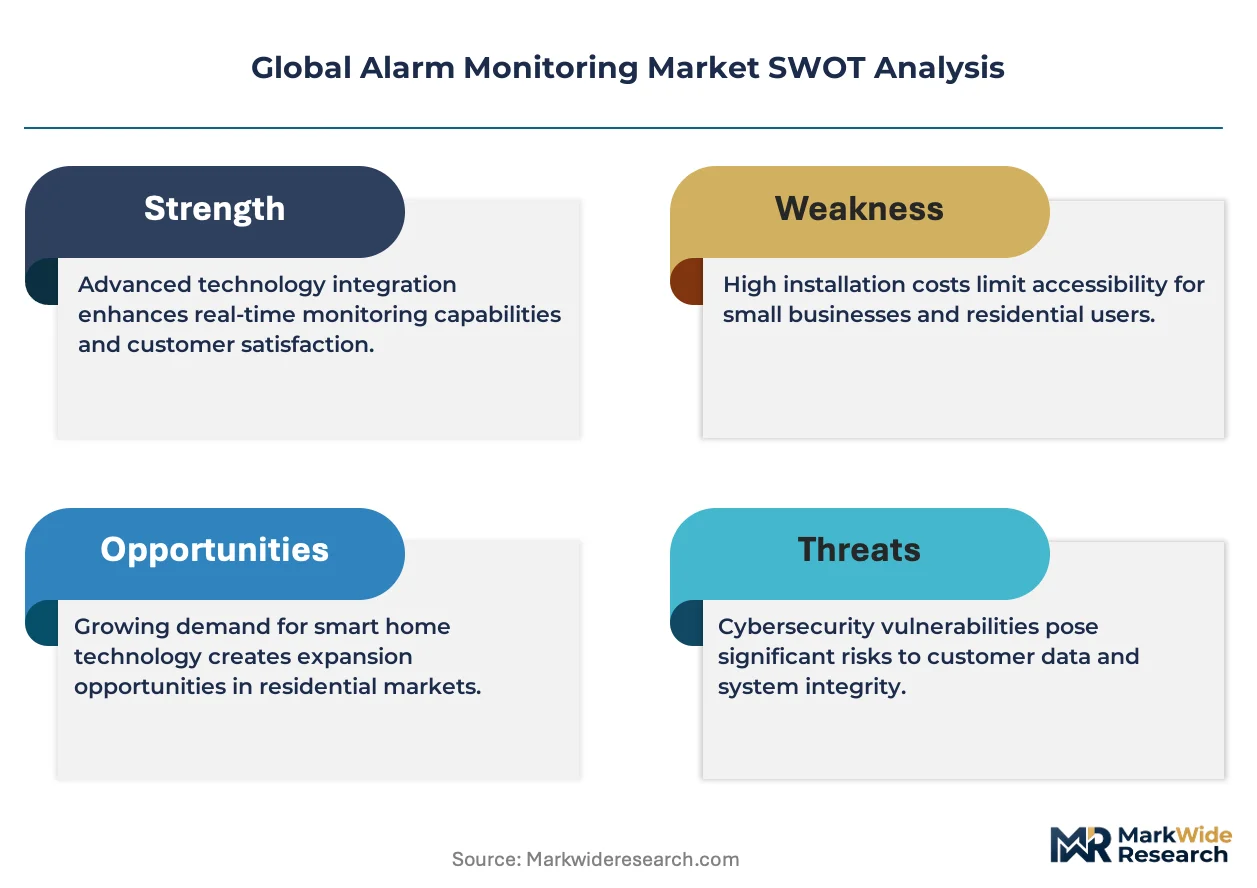
This market reads as a late-cycle quality story where buyer consolidation favors providers with integrated platform capabilities and Cyber Resilience Act compliance documentation commands sustained premiums.
For Market Incumbents: Anchor recurring revenue streams through professional installation network density in US residential segments. Defend against cloud-native entrants by accelerating backward integration into fire detection sensor manufacturing. Invest in EU-hosted cloud infrastructure to capture GDPR-mandated data localization requirements across German and French commercial portfolios.
For New Entrants and Emerging Players: India's BIS certification requirements for electronic safety equipment open a window for localized production partnerships with Mumbai and Bangalore manufacturing clusters. Target wireless retrofit applications in aging US commercial infrastructure where conduit installation costs previously blocked adoption. Pursue white-label AI video verification modules as subscription attach products for existing alarm monitoring platforms.
For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined monitoring architectures that decouple hardware from service delivery. Over a multi-year horizon, providers with captive cloud infrastructure and edge computing capabilities will outcompete hardware-dependent models. Monitor cellular module cost volatility as inflection indicator for wireless system margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling alarm monitoring with HVAC and access control contracts captures US Class A office portfolio consolidation. |
| Regulatory Certification Investment | Cyber Resilience Act compliance documentation unlocks German industrial facility refresh cycles and EU-wide procurement eligibility. |
| Backward Integration into Sensor Manufacturing | In-house fire detection hardware production insulates margins from Taiwan semiconductor supply concentration risks. |
| Cloud Infrastructure Localization | EU-hosted instances satisfy GDPR cross-border data constraints for French multi-site retail and Dutch logistics operators. |
| AI Video Verification Development | Machine learning-augmented cloud analytics expand subscription revenue beyond traditional alarm response services. |
Research Methodology
Direct dialogue with central station operators, building automation procurement directors, fire safety compliance officers, and IoT platform engineers grounded qualitative findings in operational reality. Secondary validation drew from FCC spectrum allocation filings, ETSI standards documentation, BIS certification registries, and EU Cyber Resilience Act implementation guidance. Bottom-up sensor deployment estimates triangulated against top-down building automation contract value analysis.
Segment-level outputs across hardware, connectivity, and service delivery models were generated through projection horizon modeling incorporating technology substitution rates, regulatory compliance deadlines, and insurance mandate adoption curves. CAGRs were derived from installation base growth, replacement cycle compression, and average revenue per user expansion across residential, commercial, and industrial end-use segments. Forecast inputs included cellular module cost indices, cloud storage pricing trajectories, and semiconductor foundry capacity utilization.
Revisions become necessary when geopolitical disruption affects East Asian sensor chip supply, when rare earth mineral markets spike cellular module input costs, or when GDPR enforcement actions redirect cloud infrastructure investment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Container Security Market
Security and Surveillance
Alarm Monitoring [Central Stations] Software Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Middle East Manned Security Services Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Residential Security Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Specialized Threat Analysis and Protection Market