
 Intelligent Fencing Market | 2026-2036
Intelligent Fencing Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Fencing Market Foresight
Direct-to-installer distribution is reshaping how intelligent fencing reaches end users in fragmented rural and industrial markets. Gallagher Group leverages its vertically integrated manufacturing to control supply chains across Australasia. Betafence dominates European industrial perimeter contracts through specialized anti-climb mesh systems with embedded fiber-optic detection. SensorTec positions its cloud-connected sensor arrays for North American critical infrastructure buyers seeking remote monitoring capabilities.
Intelligent fencing encompasses electrified, wireless, and sensor-integrated barrier systems engineered to detect, deter, and communicate perimeter breaches through real-time data transmission, typically operating at 5,000–9,500 volts in electrified configurations with pulse intervals under one second. These systems serve commercial, agricultural, and conservation applications by replacing passive barriers with active threat-response architectures. Electric fencing occupies the largest installed base due to mature agricultural demand, while wireless fencing registers the fastest expansion as battery and mesh-network technologies reduce trenching costs. GPS tracking technology leads R&D investment, though sensor integration captures widening margin pools through recurring software subscriptions.
The EU AI Act and CE marking frameworks govern automated threat-classification algorithms in European installations, while the US FAA and FCC regulate aerial drone detection and radio-frequency emissions for wireless mesh nodes. India's BIS standards and the PLI scheme for electronics manufacturing are accelerating local assembly of smart gate controllers and alarm systems. Stakeholders must monitor divergence between EU algorithmic transparency requirements and US sector-specific critical infrastructure rules when designing unified product platforms.
Market Dynamics
Electrification voltage standards and sensor fusion architectures are converging to redefine perimeter security economics, compressing installation timelines while expanding addressable use cases beyond traditional agriculture into critical infrastructure and renewable energy sites.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential electrification components are accelerating R&D into solid-state pulse generators and recyclable composite insulators across European manufacturing.
- Utility-scale solar deployment:Data center campuses and photovoltaic installations in the United States require intelligent perimeter detection with integrated thermal and seismic sensors for 24/7 unmanned operation.
- Mesh-network protocols:Battery-operated wireless nodes with sub-GHz LoRaWAN connectivity are eliminating trenching costs for temporary fencing at mining and construction sites.
Market Restraints
- Copper and rare-earth volatility:Conductor cable and neodymium magnet costs for pulse transformers fluctuate with commodity markets, squeezing margin on electrified systems.
- Single-source sensor dependency:Fiber-optic strain gauges and distributed acoustic sensing modules concentrate among three specialized photonics suppliers in Germany and Japan.
- Legacy 12-volt compatibility:Agricultural buyers in emerging markets resist upgrading from conventional battery energizers despite superior pulse efficiency in modern kilovolt systems.
Strategic Opportunities
- India PLI scheme for electronics:Local assembly incentives for smart gate controllers and GSM alarm modules reduce import duties and enable cost-competitive domestic production.
- Drone-detection convergence:Integration of RF spectrum analyzers with physical fencing creates bundled perimeter-airspace security for airports and correctional facilities.
- Subscription telemetry services:Cloud-based breach analytics and predictive maintenance portals generate recurring revenue from hardware installations previously sold as one-time capital expenditure.
Industry Challenges
- Embedded systems firmware certification:CE marking under the EU AI Act requires algorithmic transparency documentation for automated threat-classification modules, extending product launch timelines.
- Field technician scarcity:Installation and calibration of fiber-optic tension sensors demands specialized photonics training unavailable in rural service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Fencing Market |
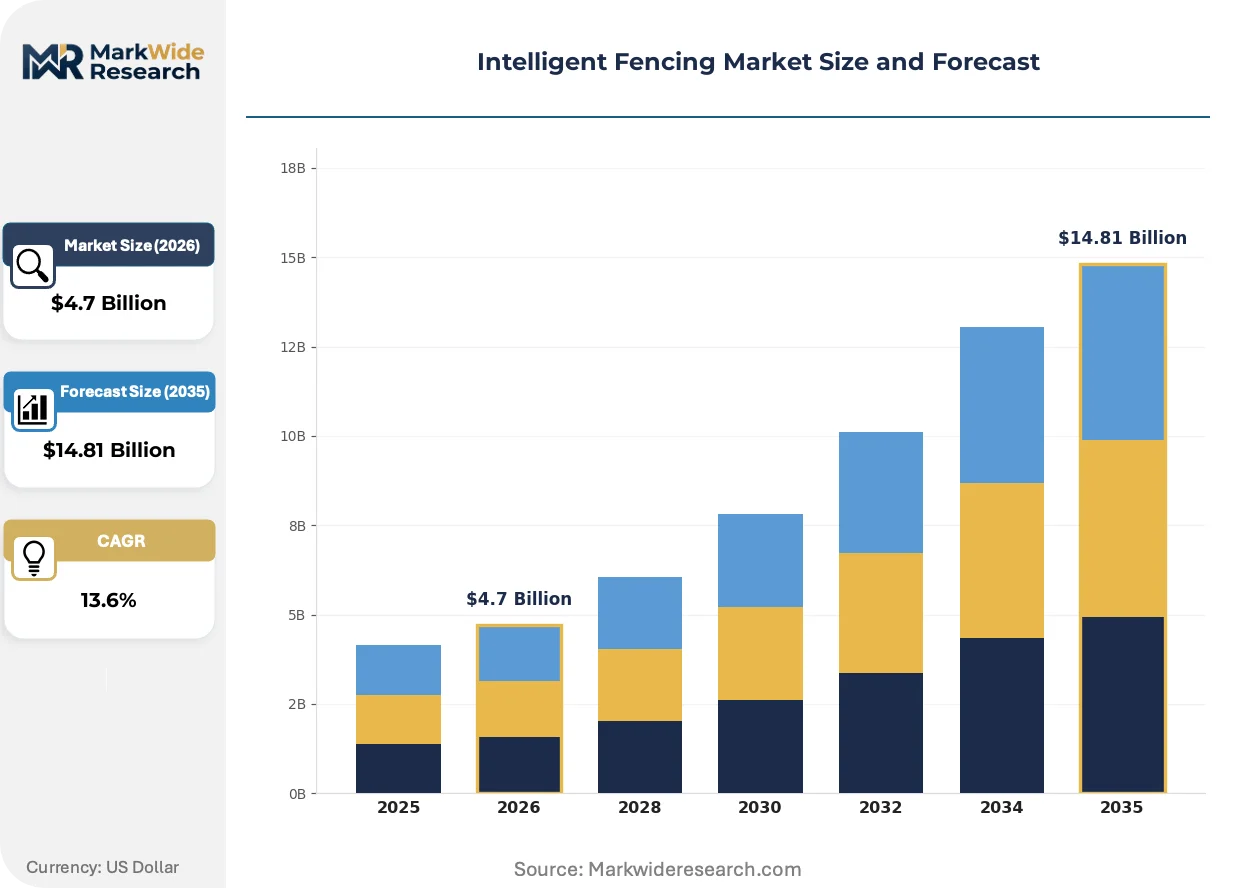
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Fencing, Wireless Fencing, Smart Gate, Alarm Systems Technology: GPS Tracking, Remote Monitoring, Sensor Integration, Cloud Computing Application: Residential Security, Agricultural Protection, Industrial Perimeters, Wildlife Management End User: Homeowners, Farmers, Corporations, Conservationists |
| Companies Covered | Smart Fence Integrated Security, Long Fence, Gallagher Group, Assa Abloy Group, CertainTeed, SensorTec, Tru-test Group, Praesidiad Group Limited, Betafence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Fencing Market Shifts & Advancements
Active perimeter systems are absorbing capabilities from adjacent security and IoT domains, eroding distinctions between physical barriers, surveillance networks, and access control platforms.
Pulse-modulated energizers are migrating from fixed-output transformers to adaptive load-matching circuits that adjust voltage delivery based on vegetation contact and soil moisture. Solar farm operators in California and Texas are specifying these units to maintain consistent detection thresholds across seasonal ground condition variations. The technology is migrating from agricultural commodity sales toward engineered system procurement with integrated SCADA compatibility.
The EU AI Act's risk-classification framework for automated decision-making is forcing manufacturers to document training data provenance and algorithmic bias testing for video-analytics-enabled fencing. Industrial perimeter contracts now require third-party conformity assessment for threat-detection accuracy rates. European critical infrastructure buyers are prioritizing vendors with established notified body relationships over lower-cost uncertified alternatives.
Direct procurement from installer networks is consolidating purchasing power among regional electrical contractors who previously bought through distribution. These contractors now specify system configurations and negotiate volume pricing directly with manufacturers, bypassing traditional security equipment wholesalers. The pattern is most pronounced in the United States, where national integrators serving data center and logistics campus clients have established preferred vendor programs with exclusive territory arrangements.
Intelligent Fencing Market Segmentation
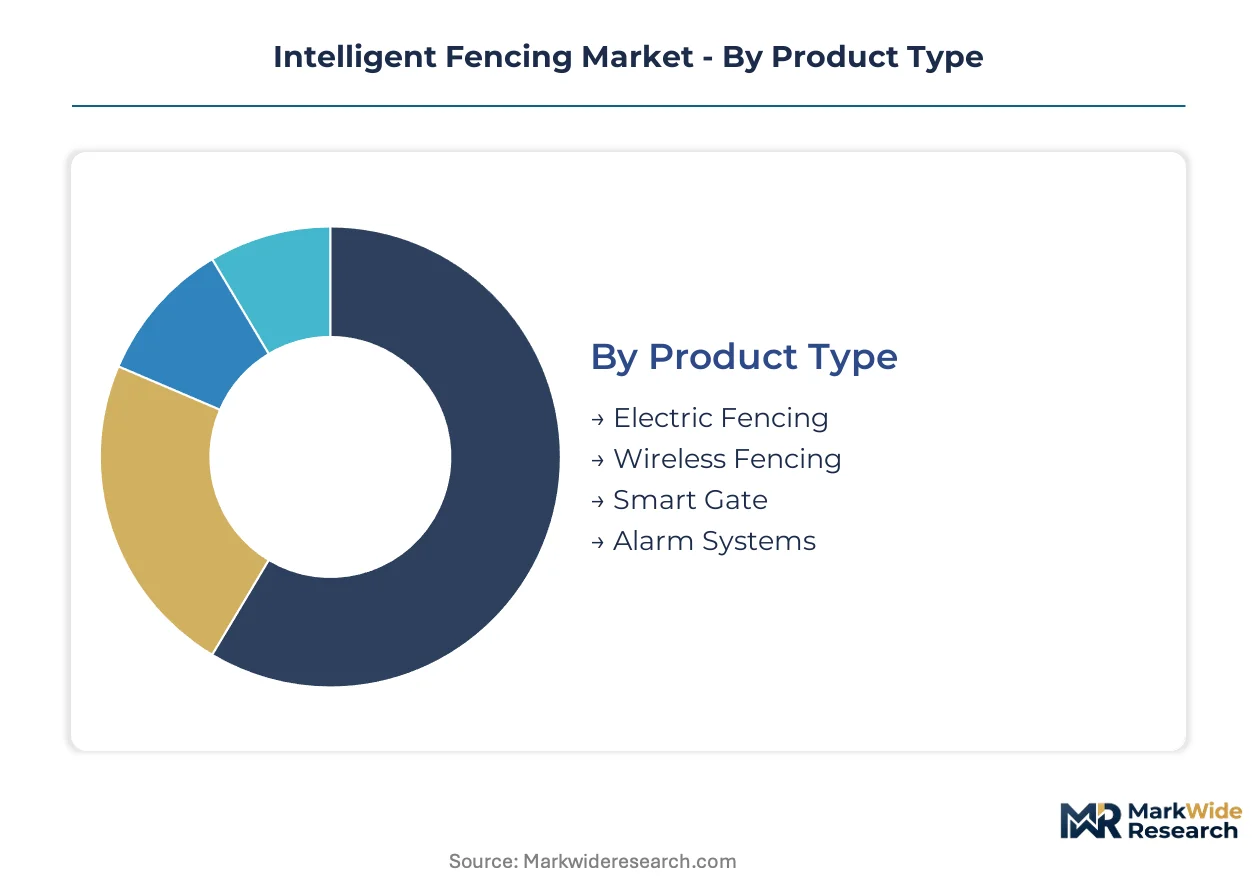
Segmentation in intelligent fencing reveals divergent equipment lifecycles and replacement patterns across product architectures. Agricultural electrification operates on decade-long refresh cycles while wireless sensor networks demand continuous firmware and battery upgrades. Understanding these temporal patterns enables manufacturers to align R&D pipelines and service revenue models with actual field replacement behavior.
Product Type:
Replacement velocity varies dramatically across physical versus connected architectures, with electrified hardware enduring longest in field conditions while wireless nodes face obsolescence pressure from protocol evolution.
- Electric Fencing:Pulse-energized conductor systems operating at 5,000–9,500 volts with ceramic or composite insulators dominate agricultural installations across Australia and New Zealand. Farmers prioritize voltage consistency and vegetation tolerance over connectivity features, extending replacement cycles to 12–15 years in pastoral regions.
- Wireless Fencing:Battery-operated mesh nodes using sub-GHz LoRaWAN protocols eliminate trenching costs for temporary mining and construction perimeters. California solar farm operators specify these systems for rapid deployment alongside photovoltaic arrays, though battery replacement cycles compress total cost of ownership calculations.
- Smart Gate:Motorized access controllers with GSM alarm integration serve remote agricultural properties lacking fixed-line connectivity. India's PLI scheme for electronics manufacturing is accelerating local assembly of these controllers to reduce import duties.
- Alarm Systems:Perimeter breach notification hardware with cloud telemetry links to central monitoring stations. European industrial buyers under EU AI Act requirements now demand third-party conformity assessment for automated threat-classification accuracy.
Electric fencing dominates installed base. Wireless fencing is where expansion concentrates.
Technology:
Development investment clusters around positioning accuracy and data transmission reliability, with hardware-software integration determining margin capture potential.
- GPS Tracking:Satellite-based livestock and asset location systems with geofencing capabilities command premium pricing in extensive grazing operations. New Zealand sheep stations deploy these for mustering efficiency across rugged terrain where physical fencing proves uneconomical.
- Remote Monitoring:Cellular and satellite telemetry enabling unmanned perimeter oversight from centralized security operations. United States data center campuses require these capabilities for 24/7 unmanned operation with integrated thermal and seismic sensor feeds.
- Sensor Integration:Fiber-optic strain gauges and distributed acoustic sensing modules embedded in physical barriers. German and Japanese photonics suppliers concentrate production of these specialized components, creating supply vulnerability.
- Cloud Computing:Subscription-based breach analytics and predictive maintenance portals converting capital expenditure into recurring revenue. Predictive algorithms for vegetation contact detection are migrating from on-premise SCADA to SaaS architectures.
Sensor integration commands highest R&D allocation. Cloud computing is climbing the fastest as manufacturers pursue recurring revenue models.
Application:
Site-specific environmental and regulatory conditions dictate technology selection, with critical infrastructure commanding engineered specifications while agricultural buyers prioritize proven reliability.
- Residential Security:Low-voltage electrified and wireless perimeter systems for single-family properties. Australian suburban developments increasingly specify these for bushfire-prone interface zones where traditional barriers face combustion risk.
- Agricultural Protection:Livestock containment and predator exclusion across extensive pastoral operations. EU F-Gas Regulation mandates are pushing European manufacturers toward solid-state pulse generators and recyclable composite insulators in this segment.
- Industrial Perimeters:Anti-climb mesh with embedded detection for manufacturing, logistics, and energy facilities. Betafence dominates European contracts through specialized fiber-optic detection integration meeting CE marking requirements.
- Wildlife Management:Species-specific barrier configurations for conservation and human-wildlife conflict mitigation. Conservationists in Southern Africa deploy these alongside GPS tracking for elephant corridor management.
Agricultural protection anchors volume demand. Industrial perimeters is gaining share fastest through critical infrastructure procurement.
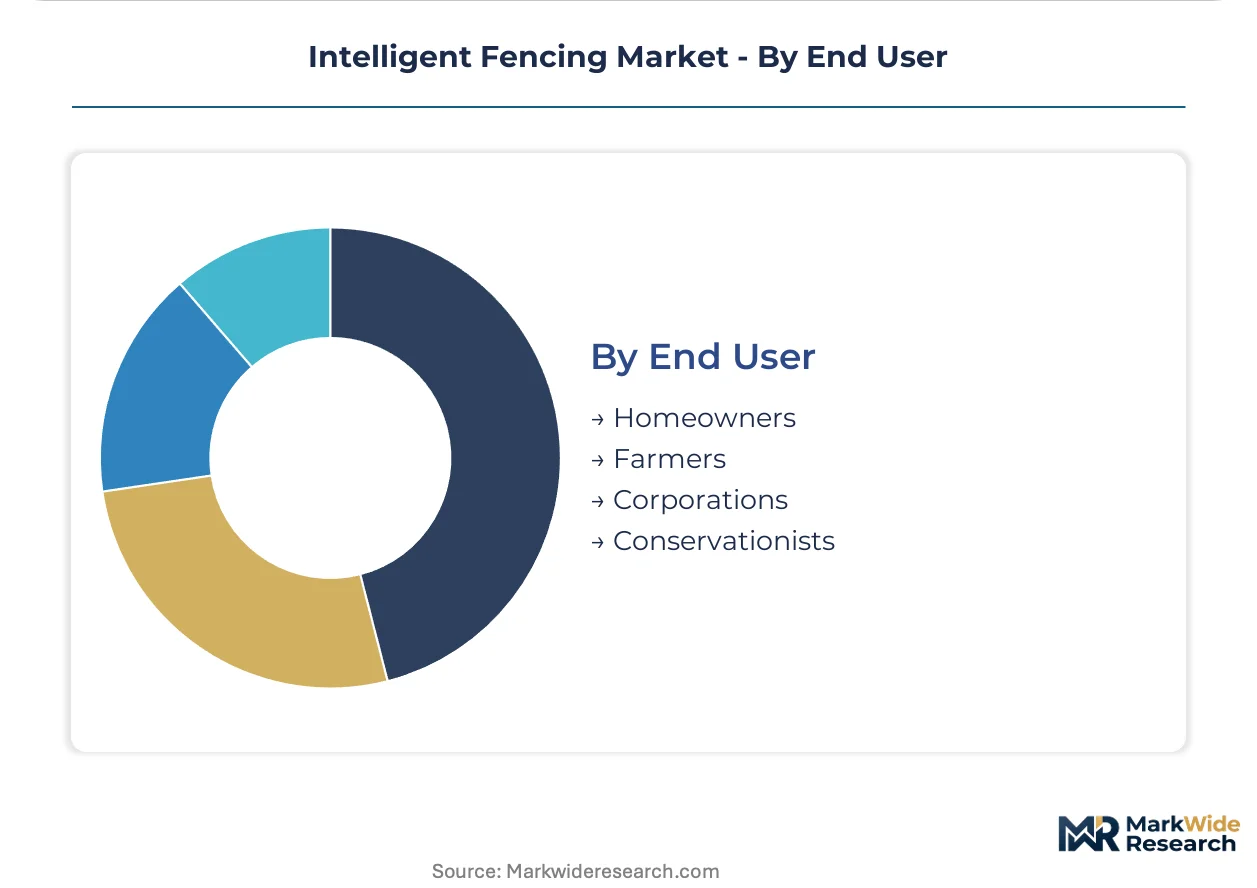
End User:
Purchasing sophistication and total cost sensitivity separate consumer-grade from enterprise procurement, with farmers occupying a hybrid position requiring durability at constrained capital budgets.
- Homeowners:Retail-channel electrified and wireless kits with DIY installation. Direct-to-installer distribution is consolidating purchasing power among regional electrical contractors who now specify configurations directly with manufacturers.
- Farmers:Agricultural electrification buyers resisting upgrade from legacy 12-volt battery energizers despite superior pulse efficiency in modern kilovolt systems. Gallagher Group's vertically integrated manufacturing controls supply chains across Australasia for this customer base.
- Corporations:Enterprise procurement of integrated perimeter-airspace security bundles. United States national integrators serving data center and logistics campus clients have established preferred vendor programs with exclusive territory arrangements.
- Conservationists:Non-governmental and governmental wildlife management agencies prioritizing non-lethal barrier effectiveness. SensorTec positions cloud-connected sensor arrays for these buyers seeking remote monitoring of protected area boundaries.
Farmers represent the largest installed base. Corporations is where procurement sophistication and bundled solution demand concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation mandates and India's PLI scheme for electronics manufacturing are redrawing procurement geographies for intelligent perimeter systems. Agricultural automation in Australia and New Zealand accelerates sensor-integrated fencing adoption. Critical infrastructure protection in the United States concentrates demand for unmanned perimeter detection.
United States
Utility-scale solar farms in California and Texas require intelligent perimeter detection with integrated thermal and seismic sensors for 24/7 unmanned operation. FAA and FCC regulations govern aerial drone detection and radio-frequency emissions for wireless mesh nodes. National integrators serving data center and logistics campus clients in Northern Virginia and Phoenix have established preferred vendor programs with exclusive territory arrangements.
Germany
Industrial perimeter contracts demand specialized anti-climb mesh systems with embedded fiber-optic detection meeting CE marking requirements. EU AI Act risk-classification frameworks force manufacturers to document training data provenance and algorithmic bias testing for video-analytics-enabled fencing. Manufacturing clusters in Bavaria and North Rhine-Westphalia concentrate photonics suppliers producing distributed acoustic sensing modules.
India
Remote agricultural properties lacking fixed-line connectivity drive demand for motorized access controllers with GSM alarm integration. BIS standards and the PLI scheme for electronics manufacturing accelerate local assembly of smart gate controllers to reduce import duties. Industrial corridors in Gujarat and Maharashtra host emerging domestic production of alarm systems and pulse energizers.
Australia
Extensive pastoral operations prioritize voltage consistency and vegetation tolerance in pulse-energized conductor systems across New South Wales and Queensland. Gallagher Group leverages vertically integrated manufacturing to control supply chains across Australasia for livestock containment applications. Bushfire-prone interface zones in Victoria increasingly specify low-voltage electrified perimeters where traditional barriers face combustion risk.
Japan
Specialized photonics suppliers concentrate production of fiber-optic strain gauges and distributed acoustic sensing modules for embedded barrier detection. METI industrial standards and JIS certification requirements govern pulse transformer efficiency and insulator material specifications. Manufacturing clusters in the Chubu region around Nagoya supply critical sensor components to European and North American system integrators.
Intelligent Fencing Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers and specialized photonics suppliers with captive component production. Three strategic archetypes dominate: agricultural electrification specialists with decades-long brand recognition in pastoral markets, industrial perimeter contractors bundling physical barriers with detection analytics, and sensor-technology firms converting hardware sales into recurring telemetry subscriptions. Competitive moves concentrate on backward integration into pulse transformer manufacturing and strategic partnerships with cloud infrastructure providers for breach-analytics hosting.
Among the named participants, Gallagher Group exemplifies the agricultural-electrification archetype through its Australasia supply chain control, while Betafence occupies a position representing European industrial perimeter specialization. SensorTec anchors the sensor-technology tier pursuing cloud-connected subscription models for critical infrastructure buyers.
| Leading Market Players |
|---|
| Smart Fence Integrated Security |
| Long Fence |
| Gallagher Group |
| Assa Abloy Group |
| CertainTeed |
| SensorTec |
| Tru-test Group |
| Praesidiad Group Limited |
| Betafence |
| Others |
Supply & Pricing Matrix
Photonics suppliers in Germany and Japan concentrate production of fiber-optic strain gauges and distributed acoustic sensing modules, anchoring margin capture in the sensor-integration tier where European industrial buyers pay premiums for CE-marked threat-classification accuracy.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified industrial systems with EU AI Act conformity documentation from agricultural commodity energizers and DIY residential kits. Price differentiation hinges on algorithmic transparency certification and volume scale, with national integrators commanding double-digit discounts through preferred vendor programs. Cost compression in the agricultural tier is intensifying because farmers resist upgrading from legacy 12-volt battery energizers. Corporate procurement teams show least price sensitivity, while smallholder farmers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Copper conductor cable and neodymium magnet feedstock for pulse transformers sources from Chilean mining operations and Chinese rare-earth processing facilities, with ceramic insulator substrates drawing from Japanese materials science suppliers. The supply chain rests on single-source photonics components from German and Japanese specialists, creating tariff exposure as EU-Japan trade terms evolve. Distribution runs through direct-to-installer channels consolidating purchasing power among regional electrical contractors bypassing traditional security wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
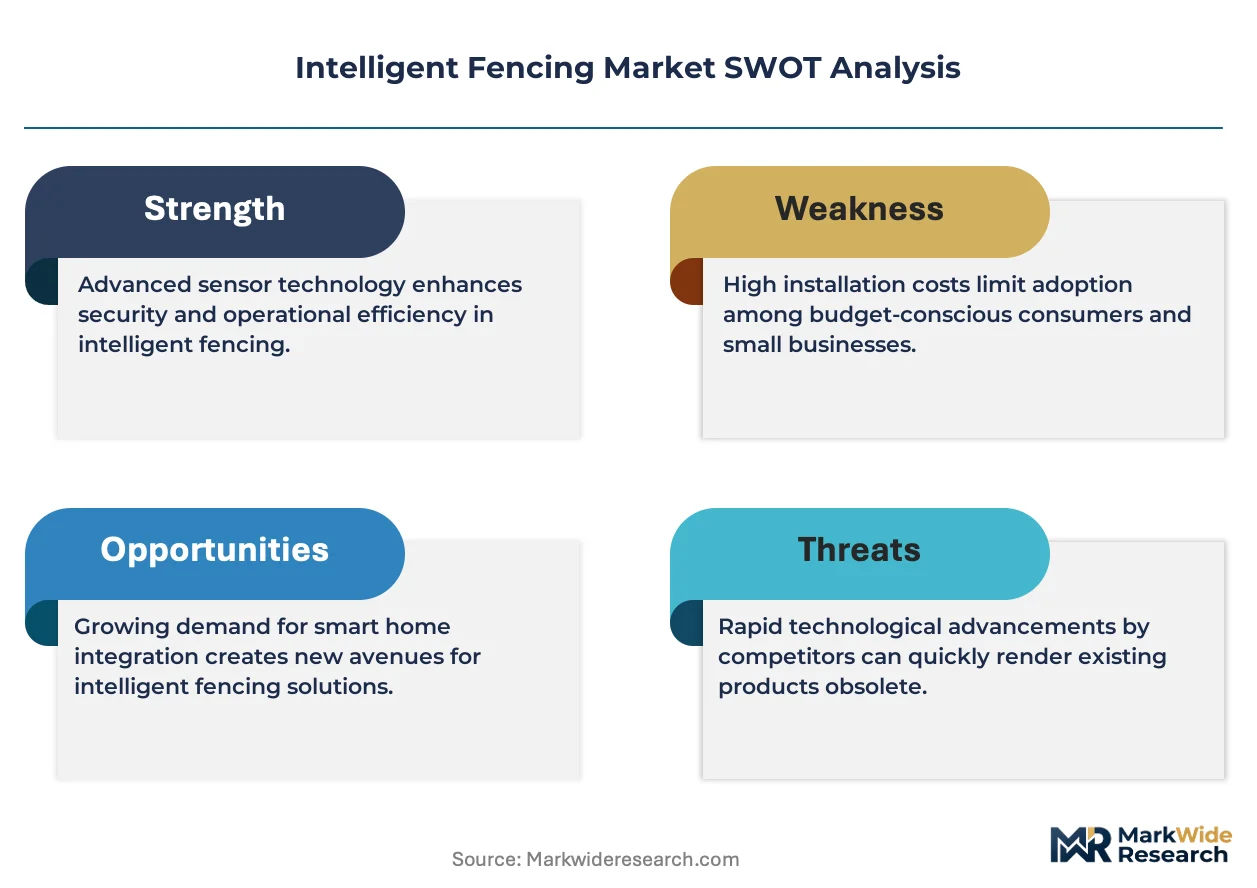
Intelligent fencing functions as a defensive-moat industry where regulatory entrenchment through CE marking and EU AI Act conformity requirements creates durable switching costs for certified vendors.
For Market Incumbents: Build algorithmic transparency documentation as a regulatory moat by securing notified body relationships before EU AI Act enforcement tightens. Backward integration into pulse transformer manufacturing reduces copper and rare-earth magnet cost volatility. Channel control through exclusive territory arrangements with national integrators defends against emerging sensor-technology firms converting hardware sales to subscription telemetry. For New Entrants and Emerging Players: Build out drone-detection convergence capabilities for airport and correctional facility bundles where RF spectrum analyzer integration with physical fencing remains underpenetrated. India's PLI scheme for electronics manufacturing offers the most penetrable geography for smart gate controller assembly with reduced import duties. A direct-to-installer go-to-market angle bypasses entrenched security equipment wholesalers in fragmented rural markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed agricultural electrification specialists possessing decades-long brand recognition in Australasian pastoral markets but lacking cloud-connected subscription revenue models. Long-term viability favors vendors with recurring telemetry services converting capital expenditure into SaaS architectures. Watch for consolidation signals when fiber-optic sensor suppliers face acquisition interest from industrial perimeter contractors seeking captive component supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Transformers | Captive supply of neodymium magnet components insulates margin from Chinese rare-earth price volatility. |
| EU AI Act Conformity Investment | Third-party algorithmic transparency certification unlocks European critical infrastructure procurement channels. |
| Drone-Detection Convergence Development | RF spectrum analyzer bundling with physical barriers addresses FAA-regulated airport perimeter-airspace security demand. |
| Direct-to-Installer Channel Expansion | Bypassing traditional security wholesalers captures purchasing power from consolidating regional electrical contractors. |
| Subscription Telemetry Service Launch | Cloud-based breach analytics convert one-time hardware sales into recurring revenue from data center campus clients. |
Research Methodology
Initial hypotheses were tested against primary input from perimeter security system engineers, agricultural electrification distributors, fiber-optic sensor procurement leads, and critical infrastructure facility managers and refined through secondary validation against SEC filings from listed security equipment manufacturers, EU CE marking databases, Indian PLI scheme beneficiary registries, and customs trade data for copper conductor and rare-earth magnet imports. Bottom-up unit economics for electrified, wireless, and sensor-integrated installations were triangulated against top-down market sizing from national agricultural census data and critical infrastructure investment disclosures.
Demand-supply-balance framing across the analysis window modeled product type segmentation by replacement velocity, technology tier by R&D investment intensity, application by site-specific regulatory requirements, and end user by procurement sophistication. CAGRs were derived from installed base growth rates adjusted for technology obsolescence patterns in wireless mesh protocols and firmware upgrade cycles. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and India's PLI scheme localization incentives.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native sensor-technology firms or state-subsidized Chinese electrification manufacturers would shift outcomes beyond modeled ranges. Cross-checking against utility-scale solar farm procurement databases and data center campus security RFP filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Cargo Container X-Ray Inspection Systems Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Security Inspection Market
Security and Surveillance
Speed Limit Radar Signs Market