
 Full Body Scanner Market | 2026-2036
Full Body Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Full Body Scanner Market Intelligence
Leasing and performance-based contracting is rewriting capital deployment across the full body scanner sector. Smiths Detection leverages its service infrastructure to anchor long-term airport contracts. L3Harris Technologies sustains R&D intensity in millimeter-wave architectures. Nuctech Company Limited dominates price-competitive tenders across emerging aviation hubs.
A full body scanner is a non-invasive screening system that detects objects concealed beneath clothing using electromagnetic radiation in the millimeter-wave or X-ray spectrum, typically operating at frequencies between 24 GHz and 300 GHz with resolution sufficient to distinguish metallic and non-metallic threats. The device serves primary commercial purpose in high-throughput security environments where manual pat-downs create operational bottlenecks. Millimeter-wave systems lead installed base in civil aviation due to privacy-compliant avatar-based output, while backscatter technology occupies specialized contraband detection roles in correctional institutions. Computed tomography represents the fastest-growing technology segment as three-dimensional bag-and-body integration schemes advance.
TSA certification requirements and EASA security equipment standards shape product development roadmaps, forcing manufacturers to reconcile detection sensitivity with false-alarm thresholds. The EU AI Act and GDPR provisions on biometric processing constrain automated threat-recognition algorithms in European deployments. Stakeholders must monitor evolving interoperability standards between scanner networks and centralized passenger-data systems.
Market Dynamics
Millimeter-wave imaging systems are compressing deployment timelines across aviation security infrastructure as TSA mandates accelerate replacement of legacy metal-detection-only checkpoints.
Growth Catalysts
- Aviation Security Mandates:TSA directives in the United States and EASA equipment standards in Europe are compelling airport operators to upgrade to automated screening lanes capable of detecting non-metallic threats.
- Privacy-Compliant Imaging:Avatar-based output technology eliminates human-viewed raw imagery, resolving civil liberties objections that previously stalled procurement in European Union member states.
- Throughput Economics:Automated screening lanes at high-volume hubs reduce passenger processing time by eliminating manual secondary screening for low-risk travelers.
Market Restraints
- Capital Intensity:Millimeter-wave scanner units require substantial upfront investment, constraining adoption at secondary airports and regional aviation facilities with limited security budgets.
- Supply Concentration:Critical radio-frequency components and specialized antenna arrays source predominantly from limited semiconductor fabrication facilities in East Asia, creating vulnerability to supply disruptions.
- Regulatory Fragmentation:Divergent certification requirements between TSA, EASA, and national aviation authorities force manufacturers to maintain multiple product variants, elevating compliance costs.
Strategic Opportunities
- Correctional Facility Expansion:Backscatter technology applications in prison contraband detection remain underpenetrated across state and federal correctional systems in the United States.
- Computed Tomography Integration:Three-dimensional bag-and-body screening convergence creates white space for unified checkpoint architectures that combine passenger and carry-on screening.
- Performance-Based Contracting:Availability-fee and throughput-guarantee models shift capital burden from airport operators to equipment vendors and system integrators.
Industry Challenges
- Algorithm Training Data Scarcity:Threat-recognition machine learning systems require extensive datasets of concealed prohibited items, which security agencies restrict for operational sensitivity reasons.
- Legacy System Interoperability:New millimeter-wave deployments must integrate with existing centralized passenger-data systems and security operations centers without disrupting real-time throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Full Body Scanner Market |
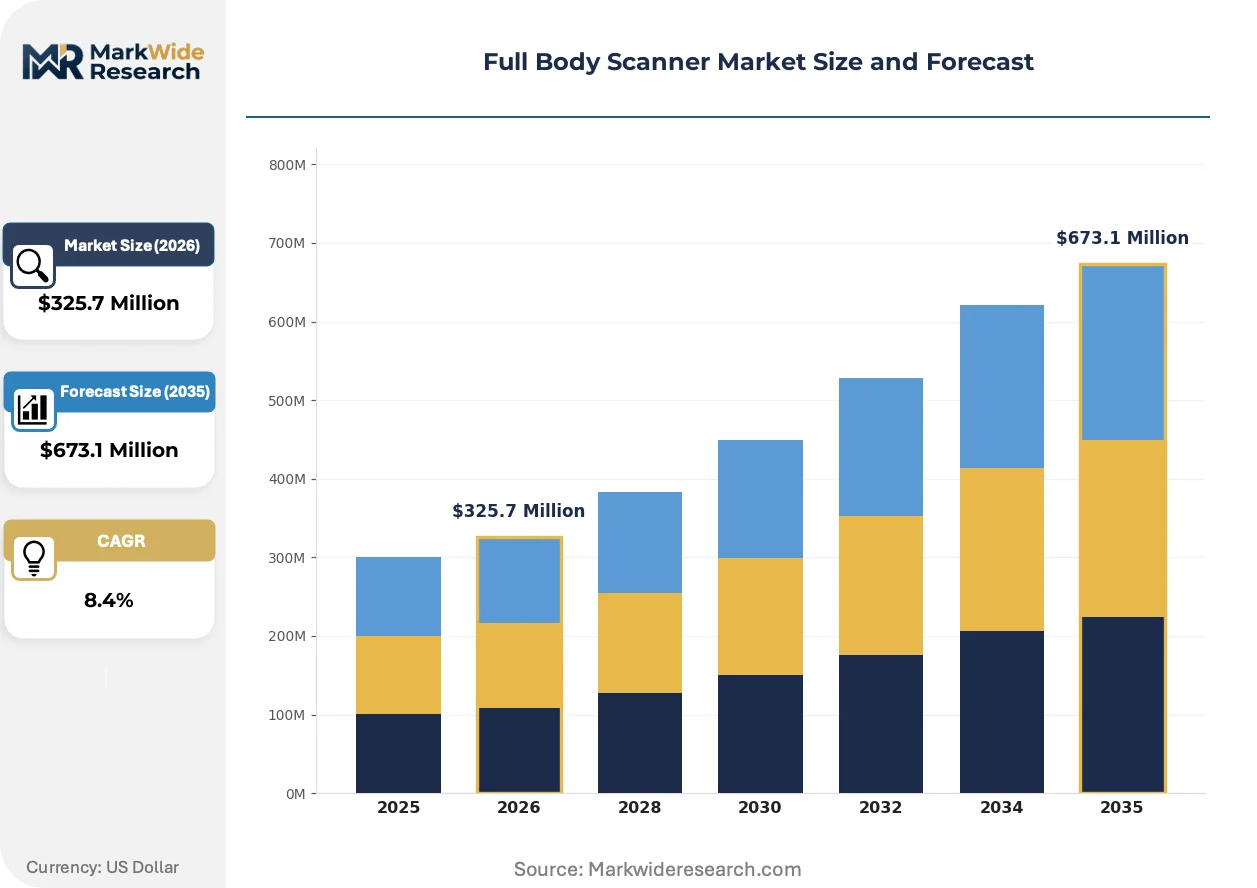
| Market Size in 2026 | $325.7 Million |
| Market Size in 2035 | $673.1 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backscatter, Millimeter Wave, X-ray, Terahertz Technology: Computed Tomography, Electromagnetic Imaging, Infrared, Ultrasound Application: Security Screening, Contraband Detection, Hazardous Material Identification, Quality Assurance End User: Airports, Correctional Institutions, Event Management, Border Control |
| Companies Covered | OSI Systems, Smiths Detection, Leidos Security Detection & Automation, Nuctech Company Limited, LINEV Systems, L3Harris Technologies, Rapiscan Systems, OD Security, Tek84, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Full Body Scanner Market Strategic Shifts & Innovations
Checkpoint architectures are converging around software-defined detection systems that separate hardware infrastructure from threat-recognition algorithms, enabling continuous capability upgrades without physical replacement cycles.
Passive millimeter-wave imaging arrays are virtualizing the traditional active-scanning paradigm by eliminating mechanical rotation components and enabling continuous, walk-through screening without passenger positioning delays. Airport operators in the United States and Germany are piloting these systems at sterile area entry points. This technology is virtualizing the distinction between primary and secondary screening tiers, collapsing checkpoint footprints while maintaining detection sensitivity.
The EU AI Act's risk-classification framework for biometric processing is forcing manufacturers to rearchitect automated threat-recognition algorithms deployed at European Union airports. Systems must now demonstrate human-in-the-loop decision protocols and algorithmic transparency documentation to achieve operational clearance. Civil aviation deployments in France, Germany, and the Netherlands are experiencing delayed certification timelines as vendors adapt software stacks to these requirements.
Airport operators are unbundling after-sales service from equipment purchase contracts, creating standalone performance-guarantee agreements with specialized maintenance providers. This shift fragments the traditional single-vendor relationship and introduces third-party service competition into previously captive revenue streams. The trend is most visible at major hub airports in the United States and United Kingdom, where procurement teams prioritize operational uptime commitments over manufacturer loyalty.
Full Body Scanner Market Segmentation
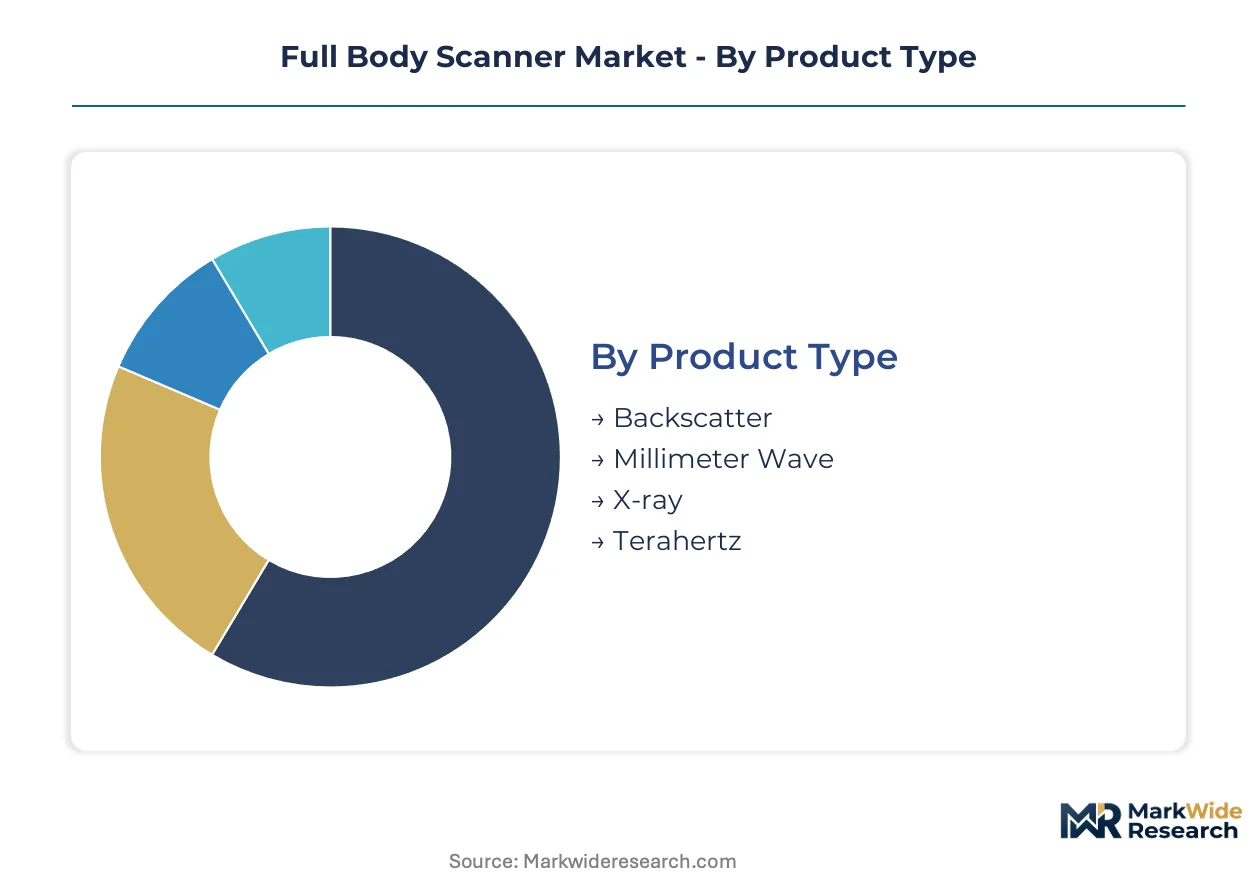
Full body scanner procurement patterns diverge sharply across deployment contexts, with aviation security demanding high-throughput millimeter-wave architectures while correctional facilities prioritize compact backscatter units for contraband interdiction. Technology selection hinges on regulatory certification scope, privacy compliance thresholds, and integration complexity with existing security infrastructure.
Product Type:
Deployment contexts span from high-volume passenger screening to confined-space contraband detection, each imposing distinct hardware specifications and operational protocols.
- Millimeter Wave:Active systems transmit low-power electromagnetic signals between 24 GHz and 300 GHz, generating three-dimensional surface maps for threat detection without ionizing radiation. Civil aviation authorities in the United States and Germany mandate these systems for primary screening lanes due to avatar-based privacy outputs that eliminate human-reviewed imagery. Demand concentrates at hub airports where TSA certification and EASA equipment standards converge on throughput-optimized automated lanes.
- Backscatter:Low-dose X-ray systems detect anomalies beneath clothing by measuring reflected radiation, producing high-resolution images suitable for dense contraband identification. State and federal correctional facilities in the United States deploy these units at visitor entry points where detection of synthetic narcotics and small metallic objects outweighs privacy concerns. Procurement accelerates where manual pat-downs create security bottlenecks during high-traffic intake periods.
- X-ray:Transmission-based systems penetrate deeper tissue layers for comprehensive concealed-object detection, primarily serving customs and border control applications where threat diversity exceeds standard aviation profiles.
- Terahertz:Emerging spectral imaging operating between microwave and infrared frequencies enables non-metallic threat differentiation with minimal health risk, gaining pilot traction at sterile area checkpoints in German airports.
Established volume favors Millimeter Wave; emerging adoption favors Terahertz.
Technology:
Detection architectures separate into volumetric reconstruction methods and surface imaging modalities, with software-defined upgrade paths increasingly determining procurement longevity.
- Computed Tomography:Three-dimensional reconstruction algorithms process multiple angular projections to resolve overlapping objects in complex concealment scenarios. Aviation security integrators in France and the Netherlands pilot these systems for unified passenger-and-baggage screening schemes that collapse checkpoint footprints. The EU AI Act's algorithmic transparency requirements are delaying certification timelines as vendors rearchitect threat-recognition protocols for human-in-the-loop compliance.
- Electromagnetic Imaging:Millimeter-wave and microwave arrays generate real-time surface topology maps without mechanical scanning components. Passive array configurations eliminate passenger positioning delays, enabling continuous walk-through screening at sterile area entry points in United States hub airports.
- Infrared:Thermal contrast detection identifies temperature anomalies associated with concealed objects, serving secondary screening roles where primary systems flag ambiguous signatures.
- Ultrasound:Acoustic impedance mapping penetrates fabric barriers for non-metallic threat identification, occupying niche applications in event security where radiation-emitting technologies face deployment restrictions.
Electromagnetic Imaging commands current installed base; Computed Tomography climbs the fastest as integration architectures mature.
Application:
Functional requirements range from high-throughput passenger processing to targeted contraband interdiction, each segment imposing distinct false-alarm tolerance and detection depth specifications.
- Security Screening:Primary checkpoint applications demand sub-10-second processing cycles with automated threat classification to maintain passenger flow at high-volume aviation facilities. TSA mandates in the United States and EASA standards in Europe compel millimeter-wave adoption for non-metallic threat detection.
- Contraband Detection:Correctional and customs applications prioritize detection depth over throughput, utilizing backscatter and transmission X-ray systems to identify synthetic narcotics, weapons, and communication devices concealed against the body or within body cavities.
- Hazardous Material Identification:Spectroscopic extensions to standard imaging platforms enable chemical composition analysis for radiological and explosive material detection at border crossings.
- Quality Assurance:Industrial applications verify personnel contamination control in semiconductor and pharmaceutical manufacturing environments where particulate exclusion is critical.
Security Screening dominates procurement volume; Contraband Detection offers steepest expansion trajectory in underpenetrated correctional systems.
End User:
Customer procurement authority fragments across federal agencies, municipal operators, and private venue managers, each with distinct budget cycles and certification requirements.
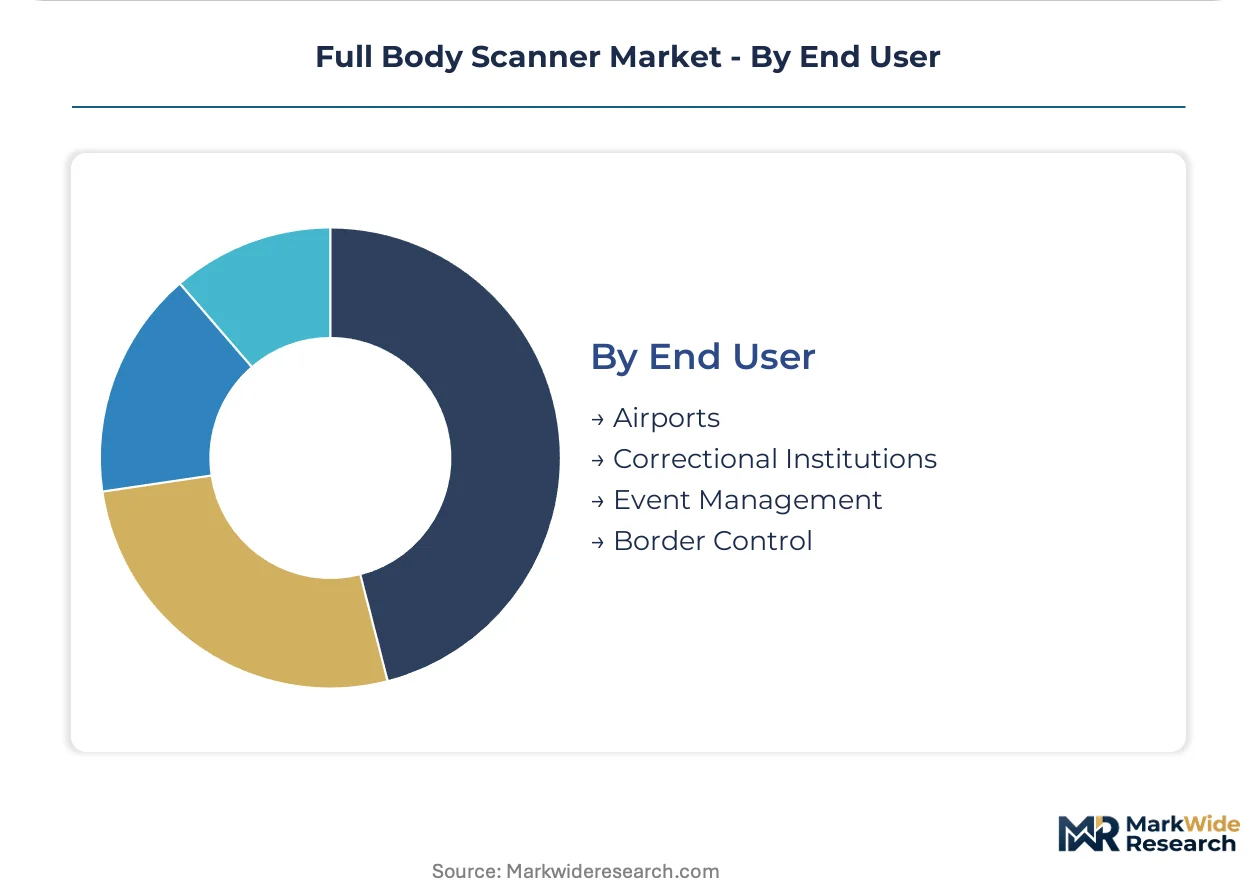
- Airports:Hub operators in the United States, Germany, and the United Kingdom drive millimeter-wave procurement through automated screening lane investments that reduce labor costs and passenger processing times. Performance-based contracting models shift capital burden to vendors through availability-fee structures.
- Correctional Institutions:State and federal prison systems in the United States represent underpenetrated demand for compact backscatter units at visitor screening checkpoints, with procurement constrained by capital budgets relative to aviation counterparts.
- Event Management:Stadium and arena operators deploy portable millimeter-wave systems for temporary high-threat events, prioritizing rapid deployment over integration depth.
- Border Control:Customs agencies require multi-modal detection platforms capable of simultaneous personnel and vehicle screening at land crossing points.
Airports anchor revenue concentration; Correctional Institutions present the fastest-climbing adoption curve as security budgets reallocate toward contraband interdiction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows concentrate in millimeter-wave scanner systems shipped from US and German manufacturing bases to aviation authorities across the Middle East and Asia-Pacific, while import dependency for specialized radio-frequency components creates supply vulnerability concentrated in East Asian semiconductor fabrication facilities.
United States
TSA mandates for automated screening lane deployment at hub airports drive procurement of millimeter-wave systems, with the FAA coordinating certification standards for aviation security equipment. OD Security and Tek84 anchor domestic manufacturing clusters in California and Massachusetts, supplying correctional facilities and event security operators with compact backscatter units.
Germany
EASA equipment standards and GDPR privacy compliance requirements shape demand for avatar-based imaging systems that eliminate human-reviewed raw imagery. The EU AI Act's algorithmic transparency provisions are delaying certification timelines as vendors adapt software stacks. LINEV Systems exemplifies the Baden-Württemberg industrial concentration around precision electromagnetic imaging hardware.
China
Domestic aviation expansion at secondary airports creates price-sensitive demand for millimeter-wave screening infrastructure, with procurement patterns favoring local certification under national aviation authority standards. Nuctech Company Limited anchors manufacturing capacity in Beijing and Shenzhen, exporting to emerging aviation hubs across Southeast Asia and Africa.
United Kingdom
Heathrow and Gatwick hub operators prioritize performance-based contracting models that shift capital burden to vendors through availability-fee structures. Smiths Detection maintains service infrastructure concentrated in London and the Southeast, anchoring long-term maintenance agreements independent of equipment purchase contracts.
United Arab Emirates
Dubai International Airport and Abu Dhabi Zayed International Airport drive premium-tier procurement for unified checkpoint architectures integrating passenger and baggage screening. MOHAP and federal aviation regulators mandate alignment with EASA-equivalent certification standards, attracting European and US system integrators to establish regional service operations in Dubai.
Full Body Scanner Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: full-system integrators with certified aviation security portfolios, specialized component suppliers for radio-frequency arrays, and regional service providers capturing fragmented maintenance contracts. Archetypes separate between premium-tier vendors with TSA and EASA dual certification, mid-tier price competitors dominating emerging market tenders, and niche specialists in correctional contraband detection. Dominant competitive moves include performance-based contracting that shifts capital burden from operators to vendors, and vertical integration into after-sales service to capture recurring revenue streams.
Among US-based defense and security conglomerates, L3Harris Technologies and Leidos Security Detection & Automation occupy positions exemplifying the premium-system integrator archetype, while Smiths Detection anchors the European full-service tier with its UK-based service infrastructure. Nuctech Company Limited represents the price-competitive export-oriented archetype, with its Chinese corporate structure reflecting manufacturing-scale positioning in emerging aviation markets.
| Leading Market Players |
|---|
| OSI Systems |
| Smiths Detection |
| Leidos Security Detection & Automation |
| Nuctech Company Limited |
| LINEV Systems |
| L3Harris Technologies |
| Rapiscan Systems |
| OD Security |
| Tek84 |
| Others |
Cost & Logistics Intelligence
Beijing and Shenzhen manufacturing clusters anchor global millimeter-wave scanner production capacity, with Nuctech's integrated fabrication facilities translating scale economics into pricing leverage at emerging aviation hubs across Southeast Asia and Africa. This geographic concentration of radio-frequency component output creates asymmetric power dynamics between upstream antenna array suppliers and downstream system integrators competing for TSA-certified contracts.
Pricing Analysis
Aviation procurement officers anchor pricing stratification across premium, standard, and economy tiers differentiated by TSA certification status and after-sales service bundling. Premium-tier vendors command substantial markups for dual-certified architectures meeting both FAA coordination standards and EASA equipment mandates, while price erosion runs through economy-tier tenders at secondary airports where national aviation authority certification suffices. Correctional facility buyers exhibit highest price sensitivity due to capital budget constraints relative to hub airport operators.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculus for radio-frequency semiconductor sourcing, with specialized antenna arrays and millimeter-wave transceivers drawing predominantly from Taiwanese and South Korean fabrication facilities. Gallium arsenide substrates and high-frequency printed circuit boards feed from limited East Asian suppliers, creating single-source vulnerability for critical detection hardware. Distribution runs through authorized system integrators with TSA certification credentials, bypassing direct OEM relationships at major hub deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs formidable defensive moats in this market, as TSA certification timelines and EASA equipment standards create switching costs that lock airport operators into established vendor relationships spanning decade-long service agreements.
For Market Incumbents: Insulate certified installed bases through performance-based contracting models that shift capital burden onto operators while capturing recurring availability-fee revenue streams. Deepen in-house production of radio-frequency components to reduce exposure to East Asian semiconductor supply disruptions. Prioritize R&D investment in passive millimeter-wave arrays that eliminate mechanical rotation components and compress competitor entry timelines. For New Entrants and Emerging Players: Establish a beachhead in underpenetrated state correctional systems where backscatter technology demand outpaces supply from incumbent aviation-focused vendors. Target compact contraband detection units for visitor screening checkpoints at federal prison facilities, where procurement cycles operate independently of TSA certification requirements. Lead with rapid-deployment portable systems for event security operators seeking temporary screening infrastructure without long-term integration obligations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-integrated vendors with captive maintenance networks spanning multiple airport hubs, as performance-guarantee agreements fragment traditional single-vendor relationships and create standalone contract value. Acquisition targets should display certified aviation security portfolios with demonstrated EASA compliance trajectories. Monitor EU AI Act algorithmic transparency implementation timelines as inflection indicators for European deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Adoption | Shifts capital burden from airport operators to vendors through availability-fee structures at Heathrow and Gatwick. |
| Passive Millimeter-Wave Array Development | Eliminates mechanical rotation components and enables continuous walk-through screening at sterile area entry points. |
| EU AI Act Compliance Investment | Delays certification timelines for automated threat-recognition algorithms requiring human-in-the-loop protocols. |
| Correctional Facility Market Entry | Captures underpenetrated demand for compact backscatter units at state and federal prison visitor checkpoints. |
| Unified Checkpoint Architecture Integration | Combines passenger and carry-on screening through computed tomography convergence at French and Dutch pilot sites. |
Research Approach
Initial hypotheses were tested against primary input from airport procurement directors, TSA certification engineers, correctional facility security administrators, and millimeter-wave hardware R&D leads, then refined through secondary validation against FAA coordination standards documentation, EASA equipment certification filings, and customs trade data for radio-frequency component flows. Bottom-up unit economics triangulated against top-down aviation security budget allocations across major hub operators.
Demand-supply balance modeling segmented the market by product type, technology architecture, application context, and end-user procurement authority, with CAGRs derived from regression analysis of historical deployment timelines and projected mandate compliance deadlines. Forecast inputs incorporated TSA automated screening lane deployment directives, EASA equipment standard revision schedules, and EU AI Act algorithmic transparency implementation trajectories across the analysis window.
Sensitivities concentrate around semiconductor supply disruption scenarios, regulatory certification timeline extensions, and shifting procurement preferences toward performance-based contracting. Forecasts reflect documented assumptions regarding mandate enforcement consistency and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Airport Baggage Screening Systems Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Integrated Security Solutions Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Baggage Scanner Market
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
Airport Security Market
Security and Surveillance
Private Security Market
Security and Surveillance
Sirens Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Commercial Security Market