
 Global Magic Wall Interactive Surface Market | 2026-2036
Global Magic Wall Interactive Surface Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magic Wall Interactive Surface Market Intelligence
Expanded manufacturing capacity in Taiwan and China for large-format display panels is tilting the supply chain dynamics for interactive surfaces. Samsung Electronics leverages its in-house display production to offer integrated solutions. SMART Technologies specializes in the education sector with its purpose-built digital whiteboards. Meanwhile, Planar Systems competes on high-specification video walls for corporate and event applications.
A magic wall interactive surface is a large-format display system that allows users to interact with digital content through touch or gestures. These systems integrate technologies like infrared or capacitive touch sensors to enable multi-user collaboration and dynamic presentations. Within technology segments, capacitive touch holds a dominant share in smaller panels, while laser projection is gaining traction for large-scale interactive exhibits. Demand from corporate presentations and education & training applications continues to outpace other uses.
Product compliance is governed by a matrix of regional electronics standards, including CE marking in Europe and FCC regulations in the United States. In China, adherence to GB standards for electronic displays is mandatory for market access. Stakeholders must now decide whether to prioritize hardware interoperability or develop proprietary, closed-ecosystem software to capture long-term value.
Market Dynamics
The transition from touch-based inputs to gesture-controlled interfaces is the central force shaping product development. This evolution compels vendors to invest heavily in sensor fusion and software algorithms to deliver intuitive multi-user experiences on large-format displays.
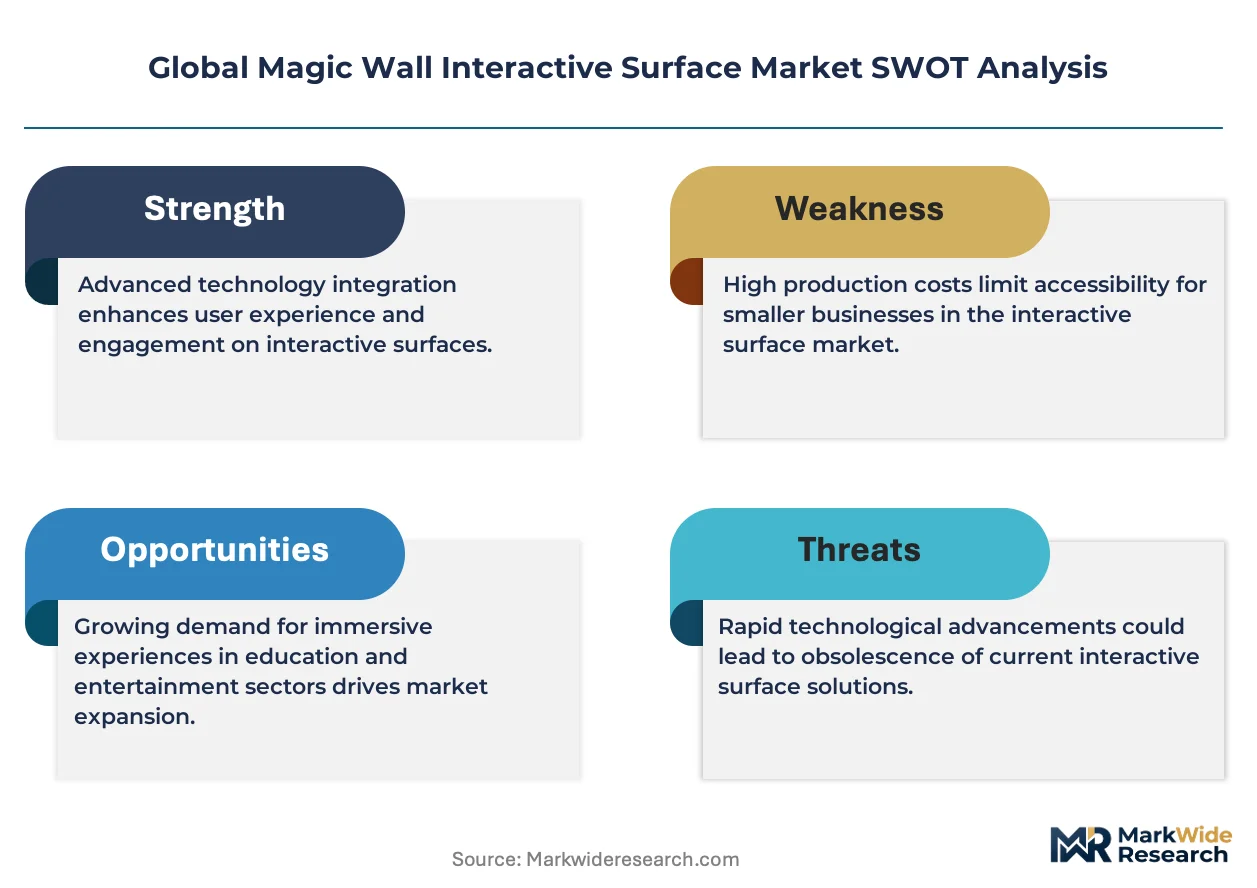
Growth Catalysts
- Corporate Presentations:Demand for more dynamic and collaborative meeting tools in corporate environments is a primary catalyst, replacing static projectors and whiteboards with interactive surfaces for brainstorming and data visualization.
- Gesture-Based Interfaces:The technological shift away from traditional touch interfaces toward more intuitive gesture-based control is accelerating product innovation and expanding the potential for multi-user interaction.
- Technology Clusters:Concentrated demand from advanced technology clusters, particularly in and around Seoul, South Korea, creates a significant pull for high-performance interactive displays in research and corporate settings.
Market Restraints
- High Capital Cost:The significant initial investment required for large-format, high-resolution interactive surfaces presents a substantial barrier to adoption for small and medium-sized enterprises and educational institutions with limited budgets.
- Integration Complexity:Difficulties in integrating magic wall systems with diverse legacy IT infrastructure, proprietary enterprise software, and existing network security protocols can delay or prevent implementation.
- Supply Chain Dependency:The market's reliance on a concentrated group of large-format display panel manufacturers, primarily based in Taiwan and China, creates vulnerability to supply disruptions and price volatility.
Strategic Opportunities
- Interactive Exhibits:There is a significant opportunity in developing systems for large-scale interactive exhibits in public spaces such as museums, galleries, and science centers, offering immersive educational experiences.
- AI-Powered Analytics:Integrating artificial intelligence and machine learning can unlock new capabilities, such as analyzing user interaction patterns to optimize content or enabling predictive, context-aware user interfaces.
- Education Sector Expansion:Targeting the education and training sector with purpose-built, cost-effective digital whiteboards and collaborative learning surfaces represents a major avenue for market expansion.
Industry Challenges
- Fragmented Compliance Standards:Manufacturers face the operational challenge of navigating a complex matrix of regional electronics standards, including CE marking in Europe, FCC rules in the US, and GB standards in China.
- Software Ecosystem Strategy:A core strategic challenge is the decision between promoting hardware interoperability through open standards or developing proprietary software ecosystems to create a competitive moat and capture recurring revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magic Wall Interactive Surface Market |
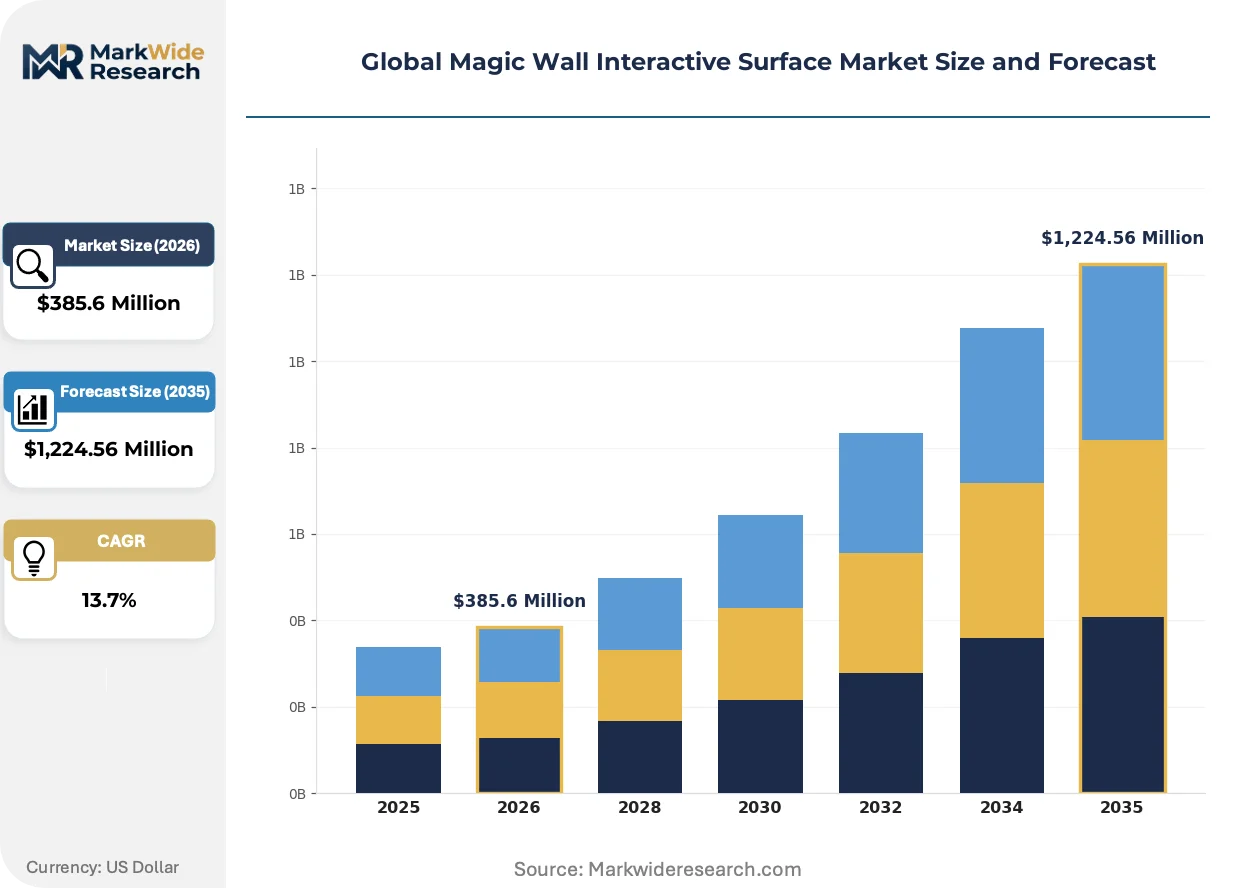
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,224.56 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Magic Wall, Fixed Magic Wall, Touch-Enabled Panels, Gesture-Based Surfaces, Digital Whiteboards Technology: Infrared, Capacitive Touch, Optical Sensors, Ultrasonic Tracking, Laser Projection Application: Education & Training, Corporate Presentations, Event Management, Indoor Advertising, Interactive Exhibits End User: Educational Institutions, Corporate Offices, Museums & Galleries, Retail Outlets, Event Organizers |
| Companies Covered | Microsoft Corporation, Samsung Electronics, LG Electronics, Google LLC, Panasonic Corporation, Sony Corporation, Planar Systems, SMART Technologies, ViewSonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magic Wall Interactive Surface Market Strategic Shifts & Innovations
Interactive surface development is moving beyond hardware specifications toward software-defined user experiences. The primary tension now resides in balancing open-platform interoperability with the value capture potential of proprietary software ecosystems, a choice that dictates long-term competitive positioning.
Gesture and Projection Integration
Laser projection technology enables interactivity on vast or irregularly shaped surfaces where traditional panels are impractical. Museums and large event producers are adopting this for creating immersive, room-scale exhibits. This technology is hybridizing the static nature of video walls with the dynamic flexibility of projection mapping, opening new creative application categories.
Regulatory Compliance as a Differentiator
European Union directives for CE marking, including the RoHS regulation restricting hazardous substances, mandate stringent component-level compliance for all electronic displays. This forces global manufacturers to manage complex supply chain documentation and validation processes to access the EU market. The corporate sector, driven by internal sustainability goals, increasingly favors suppliers who can demonstrate full compliance.
Shift to Ecosystem-Based Procurement
Enterprise customers are shifting their purchasing criteria from raw hardware performance to the quality and integration capabilities of the accompanying software ecosystem. This change diminishes the role of hardware-focused resellers, favoring vendors who provide subscription-based software updates and support. The trend is most visible in the corporate vertical, where compatibility with existing collaboration platforms is a primary purchasing criterion.
Global Magic Wall Interactive Surface Market Segmentation
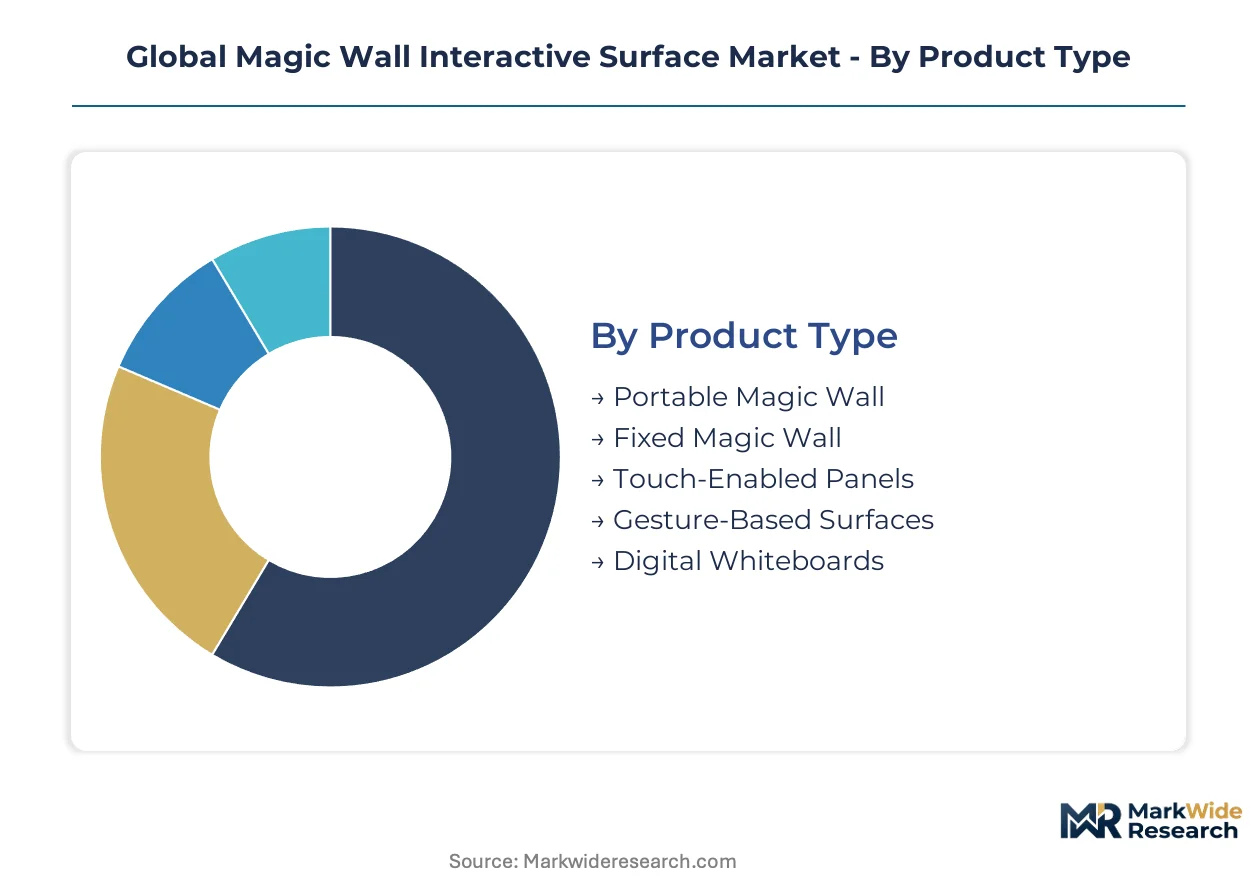
The segmentation of the global magic wall interactive surface market reveals distinct product characteristics and diverse end-user requirements. Understanding these segments is crucial for manufacturers to tailor solutions and for stakeholders to identify specific growth avenues. This detailed analysis highlights the technological nuances and application landscapes driving market evolution.
Product Type:
The after-sales-service intensity varies significantly across product types, with complex installations requiring extensive support and maintenance contracts.
- Fixed Magic Wall:These are permanently installed, large-format display systems integrated into architectural designs, often requiring professional installation and calibration. Demand concentrates in corporate boardrooms and public venues, driven by the need for robust, high-impact visual communication.
- Gesture-Based Surfaces:These advanced systems allow interaction without physical touch, utilizing optical sensors or cameras for user input. Technology clusters in South Korea show significant demand for these innovative interfaces, accelerating product innovation for multi-user experiences.
- Portable Magic Wall:Mobile interactive displays designed for temporary setups or flexible use in various locations.
- Touch-Enabled Panels:Displays that rely on direct physical contact for interaction, prevalent in many existing interactive systems.
- Digital Whiteboards:Purpose-built interactive displays primarily used for collaborative brainstorming and educational instruction.
Fixed Magic Wall holds the largest share; momentum sits with Gesture-Based Surfaces.
Technology:
The cost tier of interactive surface technologies influences adoption rates, with advanced solutions often commanding higher initial investments.
- Capacitive Touch:This technology detects changes in electrical fields when a finger or stylus makes contact, offering high precision and durability. Capacitive touch holds a dominant share in smaller interactive panels, particularly for corporate presentations requiring detailed input.
- Laser Projection:Systems using laser light to create interactive surfaces on various materials, ideal for very large or irregularly shaped displays. Laser projection is gaining traction for large-scale interactive exhibits in museums, enabling immersive educational experiences.
- Infrared:Utilizes an array of infrared LEDs and photosensors to detect touch points on the display surface.
- Optical Sensors:Employs cameras to track finger or object movements, supporting multi-touch and gesture recognition.
- Ultrasonic Tracking:Detects touch by analyzing sound wave disruptions, often used for stylus-based interaction.
Capacitive Touch technology maintains the largest market presence; Laser Projection is expanding most quickly.
Application:
Customer type significantly influences the feature set and software ecosystem required for interactive surface applications.
- Corporate Presentations:Interactive surfaces replace static projectors and whiteboards, providing dynamic tools for brainstorming and data visualization in business settings. Demand from corporate environments serves as a primary catalyst for market development across major economies.
- Education & Training:Purpose-built digital whiteboards and collaborative learning surfaces enhance engagement and facilitate interactive instruction. This application continues to outpace other uses, particularly in educational institutions seeking advanced learning tools.
- Interactive Exhibits:Large-scale, immersive displays designed for public engagement in museums, galleries, and science centers.
- Event Management:Utilizes interactive surfaces for dynamic information displays, wayfinding, and attendee engagement at conferences and trade shows.
- Indoor Advertising:Employs interactive displays in retail and public spaces to deliver engaging promotional content.
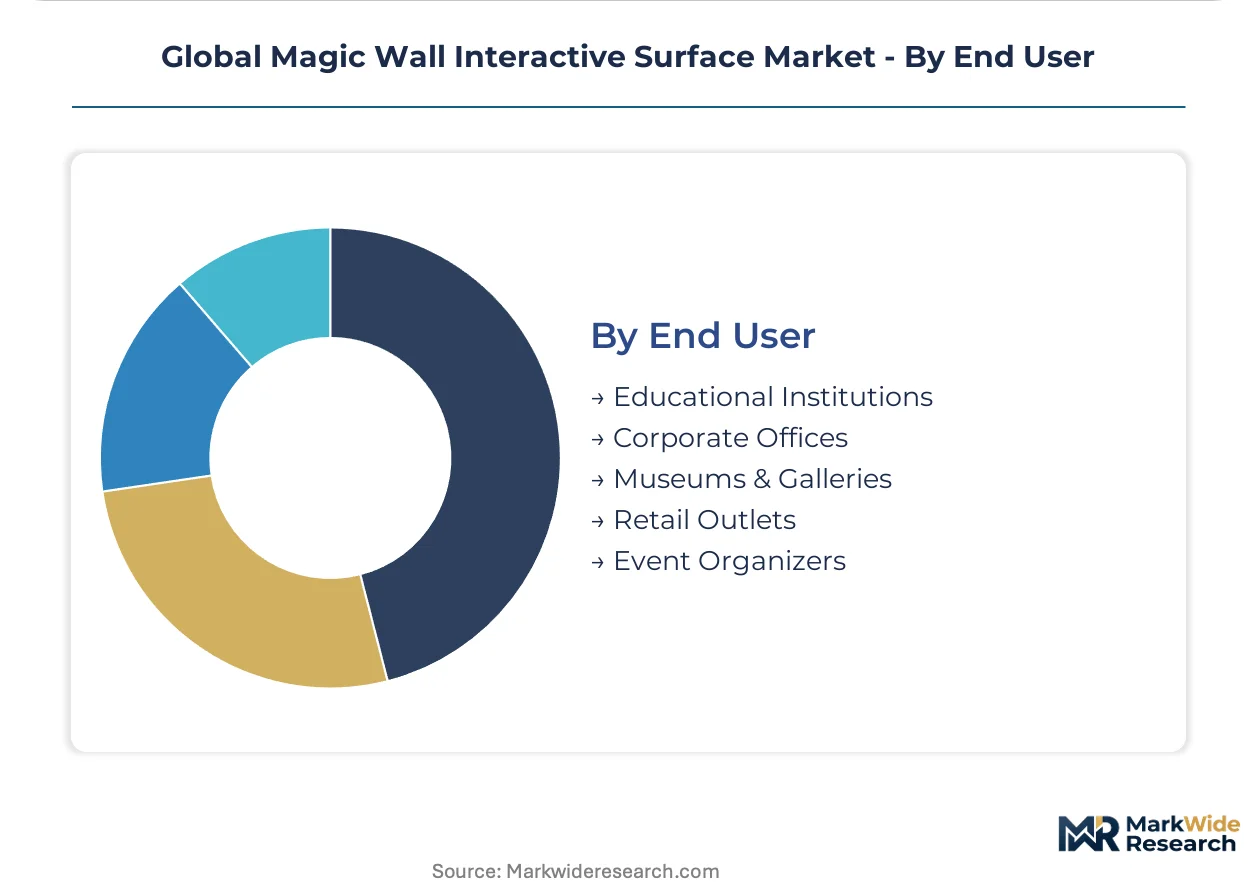
Corporate Presentations generate the highest revenue; Education & Training shows the steepest expansion trajectory.
End User:
The volume of installations varies among end-user segments, with large organizations driving significant procurement cycles.
- Corporate Offices:Businesses utilize magic wall interactive surfaces for enhanced collaboration, improved meeting efficiency, and sophisticated data visualization. These offices represent a concentrated demand for high-performance interactive displays, especially for corporate presentations.
- Educational Institutions:Schools, universities, and training centers deploy interactive surfaces for engaging students and facilitating collaborative learning environments. This segment's demand for cost-effective digital whiteboards represents a major avenue for market expansion.
- Museums & Galleries:Implement interactive displays to create immersive exhibits and provide dynamic information to visitors.
- Retail Outlets:Use interactive surfaces for product showcases, virtual try-ons, and personalized customer experiences.
- Event Organizers:Deploy interactive technology for attendee registration, interactive schedules, and engaging brand activations.
Corporate Offices command the largest share of deployments; Museums & Galleries are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global demand for magic wall interactive surfaces shows varied consumption patterns. Some regions prioritize advanced gesture-based systems for research. Others focus on large-scale corporate and educational deployments.
South Korea
South Korea exhibits strong demand for gesture-based interactive surfaces, driven by its advanced technology clusters. Adherence to national electronics standards ensures product quality and interoperability. The Seoul metropolitan area concentrates significant demand for high-performance interactive displays for research and corporate applications.
United States
The United States market sees robust demand for interactive surfaces in corporate presentations and advanced education settings. Compliance with FCC regulations is mandatory for all electronic displays. Major technology hubs across the US drive corporate adoption for enhanced collaboration and data visualization.
China
China's market for interactive surfaces is shaped by its immense manufacturing capacity for large-format display panels and rising domestic corporate demand. Adherence to GB standards for electronic displays is a prerequisite for market entry. The Pearl River Delta region also represents a significant end-user market for interactive exhibits and corporate applications.
Germany
Germany shows consistent demand for fixed magic walls in corporate boardrooms and public venues, prioritizing robust visual communication. European directives like CE marking and RoHS mandate stringent component-level compliance. Business centers such as Munich and Frankfurt increasingly adopt interactive surfaces for dynamic presentations and collaborative tools.
India
India's market for interactive surfaces is largely driven by rapid expansion in the education and training sector, alongside growing corporate collaboration needs. Compliance with national BIS standards for electronic goods ensures product safety. Technology hubs like Bengaluru and Hyderabad are witnessing increased deployment of digital whiteboards in educational institutions and corporate offices.
Global Magic Wall Interactive Surface Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure for magic wall interactive surfaces. The market exhibits a blend of specialized technology providers focusing on gesture interfaces and large electronics conglomerates leveraging their display manufacturing scale. Strategic archetypes include display manufacturing giants, software-centric integrators, and niche application specialists for education or corporate use. Key competitive moves involve vertical integration into display production and strategic partnerships for software ecosystem development and market access.
Within the competitive landscape, diverse players anchor different market segments. Samsung Electronics, a prominent electronics conglomerate, exemplifies an integrated solutions provider leveraging captive display production capabilities. SMART Technologies represents specialists focusing on purpose-built digital whiteboards, primarily targeting the education sector. Meanwhile, Planar Systems occupies a position among providers competing on high-specification video walls, tailored for corporate and event applications. These companies illustrate the varying strategies, from broad hardware integration to niche application expertise, that define competitive positioning within the magic wall interactive surface market.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Samsung Electronics |
| LG Electronics |
| Google LLC |
| Panasonic Corporation |
| Sony Corporation |
| Planar Systems |
| SMART Technologies |
| ViewSonic |
| Others |
Cost & Logistics Intelligence
Taiwan and China's concentrated large-format display panel manufacturing capacity influences downstream pricing for integrated interactive surfaces. This concentration shifts margin pools towards companies with proprietary software ecosystems or in-house production.
Pricing Analysis
Project-based contracts define initial hardware sales for large-scale interactive surfaces, complemented by recurring subscription models for software updates and support. Price differentiation stems from the depth of software ecosystem integration and the specific hardware specifications, such as display resolution or sensor type. Pricing softness reflects increasing competition as manufacturing capacity expands for display panels. Small and medium-sized enterprises exhibit the highest price sensitivity, while large corporate offices prioritize advanced features and integration.
Supply Chain Analysis
Leading contract manufacturers in Taiwan and China hold significant capacity for large-format display panels, forming the upstream foundation of the interactive surface market. The industry draws from key components like specialized capacitive touch sensors and optical sensor arrays. A structural risk involves single-source vulnerability to these panel manufacturers, which can lead to supply disruptions. Downstream distribution runs through direct sales channels and specialized system integrators, especially for enterprise solutions with bundled software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magic wall interactive surface market is at a platform-economics inflection, driven by the strategic choice between open-platform interoperability and proprietary software ecosystems. This decision dictates long-term value capture and competitive positioning for vendors.
For Market Incumbents: Insulate core market segments by deepening software ecosystem integration and expanding value-added services for corporate clients. Leverage existing captive supply of display panels to manage cost and ensure quality, countering competitive pricing pressure from new entrants. Invest in R&D for advanced sensor fusion algorithms to maintain a lead in gesture-based interfaces. Prioritize compliance certifications like CE marking to differentiate in mature markets.
For New Entrants and Emerging Players: Pursue niche applications with high growth potential, such as large-scale interactive exhibits or specialized digital whiteboards for the education sector. Target underpenetrated educational institutions with purpose-built, cost-effective solutions that offer easy integration. Develop AI-powered analytics capabilities to analyze user interaction patterns, creating a differentiated value proposition. Offer flexible, open-platform software solutions to address integration complexity challenges.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed software-centric integrators possessing strong intellectual property in sensor fusion and AI algorithms. The market demonstrates long-term viability, driven by the transition to software-defined user experiences and gesture-based interfaces. Identify acquisition targets that offer proprietary software ecosystems or specialized hardware for high-growth applications like interactive exhibits. The signal to watch is the increasing enterprise procurement shift towards integrated solutions over standalone hardware.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Software Ecosystem | Enhance compatibility with existing corporate collaboration platforms, expanding market reach. |
| Invest in Sensor Fusion R&D | Drive innovation in gesture-based interfaces, improving multi-user interaction and experience. |
| Expand Education Sector Offerings | Develop cost-effective digital whiteboards to capture the largest expansion trajectory. |
| Secure Component Supply Agreements | Mitigate vulnerability to supply disruptions from concentrated panel manufacturers. |
| Acquire Niche Software Integrators | Gain proprietary closed-ecosystem software capabilities, capturing recurring revenue. |
Research Approach
The analysis maps product types, core technologies, and key applications, each validated through primary interviews with CTOs, IT procurement officers, and educational technology specialists. Secondary research draws from technology journals, regulatory body publications like FCC and CE marking guidelines, and corporate financial reports. This approach integrates bottom-up market sizing and top-down validation.
Assumptions hold current regulatory frameworks and major technology shifts as fixed, while varying market penetration rates across the analysis window. Segmentation dimensions modeled include product type, underlying technology, application area, end-user, and regional adoption patterns. Compound annual growth rates are derived from historical trends and projected investment in R&D for gesture interfaces. Corporate IT spending trends serve as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global economic growth or corporate investment cycles shifts the trajectory. Forecasts reflect baseline assumptions, subject to revision from supply chain disruptions. Quarterly review of corporate IT budgets and display panel production forecasts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Privacy Screens Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
AMOLED Display Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Screenless Display Market
Display Technologies
Global UHD Display Market
Display Technologies
Europe Microdisplay Market
Display Technologies
Commercial Display Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
Seven Segment Display Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Smart Display Market
Display Technologies
Electronic Display Signs Market