
 Smart Display Market | 2026-2036
Smart Display Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Display Market Intelligence
The capital-intensity gap between captive display foundries and fabless assemblers is collapsing as OLED deposition equipment costs fall. Samsung Electronics leverages in-house semiconductor and panel fabrication to sustain margin control across the full stack. BOE Technology Group anchors supply security through massive Gen 10.5 LCD and emerging OLED capacity in Hefei and Wuhan. Amazon.com differentiates via vertical software-hardware integration of Alexa-enabled Echo Show devices.
Smart displays integrate touch-sensitive panels, embedded processors, wireless connectivity modules, and voice or gesture interfaces into unified interactive surfaces. LCD and LED technologies currently dominate volume manufacturing, while OLED and MicroLED segments capture premium positioning due to superior contrast ratios and thinner form factors. Retail end users drive the largest installed base for digital signage and video wall deployments, whereas healthcare and education applications represent faster-expanding demand pockets for interactive whiteboards and remote collaboration panels.
FCC certification governs radio-frequency emissions for Wi-Fi and Bluetooth connectivity in US-bound products, while CE marking under the EU Radio Equipment Directive mandates electromagnetic compatibility and safety standards for European market access. The EU AI Act introduces additional conformity requirements for displays incorporating biometric recognition or ambient intelligence features. Stakeholders must track evolving interoperability mandates between national smart home standards and energy-efficiency labeling schemes that affect product roadmaps and regional go-to-market sequencing.
Market Dynamics
The EU AI Act and GDPR compliance requirements are compressing product development timelines for voice-integrated displays while simultaneously erecting certification barriers that favor established semiconductor-panel integrators over modular assemblers.
Growth Catalysts
- Healthcare digitization:Diagnostic facilities in Germany are accelerating procurement of interactive panels for surgical suites and remote consultation rooms. The EU Medical Device Regulation creates certification pathways that favor compliant suppliers.
- Industrial automation density:Manufacturing clusters in Bavaria and Baden-Württemberg deploy specialized HMI panels for predictive maintenance interfaces. Machine-to-human visualization demands are pulling advanced touch and gesture modules.
- REACH substance restrictions:Phased limitations on hazardous materials in display manufacturing are accelerating transition to compliant OLED deposition chemistries and recyclable chassis designs.
Market Restraints
- OLED deposition equipment costs:Vacuum thermal evaporation and inkjet printing systems require substantial capital commitments that constrain mid-tier foundry expansion.
- Rare earth magnet concentration:Neodymium and dysprosium supply chains concentrate in China's refining and separation facilities, creating geopolitical input vulnerability for speaker-motor assemblies.
- F-Gas Regulation phase-down:Hydrofluorocarbon restrictions under EU climate policy are complicating thermal management system designs for high-brightness outdoor signage.
Strategic Opportunities
- MicroLED pilot production:Mass transfer yield improvements are opening commercial viability for premium residential and automotive cockpit applications previously reserved for OLED.
- CSRD disclosure mandates:Corporate sustainability reporting requirements are creating demand for energy-consumption monitoring displays in facility management and smart building retrofits.
- Edge AI inference localization:On-device neural processing is enabling biometric authentication and ambient intelligence without cloud dependency, satisfying GDPR data sovereignty constraints.
Industry Challenges
- RF coexistence engineering:Wi-Fi 6E, Bluetooth 5.3, and UWB module integration demands specialized electromagnetic compatibility testing that extends FCC and CE certification timelines.
- Legacy HVAC integration:Smart thermostat displays must interface with proprietary building automation protocols from established controls manufacturers, complicating interoperability certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Display Market |
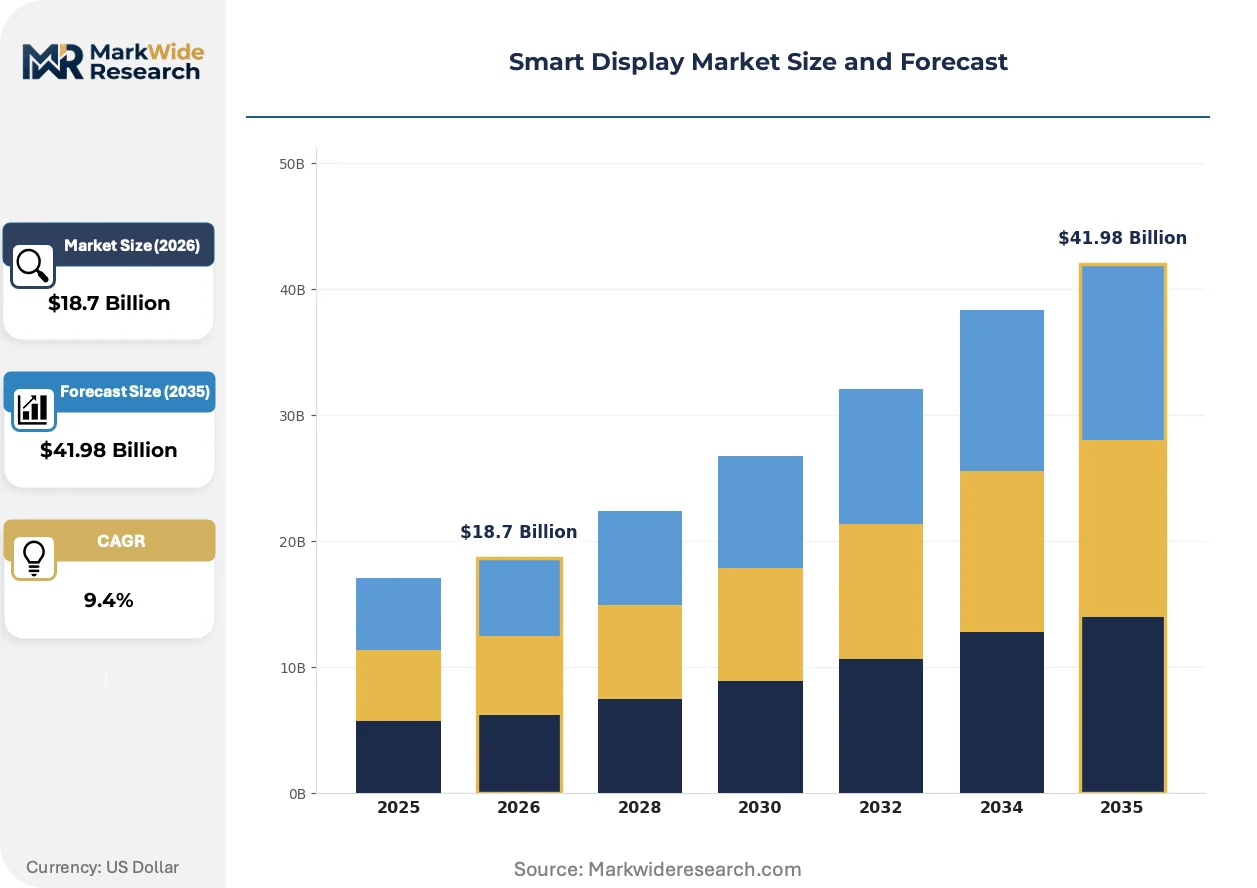
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Signage, Smart TVs, Interactive Whiteboards, Video Walls Technology: LCD, LED, OLED, MicroLED End User: Retail, Automotive, Education, Healthcare Application: Advertising, Remote Collaboration, Monitoring, Entertainment |
| Companies Covered | Google LLC, Sony Corporation, Samsung Electronics, BOE Technology Group Co. Ltd., Sharp Corporation, LG Electronics, Panasonic Corporation, Lenovo Group Limited, Amazon.com, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Display Market Strategic Shifts & Innovations
Active-matrix OLED technology is compressing LCD's dominance in premium segments while regulatory pressure on biometric data processing is forcing architectural redesigns of ambient intelligence systems.
MicroLED displays are supplanting conventional direct-view LED walls in broadcast studios and executive briefing centers. Sports venues and control room operators in the United States are piloting sub-1mm pixel pitch cabinets for daylight-visible performance. The technology is compressing maintenance intervals and power consumption benchmarks that previously favored projection-based alternatives.
The EU AI Act's risk-based classification system is mandating conformity assessments for displays incorporating facial recognition or emotion detection. Hardware manufacturers must now document algorithmic transparency and human oversight mechanisms before CE marking. Healthcare and public sector procurement in France and Germany are prioritizing compliant suppliers, creating certification-driven vendor selection.
Enterprise buyers are consolidating vendor relationships around full-stack platform providers rather than hardware-only suppliers. Facility managers in commercial real estate are unbundling display procurement from content management subscriptions, favoring interoperable standards over proprietary ecosystems. This pattern is most visible in Nordic markets where CSRD compliance pressures accelerate building automation refresh cycles.
Smart Display Market Segmentation
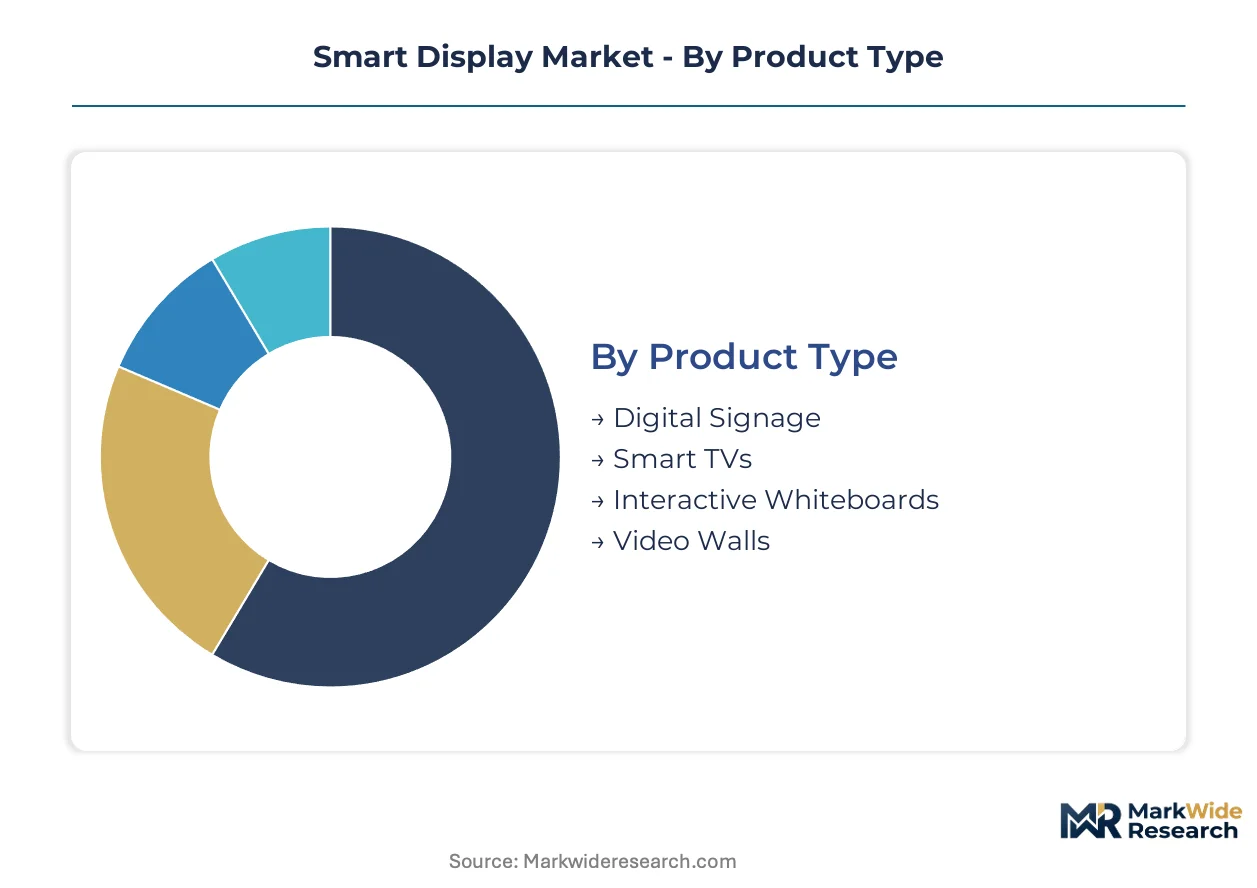
Smart display procurement patterns diverge sharply across product categories and use environments, with regulatory compliance requirements and application-specific performance thresholds driving vendor selection. Understanding these segment boundaries reveals where certification investments concentrate and where modular assembly can compete against integrated stack providers.
Product Type:
CE marking under the EU Radio Equipment Directive and FCC Part 15 certification create divergent compliance burdens across form factors, with larger surface-area products facing amplified electromagnetic compatibility testing costs.
- Digital Signage:Outdoor-rated enclosures integrate high-brightness panels, thermal management systems, and cellular connectivity modules for remote content deployment. Retail chains in Germany and France prioritize energy-efficiency labeling compliance under EU ecodesign regulations for fleet-wide installations.
- Smart TVs:Voice-integrated residential displays incorporate far-field microphone arrays and neural processing units for ambient intelligence. GDPR Article 25 data protection by design mandates are forcing architectural separation of biometric processing from cloud connectivity in European-bound units.
- Interactive Whiteboards:Infrared or capacitive touch layers overlay LCD or OLED substrates for multi-user annotation. Education procurement in Bavaria favors MDR-compliant suppliers for classroom hygiene standards.
- Video Walls:Narrow-bezel tiled configurations serve control room and broadcast applications demanding 24/7 operational ratings. Sports venues in the United States pilot sub-1mm pixel pitch cabinets for daylight-visible performance.
Established volume favors Smart TVs; emerging adoption favors Interactive Whiteboards.
Technology:
Capital intensity and deposition chemistry compliance costs stratify competitive positioning, with REACH substance restrictions accelerating transitions away from legacy manufacturing processes.
- LCD:Gen 10.5 glass substrates enable 65-inch and larger panel economics through multi-panel cutting efficiency. BOE Technology Group anchors supply security through massive capacity installations in Hefei and Wuhan.
- LED:Direct-view configurations dominate outdoor signage with IP65-rated enclosures and 10,000-nit brightness capability. F-Gas Regulation phase-down complicates thermal management system designs for high-brightness outdoor deployments.
- OLED:Vacuum thermal evaporation and inkjet printing systems produce self-emissive pixels with infinite contrast ratios. Premium residential and automotive cockpit applications reward superior black-level performance despite higher equipment depreciation.
- MicroLED:Mass transfer yield improvements are opening commercial viability for broadcast studios and executive briefing centers previously reserved for OLED. Machine-to-human visualization demands in Bavaria and Baden-Württemberg pull advanced touch and gesture module integration.
LCD commands current installed base; MicroLED climbs the fastest toward premium positioning.
End User:
Procurement authority structures and compliance documentation requirements vary dramatically across buyer categories, with healthcare and public sector tenders imposing certification-driven vendor selection.
- Retail:Digital signage and video wall deployments drive the largest installed base for fleet-wide content management. Nordic facility managers unbundle display procurement from subscription services, favoring interoperable standards over proprietary ecosystems.
- Automotive:Cockpit displays must satisfy AEC-Q100 reliability standards and NHTSA distraction guidelines for driver information systems. OLED and MicroLED segments capture premium positioning due to thinner form factors enabling curved surface integration.
- Education:Interactive whiteboards and remote collaboration panels represent expanding demand pockets as hybrid learning infrastructure persists. CSRD disclosure mandates accelerate building automation refresh cycles in Nordic markets.
- Healthcare:Diagnostic facilities in Germany accelerate procurement of interactive panels for surgical suites and remote consultation rooms. EU Medical Device Regulation creates certification pathways that favor compliant suppliers over modular assemblers.
Retail maintains broadest deployment; healthcare exhibits steepest expansion trajectory.
Application:
Revenue model structures diverge between capital expenditure hardware sales and recurring service subscriptions, with advertising-funded deployments demanding distinct durability specifications.
- Advertising:Networked displays require cellular or Wi-Fi 6E connectivity for real-time content synchronization and audience analytics. FCC and CE certification timelines extend due to RF coexistence engineering demands across multiple radio modules.
- Remote Collaboration:Enterprise video conferencing endpoints integrate beamforming microphone arrays and auto-framing cameras. Edge AI inference localization enables biometric authentication without cloud dependency, satisfying GDPR data sovereignty constraints.
- Monitoring:Industrial HMI panels in Baden-Württemberg manufacturing clusters deploy predictive maintenance interfaces. REACH substance restrictions accelerate transition to compliant chassis designs and recyclable component selection.
- Entertainment:Residential smart displays compete on voice assistant integration and streaming service partnerships. Amazon.com differentiates via vertical software-hardware integration of Alexa-enabled Echo Show devices.
Advertising generates highest unit volumes; remote collaboration gains share fastest among enterprise buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in display panel trade are tilting toward captive production zones, with fabrication capacity expansion outpacing assembly outsourcing. Panel trade deficits concentrate in Western European and North American markets, while East Asian economies sustain surplus positions through substrate and deposition equipment dominance.
United States
Sports venues and broadcast studios drive demand for sub-1mm pixel pitch video walls and daylight-visible performance specifications. FCC Part 15 certification governs radio-frequency emissions for Wi-Fi 6E and Bluetooth 5.3 connectivity modules. Control room operators in Texas and California pilot MicroLED configurations for 24/7 operational ratings.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg deploy specialized HMI panels for predictive maintenance interfaces and machine-to-human visualization. The EU AI Act and GDPR compliance requirements compress product development timelines for voice-integrated displays. Diagnostic facilities accelerate procurement of interactive panels for surgical suites and remote consultation rooms.
China
Massive Gen 10.5 LCD capacity installations in Hefei and Wuhan anchor supply security for 65-inch and larger panel economics. MIIT standards and GB certification frameworks govern electromagnetic compatibility for domestic market access. Emerging OLED deposition capacity targets premium residential and automotive cockpit applications.
South Korea
OLED technology leadership sustains premium positioning through vacuum thermal evaporation and inkjet printing system investments. The country's national semiconductor regulator enforces reliability standards for driver information systems and cockpit displays. Seoul-based fabricators leverage in-house semiconductor and panel fabrication for full-stack margin control.
Japan
Automotive display procurement concentrates on AEC-Q100 reliability standards and NHTSA distraction guideline compliance for curved surface integration. METI industrial policy supports advanced deposition chemistry development under REACH-aligned substance restrictions. Nagoya and Tokyo manufacturing clusters specialize in high-brightness thermal management systems for outdoor signage.
Smart Display Market Key Industry Players
Concentration sits with vertically integrated semiconductor-panel fabricators and captive foundry operators who control deposition equipment and substrate supply. The competitive terrain splits between scale-driven volume manufacturers and premium-tier technology specialists. Three archetypes dominate: full-stack platform providers, fabless assemblers dependent on external panel supply, and component-specialist integrators. Capacity expansion in Gen 10.5 glass substrates and strategic partnerships for OLED deposition chemistries represent the dominant competitive moves.
Within the full-stack platform tier, Samsung Electronics and Amazon.com exemplify contrasting integration models. Samsung Electronics leverages in-house semiconductor and panel fabrication to sustain margin control across substrate, deposition, and assembly stages. Amazon.com differentiates via vertical software-hardware integration of voice-enabled residential display devices. BOE Technology Group anchors the supply-security archetype through massive capacity installations in Hefei and Wuhan. These three occupy positions that modular assemblers struggle to replicate given capital intensity requirements and certification barrier escalation.
| Leading Market Players |
|---|
| Google LLC |
| Sony Corporation |
| Samsung Electronics |
| BOE Technology Group Co. Ltd. |
| Sharp Corporation |
| LG Electronics |
| Panasonic Corporation |
| Lenovo Group Limited |
| Amazon.com, Inc. |
| Others |
Cost & Logistics Intelligence
FCC Part 15 and CE marking under the EU Radio Equipment Directive gate both supplier qualification and price differentiation simultaneously, as certification timelines and electromagnetic compatibility testing costs stratify vendors by compliance capability and capital reserves.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, where certification grade under the EU AI Act and volume scale drive price differentiation. Cost compression in economy-tier LCD panels is intensifying because Gen 10.5 glass substrate capacity expansions in China feed oversupply conditions. Healthcare procurement committees exhibit lowest price sensitivity due to MDR compliance mandates, whereas retail fleet buyers negotiate aggressively on per-unit costs.
Supply Chain Analysis
Rare earth magnet refining concentration in China's separation facilities underwrites geopolitical input vulnerability for speaker-motor assemblies across voice-integrated display production. Panel fabrication draws from massive substrate capacity in Hefei and Wuhan, while OLED deposition equipment sourcing centers on South Korean and Japanese toolmakers. Tariff exposure on finished displays into Western markets disrupts margin structures. Distribution runs through captive foundry direct sales for tier-one OEMs and modular assembler channels for mid-tier brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart display demand follows industrial automation capital expenditure cycles, with Bavaria and Baden-Württemberg manufacturing clusters signaling recovery through HMI panel procurement acceleration.
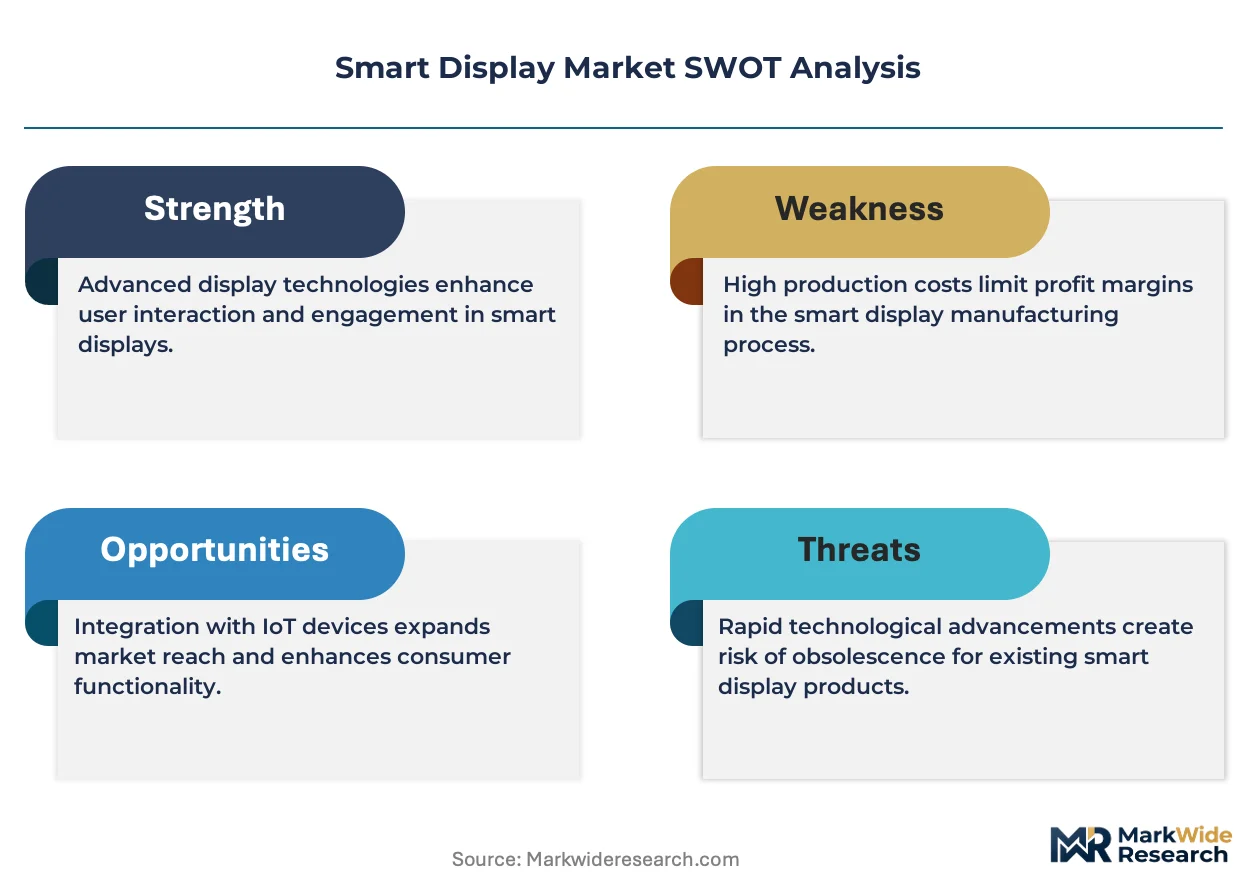
For Market Incumbents: Consolidate certification advantage by accelerating EU AI Act conformity assessments ahead of modular assemblers, and deepen backward integration into OLED deposition chemistries to defend margin position against fabless competitors. MicroLED pilot production yields represent the critical capability gap to close. For New Entrants and Emerging Players: Differentiate on edge AI inference localization for GDPR-compliant healthcare deployments in Germany, where MDR certification barriers favor compliant suppliers. White-space concentration sits with CSRD-mandated energy monitoring displays in Nordic facility management retrofits. A channel partnership with building automation integrators unlocks procurement access faster than direct OEM sales cycles. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward certified semiconductor-panel integrators with documented algorithmic transparency. Long-term viability favors full-stack platform providers with captive foundry economics over modular assemblers exposed to panel price volatility. Watch mass transfer yield improvements in MicroLED pilot lines as the inflection signal for premium segment displacement of OLED.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Acceleration | CE marking timelines compress competitive windows for voice-integrated diagnostic panels in German healthcare procurement. |
| Gen 10.5 Capacity Expansion | BOE Technology Group's Hefei and Wuhan installations anchor supply security for 65-inch and larger panel economics. |
| MicroLED Pilot Production Scale-Up | Mass transfer yield improvements open broadcast studio and automotive cockpit applications previously reserved for OLED. |
| Edge AI Inference Localization | On-device neural processing satisfies GDPR data sovereignty constraints for biometric authentication in European-bound units. |
| REACH-Compliant Deposition Chemistry Transition | Phased hazardous material limitations accelerate OLED manufacturing process redesigns and recyclable chassis adoption. |
Research Approach
A standing panel of display procurement managers at German automotive OEMs, healthcare facility technology officers, and Nordic commercial real estate facility directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization databases, EU Medical Device Regulation notified body filings, and customs trade data on panel substrate imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, technology node, end-user vertical, and application deployment model segmentations. CAGRs were derived from regression analysis of historical procurement patterns and projected replacement cycles. Industry-specific forecast inputs incorporated REACH substance restriction phase-down schedules and F-Gas Regulation thermal management compliance costs.
Material uncertainties — geopolitical disruption to rare earth magnet supply chains, unanticipated EU AI Act enforcement severity, and MicroLED mass transfer yield volatility — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and industrial automation capital expenditure continuity. Practitioners should keep alternative scenarios live as EU regulatory implementation timelines and China-US trade policy postures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
4K Technology Market
Display Technologies
IGZO Display Market
Display Technologies
Thin Display Technology Market
Display Technologies
Virtual Retinal Display (VRD) Market
Display Technologies
Phosphor Screen Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Display Port Market
Display Technologies
Flexible Display Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Video Wall Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Portable Projector Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Collaboration Display Market
Display Technologies
Multimedia Projectors Market