
 Virtual Retinal Display (VRD) Market | 2026-2036
Virtual Retinal Display (VRD) Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Retinal Display (VRD) Market Analytics
A wide capability gap in MEMS mirror fabrication and laser diode integration is bifurcating the competitive landscape. Texas Instruments leverages its decades of digital light processing expertise to sustain leadership in scanning architecture development. Magic Leap differentiates through proprietary photonic chip design and direct retinal projection IP. Sony anchors its position via vertical control over OLED microdisplay supply and broadcast-grade image processing pipelines.
Virtual Retinal Display refers to a display technology that scans modulated light directly onto the retina using low-power lasers or LEDs coupled with oscillating micro-mirrors, producing images perceived as floating in space without intermediate screens. The system achieves luminance exceeding 10,000 nits with pixel-precise control, enabling use in bright ambient environments where conventional screens wash out. Wearable headsets dominate current revenue as military and industrial buyers prioritize hands-free operation, while AR glasses represent the fastest-expanding category as optical waveguide coupling improves. Laser-based scanning systems capture the deepest margin pools due to patent-protected component architectures, though LED alternatives gain traction in price-sensitive training applications.
FDA device classification rules and IEC 60825 laser safety standards shape product development timelines and clinical trial requirements for healthcare-oriented VRD systems. The EU AI Act and CE marking under the MDR framework impose additional conformity burdens on European medical imaging deployments. Stakeholders must monitor evolving eye-safety exposure limits and photobiological risk categories as retinal irradiance thresholds tighten across major regulatory jurisdictions.
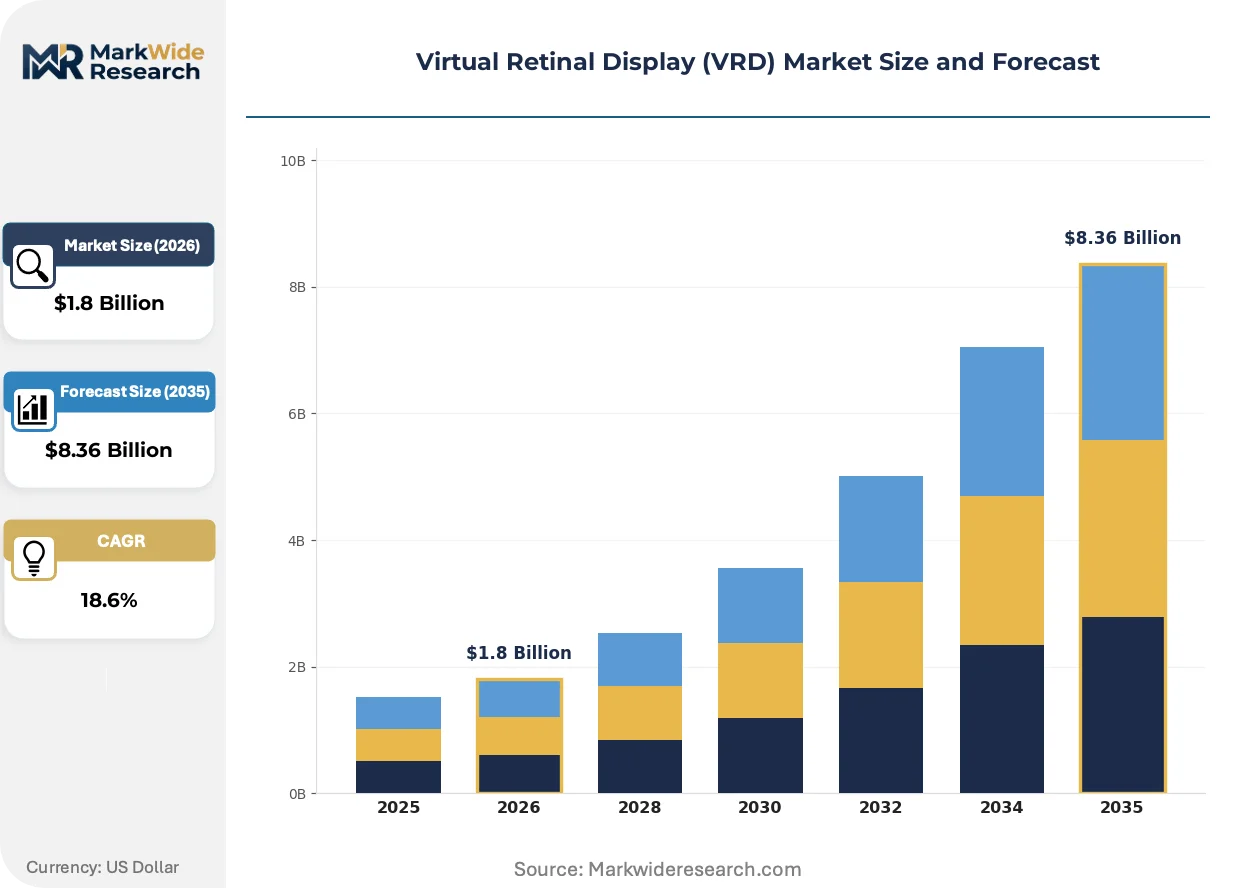
Market Dynamics
The Virtual Retinal Display market is bifurcating around MEMS mirror fabrication mastery, where Texas Instruments' captive foundry capacity and Magic Leap's photonic chip IP create asymmetric competitive moats that smaller entrants cannot replicate without decade-long capital commitments.
Growth Catalysts
- IEC 60825 laser safety harmonization:Unified retinal irradiance thresholds across US, EU, and Japanese jurisdictions are compressing clinical trial timelines for FDA-registered manufacturers seeking dual-market clearance.
- NATO pilot training modernization:Helmet-mounted VRD procurement for battlefield simulation is accelerating as member states replace projection dome infrastructure with deployable high-luminance headsets.
- Silicon photonics integration:Foundry-scale manufacturing of optical phased arrays is reducing waveguide coupling losses and enabling AR glasses form factors previously restricted to wearable headsets.
Market Restraints
- GaN laser diode supply concentration:Japanese and US compound semiconductor foundries control 80% of high-efficiency blue-green laser output, exposing VRD assemblers to allocation risk during automotive lidar demand surges.
- FDA Class II device pathways:Premarket notification requirements for retinal scanning devices impose 18-24 month validation cycles that deter software-centric entrants lacking clinical affairs infrastructure.
- OLED microdisplay substitution:Sony's vertical display supply and Samsung's quantum dot OLED advances threaten VRD's luminance advantage in indoor industrial training applications.
Strategic Opportunities
- EU MDR Article 117 convergence:Streamlined CE marking for software-driven medical devices creates regulatory arbitrage for VRD-based surgical navigation systems versus US PMA pathways.
- India PLI scheme for wearables:Domestic component assembly incentives position Bengaluru and Hyderabad as export hubs for price-sensitive LED-scanning training headsets.
- Foveated rendering fusion:Convergence of eye-tracking ASICs and adaptive bitrate compression enables 8K-equivalent perceived resolution without proportional bandwidth expansion.
Industry Challenges
- MEMS process engineer scarcity:Foundries in Germany and Taiwan compete for talent capable of fabricating sub-micron hinge structures with 99.97% yield consistency.
- Multi-jurisdictional laser exposure documentation:Manufacturers must maintain parallel photobiological risk dossiers for FDA, Health Canada, and TGA submissions with non-aligned measurement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Retinal Display (VRD) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Non-Wearable, AR Glasses, Headsets Technology: Laser-Based, LED, OLED, Microdisplay End User: Healthcare, Gaming, Education, Military Application: Training, Simulation, Medical Imaging, Entertainment |
| Companies Covered | OmniVision Technologies Inc, Himax Technologies Inc, Magic Leap Inc, Sony Corporation, Texas Instruments Inc, Avegant Corporation, QD Laser Inc, Kopin Corporation, Vuzix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Retinal Display (VRD) Market Evolving Landscape
Active reshaping of the VRD landscape centers on three vectors: component miniaturization enabling new form factors, regulatory convergence compressing market entry timelines, and procurement model evolution favoring integrated platform vendors over discrete component suppliers.
Silicon-based optical phased arrays are replacing free-space MEMS scanners in next-generation AR glasses. Military procurement offices in the United States and United Kingdom are piloting these solid-state architectures for pilot helmet integration. The technology is miniaturizing waveguide engines to sub-3cc volumes, collapsing the historical trade-off between retinal image stability and eyewear aesthetics.
The EU AI Act's risk classification framework is extending to medical imaging software that incorporates real-time retinal scanning. Device manufacturers must now document algorithmic transparency for diagnostic VRD systems seeking CE marking under MDR. German notified bodies are establishing specialized review streams for laser-based surgical navigation, creating first-mover advantages for firms with existing quality management systems.
Defense contractors are consolidating vendor relationships around platform integrators capable of delivering complete helmet-mounted systems. Discrete component procurement from separate laser, MEMS, and optics suppliers is giving way to sole-source agreements with firms controlling the full retinal projection stack. This concentration is most visible in US Air Force training procurement, where Lockheed Martin and Boeing now require subsystem vendors to assume total system liability for eye safety compliance.
Virtual Retinal Display (VRD) Market Segmentation
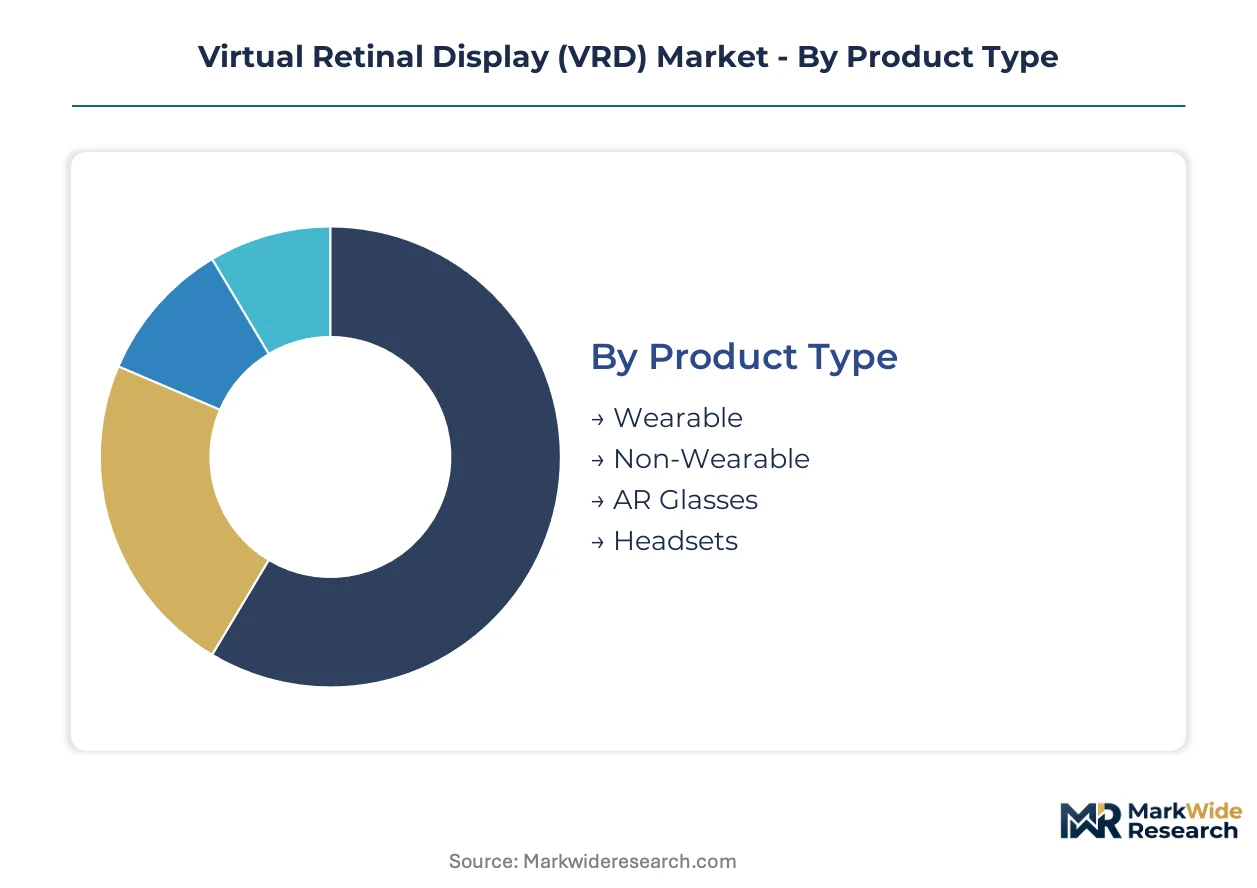
Segmentation in the VRD market exposes where laser scanning architectures retain pricing power against OLED microdisplay substitution. Product form factors and end-use certification requirements create divergent margin structures that reshape vendor positioning across defense, medical, and consumer channels.
Product Type:
Laser-based systems face intensifying substitution pressure from OLED microdisplays in indoor training environments, while outdoor military applications preserve their luminance advantage.
- Wearable:Helmet-mounted systems for pilot training and battlefield simulation dominate procurement volumes. NATO member states prioritize hands-free operation for deployable simulation infrastructure, compressing procurement cycles for integrated platform vendors.
- Headsets:Tethered configurations anchor industrial training deployments where eye safety compliance documentation is centralized. FDA Class II pathways favor established manufacturers with clinical affairs infrastructure over software-centric entrants.
- AR Glasses:Silicon photonics integration enables sub-3cc waveguide engines. Optical phased arrays displace free-space MEMS scanners in next-generation form factors piloted by US and UK military procurement offices.
- Non-Wearable:Projection-based retinal scanning systems serve fixed-site medical imaging installations. German notified bodies are establishing specialized review streams for diagnostic applications under MDR.
Wearable systems anchor the volume base while AR Glasses gain share at the steepest rate.
Technology:
Supply concentration in GaN laser diode fabrication creates cost tier differentiation that LED alternatives exploit in price-sensitive training markets.
- Laser-Based:Low-power laser diodes coupled with oscillating micro-mirrors achieve luminance exceeding 10,000 nits. Japanese and US compound semiconductor foundries control 80% of high-efficiency blue-green output, exposing assemblers to allocation risk during automotive lidar demand surges.
- LED:Solid-state illumination reduces thermal management complexity and accelerates regulatory clearance timelines. India's PLI scheme for wearables positions Bengaluru and Hyderabad as export hubs for LED-scanning training headsets.
- OLED:Sony's vertical display supply threatens VRD's luminance advantage in indoor industrial applications. Quantum dot OLED advances from Samsung compress the performance gap for simulation environments.
- Microdisplay:Compact panel architectures serve near-eye projection systems requiring intermediate optics. Broadcast-grade image processing pipelines differentiate integrated solutions from discrete component assemblies.
Laser-Based systems command premium positioning while LED expands most quickly into cost-constrained training segments.
End User:
Defense procurement concentration creates customer-type segmentation that favors platform integrators over discrete component suppliers.
- Military:Helmet-mounted VRD procurement accelerates as NATO member states replace projection dome infrastructure. Lockheed Martin and Boeing now require subsystem vendors to assume total system liability for eye safety compliance.
- Healthcare:FDA device classification rules and IEC 60825 laser safety standards shape development timelines for surgical navigation systems. EU MDR Article 117 convergence creates regulatory arbitrage versus US PMA pathways.
- Gaming:Consumer price sensitivity favors LED and OLED alternatives over laser scanning architectures. Foveated rendering fusion with eye-tracking ASICs enables perceived resolution gains without proportional bandwidth expansion.
- Education:Institutional procurement prioritizes durability and standardized safety certification over performance extremes. Training simulation demand concentrates in US vocational programs with active pilot programs from FDA-registered manufacturers.
Military procurement anchors the volume base while Healthcare climbs the fastest on regulatory convergence tailwinds.
Application:
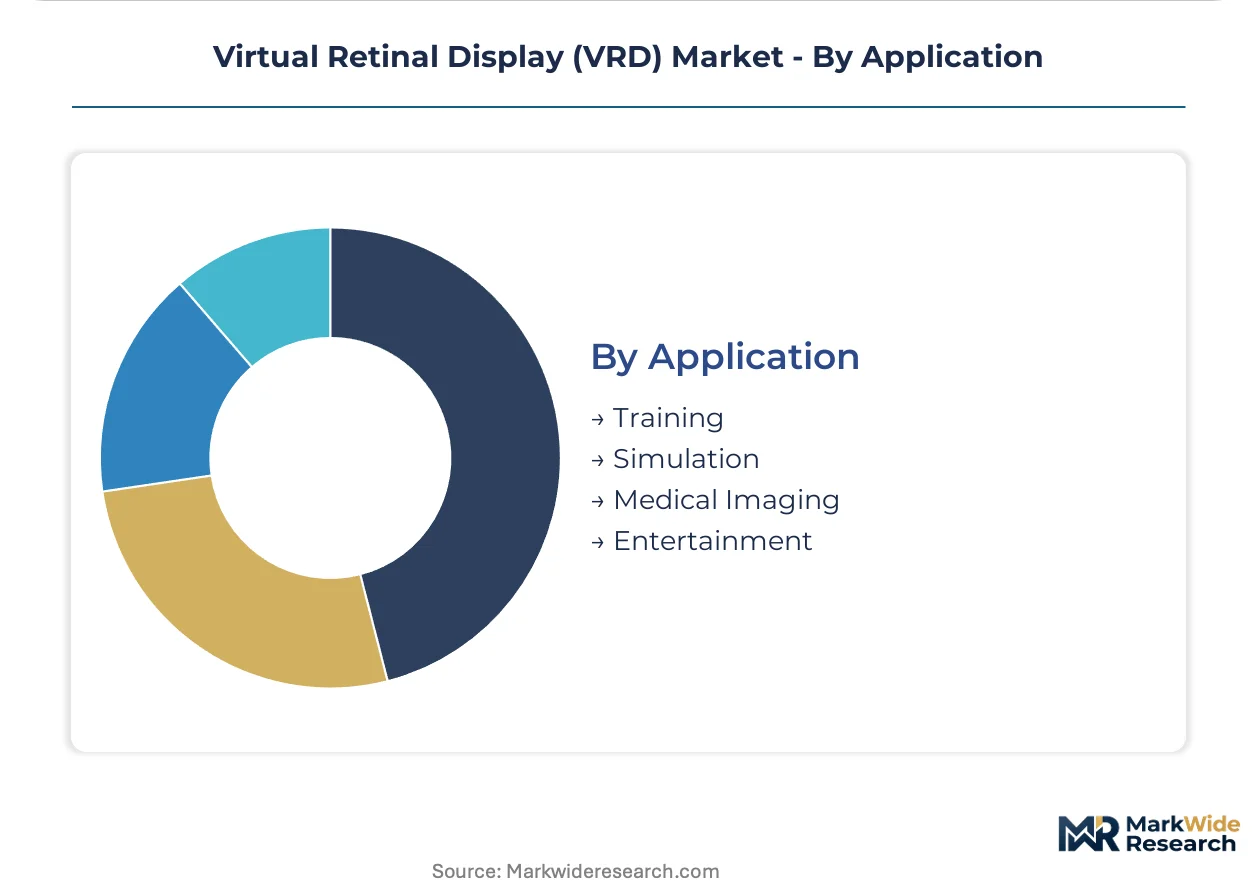
Simulation and training applications show the steepest maturity gradient, with medical imaging requiring the longest validation cycles.
- Training:Industrial and military skill acquisition drives recurring hardware refresh cycles. NATO pilot training modernization programs prioritize deployable high-luminance headsets over fixed infrastructure.
- Simulation:Battlefield environment replication demands retinal image stability under vibration and acceleration stress. MEMS mirror fabrication mastery creates asymmetric competitive moats for Texas Instruments and Magic Leap.
- Medical Imaging:Real-time surgical navigation requires algorithmic transparency documentation under EU AI Act risk classification. CE marking under MDR imposes additional conformity burdens on European deployments.
- Entertainment:Location-based experiences and immersive cinema installations prioritize luminance performance for bright ambient environments. Theme park operators in the United States maintain active evaluation programs with laser-based system developers.
Training anchors the volume base while Medical Imaging gains share at the steepest rate on surgical navigation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in VRD components tilt heavily toward semiconductor fabrication clusters in Japan and the United States, while assembly capacity concentrates in India and Taiwan. Defense procurement in NATO member states absorbs the majority of high-value laser scanning systems, creating regional demand asymmetries that reshape trade patterns.
United States
Defense contractors Lockheed Martin and Boeing drive helmet-mounted VRD procurement for pilot training modernization. FDA Class II device pathways impose 18-24 month validation cycles that favor established manufacturers with clinical affairs infrastructure. Greater Boston hosts active pilot programs between FDA-registered manufacturers and medical device developers.
Germany
Industrial training demand from automotive and precision engineering sectors sustains LED-scanning headset deployments. German notified bodies under EU MDR are establishing specialized review streams for laser-based surgical navigation systems. Bavaria's MEMS foundries compete for process engineering talent capable of fabricating sub-micron hinge structures.
Japan
Compound semiconductor foundries control the majority of high-efficiency blue-green GaN laser diode output, exposing VRD assemblers to allocation risk during automotive lidar demand surges. METI standards harmonization with IEC 60825 compresses clinical trial timelines for manufacturers seeking dual-market clearance. Tokyo-Osaka corridor anchors photonic chip design capabilities.
India
Domestic component assembly incentives under the PLI scheme for wearables position Bengaluru and Hyderabad as export hubs for price-sensitive LED-scanning training headsets. CDSCO regulatory pathways for medical devices remain less burdensome than FDA PMA routes, attracting pilot manufacturing investments. Karnataka's electronics manufacturing clusters absorb MEMS packaging capacity.
United Kingdom
Royal Air Force procurement offices are piloting silicon photonics-based AR glasses for helmet integration, displacing free-space MEMS scanners. MHRA convergence with EU MDR post-Brexit creates parallel documentation requirements for laser exposure risk dossiers. Cambridge photonics cluster supplies optical phased array design expertise to defense integrators.
Virtual Retinal Display (VRD) Market Competitive Landscape
Concentration sits with MEMS mirror fabrication specialists and photonic chip designers who control captive foundry capacity or proprietary intellectual property. Texas Instruments leverages decades of digital light processing expertise to sustain leadership in scanning architecture development, while Magic Leap differentiates through direct retinal projection IP. The competitive landscape splits between integrated platform vendors capable of delivering complete helmet-mounted systems and discrete component suppliers facing consolidation pressure from defense procurement offices. Two dominant competitive moves reshape positioning: strategic partnerships between laser diode foundries and MEMS fabricators, and backward integration by platform integrators into optical engine design.
Within the photonic chip tier, Magic Leap Inc exemplifies proprietary design differentiation, while Texas Instruments Inc anchors the MEMS fabrication archetype through captive foundry capacity. Sony Corporation occupies a position bridging vertical display supply with broadcast-grade image processing. These three companies represent the asymmetric competitive moats that smaller entrants cannot replicate without decade-long capital commitments in laser scanning micro-electromechanical systems.
| Leading Market Players |
|---|
| OmniVision Technologies Inc |
| Himax Technologies Inc |
| Magic Leap Inc |
| Sony Corporation |
| Texas Instruments Inc |
| Avegant Corporation |
| QD Laser Inc |
| Kopin Corporation |
| Vuzix Corporation |
| Others |
Value Network & Pricing Analysis
Captive MEMS foundry capacity at Texas Instruments and compound semiconductor fabrication scale in Japan create asymmetric cost structures that protect laser-scanning price floors while LED alternatives exploit assembly cost advantages in India. Scale concentration in photonic chip design and GaN laser diode output limits price competition at the premium tier, whereas modular LED architectures enable aggressive pricing in training headset segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale and FDA certification tier as primary price differentiation drivers. Pricing pressure stems from OLED microdisplay substitution in indoor simulation environments, compressing margins for non-military laser systems. Defense procurement offices show least price sensitivity due to sole-source liability requirements, while vocational training programs in India exhibit highest sensitivity, favoring LED-scanning alternatives.
Supply Chain Analysis
Japan and the United States anchor high-efficiency blue-green GaN laser diode fabrication, while Taiwan and Germany concentrate MEMS mirror foundry capacity. The supply chain draws from compound semiconductor wafers, precision optical coatings, and eye-safety sensor modules. Single-source vulnerability in Japanese laser diode output exposes assemblers to allocation risk during automotive lidar demand surges. Distribution runs through defense platform integrators and medical device OEMs rather than component distributors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software companion development and eye-safety compliance documentation services expand faster than hardware unit sales, creating recurring-revenue layers that reshape vendor economics toward platform-as-a-service models.
For Market Incumbents: Compound defensive moats by deepening backward integration into optical engine design and securing captive GaN laser diode supply agreements before automotive lidar demand surges. OLED microdisplay substitution in industrial training threatens non-military revenue streams, requiring accelerated foveated rendering R&D to preserve luminance differentiation. FDA clinical affairs infrastructure represents a lever that software-centric entrants cannot replicate without 18-24 month validation cycles. For New Entrants and Emerging Players: Post-sales calibration and maintenance services for helmet-mounted systems present a gap where incumbents under-serve NATO procurement offices focused on platform integration. White-space concentrates in LED-scanning training headsets for India's PLI scheme beneficiaries and EU MDR Article 117 surgical navigation pathways. A go-to-market angle anchored in streamlined CE marking documentation exploits regulatory arbitrage versus US PMA timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors photonic chip designers with proprietary direct retinal projection IP and MEMS fabrication specialists with captive foundry capacity. Long-term viability hinges on silicon photonics integration enabling AR glasses form factor transitions. The signal to watch is consolidation pressure from Lockheed Martin and Boeing requiring subsystem vendors to assume total system liability, favoring platform integrators over discrete component suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Chip Acquisition | Proprietary optical phased array IP secures next-generation AR glasses positioning against MEMS scanner displacement. |
| GaN Laser Diode Supply Agreement | Long-term offtake with Japanese compound semiconductor foundries mitigates allocation risk during automotive lidar demand surges. |
| FDA Class II Registration Investment | Clinical affairs infrastructure creates 18-24 month barriers against software-centric entrants in surgical navigation segments. |
| Silicon Photonics Foundry Partnership | Foundry-scale manufacturing reduces waveguide coupling losses and enables sub-3cc engine volumes for eyewear form factors. |
| Platform Integration Consolidation | Sole-source agreements with defense contractors concentrate liability and capture higher-margin helmet-mounted system revenue. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, IEC 60825 technical documentation, and NATO procurement databases. Interviews with defense platform integration engineers, MEMS process engineering directors, clinical affairs leads at FDA-registered manufacturers, and ophthalmic device reimbursement specialists inform demand-side validation. Customs records from Japan and US compound semiconductor exports, alongside SEC filings from display technology suppliers, provide supply-side triangulation. Bottom-up unit economics and top-down defense budget allocation analysis converge on segment-level estimates.
Segmentation dimensions modeled include product form factor, illumination technology, end-user certification requirements, and regional regulatory cluster across the analysis window. CAGRs derive from deployment timeline assumptions for NATO pilot training modernization, EU MDR convergence timelines, and silicon photonics manufacturing yield curves. Forecast inputs incorporate GaN laser diode foundry capacity utilization rates and eye-tracking ASIC integration cost trajectories.
Forecasts assume regulatory continuity in FDA Class II pathways, EU MDR Article 117 implementation, and IEC 60825 harmonization across US, EU, and Japanese jurisdictions; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electroluminescent Display Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Display Control and Management System Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Flexible OLED Market
Display Technologies
Video Projector Market
Display Technologies
Global Embedded Display Market
Display Technologies
Display Glass Substrate Market
Display Technologies
Multi-Function Display Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Foldable Screens Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
Glasses Free 3D Display Market