
 Smart Pressure Sensors Market | 2026-2036
Smart Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pressure Sensors Market Analytics
The industrial distributor channel is narrowing as direct OEM contracts capture volume from fragmented MRO networks. Honeywell International Inc. leverages its aerospace certification depth to sustain long-term supply agreements with tier-one airframers. Robert Bosch GmbH anchors European automotive programs through captive MEMS fabrication. Sensata Technologies Inc. specializes in high-temperature differential designs for oilfield service companies.
Smart pressure sensors are transducer devices that convert fluid or gas pressure into calibrated electrical signals, typically operating across ranges from millibar to thousands of psi with accuracy grades down to 0.05 percent full scale. They serve process safety, energy efficiency, and closed-loop control functions in continuous manufacturing and mobile equipment. Differential pressure sensors lead installed base volumes in HVAC and flow measurement where stable reference architectures dominate replacement cycles. MEMS technology captures the fastest expansion as wafer-level batch processing collapses unit costs for consumer and automotive scale. Wireless technology concentrates margin pools in predictive maintenance deployments where cabling retrofit economics deter hardwired alternatives.
EPA emissions monitoring mandates and FDA medical device quality system regulations tighten calibration traceability requirements across US industrial and healthcare deployments. CE marking under the EU MDR and REACH substance restrictions shape material selection and market access protocols for European suppliers. NHTSA automotive safety standards and FAA airworthiness directives extend certification burdens that favor established players with dedicated regulatory affairs functions. Stakeholders must weigh certification amortization against volume scalability when selecting technology and geographic priority tiers.
Market Dynamics
MEMS wafer-level batch processing is collapsing unit economics and concentrating procurement power among automotive and consumer electronics OEMs with multi-million-unit annual requirements.
Growth Catalysts
- EPA emissions monitoring mandates:Continuous pressure monitoring requirements in US industrial facilities drive replacement of legacy mechanical gauges with calibrated digital transducers.
- Automotive electrification:Battery thermal management and hydrogen fuel cell systems in Germany and Japan accelerate specification of automotive-grade MEMS units.
- China MIIT dual carbon goals:Industrial energy efficiency audits reshape specifications for process control sensors in steel, cement, and chemical plants.
Market Restraints
- Silicon wafer cost volatility:MEMS die fabrication depends on 200mm and 300mm wafer supply concentrated among Taiwanese and Korean foundries.
- FAA airworthiness certification:Aerospace applications require multi-year validation cycles that freeze design architectures and deter technology refresh.
- Optical pressure sensing substitution:Fiber-optic transducers displace electrical units in explosive atmospheres and high-EMI environments.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for manufacturing localization create first-mover advantage for domestic sensor assembly.
- Predictive maintenance convergence:Wireless IIoT protocols and edge AI analytics open retrofit markets in US oilfield and chemical processing.
- EU F-Gas Regulation:Refrigerant leak detection mandates expand addressable market for HVAC differential pressure sensors.
Industry Challenges
- Calibration technician scarcity:ISO 17025 traceability requirements outpace vocational training program output in mature economies.
- Multi-protocol integration:Legacy 4-20mA installations resist migration to IO-Link and EtherCAT without forklift infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pressure Sensors Market |
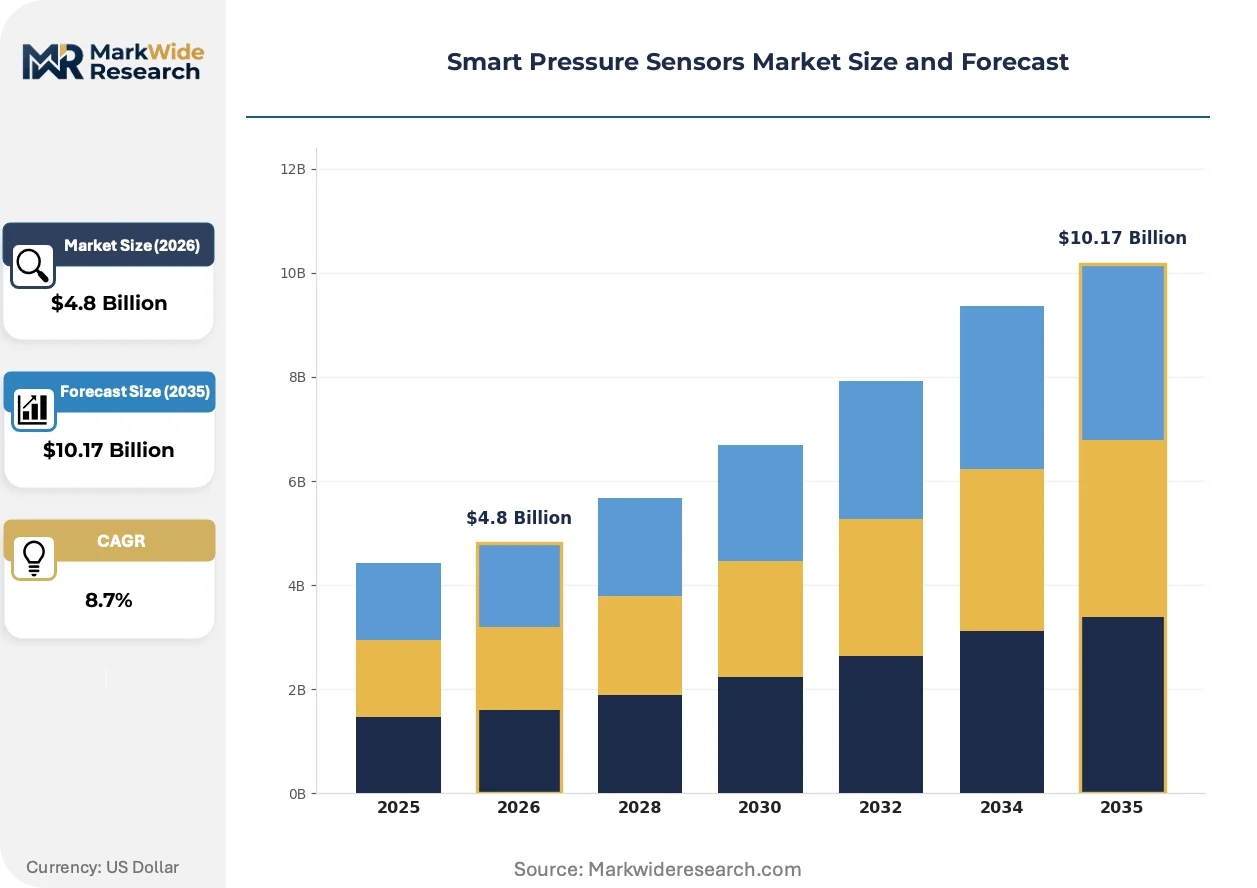
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Pressure Sensors, Gauge Pressure Sensors, Differential Pressure Sensors, Sealed Pressure Sensors Technology: Wireless Technology, Analog Technology, Digital Technology, MEMS Technology End User: Oil & Gas, Manufacturing, Automotive, Aerospace Application: Process Control, Industrial Automation, HVAC Systems, Medical Devices |
| Companies Covered | Honeywell International Inc., TE Connectivity, Robert Bosch GmbH, Infineon Technologies AG, STMicroelectronics, Sensata Technologies Inc., Emerson Electric Co., ABB, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pressure Sensors Market Evolving Landscape
Sensor architectures are fusing multiple physical measurement modalities while wireless connectivity and predictive analytics reconfigure buyer value expectations and channel economics.
Silicon carbide MEMS is hybridizing pressure and temperature sensing in single-die configurations for electric vehicle powertrain monitoring. Tier-one automotive suppliers specify these units for 150°C continuous operation. The convergence is compressing bill-of-materials count and assembly labor content in module production.
EU MDR CE marking requirements for medical devices are tightening calibration traceability and biocompatibility material documentation. European sensor suppliers must maintain notified body relationships across multiple member states. FDA 21 CFR Part 820 quality system alignment is becoming a parallel requirement for dual-continent market access.
Direct OEM contracting is displacing industrial distributor networks for volume sensor procurement. Tier-one automotive and aerospace manufacturers negotiate multi-year supply agreements with dedicated capacity allocation. The shift is most visible in Germany and Japan where captive MEMS fabrication and tiered supplier development programs concentrate sourcing decisions.
Smart Pressure Sensors Market Segmentation
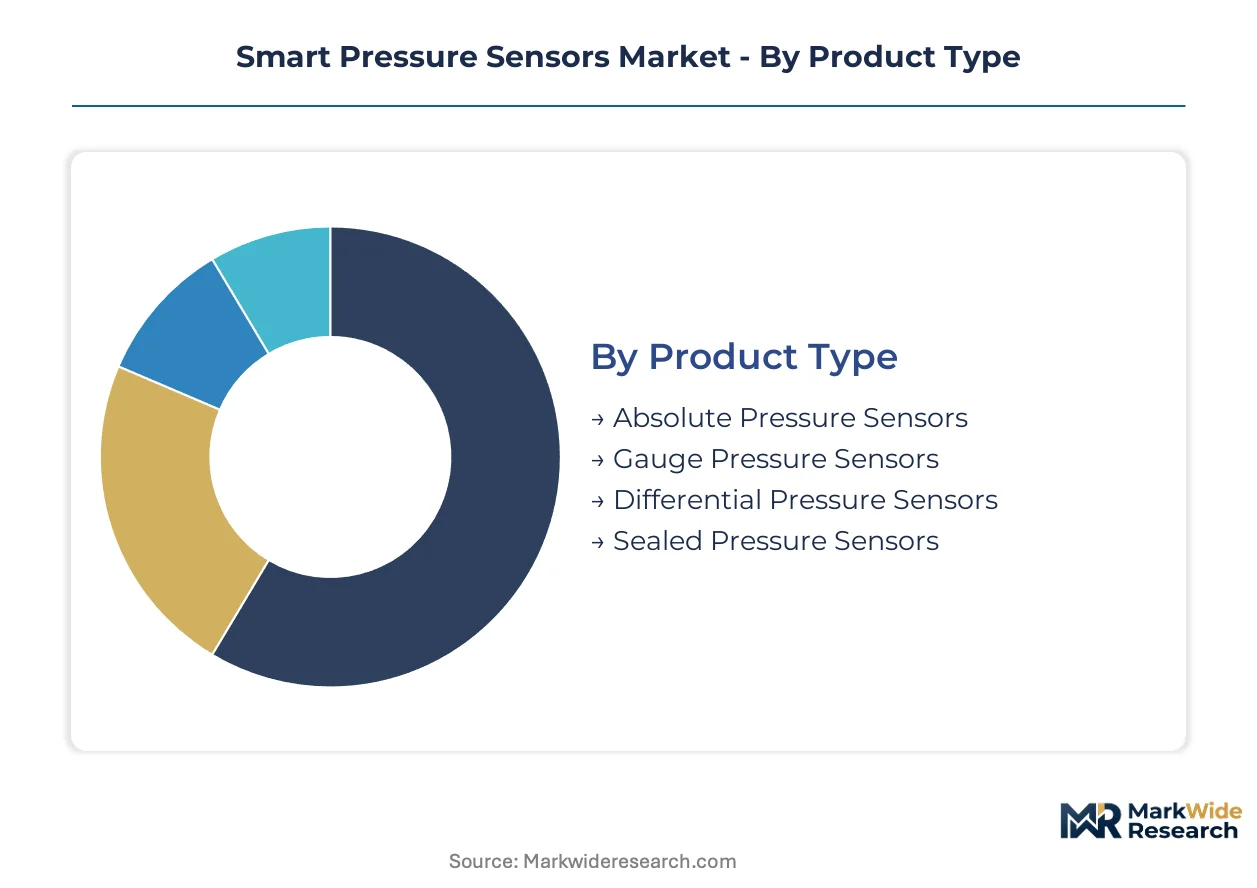
Smart pressure sensors serve divergent performance requirements across automotive underhood conditions, sterile medical environments, and hazardous oilfield settings. Segmentation reveals how MEMS batch processing, wireless retrofit economics, and regulatory certification tiers reshape procurement patterns and margin structures.
Product Type:
Cost tier differentiation separates commodity replacements from precision-calibrated units requiring ISO 17025 traceability and multi-year stability guarantees.
- Differential Pressure Sensors:These devices measure pressure variance between two process points using stable reference architectures. HVAC airflow monitoring and filter condition sensing in US commercial buildings drive replacement cycles, with EPA energy efficiency audits accelerating digital gauge retrofits.
- Absolute Pressure Sensors:Sealed vacuum-reference designs provide barometric and altitude-compensated readings. Automotive engine management in Germany and Japan specifies these for intake manifold and battery thermal management in electrified powertrains.
- Gauge Pressure Sensors:Ventilated reference ports enable atmospheric-differential industrial measurements.
- Sealed Pressure Sensors:Hermetic construction suits submersible and corrosive media applications.
Differential pressure sensors command the established base. The steepest expansion runs through absolute pressure sensors.
Technology:
Application requirements determine whether hardwired reliability or wireless flexibility dominates specification decisions.
- MEMS Technology:Wafer-level silicon micromachining collapses unit costs through batch fabrication of diaphragm-and-resistor structures. Automotive OEMs in Germany and Japan source multi-million-unit annual volumes for battery management and fuel cell systems.
- Wireless Technology:Battery-powered IIoT transmitters eliminate cabling retrofit costs in predictive maintenance deployments. US oilfield service companies specify these for wellhead monitoring where trenching economics deter wired alternatives.
- Analog Technology:4-20mA loops persist in legacy process control infrastructure.
- Digital Technology:IO-Link and EtherCAT interfaces enable edge analytics integration.
Analog technology commands the established base. MEMS technology is gaining share fastest.
End User:
Customer type concentration determines whether procurement flows through industrial distributors or direct OEM negotiations with dedicated capacity allocation.
- Automotive:Tier-one suppliers specify automotive-grade MEMS units for powertrain and thermal management systems. Electrification programs in Germany and Japan are accelerating procurement cycles with multi-year supply agreements.
- Aerospace:FAA airworthiness certification requirements freeze design architectures for multi-year validation cycles. Honeywell and established players sustain long-term contracts with tier-one airframers through dedicated regulatory affairs functions.
- Oil & Gas:High-temperature differential designs monitor wellhead and pipeline conditions.
- Manufacturing:Process control and safety instrumented systems drive industrial demand.
Manufacturing commands the established base. Aerospace is climbing the fastest.
Application:
Volume scale and margin concentration diverge between mature replacement markets and regulated premium-tier deployments.
- Process Control:Continuous pressure monitoring in chemical, steel, and cement plants ensures safety interlocks and energy efficiency. China's MIIT dual carbon goals are reshaping specifications for industrial energy audits.
- Medical Devices:FDA 21 CFR Part 820 quality systems and EU MDR CE marking requirements tighten calibration traceability and biocompatibility documentation. Infusion pumps and ventilators specify premium-grade units with 0.05 percent full-scale accuracy.
- Industrial Automation:Closed-loop control systems integrate pressure feedback for robotics and fluid power.
- HVAC Systems:Refrigerant leak detection mandates under EU F-Gas Regulation expand addressable market for differential pressure airflow sensing.
HVAC systems command the established base. Medical devices show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical throughput infrastructure underwrites European demand for process instrumentation, while China's coastal manufacturing belt and the US Gulf Coast petrochemical corridor anchor transcontinental procurement patterns for calibrated pressure transducers.
United States
FDA medical device standards and FAA aerospace certification drive premium-tier adoption in Boston's medtech cluster and Seattle's airframer supply base. EPA emissions monitoring mandates accelerate digital gauge retrofits across Texas and Louisiana refineries. The Gulf Coast petrochemical corridor concentrates procurement for safety instrumented systems.
Germany
Automotive electrification programs in Stuttgart and Munich accelerate OEM procurement of MEMS-based units for battery thermal management. KBA automotive safety standards and EU F-Gas Regulation shape refrigerant leak detection specifications. Bavaria's automotive supplier belt anchors captive MEMS fabrication capacity.
China
MIIT dual carbon goals reshape industrial sensor specifications in steel, cement, and chemical plants across the Yangtze River Delta. GB standards and SAMR market access protocols tighten calibration traceability requirements. Shanghai's process automation cluster drives specification shifts for energy efficiency audits.
Japan
METI industrial efficiency directives and hydrogen fuel cell deployment targets accelerate specification of automotive-grade MEMS units in Nagoya's automotive belt. JIS standards and PMDA medical device regulations govern precision instrument quality. Osaka's sensor fabrication corridor concentrates tier-one supplier development programs.
India
PLI scheme incentives for manufacturing localization create first-mover advantage for domestic sensor assembly in Gujarat and Tamil Nadu. BIS standards and CEA industrial efficiency mandates reshape procurement for process control infrastructure. Pune's automotive component cluster drives MEMS specification for electrification programs.
Smart Pressure Sensors Market Competitive Landscape
On the supply side, the industry is bifurcating between scale-driven MEMS fabricators serving automotive volume programs and precision specialists capturing aerospace and medical premium tiers. Diversified industrial conglomerates occupy mid-market process control segments through bundled automation offerings. Strategic moves concentrate on backward integration into wafer-level MEMS fabrication and dedicated capacity allocation through multi-year OEM supply agreements.
Within the diversified industrial tier, Honeywell International Inc. and Emerson Electric Co. exemplify archetypes that leverage regulatory certification depth to sustain long-term contracts with tier-one airframers and process operators. Robert Bosch GmbH anchors European automotive programs through captive MEMS fabrication in Germany's automotive supplier belt. These three represent distinct strategic positions: certification-driven aerospace primacy, integrated automation systems bundling, and captive vertical manufacturing for automotive scale.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| TE Connectivity |
| Robert Bosch GmbH |
| Infineon Technologies AG |
| STMicroelectronics |
| Sensata Technologies Inc. |
| Emerson Electric Co. |
| ABB |
| Siemens |
| Others |
Value Network & Pricing Analysis
Taiwanese and Korean foundry concentration for 200mm and 300mm silicon wafers concentrates upstream margin capture, while downstream value pools sit with automotive OEMs negotiating multi-year MEMS supply agreements and aerospace tier-one airframers paying certification premiums. MEMS batch processing economics collapse unit costs at volume, yet precision-calibrated units for FDA and FAA applications sustain three-tier pricing separation across premium, standard, and economy performance grades.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with automotive OEMs in Germany and Japan extracting steep unit economics for multi-million-piece annual MEMS commitments. Price differentiation hinges on certification grade—FDA 21 CFR Part 820 and FAA airworthiness tiers command substantial premiums over industrial-grade CE-marked units—and volume scale, where wafer-level batch fabrication rewards million-unit purchasers. Cost compression in consumer and automotive tiers intensifies as foundry capacity expands, while medical device and aerospace buyers exhibit lowest price sensitivity due to regulatory switching costs and qualification timelines.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard negotiating leverage for tier-one automotive and aerospace OEMs squeezing working capital from upstream MEMS fabricators. Manufacturing concentrates in Taiwan, South Korea, and Germany—foundry wafers draw from East Asian silicon processing, while captive MEMS fabrication anchors in Bavaria's automotive supplier belt. Raw material dependencies span high-purity silicon substrates, specialized packaging ceramics, and biocompatible coatings for medical grades. Single-source vulnerability runs through Taiwanese 300mm wafer supply exposed to geopolitical friction. Distribution runs through direct OEM contracting that displaces fragmented industrial distributor networks for volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart pressure sensors sit in early-cycle expansion as MEMS batch processing penetrates automotive electrification programs and wireless IIoT retrofit economics open predictive maintenance white space. Battery thermal management and hydrogen fuel cell specification in Germany and Japan represent the clearest near-term adoption tailwind.
For Market Incumbents: Entrench regulatory certification depth as the primary defensive moat against optical pressure sensing substitution in explosive atmospheres. Prioritize backward integration into wafer-level MEMS fabrication to defend margin position against foundry cost volatility, while locking multi-year supply agreements with dedicated capacity allocation for tier-one automotive OEMs in Stuttgart and Munich. For New Entrants and Emerging Players: Build out wireless IIoT sensor assembly capabilities targeting US oilfield service companies where trenching economics deter wired retrofits. India offers the most penetrable geography—PLI scheme incentives for manufacturing localization in Gujarat and Tamil Nadu create first-mover advantage for domestic sensor assembly without competing head-to-head with established MEMS foundry scale. For Investors and Strategic Acquirers: Capital is best deployed toward precision-calibration specialists with ISO 17025 traceability infrastructure and existing FDA or FAA certification relationships, as these capabilities require multi-year investment cycles that deter rapid replication. Long-term viability over the next decade favors suppliers with dual medical-aerospace regulatory competence. Monitor automotive OEM electrification program acceleration as the critical inflection signal—sustained battery thermal management specification expansion would validate MEMS volume scalability assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Capacity | Captures wafer-level margin pools and insulates against Taiwanese supply concentration risk. |
| Multi-Year OEM Supply Agreement | Locks dedicated capacity allocation with tier-one automotive manufacturers in Germany and Japan. |
| FDA 21 CFR Part 820 Quality System Investment | Opens premium medical device tier with infusion pump and ventilator specification opportunities. |
| Wireless IIoT Protocol Certification | Enables predictive maintenance retrofit sales to US oilfield and chemical processing operators. |
| India PLI Scheme Manufacturing Localization | Captures first-mover advantage in domestic sensor assembly for industrial automation demand. |
Research Methodology
Operator-level perspectives from MEMS fabrication engineers, automotive tier-one procurement directors, aerospace regulatory affairs managers, and oilfield instrumentation specialists anchored the qualitative base. Primary interview findings were cross-validated against secondary sources including EPA emissions monitoring filings, FDA 510(k) device submissions, EU MDR notified body documentation, and MIIT industrial efficiency audit protocols. Bottom-up unit economics modeling triangulated against top-down market sizing across MEMS wafer throughput estimates and automotive electrification program forecasts.
Scenario-bracketing framed the analytical approach, with baseline, accelerated electrification, and supply-constrained variants tested across the projection horizon. Segmentation dimensions modeled include product type tier, technology architecture, end-user industry concentration, and application regulatory intensity. CAGRs were derived from installed base replacement cycles, electrification program procurement timelines, and wireless retrofit penetration curves. Industry-specific forecast inputs incorporated automotive battery thermal management sensor content per vehicle and EU F-Gas Regulation refrigerant leak detection mandate implementation pace.
Stress conditions across silicon wafer price volatility, FAA certification timeline extension, and optical sensing substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about MEMS batch processing cost trajectories and automotive electrification program commitment durability. Macroeconomic contraction, regulatory harmonization delays, or breakthrough fiber-optic sensing cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Torque Sensor Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
US Occupancy Sensors Market
Sensors and Controls
Laser Scanner Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
Laser Displacement Sensor Market