
 Screenless Display Market | 2026-2036
Screenless Display Market Size, Share, and Industry Trends Forecast 2026-2036
Screenless Display Market Intelligence
The divergence in R&D spending on volumetric versus retinal projection technologies is bifurcating the competitive landscape. Microsoft Corporation leverages its extensive software ecosystem to integrate holographic displays into enterprise applications. Specialists like RealView Imaging Ltd. and Holoxica Ltd. focus on developing proprietary holographic projection systems for medical imaging. Magic Leap Inc. competes by creating integrated hardware and software platforms for spatial computing.
A screenless display is a visual information system that projects images directly onto a medium, such as the user's retina, open space, or a physical object, without a physical screen. These systems utilize technologies like laser plasma or optical waveguides to create volumetric or holographic images for immersive user experiences. Holographic projection currently leads in commercial applications, particularly in advertising and medical visualization. However, retinal projection technologies represent the fastest-growing segment, driven by developments in wearable devices for consumer electronics.
Product development must adhere to laser safety regulations, such as those overseen by the FDA in the United States and the IEC 60825 standard internationally. Devices for consumer electronics must comply with electromagnetic compatibility rules, including FCC Part 15 and Europe's CE marking requirements. Navigating the evolving intellectual property landscape around light field and holographic patents remains a critical strategic decision for all market participants.
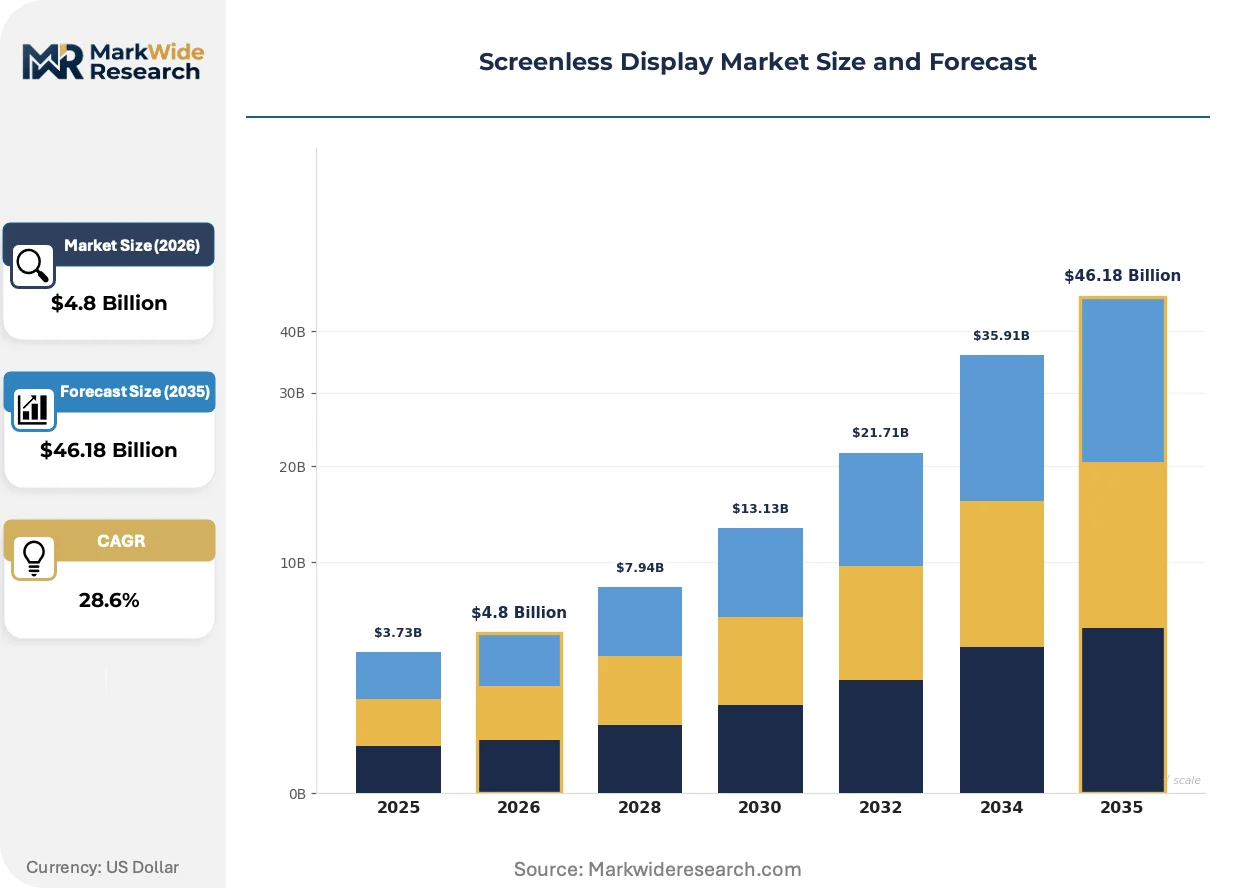
Market Dynamics
The screenless display market is defined by the technological divergence between retinal projection and volumetric display systems. This bifurcation creates distinct R&D, supply chain, and application development pathways, influencing the entire competitive landscape and investment priorities across the industry.
Growth Catalysts
- Component Miniaturization:Advances in the fabrication of optical waveguide components enable smaller, more energy-efficient projection systems, accelerating integration into wearable devices and automotive head-up displays.
- Aviation Sector Demand:Adoption within the aviation navigation sector for enhanced pilot situational awareness provides a high-value, stable demand stream for holographic projection technologies.
- Defense and Research Investment:Strong and consistent demand from defense agencies and national research institutions, particularly in the United States and Germany, funds foundational R&D in advanced holographic and volumetric imaging.
Market Restraints
- Stringent Laser Safety Regulations:Compliance with standards like IEC 60825 and FDA regulations for laser-based products imposes significant design constraints and testing costs, particularly for direct-to-retina projection systems.
- High System Development Costs:The substantial investment required to develop proprietary medical-grade holographic imaging systems creates high barriers to entry for new firms and limits scalability.
- Fidelity and Latency Issues:Volumetric displays face technical hurdles in achieving the resolution, color depth, and refresh rates necessary to compete with conventional high-definition screens, limiting current applications.
Strategic Opportunities
- Consumer Wearable Integration:Retinal projection technology is positioned for significant growth through integration into next-generation smart glasses and augmented reality headsets for the consumer electronics market.
- Enterprise Spatial Computing:The convergence of holographic displays with AI and cloud computing opens opportunities for immersive enterprise applications in remote collaboration, training, and complex data visualization.
- Automotive Head-Up Displays:Augmented reality head-up displays (AR-HUDs) that project navigation and safety information directly onto the windshield represent a major growth vector in the automotive industry.
Industry Challenges
- Intellectual Property Navigation:The dense and overlapping patent landscape for light field and holographic projection technologies creates a complex and contentious environment, posing significant legal risks for market participants.
- Lack of Interoperability Standards:A absence of common standards for spatial computing platforms hinders the development of a unified application ecosystem, creating friction for developers and end-users.
- Electromagnetic Compatibility Compliance:Meeting electromagnetic compatibility rules, such as FCC Part 15 in the US and CE marking in Europe, is a critical and often time-consuming challenge for consumer-facing devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screenless Display Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holographic Projection, Light Field Display, Retinal Projection, Audio Display, Electromagnetic Resonance Technology: Volumetric, Laser Plasma, Ultrasound-Based, Electrostatic, Optical Waveguide Application: Consumer Electronics, Aviation Navigation, Military Training, Wearable Devices, Smart Home Systems End User: Tech Manufacturers, Defense Agencies, Research Institutions, Lifestyle Brands, Entertainment Studios |
| Companies Covered | RealView Imaging Ltd., Synaptics Incorporated, Microsoft Corporation, Holoxica Ltd., EON Reality Inc., Sony Corporation, Magic Leap Inc., Leia Inc., Avegant Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screenless Display Market Strategic Shifts & Innovations
Product development is shifting from a focus on hardware specifications toward the creation of integrated software and hardware ecosystems. This transition prioritizes user experience and application utility, expanding the market beyond niche technical use cases into broader enterprise and consumer segments.
Optical waveguides are critical components that direct light from a source to create an image in the user's field of view. The consumer electronics and automotive sectors are rapidly exploring these components for next-generation products. This technological progress is miniaturizing the overall form factor of AR glasses and head-up displays, which is essential for mass-market acceptance.
Global standards, particularly IEC 60825, govern the safety of laser products and are paramount for screenless displays. The standard mandates rigorous classification and testing, directly influencing device design and power output limitations to ensure user safety. Retinal projection systems are most affected, as they must operate within strict, eye-safe power envelopes, driving innovation in low-power light sources.
A notable behavioral shift among enterprise buyers is the preference for complete platform solutions over standalone display hardware. This change disrupts the business model for component-focused manufacturers, creating an advantage for vendors who offer integrated spatial computing systems with robust developer support. The trend is most prominent in the medical visualization and industrial design verticals in North America and Europe.
Screenless Display Market Segmentation
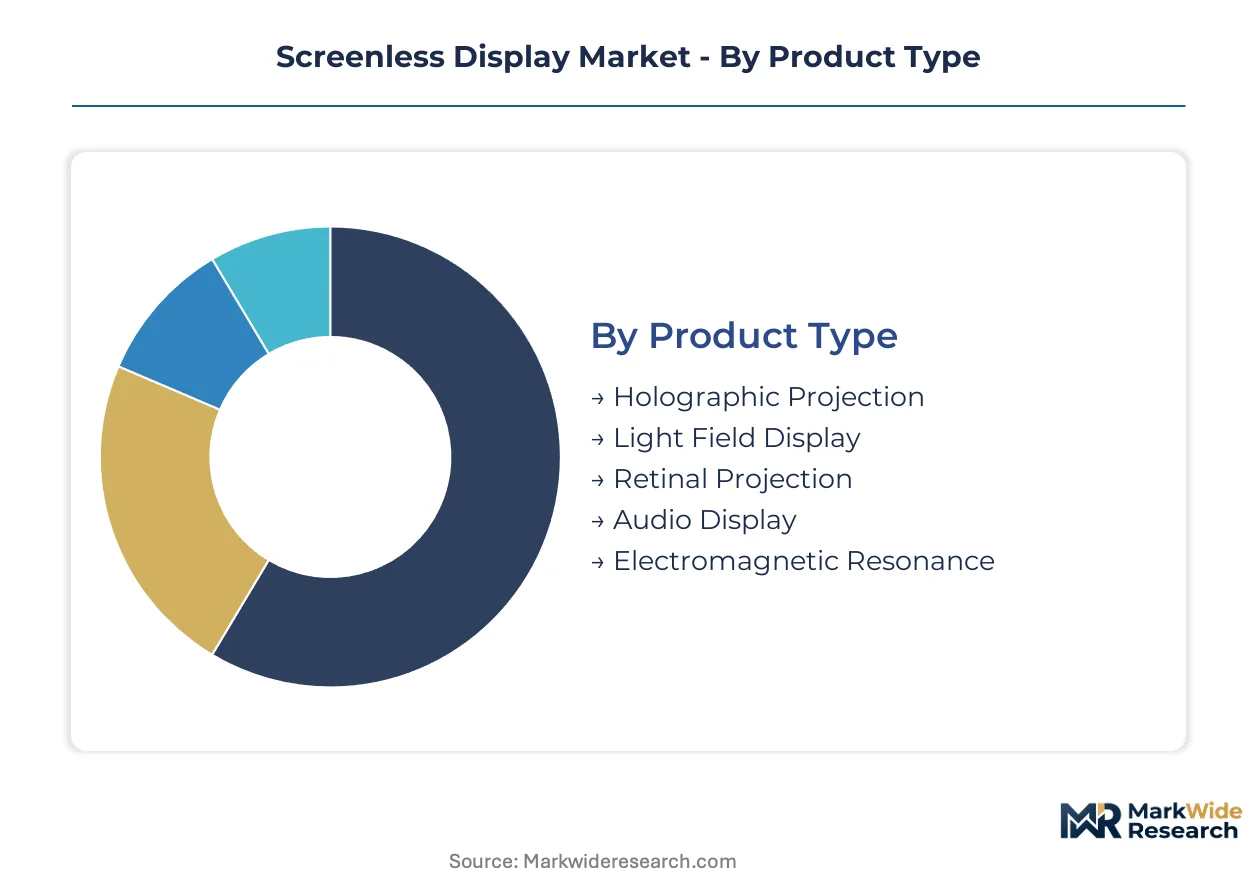
The screenless display market segmentation provides a granular view of distinct product types, underlying technologies, diverse applications, and specific end-user groups. This detailed classification highlights varied regulatory landscapes, technological maturity levels, and specific demand drivers shaping the industry's evolution.
Product Type:
Product type segmentation highlights varying regulatory compliance pathways for screenless display technologies.
- Holographic Projection:This technology creates three-dimensional images in free space using light interference patterns. Commercial applications in advertising and medical visualization drive demand for these systems.
- Retinal Projection:This method projects images directly onto the user's retina, providing highly immersive visual experiences. Wearable devices for consumer electronics represent the fastest-growing segment for retinal projection.
- Light Field Display:Light field displays generate three-dimensional images without requiring special glasses, capturing light from multiple angles.
- Audio Display:Audio displays create localized sound fields without physical speakers, primarily for specialized user interfaces in public spaces.
- Electromagnetic Resonance:This technology projects images onto surfaces using electromagnetic fields, enabling interactive displays for smart environments.
Established volume favors Holographic Projection; emerging adoption favors Retinal Projection.
Technology:
Technology segmentation reveals the core engineering principles underpinning diverse screenless display applications.
- Optical Waveguide:Optical waveguides efficiently direct light from a source to create an image within the user's field of view. Miniaturization of these components accelerates integration into wearable devices and automotive head-up displays.
- Volumetric:Volumetric displays create three-dimensional images that occupy a physical volume in space, allowing viewing from multiple angles. Defense agencies and research institutions in the United States fund foundational R&D for volumetric systems.
- Laser Plasma:Laser plasma technology generates display points by ionizing air with high-power lasers, forming free-space images.
- Ultrasound-Based:Ultrasound-based systems use acoustic radiation pressure to create tactile feedback for virtual objects, enhancing interactive experiences.
- Electrostatic:Electrostatic technology employs electrostatic forces to manipulate light, particularly for creating haptic feedback in advanced display systems.
Technological maturity varies significantly across these approaches, influencing market readiness and investment profiles.
Application:
Application segmentation highlights distinct demand drivers and user requirements across various industry verticals.
- Aviation Navigation:This application integrates holographic projections into cockpit systems, enhancing pilot situational awareness with critical flight data. This sector provides a high-value, stable demand stream for advanced display solutions.
- Consumer Electronics:Consumer electronics incorporates retinal projection into smart glasses and augmented reality headsets for immersive user experiences. This segment is positioned for significant growth through next-generation wearable devices.
- Military Training:Military training utilizes volumetric displays and holographic simulations for realistic training scenarios for defense personnel.
- Wearable Devices:Wearable devices integrate screenless display technologies into smartwatches and head-mounted displays for personal information access.
- Smart Home Systems:Smart home systems employ projected interfaces and spatial computing for intuitive control of home automation and entertainment.
High-value enterprise applications contrast with mass-market consumer adoption, shaping revenue streams and product roadmaps.
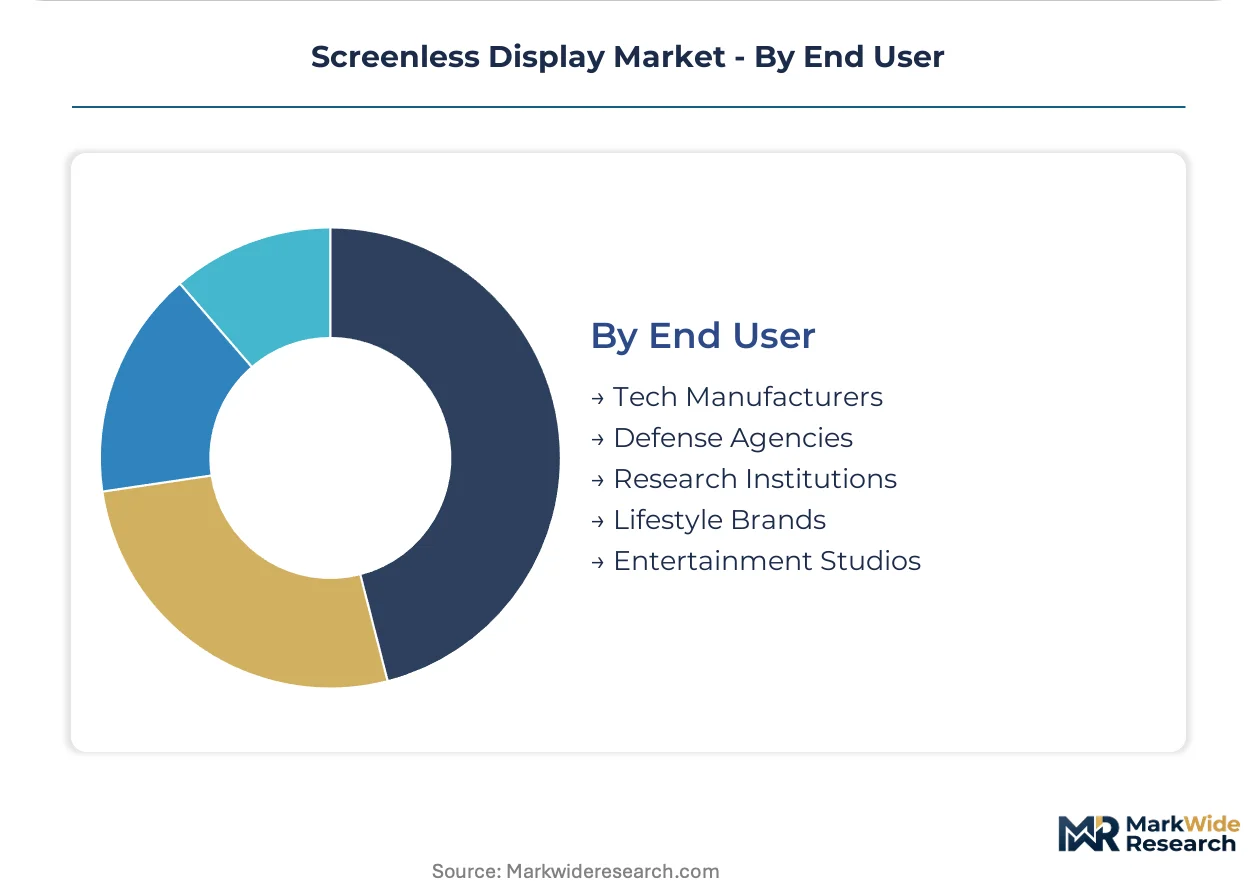
End User:
End user segmentation reflects diverse purchasing behaviors and specific functional requirements for screenless display solutions.
- Defense Agencies:Defense agencies procure advanced holographic and volumetric imaging systems for military training, intelligence, and operational planning applications. Strong and consistent demand from the United States and Germany funds foundational R&D.
- Tech Manufacturers:Tech manufacturers integrate screenless display components into their product lines, particularly for consumer electronics and automotive applications. This group prioritizes miniaturization and cost-effective production.
- Research Institutions:Research institutions drive foundational R&D in advanced display technologies, often collaborating with defense and medical sectors.
- Lifestyle Brands:Lifestyle brands explore innovative display solutions for advertising, immersive retail experiences, and product differentiation strategies.
- Entertainment Studios:Entertainment studios adopt screenless displays for creating interactive exhibits, virtual reality experiences, and advanced stage productions.
Specialized institutional buyers drive innovation, while commercial entities focus on market integration and scalable solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry is evident between the United States and emerging Asian markets. North American and European regions command higher margins due to advanced R&D and specialized applications. Asian manufacturing hubs focus on cost-effective component production and scalable consumer device integration.
United States
Demand for screenless displays stems from defense agencies and enterprise spatial computing applications. FDA regulations strictly govern laser safety for direct-to-retina projection systems. Silicon Valley and Boston serve as innovation hubs for integrated hardware-software platforms and advanced research.
Germany
Strong investment from research institutions and the automotive sector drives screenless display adoption. The IEC 60825 standard ensures laser product safety for advanced optical systems. Munich and Stuttgart concentrate on AR-HUD development and industrial design applications, fostering significant R&D.
Japan
Consumer wearable integration and automotive head-up displays are primary demand drivers. METI provides guidance on electromagnetic compatibility for electronic devices. Tokyo's tech clusters foster innovation in retinal projection and optical waveguide miniaturization for mass-market products.
China
The rapidly expanding consumer electronics market fuels demand for smart glasses and immersive advertising. GB standards ensure product quality and safety for screenless display components. Shenzhen's manufacturing ecosystem supports high-volume production of display modules for global distribution.
France
Aviation navigation and military training applications generate demand for holographic projection technologies. The EU CE marking requirements ensure compliance for advanced display systems. Toulouse's aerospace industry integrates screenless displays into next-generation cockpits and simulation environments.
Screenless Display Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes in the screenless display market. The competitive structure is bifurcated, with large technology conglomerates pursuing broad market integration and specialized innovators focusing on proprietary advancements. Strategic archetypes include integrated platform providers, niche medical imaging specialists, and component miniaturization experts. Companies primarily engage in strategic partnerships for ecosystem expansion and targeted technology licensing to secure intellectual property.
Among firms focused on integrated platforms, Microsoft Corporation exemplifies a strategy leveraging an extensive software ecosystem to embed holographic displays into enterprise applications. RealView Imaging Ltd. represents specialists developing proprietary holographic projection systems, particularly for medical imaging. Magic Leap Inc. occupies a position as an innovator creating integrated hardware and software platforms for spatial computing, targeting both enterprise and consumer sectors. These companies demonstrate varied approaches to market penetration, from broad software integration to specialized hardware development.
| Leading Market Players |
|---|
| RealView Imaging Ltd. |
| Synaptics Incorporated |
| Microsoft Corporation |
| Holoxica Ltd. |
| EON Reality Inc. |
| Sony Corporation |
| Magic Leap Inc. |
| Leia Inc. |
| Avegant Corporation |
| Others |
Cost & Logistics Intelligence
Miniaturization of optical waveguide components drives scale economies, concentrating specialized manufacturing in Asian hubs and establishing a global price floor for mass-market screenless display components. This efficiency enables broader adoption but also tightens margins for lower-tier products.
Pricing Analysis
Configured-to-order pricing for medical-grade holographic systems commands a premium due to specialized FDA certification and extensive after-sales service. Value-based pricing dominates enterprise spatial computing solutions, reflecting integration complexity and bespoke software development. Pricing pressure stems from component commoditization in consumer electronics, where volume scale is the primary differentiation driver. Tech manufacturers are most price-sensitive, while defense agencies prioritize capability over cost.
Supply Chain Analysis
The Strait of Malacca transit underpins the global flow of optical waveguide components, creating a logistics chokepoint for screenless display manufacturing. Production concentrates in China and Japan, which supply critical laser diodes and specialized optical films. Single-source vulnerability for advanced projection modules represents a structural risk. Distribution runs through integrated tech manufacturers and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The screenless display market presents a defensive moat, primarily due to regulatory entrenchment around laser safety standards. This creates high barriers to entry for new firms, particularly in medical and aviation applications.
For Market Incumbents: Shield core intellectual property through aggressive patent enforcement against light field and holographic technology infringements. Deepen vertical integration into optical waveguide component manufacturing to secure critical supply and control costs against emerging component suppliers. The threat of new entrants leveraging open-source software platforms demands continuous R&D investment in proprietary algorithms.
For New Entrants and Emerging Players: Lack of interoperability standards for spatial computing platforms creates an opportunity for new entrants to provide unified software development kits. Target the consumer electronics segment, particularly in smart glasses, with cost-effective retinal projection modules. A go-to-market angle focuses on partnerships with lifestyle brands for integrated AR experiences.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform providers capable of delivering complete hardware-software solutions. Long-term viability hinges on companies with robust intellectual property portfolios and established regulatory compliance. Acquire specialists in optical waveguide miniaturization or advanced holographic algorithms. The signal to watch is the widespread adoption of a single spatial computing standard.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Open-Source Spatial Computing SDK | This fosters a broader developer ecosystem for screenless display applications. |
| Invest in Eye-Safe Laser Technology R&D | This ensures compliance with IEC 60825 standards for retinal projection systems. |
| Form Automotive AR-HUD Partnerships | This expands market penetration into the high-growth automotive head-up display sector. |
| Acquire Medical Imaging Software Firm | This strengthens capabilities in specialized holographic visualization for healthcare. |
| Expand Manufacturing Capacity in Southeast Asia | This diversifies the supply chain for optical waveguide components and reduces costs. |
Research Approach
Desk research of academic journals, patent databases, and regulatory body publications preceded structured interviews with optical engineers, defense procurement officers, and consumer electronics product managers. This approach combined primary insights with secondary validation, ensuring comprehensive data coverage. Bottom-up market sizing was triangulated with top-down industry reports to refine initial estimates.
Variance decomposition identified key drivers impacting screenless display market growth across the analysis window. Segmentation dimensions modeled included product type, technology, application, and end-user, alongside regional adoption patterns. Compound Annual Growth Rates were derived from historical data analysis and projected technological advancements. Key inputs included R&D spending on optical waveguides and regulatory approvals for laser-based systems.
Underlying assumptions cover technological maturity and regulatory stability, with deviation risk concentrated in rapid shifts in consumer preferences or unforeseen supply chain disruptions. Forecasts reflect these assumptions, but market dynamics are sensitive to new patent disputes. Practitioners should keep alternative scenarios live as technological breakthroughs and geopolitical factors evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Projector Market
Display Technologies
Digital Holographic Display Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Phosphor Screen Market
Display Technologies
Global Monochrome Display Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Global Display Controllers Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Global Industrial Display System Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Global UHD Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Smart Screen Market
Display Technologies
Graphic LCD Modules Market