
 Global Photonic Crystal Displays Market | 2026-2036
Global Photonic Crystal Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photonic Crystal Displays Market Outlook
The EU Green Deal is shifting procurement criteria across European consumer electronics retailers toward low-power display architectures. LG Display leverages its Gyeonggi-based manufacturing complex to sustain volume leadership in OLED-photonic crystal hybrid panels. Samsung Display anchors its competitive position through vertical control over active-matrix backplane production. Corning Incorporated differentiates via captive glass-substrate engineering optimized for photonic crystal lattice integration.
Photonic crystal displays exploit periodic dielectric nanostructures to manipulate light propagation, achieving sub-wavelength confinement with refractive index contrasts typically engineered through silicon or polymer multilayer deposition. These architectures serve primarily to eliminate color filters and polarizers, cutting optical losses by half in reflective and transmissive modes. MicroLED implementations command the deepest margin pools due to epitaxial precision requirements and military-aerospace qualification premiums. OLED-photonic crystal hybrids represent the fastest-expanding segment as automotive HUD and AR waveguide adoption accelerates. Nanotechnology-based fabrication lines remain capacity-constrained, creating supply bottlenecks for sub-10 nanometer feature definitions.
The US EPA Energy Star program and Korea's MEET standards jointly shape efficiency benchmarks for commercial display deployments, while REACH compliance in Europe restricts certain photoresist chemistries used in nanoimprint lithography. China's MIIT enforces domestic content ratios for public-sector display procurement, redirecting supply chain investments toward local photonic crystal foundries. Stakeholders must monitor which regulatory jurisdiction first mandates circularity reporting for nanostructured optical components, as this will cascade into design-for-recyclability requirements across all major export markets.
Market Dynamics
Photonic crystal display architectures face a binding constraint from nanoimprint lithography throughput limits, as sub-10 nanometer feature definitions require multi-step patterning cycles that stretch lead times and concentrate output among a handful of captive foundries.
Growth Catalysts
- EU Ecodesign mandates:Energy efficiency requirements for consumer electronics are redirecting retailer procurement toward reflective display architectures that eliminate backlight power draw.
- Automotive HUD adoption:German and Japanese OEMs are expanding specifications for photonic crystal-enhanced instrument clusters to achieve sunlight-readable luminance without thermal management penalties.
- Gyeonggi Province manufacturing corridor:Concentrated deposition equipment and metrology expertise in South Korea's display belt is yielding yield improvements for OLED-photonic crystal hybrid stacks.
Market Restraints
- Epitaxial precursor cost volatility:Organometallic source materials for III-nitride microLED emitters exhibit price swings tied to rare earth supply quotas.
- Nanoimprint mask supply concentration:Master template fabrication for photonic crystal lattices depends on a single German optics cluster, creating single-point vulnerability.
- REACH photoresist restrictions:ECHA limitations on fluorinated chemistries are forcing reformulation of high-aspect-ratio etch masks, extending process qualification timelines.
Strategic Opportunities
- China domestic content mandates:MIIT procurement rules for public-sector displays are redirecting capital toward local photonic crystal foundry construction in Hefei and Shenzhen.
- AR waveguide convergence:Photonic crystal outcoupling gratings are displacing conventional diffractive optics in near-eye displays for industrial training applications.
- Direct-to-OEM component sales:Bypassing panel integrators to supply photonic crystal films directly to automotive Tier-1s captures margin previously absorbed by display module assemblers.
Industry Challenges
- Nanofabrication talent scarcity:Cleanroom process engineering expertise for dielectric multilayer deposition remains concentrated among retiring cohorts at legacy semiconductor research institutes.
- Cross-jurisdiction circularity compliance:Anticipated EU reporting mandates for nanostructured optical component recyclability are forcing premature design-for-disassembly investments ahead of harmonized standards.
- Active-matrix backplane integration:Matching photonic crystal color-filterless architectures to existing thin-film transistor drive schemes requires custom pixel circuit redesigns that fragment panel development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photonic Crystal Displays Market |
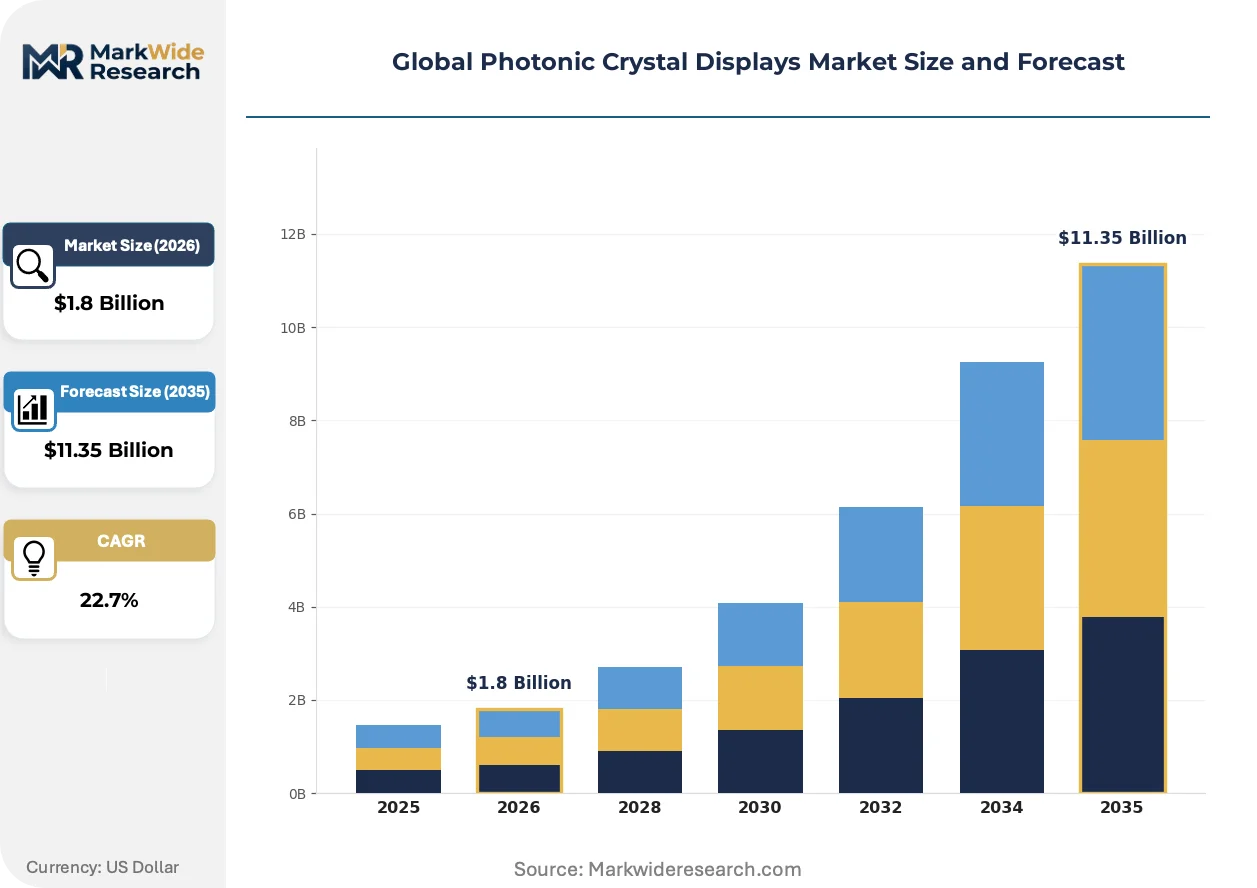
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
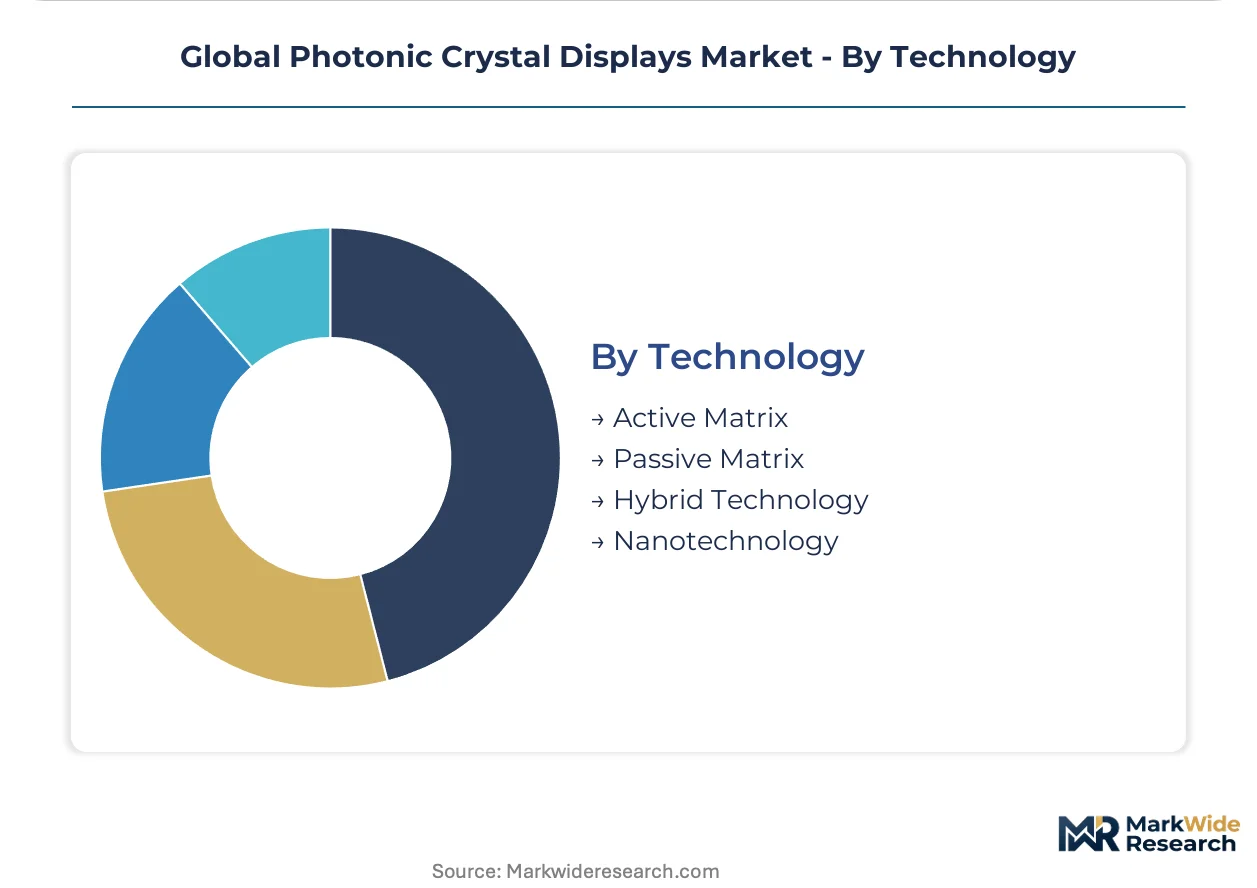
| Segmentation | Product Type: LCD, OLED, MicroLED, ePaper Application: Consumer Electronics, Automotive Displays, Medical Imaging, Augmented Reality End User: Retail, Education, Healthcare, Industrial Technology: Active Matrix, Passive Matrix, Hybrid Technology, Nanotechnology |
| Companies Covered | LG Display, Panasonic Holdings Corporation, Corning Incorporated, Lockheed Martin, Philips Lumileds Lighting Company, Opalux, NKT Photonics, Agilent Technologies, Samsung Display, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photonic Crystal Displays Market Strategic Shifts
Photonic crystal display technology is undergoing a phase transition from laboratory demonstration to manufacturing-scale deployment, with three converging forces determining which architectures achieve commercial escape velocity.
Silicon-compatible photonic crystal lattices are consolidating as the dominant platform for microLED color conversion, replacing quantum dot films in applications requiring narrow emission linewidths. Automotive HUD suppliers in Germany are qualifying these structures for mass production. The technology is consolidating supplier bases by collapsing separate color conversion and light extraction layers into single nanostructured films.
China's dual carbon goals and Korea's MEET standards are jointly tightening power density limits for commercial display installations, creating regulatory pull for reflective-mode photonic crystal architectures that operate without backlighting. Panel manufacturers are responding by accelerating R&D partnerships with nanofabrication equipment vendors. Public-sector procurement in China is most affected, with domestic content ratios redirecting supply chain investments toward local photonic crystal foundries.
Automotive OEMs are unbundling display subsystem procurement from traditional panel integrators, establishing direct material qualification relationships with photonic crystal film suppliers. Tier-1 electronics suppliers are losing specification control as German and Japanese vehicle manufacturers issue component-level technical requirements. This pattern is most visible in premium electric vehicle programs, where instrument cluster differentiation drives early adoption of unconventional optical stacks.
Global Photonic Crystal Displays Market Segmentation
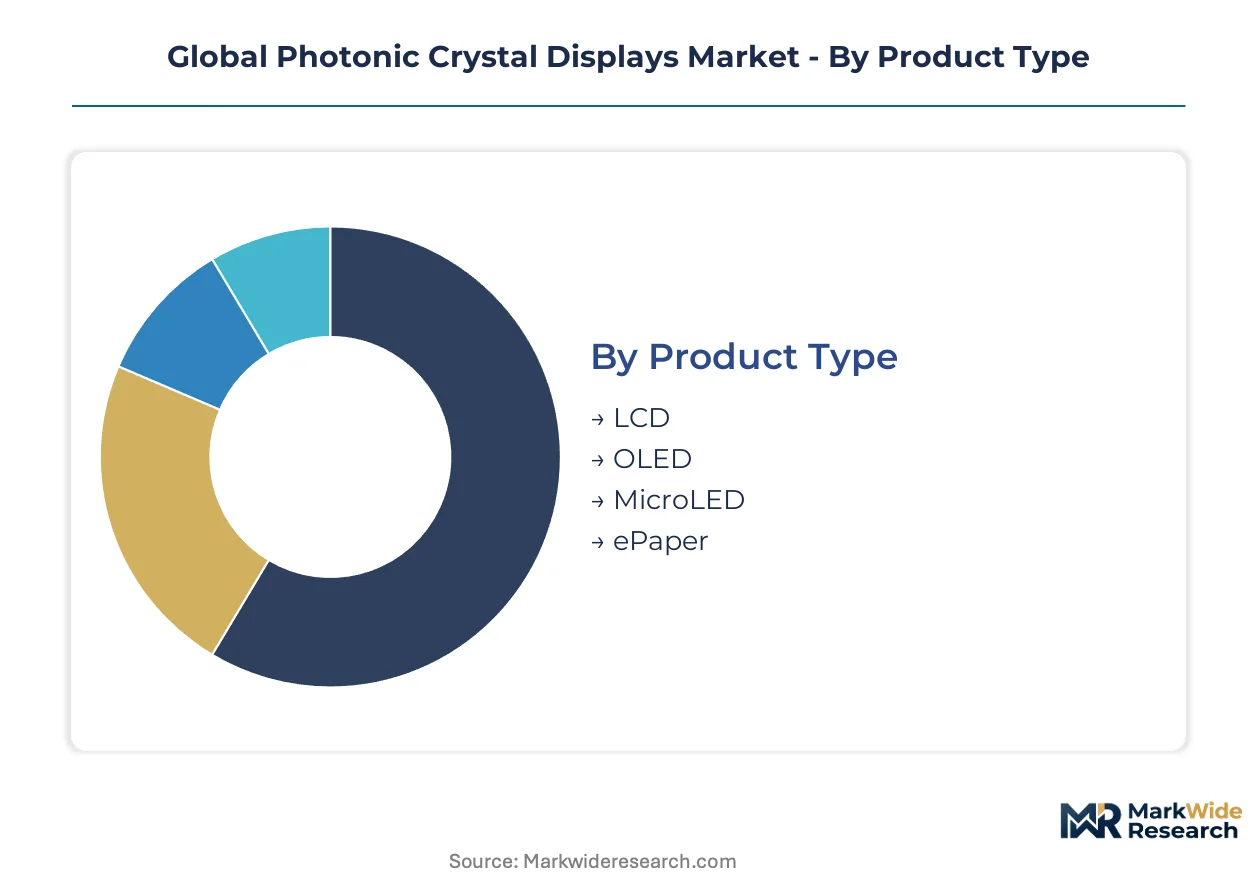
Photonic crystal display architectures diverge sharply across product and application boundaries. Technical requirements for nanostructure precision, drive electronics compatibility, and optical efficiency create distinct competitive dynamics within each segment category.
Product Type:
Standardization dominates LCD and ePaper implementations, while OLED and MicroLED demand extensive customization for photonic crystal lattice integration.
- LCD:Photonic crystal-enhanced LCDs replace conventional color filters with periodic dielectric nanostructures etched directly onto glass substrates. Automotive instrument cluster procurement in Germany concentrates demand for these reflective-mode architectures that eliminate backlight power draw entirely.
- OLED:Hybrid OLED-photonic crystal stacks integrate nanostructured outcoupling layers above organic emissive stacks. Gyeonggi Province manufacturing complexes in South Korea anchor volume production for these architectures as automotive HUD specifications tighten luminance requirements without thermal penalties.
- MicroLED:III-nitride emitters paired with silicon-compatible photonic crystal lattices achieve sub-10 nanometer linewidth color conversion. Military-aerospace qualification premiums sustain margin pools despite epitaxial precursor cost volatility.
- ePaper:Reflective photonic crystal architectures enable sunlight-readable electronic ink without frontlight power consumption. Public-sector signage procurement in China favors these configurations under dual carbon compliance mandates.
Most installed capacity flows through OLED. Expansion is steepest in MicroLED.
Application:
Volume scales inversely with performance requirements across this category, with consumer electronics absorbing commoditized output and AR systems commanding precision premiums.
- Consumer Electronics:Smartphones and tablets drive baseline demand for photonic crystal color-filterless LCDs. EU Ecodesign mandates redirect retailer procurement toward these low-power architectures across European consumer electronics distribution channels.
- Automotive Displays:German and Japanese OEMs specify photonic crystal-enhanced instrument clusters and HUD systems for premium electric vehicle programs. Direct component-level procurement from film suppliers is displacing traditional Tier-1 integration relationships.
- Medical Imaging:Diagnostic displays require nanostructure uniformity beyond standard commercial specifications. FDA device classification timelines extend qualification cycles for photonic crystal architectures in radiology workstations.
- Augmented Reality:Near-eye waveguide systems exploit photonic crystal outcoupling gratings to replace conventional diffractive optics. Industrial training applications in manufacturing facilities concentrate early adoption before consumer AR scale.
Consumer Electronics absorbs the largest volume share. Augmented Reality is climbing the fastest as waveguide designs converge on photonic crystal architectures.
End User:
Procurement sophistication varies dramatically, with Industrial and Healthcare buyers imposing qualification regimes that Retail and Education segments rarely match.
- Retail:Digital signage and point-of-sale displays prioritize cost minimization over optical precision. Reflective photonic crystal configurations without backlighting reduce total cost of ownership for 24-hour operation.
- Education:Interactive whiteboards and classroom displays represent emerging demand for sunlight-readable reflective architectures. Budget constraints limit adoption to premium institutional installations.
- Healthcare:Diagnostic imaging and surgical visualization impose stringent color accuracy and luminance stability requirements. Photonic crystal implementations must navigate FDA premarket notification pathways distinct from consumer display certifications.
- Industrial:HMI panels and process control displays demand extended temperature operation without thermal management complexity. Photonic crystal reflective modes eliminate cooling infrastructure in factory environments.
Retail commands the deepest volume. Healthcare is gaining share fastest through diagnostic imaging upgrades.
Technology:
Manufacturing maturity separates established active-matrix backplane integration from emerging nanotechnology fabrication approaches still constrained by throughput limits.
- Active Matrix:Thin-film transistor drive schemes require custom pixel circuit redesigns to match photonic crystal color-filterless architectures. Samsung Display's captive backplane production anchors competitive positioning in this configuration.
- Passive Matrix:Simplified drive electronics suit low-resolution signage and simple indicator applications. Cost advantages erode as active-matrix yields improve for mid-size panels.
- Hybrid Technology:Combinations of passive and active addressing optimize for specific illumination patterns in automotive HUD applications. German OEM specifications favor these architectures for instrument cluster differentiation.
- Nanotechnology:Sub-10 nanometer feature definitions through nanoimprint lithography enable the highest-efficiency photonic crystal lattices. Master template fabrication concentration in a single German optics cluster creates supply vulnerability.
Active Matrix carries the majority of installed capacity. Nanotechnology is expanding most quickly despite fabrication bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photonic crystal display manufacturing originated in Japanese and South Korean electronics corridors during the early 2000s, with subsequent scaling concentrated in East Asian deposition equipment clusters. Today, regulatory energy efficiency mandates across multiple jurisdictions are redirecting capital toward reflective-mode architectures that eliminate backlight power consumption entirely.
United States
Military-aerospace procurement sustains demand for microLED photonic crystal implementations requiring narrow emission linewidths. The EPA Energy Star program tightens commercial display efficiency benchmarks annually. Greater Boston hosts specialized nanofabrication research institutes supplying process engineering talent to captive foundry operations.
Germany
Automotive OEMs in Stuttgart and Munich specify photonic crystal-enhanced instrument clusters for premium electric vehicle programs. REACH compliance through ECHA restricts fluorinated photoresist chemistries used in nanoimprint lithography mask fabrication. The Jena optics cluster concentrates master template production for sub-10 nanometer photonic crystal lattice definitions.
China
Public-sector signage procurement under MIIT domestic content mandates redirects supply chain investments toward local photonic crystal foundry construction. Dual carbon goals enforce power density limits for commercial display installations. Hefei and Shenzhen manufacturing complexes scale deposition equipment for reflective-mode ePaper architectures.
South Korea
Gyeonggi Province manufacturing corridors anchor volume production of OLED-photonic crystal hybrid stacks for automotive HUD applications. Korea's MEET standards shape efficiency benchmarks alongside US EPA programs. Suwon and Asan host concentrated metrology expertise yielding yield improvements for nanostructured outcoupling layers.
Japan
METI industrial policy supports photonic crystal integration into next-generation display export platforms. Japanese OEMs in Toyota City and Hiroshima expand procurement specifications for sunlight-readable instrument clusters. Kyushu-based deposition equipment vendors supply multi-step patterning systems to captive foundries worldwide.
Global Photonic Crystal Displays Market Competitive Environment
Premium-margin players sit above commodity-margin players across nanofabrication precision tiers, with microLED qualification premiums separating military-aerospace suppliers from consumer electronics fabricators. The vendor base concentrates among display panel integrators with captive backplane production and specialized photonic crystal film suppliers serving direct automotive Tier-1 relationships. Three archetypes dominate: vertically integrated Korean panel manufacturers, German optics cluster precision fabricators, and US defense-aerospace qualification specialists. Competitive moves center on direct-to-OEM component sales bypassing traditional integrators and nanoimprint lithography capacity expansion to relieve sub-10 nanometer throughput bottlenecks.
Within the vertically integrated tier, Samsung Display and LG Display exemplify scale-driven positioning through captive thin-film transistor backplane production. Corning Incorporated represents the materials engineering archetype, with glass-substrate optimization for photonic crystal lattice integration anchoring its competitive differentiation. These three companies occupy positions spanning consumer electronics volume and automotive specification control.
| Leading Market Players |
|---|
| LG Display |
| Panasonic Holdings Corporation |
| Corning Incorporated |
| Lockheed Martin |
| Philips Lumileds Lighting Company |
| Opalux |
| NKT Photonics |
| Agilent Technologies |
| Samsung Display |
| Others |
Value Chain & Pricing Dynamics
Nanoimprint lithography throughput limits for sub-10 nanometer feature definitions simultaneously compress margin structures and concentrate output among captive foundries, reshaping both cost economics and supplier power dynamics across photonic crystal display architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by nanofabrication precision and qualification tier. Premium microLED implementations command the highest price points due to military-aerospace certification requirements, while reflective ePaper configurations compete on volume scale. Cost compression in standard-tier OLED-photonic crystal hybrids is intensifying because nanoimprint mask supply bottlenecks extend lead times. Retail signage buyers exhibit the greatest price sensitivity, whereas German automotive OEMs prioritize optical performance over unit cost.
Supply Chain Analysis
China's MIIT domestic content mandates for public-sector display procurement are redirecting capital toward local photonic crystal foundry construction in Hefei and Shenzhen, fragmenting sourcing patterns established by South Korean and Japanese manufacturing corridors. Master template fabrication draws from a single German optics cluster in Jena, creating single-source vulnerability for sub-10 nanometer lattice definitions. Distribution runs through panel integrators with captive backplane production, though direct-to-OEM component sales are displacing traditional Tier-1 relationships in automotive specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Photonic Crystal Displays Market functions as a stable compounder, with regulatory energy efficiency mandates across multiple jurisdictions providing durable demand tailwinds for reflective-mode architectures.
For Market Incumbents: Cement specification control by deepening captive nanoimprint lithography capacity to relieve sub-10 nanometer throughput constraints. Lock in direct component-level procurement relationships with German and Japanese automotive OEMs before emerging film suppliers qualify for HUD programs. Defend against margin erosion from epitaxial precursor cost volatility through long-term organometallic source material offtake agreements.
For New Entrants and Emerging Players: Enter via AR waveguide outcoupling gratings for industrial training applications, where photonic crystal architectures are displacing conventional diffractive optics before consumer scale. Target China's domestic content mandates by establishing local foundry partnerships in Hefei or Shenzhen for public-sector ePaper procurement. Lead with nanofabrication equipment vendor relationships to bypass panel integrator qualification timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized photonic crystal film suppliers lacking captive backplane integration but holding direct automotive Tier-1 relationships. The long-term viability window favors acquisition targets with qualified nanoimprint master template fabrication capabilities, given Jena cluster concentration risk. Watch for the first regulatory jurisdiction mandating circularity reporting for nanostructured optical components as an inflection signal for design-for-recyclability investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Nanoimprint Lithography Capacity Expansion | Relieves throughput bottlenecks for sub-10 nanometer photonic crystal lattice production. |
| Direct-to-OEM Component Supply Agreement | Bypasses panel integrators to capture margin from German automotive HUD specifications. |
| Domestic Content Compliance Partnership | Aligns with China's MIIT procurement rules for public-sector reflective display installations. |
| Master Template Fabrication Acquisition | Secures supply resilience against Jena optics cluster single-point vulnerability. |
| Reflective Architecture R&D Collaboration | Accelerates EU Ecodesign-compliant color-filterless LCD qualification for retailer procurement. |
Study Parameters
Direct dialogue with nanofabrication process engineers, automotive Tier-1 procurement directors, display panel integration specialists, and regulatory affairs leads at ECHA and EPA combined with secondary validation from SEC 10-K filings, customs deposition equipment trade data, EU Ecodesign directive documentation, and Korea MEET standard filings. Bottom-up and top-down triangulation anchored volume estimates across the analysis window.
Bottom-up modeling of unit economics by product type, application, and technology tier integrated with top-down macro constraint analysis. Segmentation dimensions included display architecture, end-use vertical, manufacturing technology maturity, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to disclosed capacity expansion timelines and procurement contract visibility. Epitaxial precursor cost trajectories and nanoimprint lithography yield improvement curves served as industry-specific forecast inputs.
Inputs from OEM procurement databases and foundry equipment order backlogs were available through the study window; gaps in sub-10 nanometer master template production capacity data introduce uncertainty bands around microLED segment projections. Forecasts reflect assumptions regarding REACH photoresist reformulation timelines and dual carbon goal enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
AMOLED Substrate Market
Display Technologies
Field Emission Display Market
Display Technologies
Asia-Pacific Industrial Display Market
Display Technologies
Industrial Display Market
Display Technologies
Volumetric Display Market
Display Technologies
Video Projector Market
Display Technologies
Electrochromic Window Market
Display Technologies
Smart Display Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Global Next Generation Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Projector Screen Market
Display Technologies
Phosphor Screen Market
Display Technologies
8K Display Resolution Market
Display Technologies
Visual Computing Market