
 AMOLED Display Market | 2026-2036
AMOLED Display Market Size, Share, and Industry Trends Forecast 2026-2036
AMOLED Display Market Intelligence
EU F-Gas Regulation is repositioning the cost structure for AMOLED manufacturing equipment and etching gases across European-bound supply chains. Samsung Display leverages vertical integration from substrate to module assembly, sustaining its technology leadership in flexible panel architectures. BOE Technology Group anchors massive Gen-6 production lines in China, while LG Display competes through specialized OLED-on-glass solutions for premium television applications.
Active-matrix organic light-emitting diode displays employ thin-film transistor backplanes to drive individual organic pixels, achieving contrast ratios exceeding one million to one through emissive architecture that eliminates backlight requirements. Flexible technology leads volume shipments as foldable smartphones penetrate premium tiers, whereas rigid panels occupy cost-sensitive mid-range handset segments. Transparent AMOLED variants remain nascent but attract enterprise interest for automotive HUD and retail showcase integrations where see-through functionality commands design premiums.
EPA guidelines on volatile organic compound emissions constrain solvent-based photoresist processes in US-bound manufacturing, while REACH and RoHS frameworks in Europe restrict heavy metal content in phosphorescent emitter complexes. China's GB standards and MIIT directives enforce domestic recycling quotas for display modules, tightening material recovery obligations. Stakeholders must monitor divergence between regional chemical compliance regimes when siting deposition and encapsulation capacity.
Market Dynamics
Flexible substrate technology is compressing rigid panel margins while East Asian supply clusters concentrate deposition equipment procurement, creating a bifurcation between premium foldable architectures and commodity handset displays.
Growth Catalysts
- EU F-Gas Regulation:Equipment manufacturers are retrofitting etching gas recovery systems to maintain European market access, accelerating capital deployment toward compliant deposition tools.
- Foldable smartphone penetration:Device makers are expanding flexible panel orders as hinge mechanisms and ultra-thin glass mature, pulling substrate and encapsulation capacity toward rollable form factors.
- Phosphorescent emitter complexes:Material suppliers are scaling iridium and platinum-doped organic compounds that boost power efficiency in high-resolution mobile displays.
Market Restraints
- Input cost volatility:Indium tin oxide sputtering targets and rare-earth dopants face price swings tied to Chinese export quotas, squeezing backplane deposition margins.
- Supply concentration risk:Canon Tokki and Ulvac hold dominant positions in vapor deposition equipment, creating single-source vulnerability for Gen-8.5 fab expansions.
- Technical limitation:Blue emitter lifetime degradation remains unresolved in tandem OLED stacks, constraining brightness targets for automotive exterior lighting applications.
Strategic Opportunities
- India PLI scheme:Display module assembly incentives are attracting component suppliers to establish bonding and driver IC integration facilities near handset manufacturing clusters.
- Transparent AMOLED:See-through panels are penetrating automotive head-up display and retail showcase installations where optical transparency commands design premiums.
- Micro-LED convergence:Hybrid manufacturing processes combining OLED deposition with micro-LED transfer are emerging for ultra-high-brightness signage and cinema applications.
Industry Challenges
- Thin-film transistor engineering talent:Foundry operators face shortages of process engineers skilled in low-temperature polysilicon and oxide semiconductor backplane fabrication.
- Encapsulation barrier certification:Multi-layer thin-film sealing must pass accelerated lifetime testing under IEC standards before automotive and medical device qualification.
- Legacy LCD fab conversion:Retooling Gen-8.5 TFT-LCD lines for AMOLED requires complete replacement of exposure and etching equipment, extending payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AMOLED Display Market |
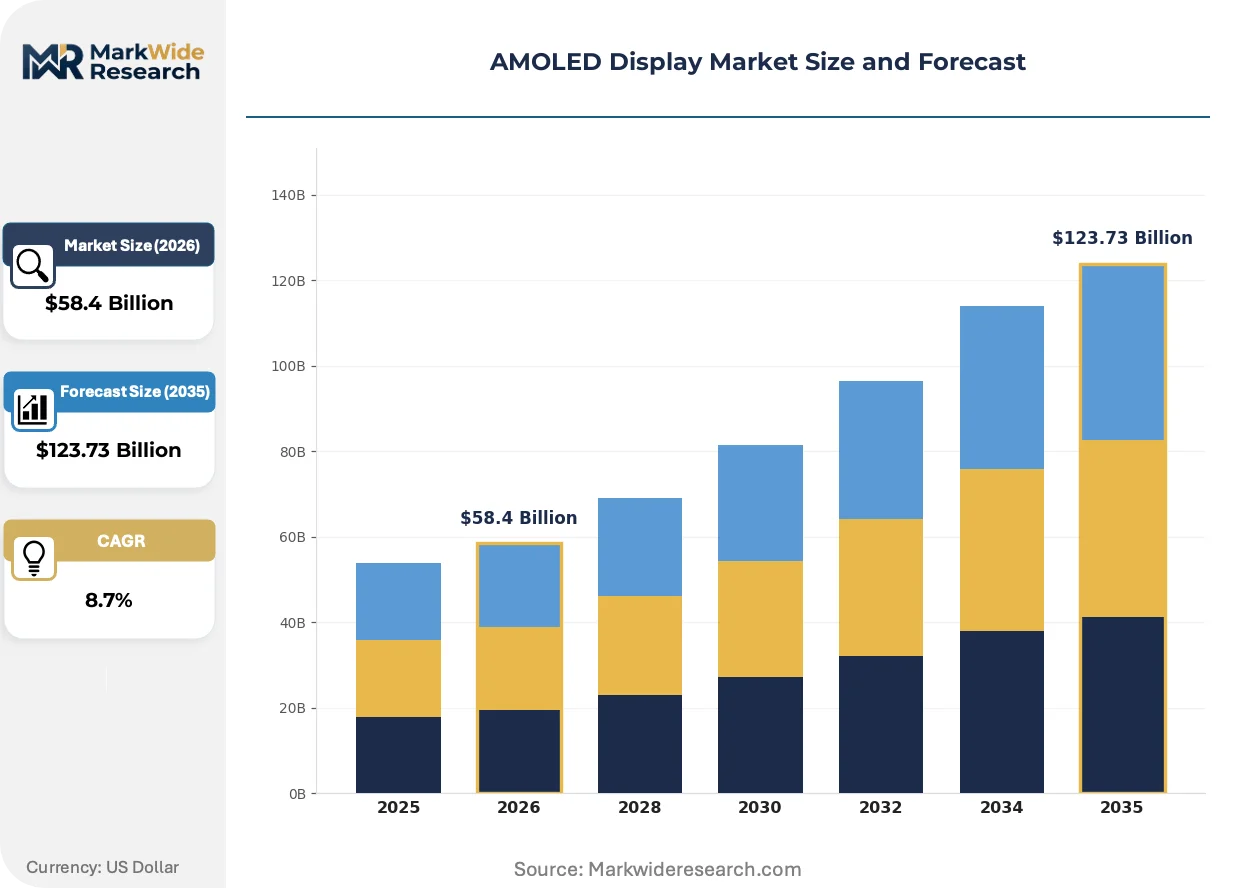
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, TVs, Wearables End User: Consumers, Enterprises, OEMs, Retailers Technology: Flexible, Rigid, Transparent, Microdisplays Application: Gaming, Entertainment, Advertising, Digital Signage |
| Companies Covered | China Star Optoelectronics Technology, EverDisplay Optronics, Samsung Display, Visionox Information Technology, CSOT, LG Display, Tianma Microelectronics, AU Optronics, BOE Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AMOLED Display Market Strategic Shifts & Innovations
Material substitution and deposition precision are redefining manufacturing economics, while regulatory chemical restrictions and buyer consolidation reshape competitive positioning across the value chain.
LTPO (low-temperature polycrystalline oxide) backplane technology is integrating variable refresh rate control with power-efficient pixel driving. Smartwatch and flagship smartphone makers are adopting hybrid oxide-poly silicon architectures to extend battery endurance. This integration is compressing demand for conventional LTPS-only panels in premium tiers.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of photoresist stripping solvents and planarization materials. European panel importers must certify supply chains against Substances of Very High Concern candidate lists. Display chemical suppliers are accelerating fluorine-free etchant development to preserve automotive and medical device market access.
Brand-led direct sourcing of display modules is bypassing traditional ODM intermediaries in handset supply chains. Samsung Electronics and Apple are negotiating directly with Samsung Display and BOE for customized flexible panel specifications. This pattern concentrates volume commitments among top-tier panel makers while marginalizing second-source suppliers in South Korea and China.
AMOLED Display Market Segmentation
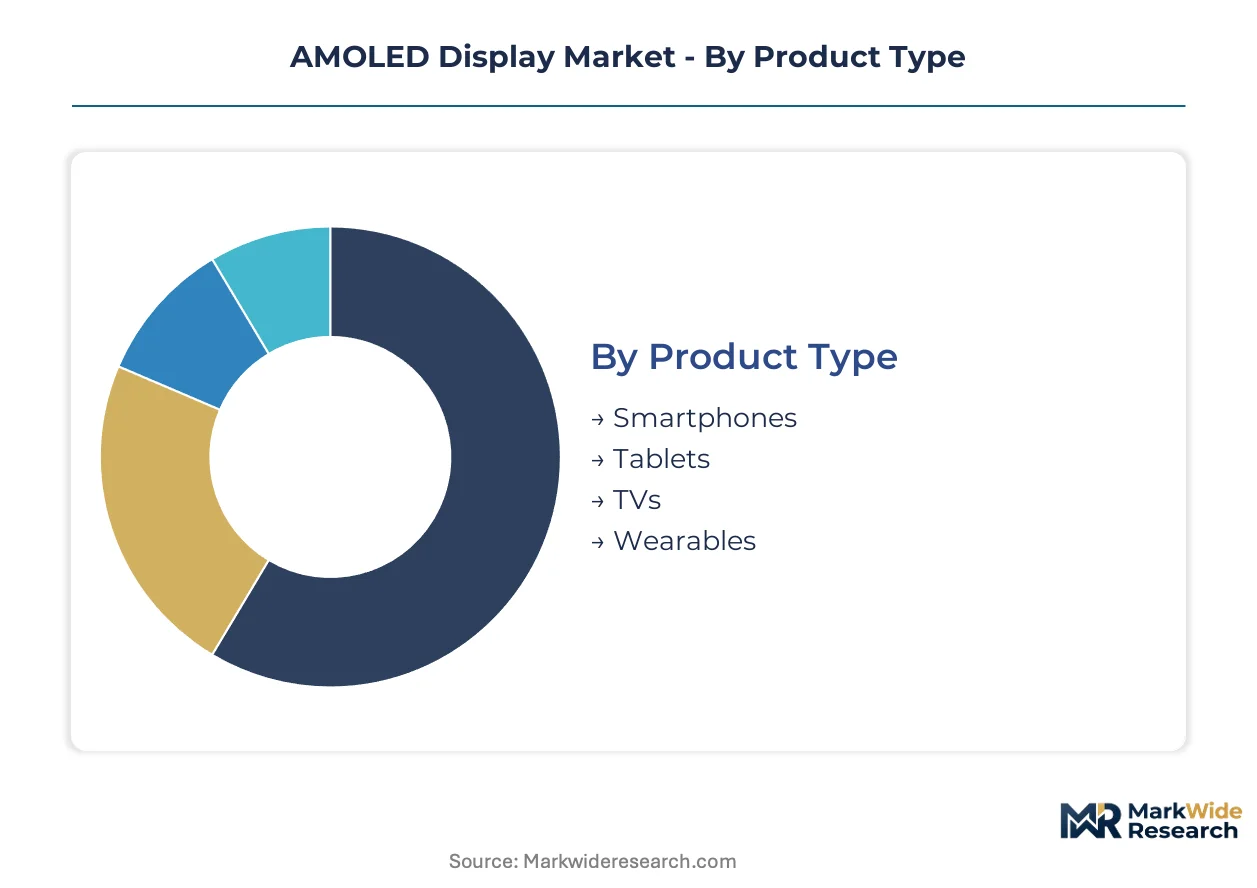
AMOLED display procurement patterns diverge sharply across device categories, with upgrade cycles and replacement demand dictating substrate specifications and volume commitments. Panel makers calibrate deposition capacity and encapsulation investments against the refresh velocity of each downstream segment.
Product Type:
Smartphone replacement cycles averaging 24-36 months compress procurement windows and intensify competition for flagship flexible panel allocations.
- Smartphones:Flexible substrate panels dominate flagship tier volumes, with LTPO backplane integration extending battery endurance in high-refresh-rate configurations. Samsung Electronics and Apple directly negotiate customized flexible specifications with Samsung Display and BOE, bypassing traditional ODM intermediaries.
- Tablets:Rigid AMOLED substrates retain cost advantages in mid-range education and enterprise deployments where foldability adds limited functional value. BOE anchors Gen-6 production lines to serve domestic Chinese tablet brands expanding display procurement.
- TVs:LG Display specializes in OLED-on-glass architectures for premium residential installations, leveraging white-OLED with color filter approaches distinct from mobile RGB patterning.
- Wearables:Compact form factors demand specialized microdeposition equipment and ultra-thin encapsulation barriers for smartwatch and fitness tracker integration.
Volume placements concentrate in smartphones; the faster expansion belongs to wearables as health-monitoring functionality extends device attach rates.
End User:
Procurement authority consolidation among device OEMs is compressing margin capture for downstream intermediaries and reshaping contract structures.
- Consumers:Direct retail purchases drive flagship smartphone panel specifications, with brand loyalty translating into premium flexible substrate commitments and extended color-gamut requirements.
- Enterprises:Ruggedized tablet and wearable deployments prioritize encapsulation reliability over optical performance, with automotive and medical device qualification timelines extending procurement cycles.
- OEMs:Module assembly integration near handset manufacturing clusters in India leverages PLI scheme incentives, attracting driver IC and bonding equipment suppliers to establish regional capacity.
- Retailers:Digital signage and showcase installations command transparent AMOLED variants where see-through functionality supports experiential merchandising strategies.
Contract concentration favors OEM direct sourcing; retailers represent the most price-elastic demand tier with project-based procurement patterns.
Technology:
Substrate flexibility determines equipment depreciation schedules and encapsulation complexity, creating divergent capital intensity profiles across deposition architectures.
- Flexible:Polyimide substrate handling with laser lift-off separation enables foldable and rollable form factors, though ultra-thin glass cover lens integration adds yield complexity. Foldable smartphone penetration pulls substrate and encapsulation capacity toward hinge-compatible architectures.
- Rigid:Glass substrate retention suits cost-sensitive mid-range handset segments where mechanical durability requirements exceed flexibility needs. South Korean and Chinese display clusters concentrate rigid panel deposition equipment procurement.
- Transparent:Partially transparent cathode structures and optimized pixel aperture ratios enable automotive HUD and retail showcase applications commanding design premiums.
- Microdisplays:Silicon backplane integration supports AR/VR headset requirements with pixel densities exceeding conventional TFT limitations.
Flexible technology commands the steepest capacity expansion trajectory; rigid substrates defend volume share in emerging market handset tiers.
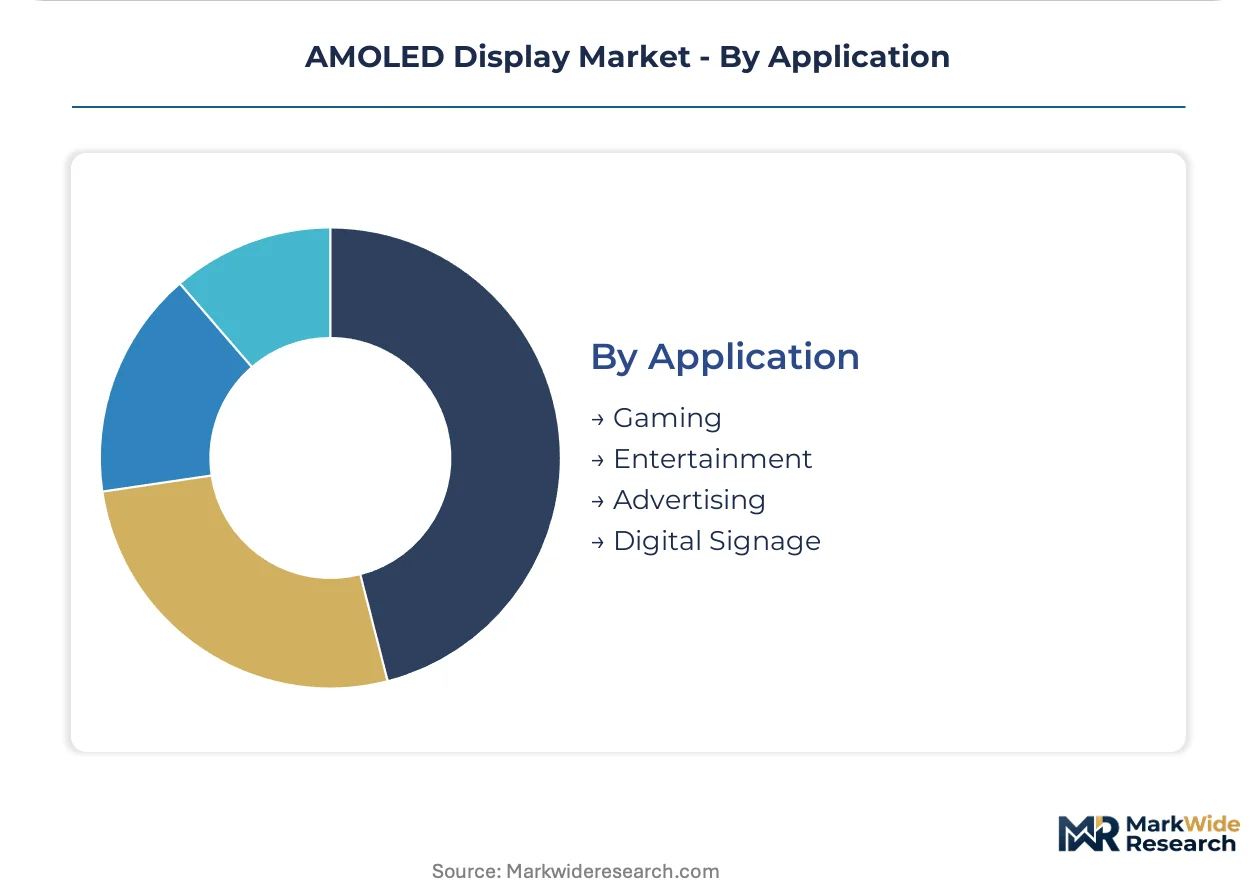
Application:
Content consumption intensity and ambient lighting conditions dictate brightness targets, emitter stack configurations, and thermal management requirements across use cases.
- Gaming:High-refresh-rate panels with sub-10ms response times prioritize motion clarity over power efficiency, with phosphorescent emitter complexes improving luminance stability during extended sessions.
- Entertainment:Cinema and streaming applications leverage HDR10+ certification and expanded color volume for premium television and tablet experiences.
- Advertising:Outdoor digital signage demands tandem OLED stacks or hybrid micro-LED convergence for sunlight-readable brightness levels exceeding mobile panel specifications.
- Digital Signage:Transparent AMOLED installations in retail and corporate environments balance optical transparency with sufficient emissive brightness for content visibility.
Gaming applications set the most aggressive refresh-rate specifications; digital signage offers the clearest path for transparent technology commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device OEM procurement decisions concentrate display module sourcing in East Asian manufacturing clusters, with South Korea and China commanding deposition equipment and substrate handling capacity. Flagship smartphone launches in North America and Europe pull flexible panel shipments from these supply bases, while domestic content requirements in India reshape final assembly geography.
South Korea
Samsung Electronics and Apple source customized flexible specifications directly from domestic panel producers, bypassing traditional ODM intermediaries. The MFDS enforces medical device qualification timelines for AMOLED integration in diagnostic equipment. Gyeonggi Province hosts concentrated vapor deposition equipment procurement and laser lift-off separation facilities serving foldable smartphone programs.
China
Domestic handset brands expand rigid and flexible panel procurement from Gen-6 production lines anchored in Beijing and Hefei. MIIT directives enforce GB standards compliance and domestic recycling quotas for display modules under circular economy frameworks. The Yangtze River Delta cluster concentrates driver IC integration and bonding equipment capacity for tablet and wearable applications.
United States
EPA guidelines constrain solvent-based photoresist processes in manufacturing facilities supplying North American device assembly. The FCC regulates electromagnetic emissions from AMOLED-integrated mobile devices entering commercial distribution. California-based technology OEMs negotiate directly with East Asian panel makers for LTPO backplane specifications in premium smartphone tiers.
Japan
METI coordinates national strategy for next-generation display manufacturing equipment and materials chemistry development. JIS standards govern encapsulation barrier performance for automotive and industrial AMOLED deployments. The Chubu region around Nagoya maintains specialized microdeposition equipment production for wearable and microdisplay applications.
India
The PLI scheme attracts display module assembly and driver IC integration facilities near handset manufacturing clusters in Uttar Pradesh and Tamil Nadu. BIS certification requirements tighten incoming quality controls for panel imports bound for domestic OEM integration. Noida and Chennai industrial corridors concentrate bonding equipment deployment and final module qualification capacity.
AMOLED Display Market Key Industry Players
South Korean producers anchor the premium flexible tier; Chinese specialists hold volume positions in rigid and mid-range flexible segments. The vendor base separates into three distinct strata: vertically integrated substrate-to-module operators, deposition equipment-dependent fabricators, and specialized microdisplay developers. Strategic moves concentrate on direct OEM contracting relationships and LTPO backplane technology licensing rather than capacity expansion alone.
Among Korea-based integrated producers, Samsung Display and LG Display occupy positions defining industry archetypes for flexible substrate handling and OLED-on-glass architectures respectively. BOE Technology Group represents the scale-driven Chinese tier with Gen-6 line deployment. Tianma Microelectronics exemplifies specialized positioning in compact wearable and automotive display segments.
| Leading Market Players |
|---|
| China Star Optoelectronics Technology |
| EverDisplay Optronics |
| Samsung Display |
| Visionox Information Technology |
| CSOT |
| LG Display |
| Tianma Microelectronics |
| AU Optronics |
| BOE Technology Group |
| Others |
Cost & Logistics Intelligence
Flexible-versus-rigid substrate divergence separates premium LTPO backplane contracts from commodity glass-panel spot markets, concentrating pricing power with East Asian deposition equipment holders while compressing margins for second-source rigid suppliers dependent on indium tin oxide cost swings.
Pricing Analysis
Volume-margin splits favor flagship flexible panels commanding premium-mid-economy pricing differentiation against rigid substrates fighting for education-tablet and mid-range handset allocations. Price differentiation rests on LTPO certification tier and direct OEM contracting status, with Samsung Electronics and Apple negotiations bypassing traditional ODM intermediaries. Cost compression in rigid tiers intensifies because Chinese export quotas on rare-earth dopants inflate backplane deposition inputs. OEM direct buyers exhibit least price sensitivity; retail digital signage project tenders show maximum elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Canon Tokki and Ulvac vapor deposition equipment dominance for Gen-8.5 fab expansions. Geographic supply concentration centers on South Korea, China, and Japan for substrate handling, laser lift-off separation, and microdeposition tooling. Raw material dependencies draw from indium tin oxide sputtering targets, iridium-doped phosphorescent emitters, and polyimide flexible substrates. Tariff exposure on etching gas recovery systems threatens European market access compliance. Distribution runs through East Asian deposition clusters to India PLI scheme module assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AMOLED display market functions as a cost-of-compliance story where EU F-Gas Regulation retrofit requirements for etching gas recovery systems erect capital barriers that fortified incumbents leverage to exclude undercapitalized entrants.
For Market Incumbents: Acquire vapor deposition equipment fabrication capabilities to neutralize Canon Tokki single-source chokepoints. Samsung Display's captive substrate-to-module integration demonstrates how backward integration into laser lift-off separation technology defends against BOE's Gen-6 scale aggression. Prioritize REACH fluorine-free etchant R&D to preserve automotive qualification timelines against emerging Chinese chemical suppliers. For New Entrants and Emerging Players: Module assembly partners in India's Noida and Chennai corridors offer the most penetrable entry vector given PLI scheme incentives and BIS certification backlogs delaying incumbent expansion. Target transparent AMOLED retail showcase installations where project-based procurement tolerates longer qualification cycles. Pursue automotive HUD qualification as a differentiation anchor against saturated smartphone panel competition. For Investors and Strategic Acquirers: Re-rating potential sits with specialized microdisplay developers given silicon backplane AR/VR headset inflection. Long-term viability over a decade horizon favors deposition equipment-dependent fabricators with LTPO licensing leverage over pure capacity plays. Watch blue emitter lifetime degradation resolution as the signal indicating automotive exterior lighting market unlock.| Strategic Initiative | Industry Significance |
|---|---|
| LTPO Backplane Licensing | Variable refresh rate IP holders capture royalty streams from flagship smartphone OEMs adopting hybrid oxide-poly silicon architectures. |
| Etching Gas Recovery Retrofit | EU F-Gas Regulation compliance investments preserve European automotive and medical device market access for deposition tool operators. |
| India Module Assembly Expansion | PLI scheme incentives attract driver IC bonding capacity near Uttar Pradesh and Tamil Nadu handset manufacturing clusters. |
| Phosphorescent Emitter Scale-Up | Iridium and platinum-doped organic compound suppliers secure power efficiency advantages in high-resolution mobile display contracts. |
| Transparent AMOLED Qualification | Automotive HUD and retail showcase penetration commands design premiums for see-through cathode structure developers. |
Research Approach
SEC 10-K filings, MIIT directive publications, and EU ECHA Substances of Very High Concern candidate lists formed the secondary backbone, supplemented by customs records tracking indium tin oxide and rare-earth dopant trade flows. Primary interviews with deposition equipment procurement directors, flexible substrate process engineers, and automotive HUD qualification managers validated input cost assumptions and capacity expansion timelines. Bottom-up and top-down triangulation reconciled Gen-6 and Gen-8.5 fab utilization rates against smartphone OEM flexible panel order pipelines.
Bottom-up modeling aggregated individual panel maker capacity schedules, equipment delivery lead times, and substrate yield assumptions across the analysis window. Segmentation dimensions incorporated substrate flexibility tier, backplane technology architecture, end-use device category, and regional regulatory compliance cluster. CAGRs derived from equipment depreciation schedules, replacement cycle velocity, and emitter material cost curve projections. Forecast inputs included foldable smartphone penetration rates and LTPO adoption curves in flagship tiers.
Caveats apply where blue emitter lifetime degradation breakthroughs or EU F-Gas Regulation enforcement intensity could materially shift the outlook for automotive and tandem OLED stack applications. Forecasts reflect assumptions regarding Chinese export quota stability, India PLI scheme renewal, and REACH fluorine-free solvent commercialization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global LED Digital Signage Market
Display Technologies
Global Embedded Display Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Backlit Displays Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Wireless Display Market
Display Technologies
Smart Display Market
Display Technologies
Low Power Display Market
Display Technologies
Privacy Screens Market
Display Technologies
Thin Display Technology Market
Display Technologies
Global Portable Monitor Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Next Generation 3D Display Market
Display Technologies
Global OLED Market