
 Commercial Display Market | 2026-2036
Commercial Display Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Display Market Intelligence
Subscription-based content management and remote monitoring software is expanding the addressable revenue per commercial display deployment beyond hardware margins. Samsung Display Co., Ltd. leverages its vertical integration in OLED panel production to control supply for premium digital signage installations. LG Display Co., Ltd. sustains manufacturing scale across large-area LCD and OLED lines serving both corporate boardroom and retail applications. BOE Technology Group Co., Ltd. dominates domestic Chinese commercial display supply while extending capacity into interactive whiteboards for education.
Commercial display denotes professional-grade visual output equipment engineered for continuous operation in ambient-lit environments, typically specified at 500 to 2,500 nits brightness, with thermal architectures designed for 16- to 24-hour daily duty cycles in retail storefronts, transit hubs, and command centers. LCD panels retain the largest installed base across price-sensitive hospitality and government installations where 4K resolution has become baseline specification. LED direct-view displays command premium positioning in entertainment venues and flagship retail where bezel-free scaling and 1,000+ nit output justify higher capital outlay. OLED penetration concentrates in corporate and high-end transportation settings where contrast ratio and form-factor flexibility offset burn-in risk management costs.
The U.S. EPA ENERGY STAR program and California Title 20 appliance standards constrain standby power and active-mode consumption for displays sold into North American commercial channels. The EU Ecodesign Directive and REACH chemical restrictions shape panel material selection and end-of-life recyclability requirements across European procurement. China's GB standards for electronic display energy efficiency and the national dual carbon goals pressure domestic manufacturers toward lower-power backlight architectures. Stakeholders must monitor how regional efficiency thresholds diverge and whether modular upgrade pathways or full replacement cycles prove more cost-effective under tightening operational carbon accounting.
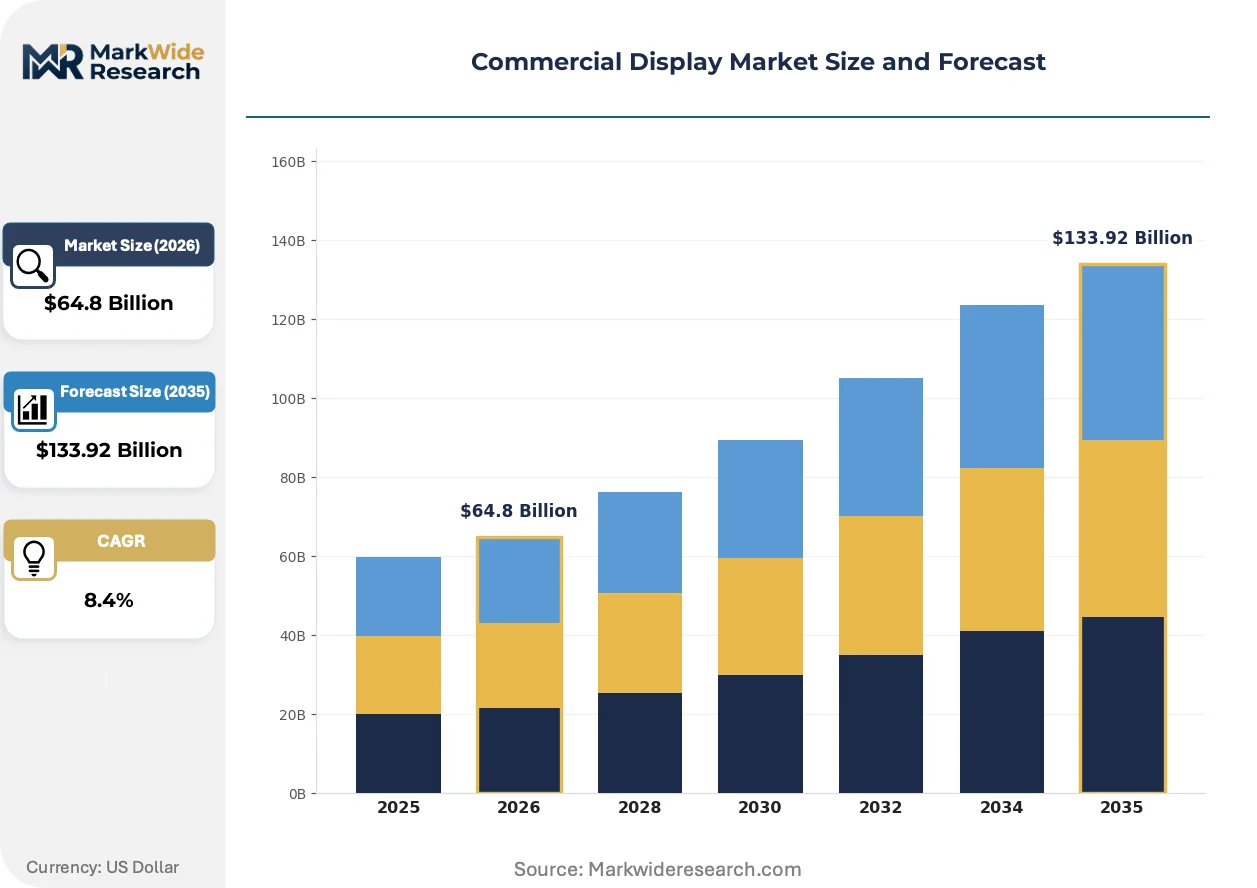
Market Dynamics
Energy efficiency mandates and fab concentration in China are compressing panel supply chains while forcing specification upgrades across retail, transit, and corporate installations worldwide.
Growth Catalysts
- EU F-Gas Regulation:Cooling-related efficiency standards are accelerating replacement cycles for commercial displays in European quick-service restaurants and transit hubs, creating pull for lower-power LED backlight architectures.
- Quick-service restaurant digital signage:North American and Asian fast-food chains are deploying menu boards with 4K resolution and remote content management, shortening hardware refresh intervals from seven years to four.
- China's dual carbon goals:National energy efficiency pressure under GB standards is redirecting domestic fab output toward commercial-grade panels with reduced active-mode consumption for export markets.
Market Restraints
- Gen 10.5+ fab concentration:BOE Technology Group and TCL China Star control disproportionate large-area LCD capacity, creating supply vulnerability for non-Chinese integrators during demand spikes.
- OLED burn-in mitigation costs:Static content applications in transit and corporate settings require pixel-shifting firmware and extended warranties, elevating total cost of ownership versus LCD alternatives.
- Indium tin oxide price volatility:Touch-enabled interactive whiteboards and kiosks face input cost pressure from fluctuating rare earth supply chains concentrated in Southeast Asian refining operations.
Strategic Opportunities
- Subscription content management software:Recurring revenue models for remote monitoring and dynamic scheduling are expanding addressable value per deployment beyond hardware margins in North American retail.
- Interactive whiteboards for education:Underpenetrated K-12 and higher-education segments in India and Southeast Asia represent white space for touch-integrated large-format displays with collaborative software bundles.
- LED direct-view entertainment venues:Bezel-free scaling and 1,000+ nit output specifications are opening flagship retail and stadium applications where projection and LCD walls previously dominated.
Industry Challenges
- Thermal engineering talent scarcity:16- to 24-hour duty cycle specifications for transit and command center installations require specialized thermal architecture expertise that outpaces current workforce supply.
- Multi-jurisdiction certification complexity:Simultaneous compliance with U.S. EPA ENERGY STAR, California Title 20, EU Ecodesign, and China's GB standards extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Display Market |
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $133.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, Projection Application: Retail, Education, Corporate, Entertainment Technology: Touchscreen, Interactive, Digital Signage, 4K End User: Hospitality, Transportation, Healthcare, Government |
| Companies Covered | Innolux Corporation, TCL China Star Optoelectronics Technology Co., Ltd., BOE Technology Group Co., Ltd., Sony Corporation, Sharp Corporation, LG Display Co., Ltd., AU Optronics Corp., Panasonic Connect Co., Ltd., Samsung Display Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Display Market Strategic Shifts & Innovations
Mini-LED backlighting, tightening efficiency regulations, and software-integrated service models are simultaneously elevating performance floors and compressing traditional hardware-centric business models across commercial display procurement.
Mini-LED local dimming arrays with thousands of zones are rewriting brightness uniformity standards for high-ambient retail and window-facing installations. Luxury flagship stores in Dubai and Singapore are specifying 2,000+ nit panels with precision HDR rendering, forcing mid-tier hospitality buyers to accept wider specification gaps or absorb 40-60% panel cost premiums.
The EU Ecodesign Directive's 2025 standby power thresholds are eliminating inefficient legacy power supplies from European procurement channels. Display integrators serving German automotive showrooms and French retail chains are redesigning thermal architectures to meet sub-0.5W standby requirements, compressing supplier qualification lists to vertically integrated panel makers with captive power electronics design.
Content-as-a-service bundling is displacing capital-expense-heavy hardware-only procurement in North American quick-service restaurant chains. Operators now prioritize subscription platforms with real-time menu pricing integration and remote diagnostics, relegating panel specifications to secondary evaluation criteria behind software ecosystem completeness and API flexibility for loyalty program connectivity.
Commercial Display Market Segmentation
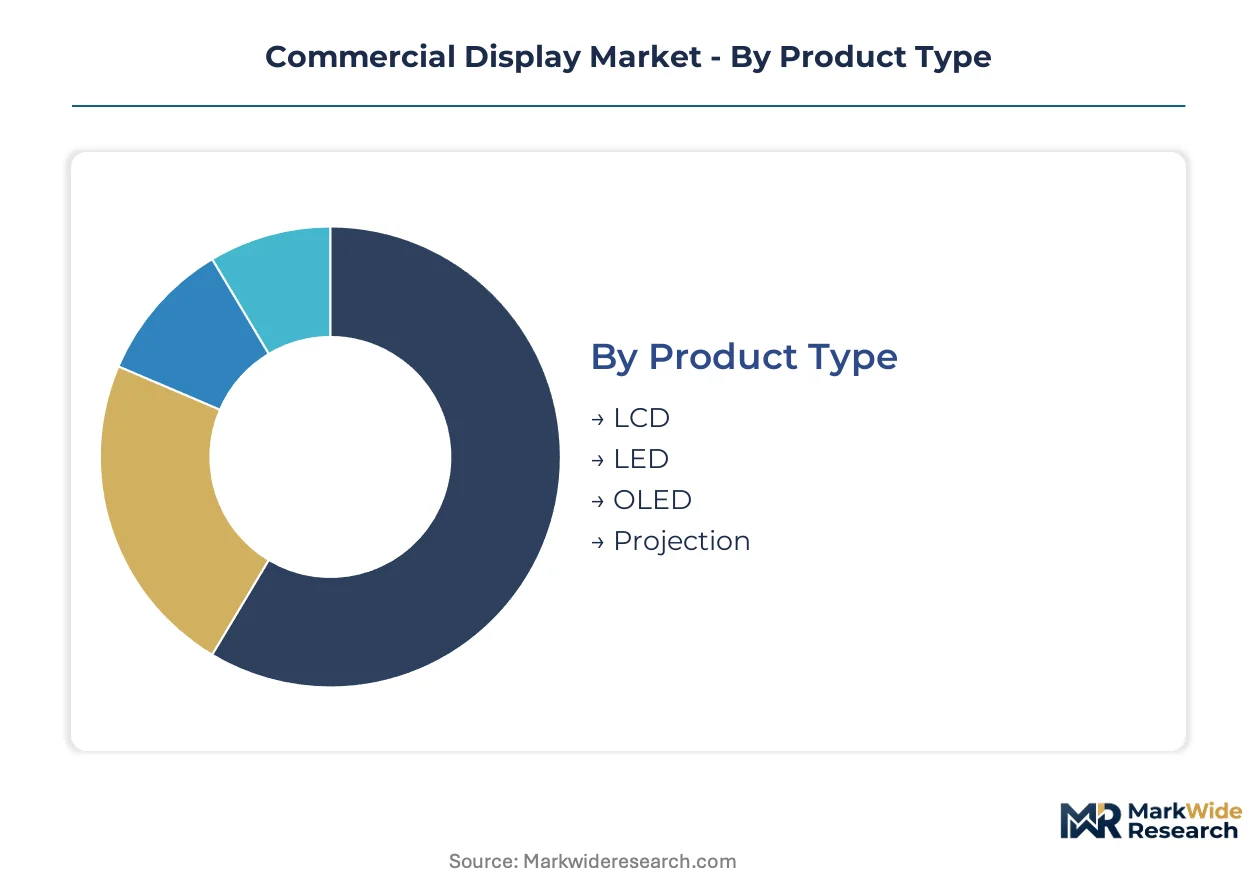
Commercial display procurement varies sharply by deployment context—standalone installations in retail storefronts demand different thermal architectures and brightness specifications than embedded systems integrated into transportation infrastructure or healthcare equipment. Understanding these segment boundaries clarifies where panel makers compete on specification versus where software and service layers capture margin.
Product Type:
LCD panels dominate embedded deployments where cost sensitivity and proven supply chains outweigh premium specifications, while LED and OLED concentrate in standalone applications demanding visual impact.
- LCD:Liquid crystal display panels with LED edge-lit or direct backlight architectures remain the workhorse for price-sensitive hospitality and government installations. Demand concentrates in China where BOE Technology Group and TCL China Star operate Gen 10.5 and Gen 11 fabs, with procurement favoring 4K resolution as baseline specification under tightening EU Ecodesign standby power thresholds.
- LED:Direct-view LED displays eliminate bezels entirely through modular tile assemblies, enabling seamless scaling to architectural dimensions. Entertainment venues in Dubai and Singapore specify 2,000+ nit brightness with precision HDR rendering, justifying 40-60% capital premiums over LCD alternatives for flagship retail and stadium applications.
- OLED:Organic light-emitting diode panels deliver infinite contrast ratios and flexible form factors for corporate boardrooms and premium transportation lounges. Static content applications require pixel-shifting firmware and extended warranties to mitigate burn-in risk, elevating total cost of ownership.
- Projection:Laser and lamp-based projection systems persist in large-venue temporary installations and heritage building retrofits where display weight and heat dissipation constraints prohibit panel mounting.
LCD leads volumes today; LED is gaining share fastest in entertainment and flagship retail.
Application:
End-use context determines whether displays operate as standalone customer-facing assets or integrate into broader environmental systems with centralized control.
- Retail:Digital signage deployments in quick-service restaurant chains are accelerating replacement cycles across North America and Asia, with menu boards now specifying 4K resolution and remote content management platforms.
- Education:Interactive whiteboards for K-12 and higher-education segments represent underpenetrated white space in India and Southeast Asia, requiring touch-integrated large-format displays with collaborative software bundles.
- Corporate:Boardroom and command center installations demand 16- to 24-hour duty cycle specifications with specialized thermal architecture expertise that outpaces current workforce supply.
- Entertainment:Stadium and venue applications prioritize bezel-free scaling and 1,000+ nit output where projection and LCD walls previously dominated.
Retail commands the largest installed base; education shows the steepest expansion trajectory for interactive formats.
Technology:
Interface and resolution specifications segment procurement between basic information display and immersive interactive engagement.
- Touchscreen:Capacitive and infrared touch overlays enable direct user interaction in kiosks and wayfinding terminals. Indium tin oxide price volatility from Southeast Asian refining concentration creates input cost pressure for high-volume deployments.
- Interactive:Multi-user collaborative systems with embedded computing and whiteboarding software differentiate education and corporate meeting room procurement beyond panel hardware margins.
- Digital Signage:Network-connected displays with content management system integration dominate quick-service restaurant and transit hub deployments, with subscription software models expanding addressable revenue per installation.
- 4K:Ultra-high-definition resolution has become baseline specification across price-sensitive segments, with Mini-LED local dimming arrays now rewriting brightness uniformity standards for high-ambient window-facing installations.
Digital signage leads deployment volumes; interactive technology is climbing the fastest in education and corporate segments.
End User:
Operational environment and regulatory exposure shape durability requirements and certification complexity across vertical markets.
- Hospitality:Hotel lobbies, conference centers, and restaurant chains balance aesthetic impact with 24/7 reliability specifications, with procurement increasingly prioritizing software ecosystem completeness over panel specifications alone.
- Transportation:Airports, rail terminals, and transit hubs demand 500 to 2,500 nits brightness for ambient-lit environments with thermal architectures engineered for continuous operation.
- Healthcare:Medical-grade displays for imaging and patient-facing information systems face multi-jurisdiction certification complexity extending product launch timelines by 8-14 months.
- Government:Public sector installations in the United States must comply with EPA ENERGY STAR and California Title 20 appliance standards constraining standby power and active-mode consumption.
Hospitality retains the largest installed base; transportation is expanding most quickly under infrastructure modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fab concentration contrasts with Germany's regulatory-driven specification upgrades, while the United States and Japan pursue divergent paths on software integration versus thermal engineering specialization.
United States
Quick-service restaurant chains deploy 4K menu boards with remote content management, shortening replacement cycles from seven to four years. The EPA ENERGY STAR program and California Title 20 appliance standards constrain standby power and active-mode consumption. Dallas and Atlanta host major digital signage integration clusters serving North American retail and hospitality verticals.
China
BOE Technology Group and TCL China Star operate Gen 10.5 and Gen 11 fabs serving domestic and export commercial display customers with massive scale. National dual carbon goals under GB standards pressure manufacturers toward lower-power backlight architectures. The Yangtze River Delta concentration around Shanghai and Suzhou anchors panel production for interactive whiteboards and digital signage exports.
Germany
Automotive showrooms and retail chains demand sub-0.5W standby compliance under EU Ecodesign Directive thresholds. The EU F-Gas Regulation reshapes cooling-related efficiency standards for transit hub installations. Stuttgart and Munich industrial clusters specialize in thermal architecture design for 16- to 24-hour duty cycle specifications.
Japan
Corporate boardrooms and command centers prioritize thermal engineering expertise for continuous operation specifications. METI efficiency guidelines shape procurement criteria for public sector and transportation deployments. The Kanto region around Tokyo maintains concentration in high-reliability panel integration for premium transportation lounges.
Singapore
Luxury flagship stores specify 2,000+ nit panels with precision HDR rendering for high-ambient window-facing installations. Regional efficiency mandates from ASEAN harmonization efforts influence procurement specifications. The city-state serves as a demonstration hub for LED direct-view entertainment venue deployments across Southeast Asian markets.
Commercial Display Market Key Industry Players
Top-tier vendors anchor premium-tier supply, while mid-scale fabricators compete on volume efficiency and regional customization. Panel production concentrates among display specialists with captive fab capacity, creating tiered access to advanced backlight architectures. Three archetypes dominate: vertically integrated Korean and Chinese panel makers, Japanese precision engineering specialists, and Taiwan-based volume fabricators. Capacity expansion and strategic software partnerships represent the dominant competitive vectors reshaping procurement relationships.
Among Korean and Chinese panel specialists, Samsung Display Co., Ltd., LG Display Co., Ltd., and BOE Technology Group Co., Ltd. occupy positions exemplifying the vertically integrated archetype with captive control over OLED and large-area LCD supply chains. These entities represent the structural foundation through which premium digital signage and corporate display specifications reach global integrators.
| Leading Market Players |
|---|
| Innolux Corporation |
| TCL China Star Optoelectronics Technology Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| Sony Corporation |
| Sharp Corporation |
| LG Display Co., Ltd. |
| AU Optronics Corp. |
| Panasonic Connect Co., Ltd. |
| Samsung Display Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Quick-service restaurant procurement teams demanding 4K resolution with embedded content management platforms are forcing panel makers to absorb firmware integration costs or lose volume contracts, compressing hardware margins while elevating subscription software pricing power.
Pricing Analysis
Capacity additions in China are reshaping price floors for large-area LCD panels as BOE Technology Group and TCL China Star expand Gen 10.5 and Gen 11 output. Three-tier pricing structure across premium, standard, and economy levels separates OLED corporate installations from LED direct-view entertainment venues from edge-lit LCD hospitality deployments. Cost compression in mid-tier LCD segments is intensifying because 4K resolution has become baseline specification rather than premium upgrade. Government and education buyers exhibit highest price sensitivity, while luxury retail flagships in Dubai and Singapore accept 40-60% premiums for 2,000+ nit HDR specifications.
Supply Chain Analysis
Thermal engineering talent scarcity in the Yangtze River Delta and Kanto region constrains output scaling for 16- to 24-hour duty cycle specifications. Manufacturing concentrates in China, South Korea, and Japan, with panel production drawing from indium tin oxide touch layers, gallium nitride power electronics, and rare earth phosphors for LED backlights. Single-source vulnerability runs through Southeast Asian indium refining operations concentrated in Malaysian and Indonesian processing facilities. Distribution runs through integrator clusters in Dallas, Atlanta, and Stuttgart serving regional retail, hospitality, and automotive showroom verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by quick-service restaurant chains prioritizing software ecosystem completeness over raw panel specifications in procurement evaluations.
For Market Incumbents: Deploy captive OLED supply chains to defend premium positioning against Mini-LED backlighting substitutes encroaching from high-ambient retail applications. Deepen thermal architecture R&D partnerships with German automotive showroom integrators facing EU Ecodesign Directive standby power thresholds. Control content management platform APIs to lock in quick-service restaurant loyalty program connectivity and extend replacement cycle influence. For New Entrants and Emerging Players: Begin with interactive whiteboard deployments in Indian and Southeast Asian education sectors where collaborative software bundles remain underdeveloped against hardware-centric procurement. Target K-12 districts with touch-integrated large-format displays bundled with cloud-based classroom management platforms. Pursue white-label partnerships with established display integrators lacking proprietary software development capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale software-integrated service providers capturing recurring revenue from remote monitoring and dynamic scheduling subscriptions. Five-to-ten-year viability favors entities controlling both panel supply and content management platforms rather than pure hardware fabricators. Watch for inflection when quick-service restaurant chains consolidate vendor relationships around single-platform ecosystems rather than multi-supplier hardware sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive supply of gallium nitride components meets EU Ecodesign standby thresholds for German automotive showroom deployments. |
| Content Management Platform Acquisition | Software layer control secures recurring revenue from quick-service restaurant menu pricing API integrations. |
| Thermal Engineering Talent Recruitment | Specialized workforce expansion enables 24-hour duty cycle compliance for Singapore airport transit hub installations. |
| Interactive Whiteboard Joint Venture | Local manufacturing partnerships penetrate Indian education procurement channels with collaborative software bundles. |
| Mini-LED Backlight Capacity Buildout | Precision local dimming arrays capture high-ambient retail specifications from Dubai luxury flagship store renovations. |
Research Approach
Bottom-up quick-service restaurant and transit hub deployment modeling reconciled against top-down fab capacity tracking forms the analytical core of this study. Primary interviews with display integrator procurement directors, thermal engineering specialists, content management platform developers, and quick-service restaurant technology officers combined with secondary validation against SEC filings from Samsung Display and LG Display, EPA ENERGY STAR certified product databases, EU Ecodesign implementing measure documentation, and China GB standards disclosure records. Triangulation across supply-side capacity announcements and demand-side deployment timelines ensures consistency.
Historical trendline analysis of replacement cycle compression from seven-year to four-year intervals informed projection frameworks across the modeling period. Segmentation dimensions include display technology, application context, brightness specification tier, and regional regulatory cluster. CAGRs derive from weighted average of unit deployment trajectories and average selling price evolution, with specific inputs from ENERGY STAR qualification rates and EU F-Gas Regulation compliance timelines shaping efficiency-driven replacement assumptions.
Several conditions sit outside the modeled scope, including potential indium export restrictions from Southeast Asian refining operations and abrupt shifts in quick-service restaurant capital expenditure priorities. Forecasts reflect documented assumptions about software subscription attach rates and thermal engineering workforce expansion trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Global OLED Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Global Industrial Display System Market
Display Technologies
OLED Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Rugged Display Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Holographic Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
Display Material Market
Display Technologies
Backlit Displays Market
Display Technologies
Digital Kiosk Display Market