
 Automated Cell Culture Systems Market | 2026-2036
Automated Cell Culture Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Cell Culture Systems Market Analysis
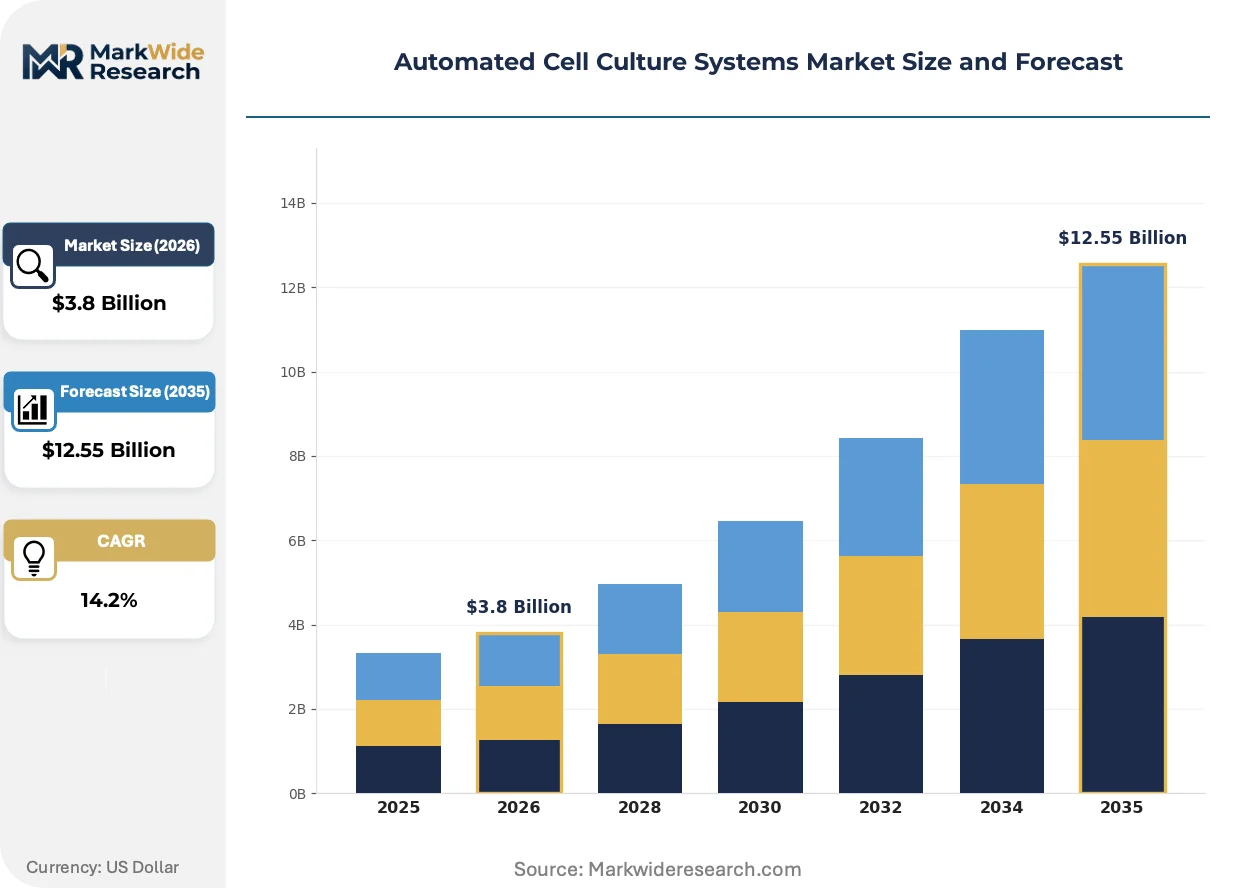
The automated cell culture systems market is restructuring around a sharp split between closed, GMP-compliant bioreactor platforms for commercial cell therapy manufacturing and open, benchtop systems for academic research. Thermo Fisher Scientific leverages its global service network to sustain dominance in high-throughput pharmaceutical workflows. Lonza Group AG anchors its position through captive bioprocess automation capabilities that extend from equipment supply into contract manufacturing. Eppendorf AG competes by specializing in compact, modular systems that occupy mid-scale research and process development niches.
Automated cell culture systems integrate bioreactors, environmental controls, and analytics hardware with software protocols that maintain sterile conditions across passages, typically operating at 37°C with 5% CO2 and dissolved oxygen monitoring for mammalian cell lines. Their primary purpose is to reduce manual handling variability while scaling from milliliter process development to liter-scale biomanufacturing. Bioreactors command the largest installed base among product types, though microfluidics-enabled systems represent the fastest-expanding technology segment as pharmaceutical companies miniaturize perfusion models. Drug discovery applications generate the steadiest revenue flow, while regenerative medicine creates the most aggressive capacity buildout among end users.
FDA's guidance on chemistry, manufacturing, and controls for cell and gene therapy products shapes equipment validation requirements, while EMA's ATMP framework drives parallel compliance investments in European facilities. ISO 14644 cleanroom classifications and GMP Annex 1 revisions pressure vendors to integrate continuous environmental monitoring into platform designs. Stakeholders must weigh the capital intensity of closed-system automation against the operational risk of manual contamination in expanding cell therapy pipelines.
Market Dynamics
Cell therapy manufacturers face a structural squeeze between FDA's GMP validation timelines and the capital intensity of closed-system automation, forcing equipment vendors to pre-validate platforms before sale rather than customize post-installation.
Growth Catalysts
- EMA ATMP Framework:European cell therapy developers must automate manufacturing to meet centralized marketing authorization requirements, pulling demand for GMP-compliant bioreactor systems into German and Swiss contract manufacturing facilities.
- Perfusion microfluidics:Miniaturized continuous culture platforms reduce media consumption by 60% in process development, accelerating adoption among mid-stage biotechs optimizing CAR-T expansion protocols.
- Boston-San Diego corridor concentration:Regenerative medicine startups cluster within 50 miles of these hubs, creating localized demand density that justifies regional service infrastructure investments by equipment suppliers.
Market Restraints
- Stainless steel supply concentration:Pharmaceutical-grade 316L bioreactor vessels depend on specialized German and Japanese metallurgical suppliers, exposing lead times to energy cost volatility in European smelting operations.
- Single-use plastic resin pricing:Cell culture bags and tubing rely on medical-grade TPE and COC polymers whose petrochemical feedstock costs fluctuate with natural gas benchmarks, compressing margin on consumables-heavy platforms.
- ISO 14644 cleanroom retrofit requirements:Existing open-system facilities face six-figure infrastructure upgrades to achieve Grade B environmental classifications, freezing capital allocation for academic labs with limited grant flexibility.
Strategic Opportunities
- India CDMO buildout:Contract manufacturers in Hyderabad and Bengaluru seek entry-level automated systems to serve domestic biosimilar developers and export to Middle Eastern markets with limited local GMP capacity.
- Organ-on-chip convergence:Integration of automated cell culture with microphysiological systems creates new product category spanning drug discovery and personalized medicine applications.
- Japan regenerative medicine commercialization:PMDA's conditional approval pathway for iPSC-derived therapies mandates scalable manufacturing, opening demand for closed-system platforms in Osaka and Kobe bioclusters.
Industry Challenges
- Cross-functional talent scarcity:Facilities require engineers who simultaneously understand bioprocess science, automation programming, and GMP documentation, with fewer than 200 certified training programs worldwide.
- Legacy LIMS integration friction:New automated platforms must communicate with decade-old laboratory information management systems through custom API bridges, extending validation timelines by 4-6 months.
- Process analytical technology certification:Real-time dissolved oxygen and pH sensors require individual lot calibration certificates under GMP Annex 1, creating documentation bottlenecks during scale-up campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Cell Culture Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Cell Counters, Incubators, Analyzers Technology: Microfluidics, Bioprocess Automation, Digital Imaging, Robotics End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Academic Labs Application: Drug Discovery, Vaccine Development, Regenerative Medicine, Tissue Engineering |
| Companies Covered | Merck KGaA, Lonza Group AG, Thermo Fisher Scientific Inc., Eppendorf AG, Tecan Group Ltd., Sartorius AG, Becton, Dickinson and Company, Corning Incorporated, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Cell Culture Systems Market Emerging Trajectories
Equipment architecture is fragmenting into interchangeable subsystems as buyers reject monolithic platforms, while regulatory pressure forces embedded compliance features rather than bolt-on validation packages.
Modular bioreactor control systems are modularizing the traditional integrated hardware stack. Mid-scale process development groups at pharmaceutical companies now mix vessels from one supplier with analytics modules from another. This interoperability is modularizing vendor lock-in, compressing switching costs and forcing incumbents to publish open communication protocols.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating fluoropolymer substitution in cell culture vessel linings. European manufacturers face 2025 deadlines for PFAS phase-out in single-use consumables, driving migration to silicone and thermoplastic elastomer alternatives. German equipment suppliers are responding with pre-validated material qualification packages to shorten customer re-validation cycles.
Cell therapy developers are unbundling equipment purchases from service contracts, treating automation platforms as capital assets with third-party maintenance. This procurement pattern disrupts the traditional bundled pricing model dominant in pharmaceutical equipment. The shift is most visible in United States academic medical centers spinning out commercial manufacturing operations.
Automated Cell Culture Systems Market Segmentation
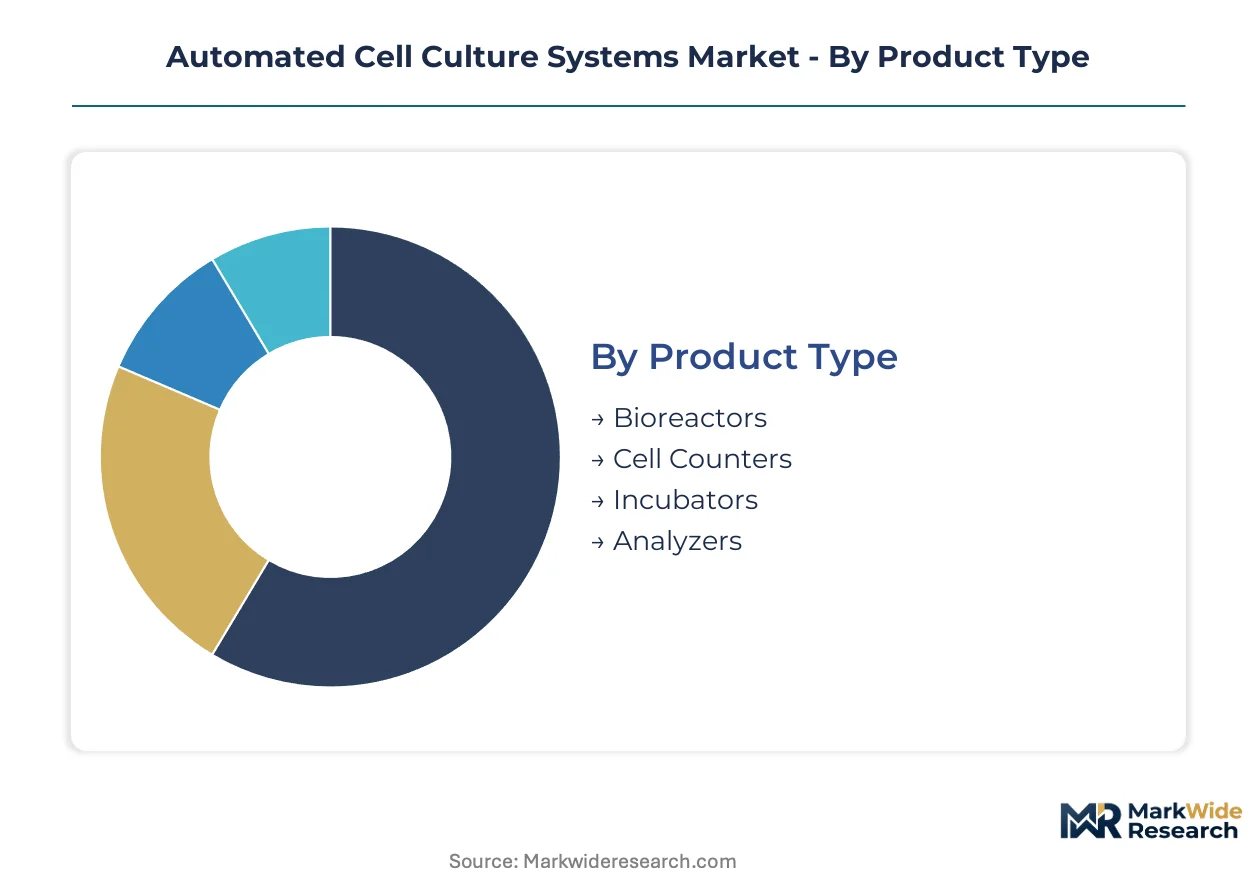
Equipment segmentation in automated cell culture systems determines capital allocation cycles and service contract structures. Pharmaceutical procurement teams segment purchases by regulatory compliance tier, while academic buyers prioritize modularity over validation depth.
Product Type:
Upgrade cycles for bioreactors and incubators run 7-10 years in GMP facilities, driving replacement revenue concentration among established pharmaceutical manufacturers.
- Bioreactors:Closed-system stirred-tank and perfusion vessels dominate commercial cell therapy manufacturing. Stainless steel platforms anchor large-scale operations in German and Swiss contract manufacturing facilities, while single-use systems penetrate mid-scale process development labs near Boston and San Diego.
- Cell Counters:Automated viability analyzers integrate with bioreactor control loops for real-time density feedback. Demand concentrates in CAR-T process development groups optimizing expansion protocols, with image-based systems displacing Coulter counter methods in high-throughput screening.
- Incubators:Stackable CO2 units with HEPA filtration serve academic labs with limited cleanroom infrastructure.
- Analyzers:Metabolite and dissolved oxygen sensors complete the environmental monitoring stack.
Bioreactors sit at the top of the volume ranking, with cell counters climbing the fastest.
Technology:
Technology selection correlates with end-user maturity, with pharmaceutical companies prioritizing validated automation stacks over experimental platforms.
- Bioprocess Automation:Integrated control systems orchestrate vessel environment, media exchange, and harvest scheduling through unified software protocols. GMP-compliant platforms command premium positioning in FDA-regulated cell therapy facilities, where batch record automation reduces documentation burden.
- Microfluidics:Miniaturized perfusion chambers reduce media consumption and enable parallel process development. Mid-stage biotechs in Cambridge and South San Francisco adopt these systems for CAR-T optimization, with chip-based platforms gaining share in personalized medicine applications.
- Digital Imaging:Label-free microscopy enables continuous confluence monitoring without sampling disruption.
- Robotics:Liquid handling arms automate passage and plating in high-throughput drug discovery workflows.
Bioprocess automation holds the largest installed base, though microfluidics is expanding most quickly among emerging biotechs.
End User:
Customer type shapes pricing architecture, with pharmaceutical companies accepting capital intensity for compliance depth while academic labs optimize grant-funded procurement.
- Pharmaceutical Companies:Multinational drug manufacturers deploy closed-system platforms across global manufacturing networks. FDA and EMA validation requirements drive standardization on pre-qualified equipment, with procurement centralized at headquarters level to secure service consistency.
- Biotechnology Firms:Venture-backed cell therapy developers prioritize scalable platforms that bridge process development into commercial manufacturing. These buyers cluster in regenerative medicine corridors near Boston, San Diego, and Basel, creating localized demand density.
- Research Institutions:National laboratories and medical centers balance throughput against infrastructure constraints.
- Academic Labs:University groups favor open, benchtop systems with flexible protocol programming.
Pharmaceutical companies generate the steadiest revenue flow, with biotechnology firms showing the steepest expansion trajectory.
Application:
Application focus determines equipment specification, with regenerative medicine demanding closed GMP platforms and drug discovery favoring open, high-throughput configurations.
- Regenerative Medicine:Cell therapy manufacturing requires closed, automated platforms that maintain sterile conditions across expansion and harvest. FDA's CMC guidance for cell and gene therapy products mandates process validation that favors pre-qualified bioreactor systems.
- Drug Discovery:High-throughput screening operations prioritize parallel processing capacity over environmental control stringency. Pharmaceutical discovery groups in New Jersey and Basel deploy automated liquid handling and imaging systems for compound toxicity testing.
- Vaccine Development:Viral vector production uses similar bioreactor infrastructure to cell therapy, with EMA's ATMP framework driving European demand.
- Tissue Engineering:Organ-on-chip and scaffold-based applications require specialized perfusion and mechanical stimulation modules.
Drug discovery maintains the broadest installed base, while regenerative medicine is gaining share fastest among capital-intensive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bioprocess engineers cluster in the Boston-San Diego corridor, anchoring North American demand density. German and Swiss metallurgical expertise sustains European equipment fabrication. Japanese precision manufacturing supports Asia-Pacific platform development.
United States
FDA's CMC guidance for cell and gene therapy products mandates closed-system automation for commercial manufacturing. Regenerative medicine startups concentrate within 50 miles of Boston and San Diego, creating localized demand for GMP-compliant bioreactor platforms. Academic medical centers in these corridors are spinning out commercial manufacturing operations.
Germany
EMA's ATMP framework pulls demand for validated automation into centralized European marketing authorization pathways. REACH restrictions on PFAS substances are accelerating fluoropolymer substitution in cell culture vessel linings by 2025. Pharmaceutical-grade 316L bioreactor vessel fabrication concentrates in specialized metallurgical supply chains.
Switzerland
Swissmedic's alignment with EMA standards positions Basel-area contract manufacturers as automation adopters. Captive bioprocess automation capabilities extend from equipment supply into integrated contract manufacturing services. The country's precision engineering tradition supports closed-system platform development for cell therapy applications.
Japan
PMDA's conditional approval pathway for iPSC-derived therapies mandates scalable manufacturing infrastructure. Osaka and Kobe bioclusters are building demand for closed-system platforms to support regenerative medicine commercialization. METI's industrial policy prioritizes biomanufacturing automation as a strategic sector.
India
CDSCO's evolving biosimilar regulations are pulling entry-level automation into domestic contract manufacturing. Hyderabad and Bengaluru CDMOs seek automated systems to serve regional biosimilar developers and Middle Eastern export markets. The country's pharmaceutical manufacturing base is upgrading from manual to semi-automated cell culture workflows.
Automated Cell Culture Systems Market Vendor Landscape
Top-tier vendors anchor the GMP-compliant platform segment, while mid-scale specialists occupy modular research niches. The market structures around three tiers: integrated multinationals with global service networks, regional equipment fabricators with captive bioprocess expertise, and modular specialists targeting process development. Strategic moves concentrate on pre-validation partnerships with cell therapy developers and geographic expansion into emerging bioclusters.
Within the integrated multinational tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify global service network dominance. Lonza Group AG and Sartorius AG occupy positions bridging equipment supply into contract manufacturing capabilities. Eppendorf AG represents the modular specialist archetype targeting mid-scale research and process development applications.
| Leading Market Players |
|---|
| Merck KGaA |
| Lonza Group AG |
| Thermo Fisher Scientific Inc. |
| Eppendorf AG |
| Tecan Group Ltd. |
| Sartorius AG |
| Becton, Dickinson and Company |
| Corning Incorporated |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Medical-grade TPE and COC polymer price indices cascade through automated cell culture system manufacturing, compressing margins on consumables-heavy platforms while amplifying cost differentials between stainless steel bioreactor vessels and single-use alternatives. German and Japanese metallurgical supply concentration for pharmaceutical-grade 316L steel creates pricing power asymmetries that equipment vendors pass through to cell therapy manufacturers in tiered service configurations.
Pricing Analysis
The bundled-vs-unbundled service split is restructuring procurement patterns across buyer archetypes. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated closed systems from modular research platforms and entry-level academic configurations. Price differentiation hinges on certification depth and geographic service density, with Boston and San Diego corridor buyers accepting premium positioning for validated automation. Cost compression in mid-scale process development tiers is intensifying because venture-backed biotechs unbundle equipment purchases from maintenance contracts. Academic labs exhibit highest price sensitivity, while commercial cell therapy manufacturers prioritize compliance depth over capital efficiency.
Supply Chain Analysis
Domestic-content mandates in Indian pharmaceutical manufacturing are reshaping sourcing patterns for entry-level automation platforms. Equipment fabrication draws from German precision engineering, Swiss bioprocess expertise, and Japanese precision manufacturing for control systems and sensors. Raw material dependencies center on pharmaceutical-grade 316L stainless steel, medical-grade fluoropolymer linings, and specialized TPE resins for single-use consumables. Single-source vulnerability concentrates in European metallurgical suppliers for bioreactor vessels, exposing lead times to energy cost volatility. Distribution runs through direct sales forces for GMP-compliant platforms and specialized distributors for research-grade systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated cell culture systems function as a geographic-arbitrage play between FDA-validated US commercial manufacturing and emerging CDMO buildouts in India, where regulatory compliance costs run substantially lower for entry-level automation.
For Market Incumbents: Lock in regional service infrastructure around Boston and San Diego bioclusters to defend against modular specialists unbundling hardware from validation packages. Deepen backward integration into pre-qualified material supply chains to offset REACH-driven fluoropolymer substitution timelines. Captive bioprocess automation capabilities anchor customer switching costs across contract manufacturing relationships. For New Entrants and Emerging Players: Launch via regional CDMO partnerships in Hyderabad and Bengaluru to bypass direct competition with integrated multinationals in validated GMP segments. White-space targets include organ-on-chip convergence applications and Japan's iPSC-derived therapy manufacturing buildout. The most penetrable entry point sits in mid-scale process development niches bridging academic research into commercial scale-up. For Investors and Strategic Acquirers: Asymmetric upside sits with modular specialists possessing open-protocol bioreactor control systems that enable vendor-agnostic interoperability. Long-term viability over a multi-year window favors platforms with embedded compliance features rather than bolt-on validation packages. Acquisition target archetype: mid-scale equipment fabricators with captive bioprocess expertise and regional service density in emerging bioclusters. The signal to watch is unbundling of equipment purchases from service contracts among academic medical centers spinning out commercial operations.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-validation Partnerships | Equipment vendors pre-validate platforms with FDA to compress cell therapy developer timelines. |
| PFAS Material Substitution | German suppliers accelerate silicone and thermoplastic elastomer alternatives ahead of REACH deadlines. |
| Regional CDMO Buildout | Indian contract manufacturers in Hyderabad seek entry-level automation for biosimilar export markets. |
| Open Protocol Publication | Modular specialists publish communication protocols to reduce buyer switching costs and disrupt lock-in. |
| Organ-on-Chip Integration | Convergence with microphysiological systems creates new product category spanning drug discovery applications. |
Methodological Framework
Direct dialogue with bioprocess engineers, regulatory affairs leads at cell therapy developers, GMP facility managers, and academic lab directors grounded qualitative findings in operational reality. Secondary validation drew from FDA CMC guidance documents, EMA ATMP framework submissions, ISO 14644 cleanroom standards, and GMP Annex 1 revision drafts. Bottom-up equipment installation data and top-down pharmaceutical capital expenditure patterns were triangulated to anchor market sizing.
Bottom-up modeling of bioreactor vessel shipments, control system installations, and consumables consumption across product tiers was cross-checked against top-down pharmaceutical and biotechnology R&D spending allocations. Segmentation dimensions included product type, technology platform, end-user maturity, application focus, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle analysis rather than extrapolated from historical trends. Forecast inputs incorporated EMA centralized marketing authorization timelines and PMDA conditional approval pathway progression for iPSC therapies.
Several conditions sit outside the modeled scope, including macroeconomic shocks to petrochemical feedstock pricing, abrupt REACH enforcement acceleration, and breakthroughs in fully continuous cell culture eliminating batch-based equipment demand. Forecasts reflect assumptions about regulatory harmonization between FDA and EMA standards and sustained venture capital availability for cell therapy developers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market