
 Cellular Localization Kits Market | 2026-2036
Cellular Localization Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Localization Kits Market Analytics
The customer base for cellular localization kits is broadening beyond academic core facilities into distributed biopharma R&D groups and contract research organizations. Merck KGaA leverages its chemical reagent heritage to anchor supply relationships with European research consortia. Thermo Fisher Scientific competes through integrated workflows that bundle localization reagents with imaging instrumentation. Abcam specializes in antibody-dependent localization formats, occupying a defensible niche in protein-specific detection protocols.
Cellular localization kits comprise reagent systems designed to visualize and quantify the spatial distribution of nucleic acids, proteins, or organelles within intact cells, typically employing fluorophore-conjugated probes, hybridization oligonucleotides, or genetically encoded reporters with spectral properties matched to confocal and super-resolution platforms. These kits serve fundamental roles in validating subcellular drug targets, mapping disease-associated trafficking defects, and confirming gene editing outcomes in living or fixed specimens. Protein localization kits dominate current revenue owing to mature antibody supply chains and recurring demand from oncology drug programs. Live cell imaging technology represents the fastest-expanding dimension as pharmaceutical sponsors prioritize kinetic data over endpoint assays. RNA localization kits command premium positioning due to complex probe design requirements and limited qualified vendor pools.
FDA oversight of companion diagnostic development shapes kit performance standards for clinical translation pathways, while ISO 13485 certification requirements filter supplier eligibility in regulated end markets. NIH guidelines on research reproducibility indirectly pressure laboratories to standardize reagent sourcing, reinforcing vendor consolidation trends among kit manufacturers. Stakeholders must monitor how EPA chemical substance notifications and evolving REACH restrictions on fluorophore precursors reshape raw material availability and reformulation costs.
Market Dynamics
CRISPR-based gene editing workflows have intensified demand for precise subcellular tracking tools, forcing kit manufacturers to reconfigure probe chemistries around live-cell compatible fluorophores and genetically encoded reporters that withstand extended imaging sessions.
Growth Catalysts
- NIH reproducibility guidelines:Federal mandates on research replicability compel laboratories to standardize reagent sourcing, consolidating procurement around qualified kit vendors with documented batch consistency.
- Oncology drug programs:Pharmaceutical sponsors require validated subcellular target confirmation for checkpoint inhibitor and antibody-drug conjugate pipelines, sustaining recurring kit consumption.
- Super-resolution microscopy:Commercialization of STED and SIM platforms creates matched demand for spectral-optimized localization probes with precise photophysical properties.
Market Restraints
- Fluorophore precursor restrictions:REACH regulations on aromatic amine compounds constrain European supply chains for rhodamine and cyanine dye building blocks.
- Antibody supply concentration:Protein localization kits depend on mammalian cell-derived secondary antibodies, with production gravity centering on Chinese and South Korean contract manufacturing organizations.
- Probe design complexity:RNA localization formats require locked nucleic acid modifications and extensive off-target validation, limiting qualified vendor pools and extending development timelines.
Strategic Opportunities
- Contract research organizations:Distributed biopharma R&D outsourcing creates demand for kit vendors offering technical application support alongside reagent supply.
- Companion diagnostic pathways:FDA oversight of CDx development elevates performance standards for kits targeting clinical translation, enabling premium positioning for ISO 13485-certified suppliers.
- AI-driven image analysis:Convergence of machine learning segmentation tools with high-content screening platforms opens subscription-based service models bundled with localization reagents.
Industry Challenges
- Cross-functional talent scarcity:Kit development requires hybrid expertise in synthetic organic chemistry, molecular biology, and imaging hardware integration, with competition from pharmaceutical and instrumentation sectors for qualified personnel.
- Multi-jurisdiction certification:Simultaneous pursuit of FDA QSR compliance, EMA notified body approval, and PMDA shonin filing stretches regulatory affairs bandwidth and delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Localization Kits Market |
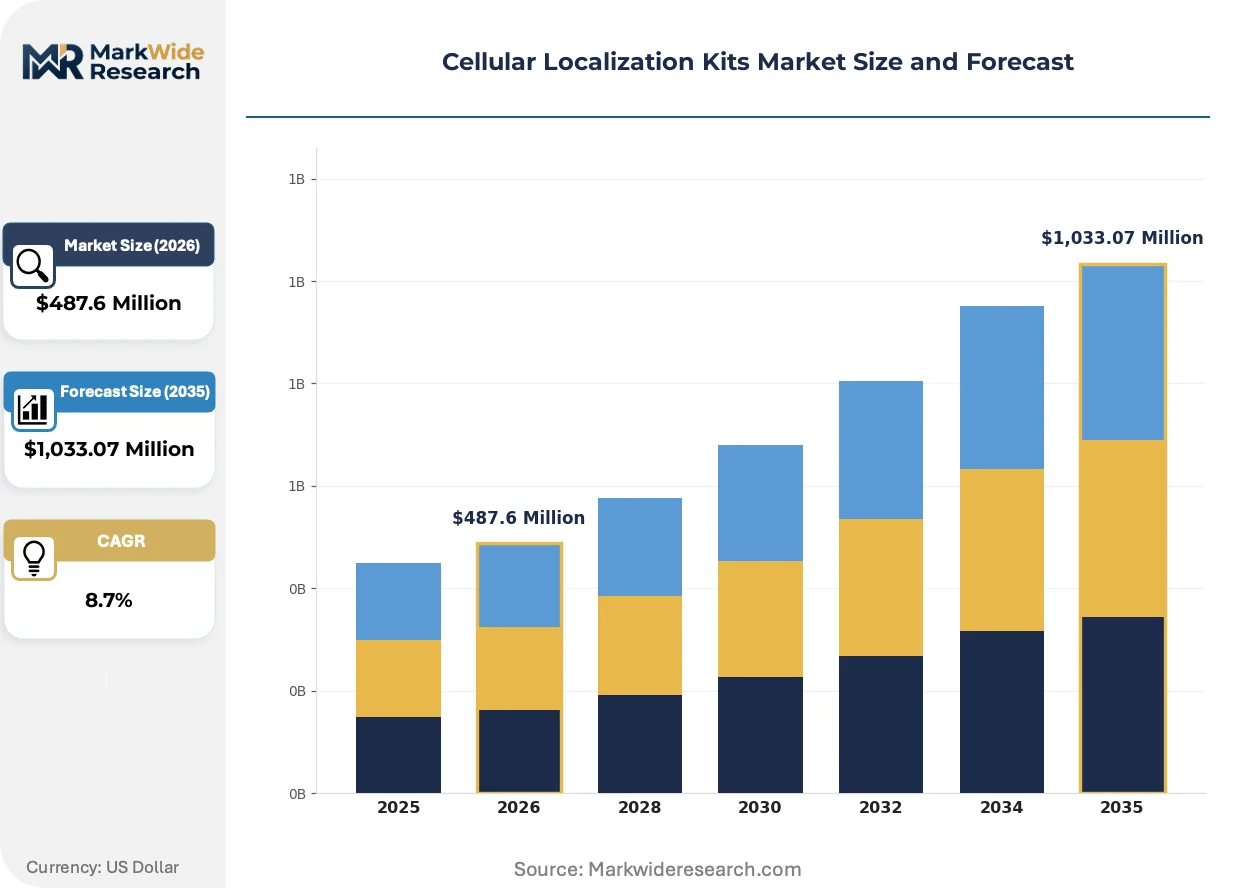
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RNA Localization Kits, Protein Localization Kits, DNA Localization Kits, Cell Line Kits Application: Genetic Research, Drug Development, Clinical Diagnostics, Cellular Biology Technology: Fluorescence Microscopy, Live Cell Imaging, FISH, PCR End User: Research Laboratories, Pharmaceutical Companies, Academic Institutions, Biotechnology Firms |
| Companies Covered | Merck KGaA, Abcam, Thermo Fisher Scientific, Promega Corporation, Santa Cruz Biotechnology, Cell Signaling Technology, Bio-Rad Laboratories, PerkinElmer, New England BioLabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Localization Kits Market Evolving Landscape
Workflow integration pressures are compressing standalone reagent margins while rewarding vendors who embed localization kits within broader imaging and analysis ecosystems. Three developments are reconfiguring competitive positioning.
High-throughput liquid handling platforms are automating probe dispensing and cell staining protocols across pharmaceutical screening operations. Contract research organizations operating in Boston and San Diego clusters have adopted these integrated workstations to compress assay timelines. This automation is automating the transition from artisanal bench protocols to standardized, auditable procedures that satisfy sponsor quality requirements.
EMA's evolving In Vitro Diagnostic Regulation recalibrates performance documentation requirements for kits intended for clinical specimen analysis. Manufacturers must now generate extended analytical and clinical validation datasets prior to CE marking. Protein localization formats targeting HER2 or PD-L1 companion diagnostic applications face the steepest compliance burden, with several vendors accelerating notified body engagement to secure pipeline positioning.
Biopharma procurement teams are consolidating supplier relationships through enterprise framework agreements that bundle localization reagents with imaging instrumentation and software licenses. Core facilities at academic medical centers are ceding purchasing autonomy to centralized vendor management offices. This concentration is most visible in the United States, where NIH-funded institutions face pressure to demonstrate cost efficiency through preferred supplier programs.
Cellular Localization Kits Market Segmentation
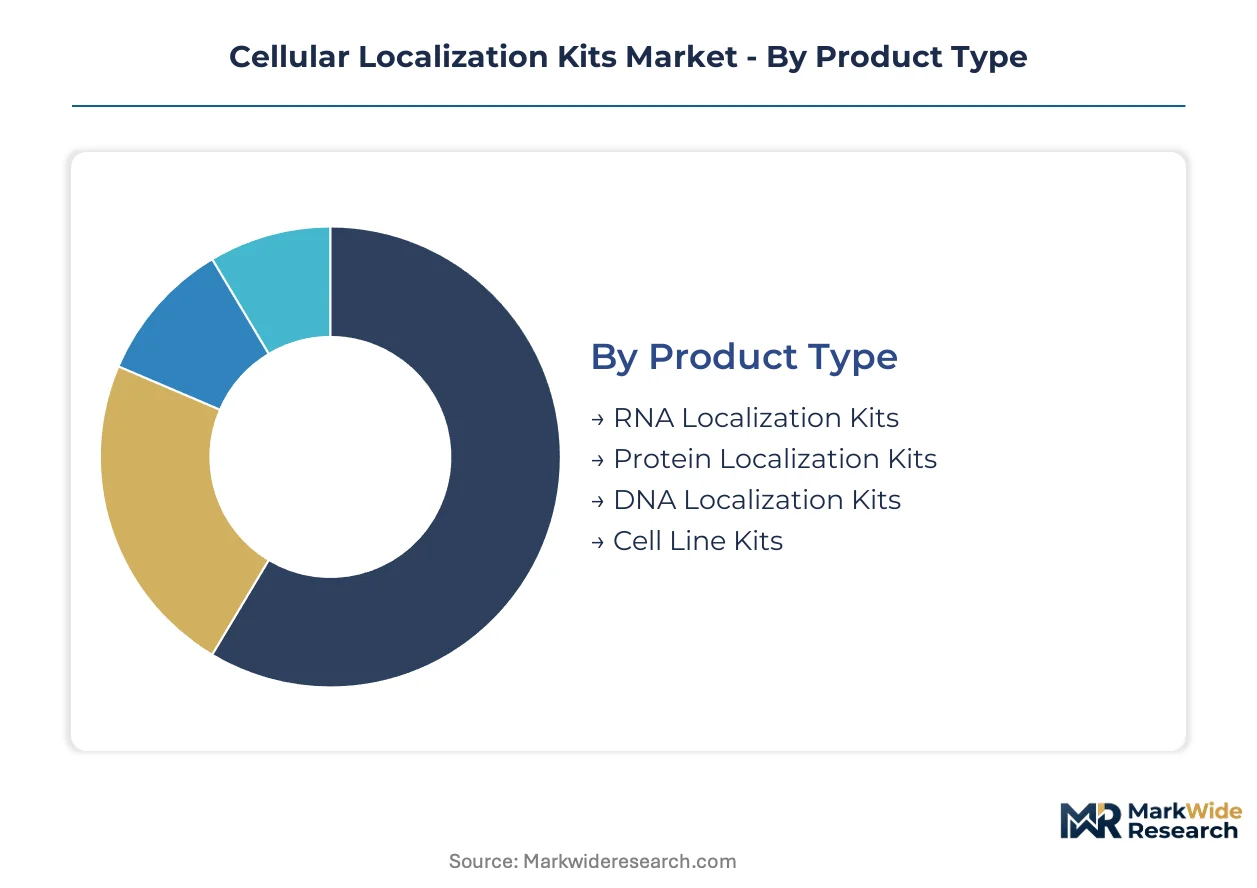
Cellular localization kits fragment across four intersecting dimensions that shape procurement patterns and vendor positioning. Product chemistry determines reagent shelf life and spectral compatibility. Application context dictates regulatory exposure and validation burden. Technology platform constrains probe design requirements. End-user type governs purchasing authority and technical support expectations.
Product Type:
Buyers differentiate by detection target complexity and reagent stability requirements rather than price alone.
- RNA Localization Kits:Locked nucleic acid probes and hybridization oligonucleotides target mRNA and non-coding RNA species with subcellular resolution. Academic medical centers in Boston and San Diego sustain demand for single-molecule FISH workflows in neuroscience and cancer biology programs.
- Protein Localization Kits:Antibody-conjugated fluorophores and immunofluorescence reagents dominate current procurement volumes through mature supply chains and recurring oncology drug target validation needs. Pharmaceutical sponsors in the United States consume these kits at scale for checkpoint inhibitor development pipelines.
- DNA Localization Kits:Chromosomal and episomal visualization reagents support gene editing confirmation and structural variation mapping.
- Cell Line Kits:Pre-validated reporter systems and engineered cell lines reduce protocol development burden for distributed R&D groups.
Volume sits with protein localization formats; growth tilts toward RNA localization kits as transcriptomics programs expand.
Application:
Regulatory pathway and reimbursement potential segment buyers into divergent procurement workflows.
- Drug Development:Target validation, mechanism-of-action studies, and lead optimization campaigns drive kit consumption at contract research organizations. FDA companion diagnostic oversight elevates performance documentation requirements for kits entering clinical translation pathways.
- Genetic Research:Fundamental discovery programs in academic settings prioritize flexibility and publication-grade reproducibility over standardization.
- Clinical Diagnostics:HER2 and PD-L1 companion diagnostic applications face EMA In Vitro Diagnostic Regulation compliance burdens with extended analytical validation datasets.
- Cellular Biology:Organelle trafficking and membrane dynamics studies employ live-cell compatible probes with reduced phototoxicity profiles.
Procurement concentrates in drug development; steepest expansion trajectory runs through clinical diagnostics as regulatory frameworks mature.
Technology:
Instrumentation installed base and image analysis infrastructure determine probe chemistry selection.
- Live Cell Imaging:Genetically encoded reporters and photostable fluorophores enable kinetic data collection over extended sessions. Pharmaceutical sponsors prioritize these formats for mechanism-of-action studies requiring temporal resolution.
- Fluorescence Microscopy:Widefield and confocal platforms anchor current demand through established protocols and trained operator pools.
- FISH:Fluorescence in situ hybridization maintains position in cytogenetic and gene amplification detection with specialized probe design services.
- PCR:Quantitative amplification methods support localization studies through complementary endpoint validation rather than direct spatial resolution.
Revenue gravity centers on fluorescence microscopy; share gains accrue fastest to live cell imaging as kinetic assays displace endpoint formats.
End User:
Purchasing authority and technical support requirements fragment the customer base across organizational types.
- Pharmaceutical Companies:Centralized procurement teams negotiate enterprise framework agreements bundling reagents with imaging instrumentation and software licenses. NIH-funded institutions face cost efficiency pressures through preferred supplier programs.
- Research Laboratories:Core facilities at academic medical centers cede autonomy to vendor management offices, consolidating around qualified suppliers with documented batch consistency.
- Academic Institutions:Federal reproducibility guidelines compel standardization of reagent sourcing, reinforcing consolidation trends among kit manufacturers.
- Biotechnology Firms:Distributed R&D outsourcing creates demand for vendors offering technical application support alongside reagent supply.
Spend aggregates with pharmaceutical companies; expansion concentrates in biotechnology firms as venture-funded pipelines proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorophore precursor manufacturing concentrates in Germany's Rhine-Ruhr chemical corridor and China's Yangtze River Delta, anchoring supply networks for localization kit producers across three continents.
United States
NIH funding patterns and biotech clustering sustain kit procurement volumes in Boston and San Diego. FDA oversight of companion diagnostic development shapes performance standards for clinical translation pathways. Pharmaceutical sponsors in these coastal hubs consume protein localization kits at scale for checkpoint inhibitor pipelines.
Germany
Merck KGaA leverages its chemical reagent heritage to anchor supply relationships with European research consortia. ECHA REACH regulations on aromatic amine compounds constrain rhodamine and cyanine dye building block availability. The Rhine-Main metropolitan region houses specialized probe chemistry operations serving academic core facilities.
China
Mammalian cell-derived secondary antibody production centers on Chinese contract manufacturing organizations, feeding global protein localization kit supply chains. NMPA medical device regulations increasingly influence quality documentation expectations for imported reagents. Shanghai's Zhangjiang Hi-Tech Park clusters gene editing service providers driving live-cell probe demand.
Japan
PMDA shonin filing requirements stretch regulatory affairs bandwidth for kit manufacturers targeting clinical diagnostic applications. METI industrial policy supports domestic precision medicine infrastructure development. The Kansai region's Osaka-Kobe biomedical corridor sustains demand for RNA localization formats in neuroscience programs.
United Kingdom
Abcam's Cambridge headquarters anchors a protein-specific detection protocol niche serving European pharmaceutical R&D groups. MHRA post-Brexit regulatory autonomy creates parallel compliance pathways for clinical-grade kits. The Oxford-Cambridge-London golden triangle concentrates academic medical center procurement authority.
Cellular Localization Kits Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-integrated image analysis services and CRISPR-compatible reporter systems. The vendor base stratifies around three functional tiers: diversified life science conglomerates bundling reagents with instrumentation, antibody-specialized boutiques defending protein detection niches, and CRISPR-tooling firms extending into subcellular tracking. Consolidation pressures intensify as enterprise procurement teams negotiate framework agreements spanning multiple reagent categories. Strategic partnerships between kit manufacturers and imaging platform vendors compress standalone margins while locking in recurring revenue streams.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify integrated workflow strategies that bundle localization reagents with complementary instrumentation. Abcam occupies a position among antibody-dependent specialists, representing the boutique archetype focused on protein-specific detection formats. These three entities illustrate competitive positioning across the spectrum from scale-driven platform bundling to defensible niche specialization in molecular probe supply.
| Leading Market Players |
|---|
| Merck KGaA |
| Abcam |
| Thermo Fisher Scientific |
| Promega Corporation |
| Santa Cruz Biotechnology |
| Cell Signaling Technology |
| Bio-Rad Laboratories |
| PerkinElmer |
| New England BioLabs |
| Others |
Value Network & Pricing Analysis
Live-cell compatible fluorophore chemistry migration simultaneously compresses production costs for established reagent formats and concentrates supply relationships around vendors with captive dye synthesis capabilities. Pharmaceutical procurement teams exploit this transition to extract volume discounts from qualified suppliers while locking out smaller competitors dependent on merchant fluorophore markets.
Pricing Analysis
Application support bundling separates premium-positioned kit vendors from commodity reagent suppliers, with ISO 13485-certified manufacturers commanding sustained margin premiums for companion diagnostic-grade formats. Price differentiation rests on batch documentation depth and regulatory file completeness rather than probe performance alone. Cost compression in standard immunofluorescence tiers is intensifying as Chinese antibody producers expand direct sales channels. Academic core facilities exhibit highest price sensitivity due to NIH budget constraints, while pharmaceutical sponsors prioritize total protocol cost over per-kit pricing.
Supply Chain Analysis
Specialized organic synthesis talent scarcity in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta constrains expansion of rhodamine and cyanine dye manufacturing capacity. Raw material flows draw from German aromatic amine precursors, Chinese mammalian cell culture facilities for antibody production, and South Korean fluorophore conjugation operations. Single-source vulnerability concentrates in locked nucleic acid monomer supply for RNA probe formats. Distribution runs through authorized distributor networks serving academic medical centers and direct enterprise agreements with pharmaceutical procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellular localization kits sector is executing a platform transition from fixed-cell endpoint assays to kinetic live-cell imaging systems, with genetically encoded reporters displacing conventional antibody-fluorophore conjugates in mechanism-of-action studies.
For Market Incumbents: To counter CRISPR-tooling firms extending into subcellular tracking, Thermo Fisher Scientific and Merck KGaA should deepen backward integration into photostable fluorophore chemistry and accelerate notified body engagement for companion diagnostic pathways. Enterprise framework agreements bundling reagents with imaging instrumentation represent the priority defensive lever. For New Entrants and Emerging Players: Distributed biotechnology firms with venture-funded gene editing pipelines constitute the most penetrable buyer archetype, as these organizations lack established vendor relationships and prioritize technical application support. RNA localization formats for neuroscience programs in Japan's Kansai region offer additional white-space opportunity. A subscription-based service model bundling localization reagents with AI-driven image analysis software provides differentiation against incumbent reagent-only positioning. For Investors and Strategic Acquirers: Re-rating potential sits with antibody-specialized boutiques possessing validated protein detection protocols given EMA In Vitro Diagnostic Regulation compliance burdens that favor incumbent expertise. Long-term viability over a five-to-ten year window favors vendors with dual capability in probe chemistry and regulatory file management. The signal to watch is FDA companion diagnostic approval velocity for HER2 and PD-L1 applications, which would validate premium pricing tiers and trigger acquisition interest.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Compatible Reporter Development | Genetically encoded systems capture live-cell imaging growth from pharmaceutical mechanism-of-action studies. |
| ISO 13485 Certification Investment | Regulatory qualification opens companion diagnostic pathways for HER2 and PD-L1 protein detection formats. |
| Backward Integration into Fluorophore Synthesis | Captive dye production insulates margins from REACH restrictions on aromatic amine precursors in Europe. |
| AI-Driven Image Analysis Platform Launch | Subscription bundling with localization reagents creates recurring revenue streams distinct from transactional kit sales. |
| Enterprise Framework Agreement Expansion | Centralized procurement at NIH-funded institutions consolidates vendor relationships and compresses competitor access. |
Research Methodology
SEC filings, EMA regulatory submissions, and NIH RePORTER grant databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with drug development executives, regulatory affairs leads at kit manufacturers, core facility directors at academic medical centers, and pharmaceutical procurement managers validated demand patterns and pricing dynamics. Bottom-up segment sizing triangulated against top-down industry expenditure estimates derived from federal research funding flows and pharmaceutical R&D disclosure.
Historical trendline analysis of reagent procurement volumes across product chemistry, application context, and end-user type established baseline growth trajectories. The analytical framework modeled segmentation across detection target complexity, regulatory exposure tier, instrumentation platform compatibility, and purchasing authority concentration throughout the projection horizon. CAGRs were derived from fitted growth curves adjusted for NIH funding patterns, CRISPR adoption rates, and companion diagnostic regulatory filing velocity.
Revisions become necessary when EPA chemical substance notifications, evolving REACH restrictions on fluorophore precursors, or PMDA regulatory timeline extensions materialize beyond baseline assumptions. Forecasts reflect documented procurement patterns and vendor capacity expansion plans subject to these contingent triggers. Material deviation in fluorophore precursor availability or companion diagnostic approval velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Single-Use Bioreactor Bag Integrity and Leak Test Equipment Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Small-Scale Bioreactors Market
Biotechnology Equipment
Global Biological Microscope Objectives Market