
 Global Protein Characterization and Quantification Market | 2026-2036
Global Protein Characterization and Quantification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Characterization and Quantification Market Foresight
Pharma-grade mass spectrometry resolution is collapsing the gap between research and GMP-release testing. Thermo Fisher Scientific leverages its Orbitrap platform dominance to anchor high-resolution workflows across biopharma QC labs. Agilent Technologies competes through integrated LC-MS systems that sustain instrument-to-instrument reproducibility for regulated environments. Danaher Corporation differentiates via Pall filtration paired with SCIEX mass spec, occupying a niche in process analytical technology.
Protein characterization and quantification encompasses analytical methods that determine molecular weight, purity, post-translational modifications, and concentration of proteins through techniques operating at picomole sensitivity and mass accuracy below 5 ppm. These capabilities enable batch release decisions for biologics, allergen detection in food matrices, and biomarker validation in clinical research. Mass spectrometry leads in revenue contribution due to capital intensity and software attach rates, while immunoassay growth accelerates in point-of-care infectious disease panels where speed outweighs absolute specificity. Academic research remains a volume anchor for electrophoresis, though margin pools sit with cloud-integrated platforms serving multi-site pharmaceutical networks.
FDA enforces ICH Q5E and Q6B guidelines that mandate comparability protocols for protein therapeutics, directly shaping instrument qualification requirements and software validation burdens. EMA's MDR and REACH frameworks govern in-vitro diagnostic reagents and chemical standards used in European protein assays, while China's NMPA aligns GB standards with ICH guidelines to accelerate biosimilar approvals. Stakeholders must monitor how AI-enabled deconvolution algorithms reshape regulatory acceptance of automated peak identification without manual spectral review.
Market Dynamics
Biopharmaceutical manufacturers are consolidating analytical workflows around high-resolution mass spectrometry platforms that collapse the traditional separation between R&D characterization and GMP-release testing, compressing capital deployment timelines and forcing vendor consolidation.
Growth Catalysts
- ICH Q5E Comparability Mandates:FDA and EMA enforcement of protein therapeutic comparability protocols drives instrument qualification spending across biologics QC labs.
- Monoclonal Antibody Pipeline Expansion:Biosimilar developers in China, Germany, and the United States require expanded purity verification capacity for batch release decisions.
- Cloud-Integrated Multi-Site Platforms:Pharmaceutical networks spanning Boston, Basel, and Shanghai deploy centralized data architectures for cross-facility method transfer.
Market Restraints
- Helium Supply Volatility:Mass spectrometry operations face input cost pressure from concentrated noble gas sourcing through Algeria, Qatar, and Russia.
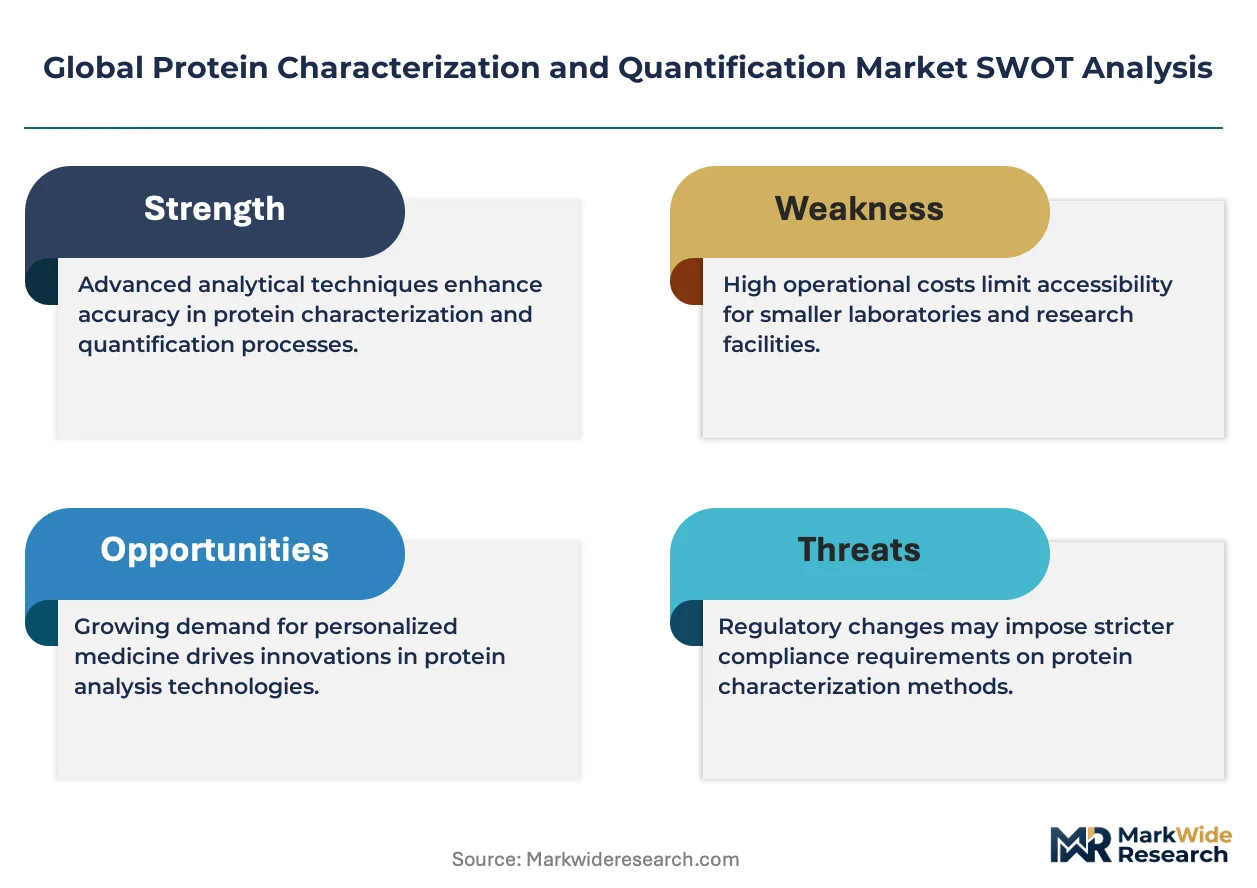
- Capital Intensity of Orbitrap Systems:Sub-5 ppm mass accuracy instruments require seven-figure capital commitments that constrain mid-tier CMO adoption.
- Software Validation Burdens:FDA 21 CFR Part 11 compliance timelines extend deployment cycles for AI-enabled peak identification algorithms.
Strategic Opportunities
- Point-of-Care Infectious Disease Panels:Immunoassay manufacturers target speed-sensitive diagnostic settings where absolute specificity trades off against turnaround time.
- Process Analytical Technology Integration:Real-time protein quantification during upstream bioprocessing converges spectroscopy with filtration skids for continuous manufacturing.
- India's Biosimilar Export Push:CDSCO alignment with ICH guidelines creates regulatory runway for analytical service providers supporting contract manufacturing.
Industry Challenges
- Spectral Interpretation Talent Scarcity:Biopharma QC labs compete for mass spectrometrists capable of manual spectral review for regulatory submissions.
- Legacy Electrophoresis System Integration:Academic and industrial labs face friction migrating decades of SDS-PAGE method databases to cloud-native platforms.
- Cross-Platform Reproducibility Certification:Multi-vendor LC-MS environments struggle with instrument-to-instrument variation under ISO 17025 accreditation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Characterization and Quantification Market |
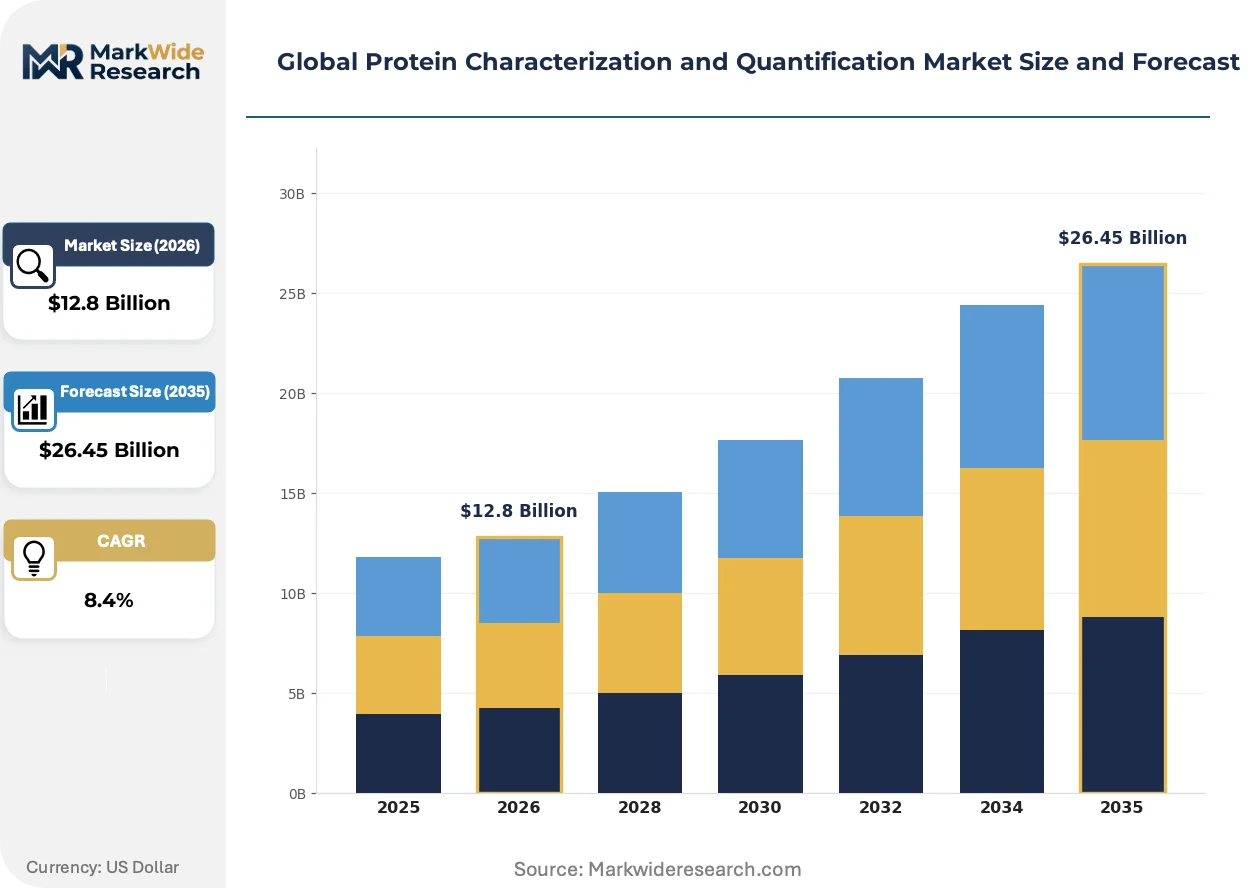
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Spectrometry, Chromatography, Electrophoresis, Immunoassay, Surface Plasmon Resonance Application: Biopharmaceutical Development, Food Safety Analysis, Environmental Monitoring, Academic Research, Cosmetic Testing End User: Biotechnology Firms, Pharmaceuticals, Academic Laboratories, Food Testing Laboratories, Contract Research Organizations Deployment: Laboratory-based, Point-of-Care, Mobile Units, Cloud-integrated Platforms, Automated Systems |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Merck KGaA, Danaher Corporation, Waters Corporation, Bio-Rad Laboratories, PerkinElmer, Shimadzu Corporation, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Characterization and Quantification Market Shifts & Advancements
Artificial intelligence is penetrating spectral deconvolution workflows, regulatory agencies are codifying automated data integrity standards, and procurement patterns are fragmenting between centralized pharmaceutical networks and distributed point-of-care diagnostics.
Native mass spectrometry of intact protein complexes is displacing traditional bottom-up proteomics in biopharma QC environments. Contract manufacturing organizations in Basel and Boston adopt non-denaturing workflows to preserve quaternary structure during mAb aggregate detection. This shift is displacing lengthy peptide mapping protocols that previously dominated release testing timelines.
EMA's Medical Device Regulation and FDA's evolving guidance on AI-enabled analytical software are tightening validation requirements for automated peak calling. Biologics manufacturers must now document algorithm training sets and decision thresholds for regulatory submissions. Small-molecule CMOs in Germany and Switzerland are most affected, responding by embedding quality-by-design into software development lifecycles.
Service unbundling now separates instrument hardware from cloud-based data analysis subscriptions. Academic core facilities and mid-sized biotechs in Cambridge, Heidelberg, and Shanghai purchase mass spectrometry detection capability while outsourcing spectral interpretation to specialized bioinformatics vendors. This pattern is most visible in proteomics service bureaus competing on turnaround time rather than capital ownership.
Global Protein Characterization and Quantification Market Segmentation
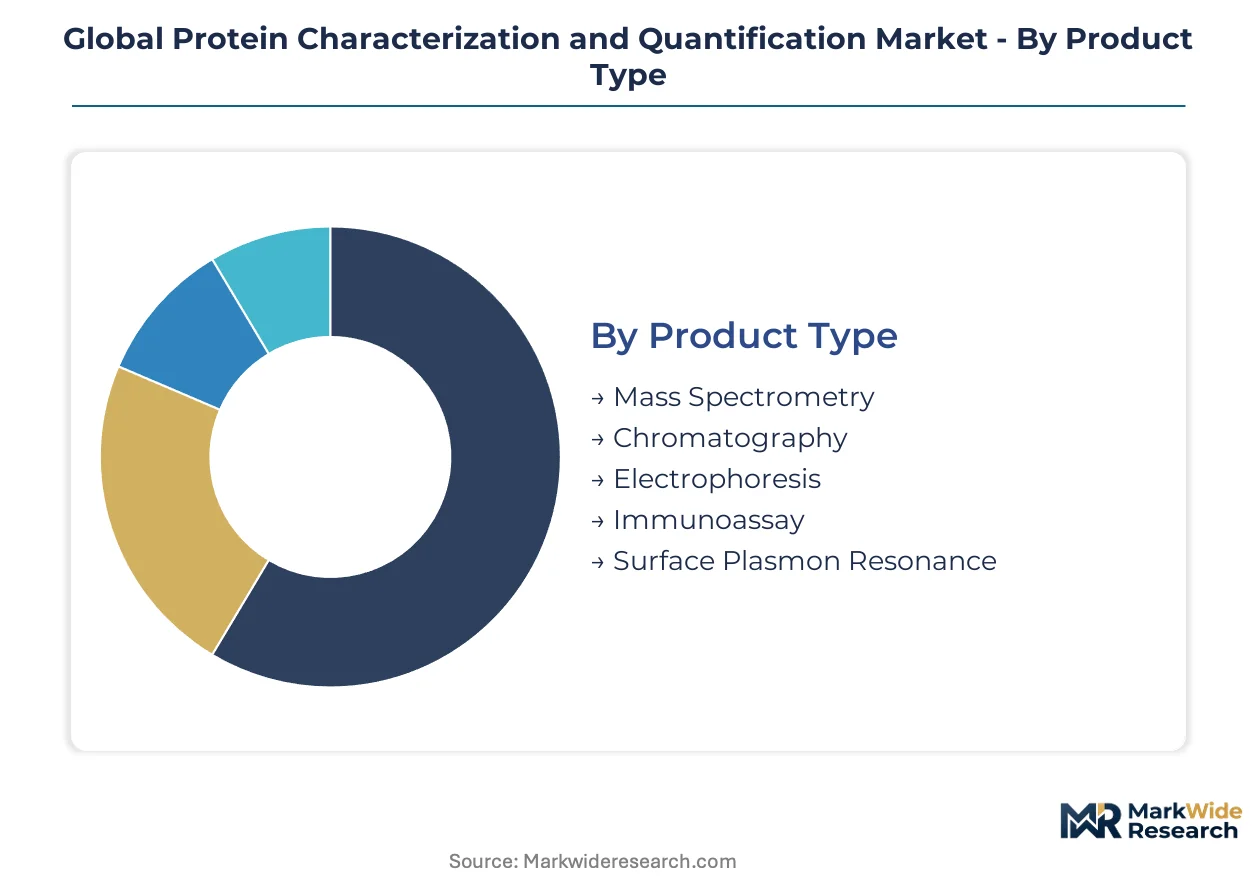
Protein characterization and quantification segments fragment across technology maturity curves, with established platforms facing displacement pressure from integrated workflows. Substitution dynamics vary sharply by end-use: GMP-release testing demands capital-intensive precision, while point-of-care settings prioritize speed over absolute specificity.
Product Type:
Mass spectrometry platforms face the most acute substitution pressure from cloud-integrated multi-modal systems that collapse previously separate analytical steps into unified workflows.
- Mass Spectrometry:High-resolution Orbitrap and Q-TOF systems deliver sub-5 ppm mass accuracy for monoclonal antibody aggregate detection and post-translational modification mapping. Demand concentrates in United States and German biopharma QC labs where FDA and EMA comparability mandates drive seven-figure capital commitments for GMP-release testing.
- Chromatography:LC and HPLC systems anchor purity verification workflows through size-exclusion and ion-exchange separations. United States and Chinese biosimilar developers in Boston and Shanghai clusters deploy these systems for batch consistency protocols under tightening ICH Q5E enforcement.
- Electrophoresis:SDS-PAGE and capillary systems retain academic volume for protein separation at lower capital thresholds.
- Immunoassay:ELISA and chemiluminescence platforms target infectious disease panels where turnaround time outweighs mass accuracy requirements.
- Surface Plasmon Resonance:Label-free binding kinetics systems serve biopharma R&D for antibody-antigen interaction characterization.
Mass spectrometry retains volume leadership; immunoassay holds the steepest expansion curve as point-of-care infectious disease testing accelerates.
Application:
Cost tier stratification separates capital-intensive biopharmaceutical development from price-sensitive environmental monitoring contracts.
- Biopharmaceutical Development:Monoclonal antibody and biosimilar pipelines require comprehensive characterization spanning intact mass analysis, peptide mapping, and aggregate quantification. German and Swiss contract manufacturing organizations in Basel and Munich invest most heavily in multi-attribute method platforms under EMA MDR compliance timelines.
- Food Safety Analysis:Allergen detection and protein adulteration screening deploy LC-MS/MS and immunoassay workflows for regulatory compliance. Chinese food testing laboratories under GB standards and United States facilities under FDA FSMA rules drive dual-hemisphere demand for high-throughput screening.
- Environmental Monitoring:Protein biomarker tracking in water and soil matrices employs portable immunoassay and spectroscopy systems.
- Academic Research:Core facilities maintain electrophoresis and basic mass spectrometry for discovery proteomics at constrained budgets.
- Cosmetic Testing:Protein content verification for allergen labeling supports regulatory compliance in European and Asian personal care markets.
Biopharmaceutical development commands the highest per-site spending; food safety analysis is expanding most quickly as regulatory jurisdictions broaden mandatory testing scope.
End User:
Customer type determines procurement pattern: pharmaceutical networks centralize multi-site platforms while academic laboratories favor service unbundling.
- Biotechnology Firms:Venture-backed developers in Cambridge, Heidelberg, and Shanghai deploy cloud-integrated mass spectrometry for rapid CMC package assembly. These firms prioritize speed-to-IND over capital efficiency, driving subscription-based software attach rates for automated data analysis.
- Pharmaceuticals:Large-cap biologics manufacturers consolidate analytical operations around high-resolution platforms that bridge R&D and QC functions. United States and German facilities lead this convergence under FDA and EMA pressure to compress method transfer timelines.
- Academic Laboratories:Core facilities fragment procurement between instrument ownership and outsourced spectral interpretation services.
- Food Testing Laboratories:Third-party certifiers balance throughput against ISO 17025 accreditation requirements for multi-platform reproducibility.
- Contract Research Organizations:Analytical service providers compete on turnaround time through dedicated biopharma and food safety business units.
Pharmaceuticals retain volume leadership; contract research organizations hold the steepest expansion curve as outsourcing penetrates mid-tier biotech analytical needs.
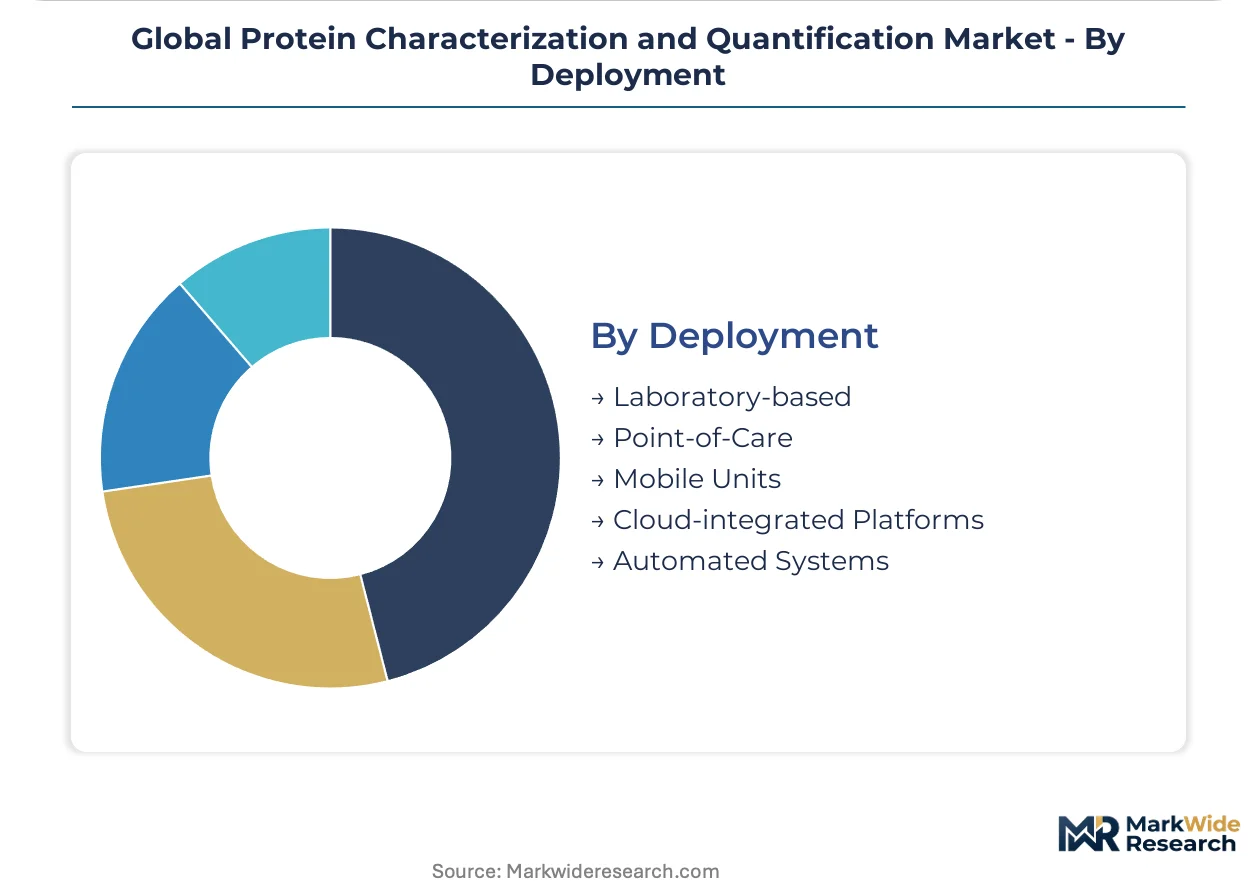
Deployment:
Supply concentration in laboratory-based systems is fragmenting toward distributed point-of-care and mobile configurations.
- Laboratory-based:Fixed installations in regulated QC environments dominate revenue through capital intensity and service contract attach. United States, German, and Chinese biopharma manufacturing clusters anchor this segment under FDA, EMA, and NMPA qualification requirements.
- Point-of-Care:Compact immunoassay and portable mass spectrometry systems target infectious disease diagnostics and field-based food safety screening. Indian and Brazilian healthcare networks under CDSCO and ANVISA frameworks drive emerging market penetration.
- Mobile Units:Trailer-mounted laboratories serve environmental monitoring and emergency response applications.
- Cloud-integrated Platforms:Centralized data architectures enable cross-facility method transfer for pharmaceutical networks spanning multiple countries.
- Automated Systems:Robotic sample handling reduces manual intervention for high-throughput biopharma QC workflows.
Laboratory-based deployment retains volume leadership; cloud-integrated platforms hold the steepest expansion curve as multi-site pharmaceutical networks consolidate data architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports analytical instrumentation to biopharma clusters in Basel and Boston, while China imports high-resolution mass spectrometry platforms for biosimilar manufacturing scale-up. Trade corridors concentrate capital equipment flows from European precision manufacturers to Asian contract development organizations.
United States
FDA enforces ICH Q5E comparability protocols that mandate instrument qualification spending across biologics QC labs. The agency's 21 CFR Part 11 compliance timelines extend deployment cycles for AI-enabled peak identification software. Boston and San Francisco biotech corridors drive cloud-integrated mass spectrometry adoption for rapid CMC package assembly.
Germany
EMA's MDR framework governs in-vitro diagnostic reagents used in European protein assays, tightening validation requirements for automated analytical software. REACH chemical standards constrain reagent sourcing for multi-attribute method platforms. Munich and Basel-area contract manufacturing organizations invest most heavily in native mass spectrometry workflows for mAb aggregate detection.
China
NMPA aligns GB standards with ICH guidelines to accelerate biosimilar approvals, expanding purity verification capacity demands. The regulator's quality-by-design mandates reshape software validation burdens for automated data integrity. Shanghai and Suzhou biologics manufacturing clusters anchor demand for high-resolution Orbitrap systems under tightening batch release protocols.
Switzerland
Swissmedic enforces pharmaceutical manufacturing standards that converge with EMA MDR compliance timelines for analytical service providers. The country's dual-accession to EU regulatory frameworks streamlines instrument qualification for cross-border biopharma networks. Basel anchors contract manufacturing demand for non-denaturing mass spectrometry workflows that preserve quaternary structure during release testing.
India
CDSCO alignment with ICH guidelines creates regulatory runway for analytical service providers supporting contract manufacturing export growth. The PLI scheme for pharmaceuticals incentivizes domestic production of diagnostic reagents and reference standards. Hyderabad and Bengaluru biotech corridors attract investment in electrophoresis and chromatography capacity for biosimilar development.
Global Protein Characterization and Quantification Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and software attach rate dimensions. Thermo Fisher Scientific and Danaher Corporation anchor the public-company tier with integrated platform portfolios, while family-owned precision instrument makers occupy mid-market chromatography and electrophoresis segments. Strategic archetypes separate high-resolution mass spectrometry platform owners from filtration-skid integrators and reagent specialists. Competitive moves concentrate on cloud-native data architecture partnerships and service unbundling that separates instrument hardware from subscription-based spectral interpretation.
Within the platform-dominance archetype, Thermo Fisher Scientific exemplifies Orbitrap ecosystem control across biopharma QC labs. Agilent Technologies occupies a position among integrated LC-MS system providers competing on instrument-to-instrument reproducibility. Danaher Corporation anchors the filtration-mass spec convergence niche through Pall-SCIEX combination strategies for process analytical technology.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Merck KGaA |
| Danaher Corporation |
| Waters Corporation |
| Bio-Rad Laboratories |
| PerkinElmer |
| Shimadzu Corporation |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month lead times for Orbitrap mass spectrometry systems concentrate pricing power with German and United States precision manufacturers, while helium supply volatility through Algerian and Qatari sourcing injects cost unpredictability into consumables pricing for biopharma QC labs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Global Protein Characterization and Quantification Market. Price differentiation rests on FDA 21 CFR Part 11 certification tier and after-sales service bundling for GMP-release environments. Cost compression in mid-tier chromatography systems is intensifying because Chinese biosimilar developers negotiate volume scale discounts. Academic core facilities exhibit highest price sensitivity; large-cap biologics manufacturers show lowest sensitivity due to speed-to-IND priorities.
Supply Chain Analysis
Germany and the United States anchor precision instrumentation manufacturing for high-resolution mass spectrometry platforms serving biopharma QC networks. Critical component dependencies include superconducting magnets, noble gas purification systems, and specialized ion optics. Single-source vulnerability concentrates in helium feedstock through Algerian and Qatari suppliers. Distribution runs through direct manufacturer relationships with large pharmaceutical networks and regional distributors serving academic core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as cloud-integrated multi-site platforms penetrate pharmaceutical networks spanning Boston, Basel, and Shanghai, compressing method transfer timelines that previously fragmented analytical operations.
For Market Incumbents: Secure cloud-native data architecture partnerships before AI-enabled spectral deconvolution algorithms commoditize peak identification workflows. Invest in ISO 17025 certification expansion for cross-platform reproducibility to defend against mid-tier CMO price competition. Lock in long-term helium supply agreements to stabilize consumables margins against Algerian and Qatari sourcing volatility. For New Entrants and Emerging Players: Cloud-based spectral interpretation services represent the most penetrable white-space where Thermo Fisher and Danaher under-serve mid-tier biotechs in Cambridge and Heidelberg. Target India's CDSCO-aligned contract manufacturing corridor with subscription-based bioinformatics offerings. Lead with turnaround-time guarantees rather than capital ownership to differentiate from incumbent hardware bundling. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EMA comparability mandates create sticky instrument qualification spending that outlasts product cycle volatility. Acquisition targets should display embedded software attach rates above hardware margins and multi-site pharmaceutical network relationships. Watch NMPA biosimilar approval velocity as the inflection signal for Chinese manufacturing cluster equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Enables cross-facility method transfer for pharmaceutical networks under FDA 21 CFR Part 11 compliance. |
| Helium Supply Agreement | Stabilizes input costs for mass spectrometry operations facing Algerian and Qatari sourcing concentration. |
| ISO 17025 Accreditation Expansion | Certifies instrument-to-instrument reproducibility for multi-vendor LC-MS environments in regulated QC labs. |
| AI-Enabled Spectral Deconvolution | Accelerates automated peak identification while navigating EMA MDR software validation timelines. |
| India Biosimilar Service Bureau | Captures CDSCO-aligned contract manufacturing export growth with electrophoresis and chromatography capacity. |
Research Methodology
Cross-validation between primary interviews with biopharma QC directors, regulatory affairs leads, mass spectrometry core facility managers, and CMO procurement officers anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA scientific advice letters, NMPA biosimilar approval databases, and instrument vendor SEC disclosures. Bottom-up triangulation across technology segment demand and top-down reconciliation against biologics manufacturing capacity expansion ensures analytical coherence.
Sensitivity analysis across the projection horizon models technology type, application tier, end-user archetype, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from instrument shipment tracking, software attach rate trends, and biopharma capital expenditure patterns. Forecast inputs include monoclonal antibody pipeline expansion rates and cloud platform adoption curves across pharmaceutical network configurations.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA comparability frameworks; material policy shifts would require re-modeling. Specific risks include helium supply disruption, AI-enabled software validation delays, and biosimilar approval velocity deceleration. Recalibration cycles align with material shifts in biologics manufacturing capacity expansion and regulatory guidance publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Fluorescent in Situ Hybridization Market