
 North America Life Science Tools Market | 2026-2036
North America Life Science Tools Market Size, Share, and Industry Trends Forecast 2026-2036
North America Life Science Tools Market Intelligence
Buyer concentration among contract research organizations and large pharmaceutical houses is repositioning procurement power toward volume-committed purchasing agreements. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to anchor long-term supply relationships with top-tier buyers. Danaher Corporation competes through operational excellence and brand strength in consumables workflows. Illumina, Inc. specializes in sequencing instrumentation, dominating the genomics technology layer with platform-specific consumable pull-through.
Life science tools encompass instruments, reagents, consumables, and software designed for biological sample analysis, with specifications ranging from picoliter fluidic precision in liquid handlers to mass accuracy below 1 ppm in high-resolution mass spectrometry. Their primary commercial purpose is enabling reproducible generation of quantitative biological data for therapeutic development and clinical decision-making. Reagents and consumables capture recurring revenue streams with higher margin stability than capital-intensive instruments, while genomics applications within drug discovery represent the fastest-expanding demand node. Flow cytometry and mass spectrometry technologies lead in proteomics and cell analysis, though PCR maintains installed-base depth across molecular biology laboratories.
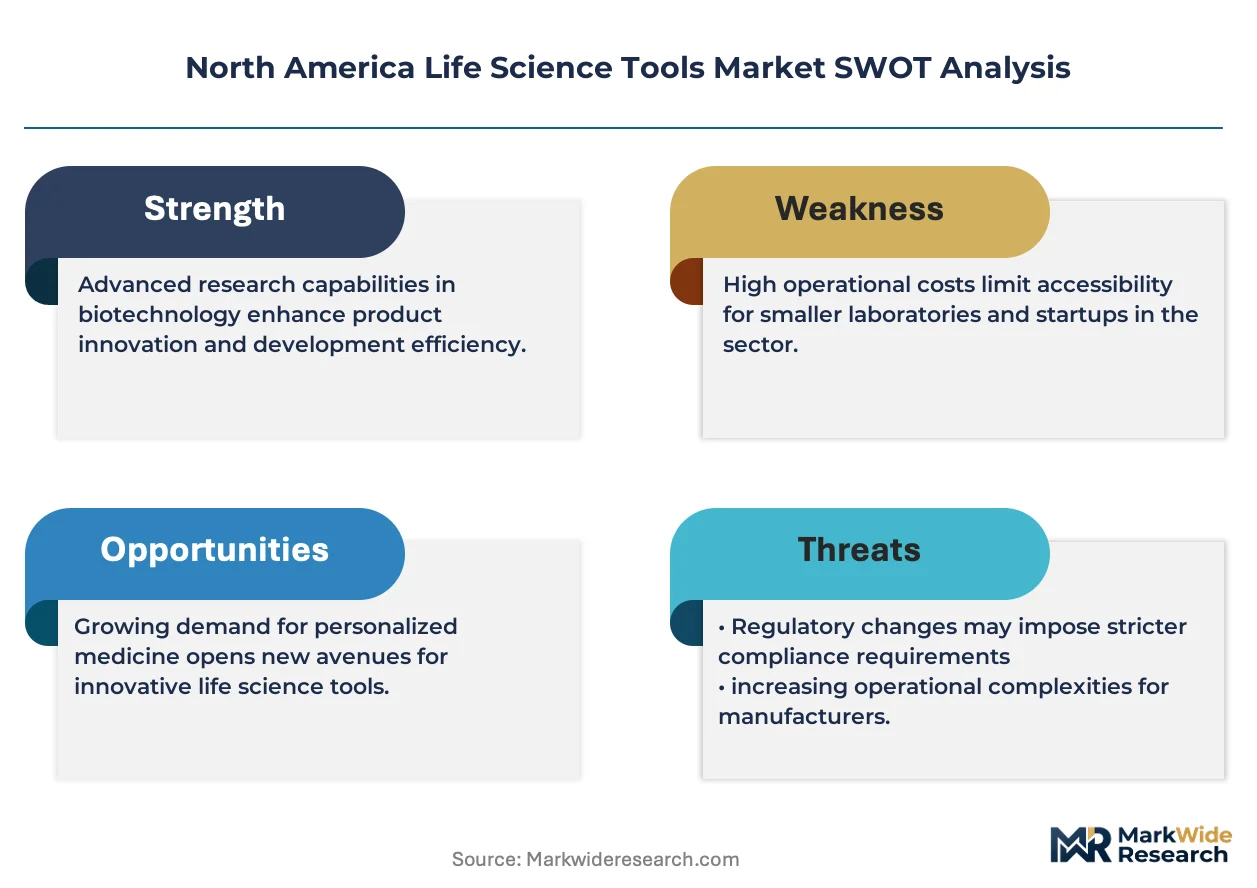
FDA quality system regulation and guidance documents for in vitro diagnostics shape design control requirements and predicate device pathways for new tool introductions. EPA standards for laboratory waste streams and chemical handling influence reagent formulation decisions and facility compliance costs across manufacturing and end-use sites. Health Canada and the FDA's parallel review programs for breakthrough devices create divergent but harmonizing regulatory tracks that stakeholders must monitor for market access timing and clinical validation requirements.
Market Dynamics
Pharmaceutical houses and CROs are consolidating procurement power through multi-year reagent supply agreements, compressing vendor margins while locking in volume commitments that reshape competitive positioning across the reagent-instrument stack.
Growth Catalysts
- FDA quality system regulation:The agency's predicate device pathway for next-generation sequencing tools accelerates market entry timelines for innovative platforms targeting clinical diagnostics.
- Cell and gene therapy manufacturing:Commercial-scale production of CAR-T therapies and viral vectors demands specialized analytical instrumentation and single-use consumables across the Boston-Cambridge corridor.
- CRISPR-based drug discovery:Gene editing workflows in target validation and functional genomics are pulling high-throughput screening platforms and associated reagent volumes.
Market Restraints
- Helium supply volatility:Mass spectrometry and cryogenic storage systems depend on constrained helium extraction, with price spikes disrupting instrument operating costs and service contracts.
- Reagent import concentration:Critical enzymes and modified nucleotides originate from concentrated Asian manufacturing hubs, exposing North American users to shipping delays and tariff exposure.
- Cross-platform incompatibility:Proprietary consumable formats lock laboratories into single-vendor ecosystems, limiting price competition and experimental flexibility.
Strategic Opportunities
- Canadian biomanufacturing expansion:Health Canada's parallel review programs for breakthrough devices create faster market access for sequencing and cell analysis platforms in Toronto and Montreal clusters.
- AI-integrated liquid handling:Machine learning optimization of pipetting protocols and error detection is converging with acoustic dispensing to reduce reagent waste and protocol development time.
- EPA green chemistry mandates:Laboratory waste stream regulations are creating pull for aqueous buffer formulations and biodegradable consumable materials that reduce hazardous disposal costs.
Industry Challenges
- Bioinformatics talent scarcity:Genomics and proteomics platforms generate data volumes exceeding the analytical capacity of trained computational biologists, creating bottlenecks in interpretation workflows.
- Instrument qualification timelines:FDA 21 CFR Part 11 compliance and software validation requirements extend deployment cycles for electronic laboratory notebook integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Life Science Tools Market |
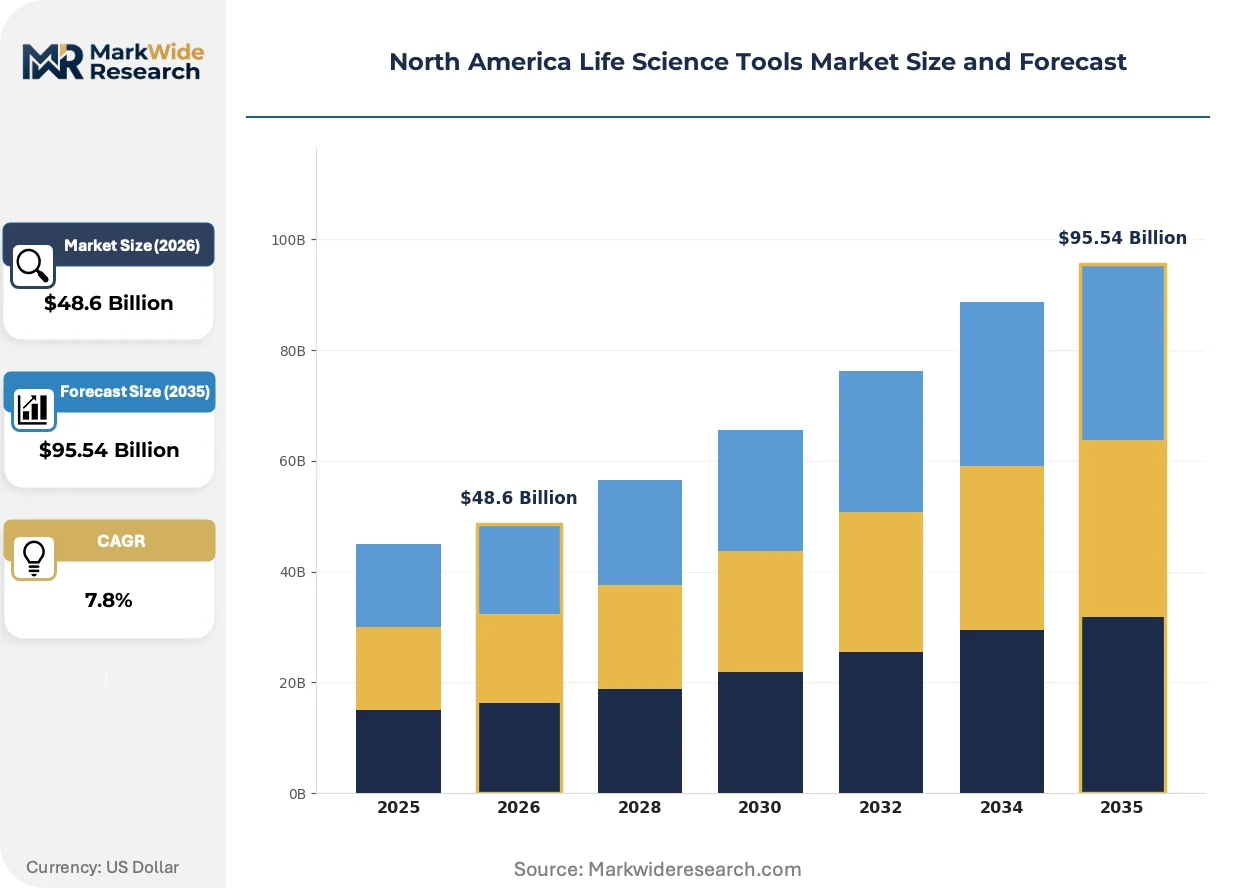
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $95.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Software End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Laboratories Application: Drug Discovery, Genomics, Proteomics, Molecular Biology Technology: Flow Cytometry, Mass Spectrometry, PCR, Immunoassays |
| Companies Covered | Thermo Fisher Scientific, Inc., Agilent Technologies, Illumina, Inc., Danaher Corporation, Becton, Dickinson and Company, Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd., Merck KGaA, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Life Science Tools Market Strategic Shifts & Innovations
Multi-omics integration is collapsing traditional boundaries between genomics, proteomics, and metabolomics workflows, forcing vendors to rearchitect instrument platforms around unified data outputs rather than single-analyte specialization.
Spatial transcriptomics is unifying tissue morphology with gene expression mapping at single-cell resolution. Academic medical centers and pharmaceutical discovery groups are adopting these platforms at accelerating pace. The technology is compressing the timeline from tissue sample to therapeutic hypothesis by embedding histopathological context directly into molecular profiling workflows.
The FDA's guidance on next-generation sequencing-based oncology panels is tightening analytical validation requirements for tumor mutational burden and microsatellite instability reporting. Clinical laboratories must now demonstrate traceability to reference materials and cross-platform concordance. High-complexity molecular diagnostics facilities in California and Massachusetts are responding by building in-house bioinformatics pipelines rather than relying on vendor-hosted solutions.
Consolidated purchasing through group purchasing organizations is displacing direct vendor relationships for consumables and reagents. Academic consortia and mid-sized biotechnology firms are aggregating demand through shared service centers and core facility networks. This concentration is most visible in the San Francisco Bay Area, where institutional buyers negotiate enterprise licenses spanning multiple research campuses.
North America Life Science Tools Market Segmentation
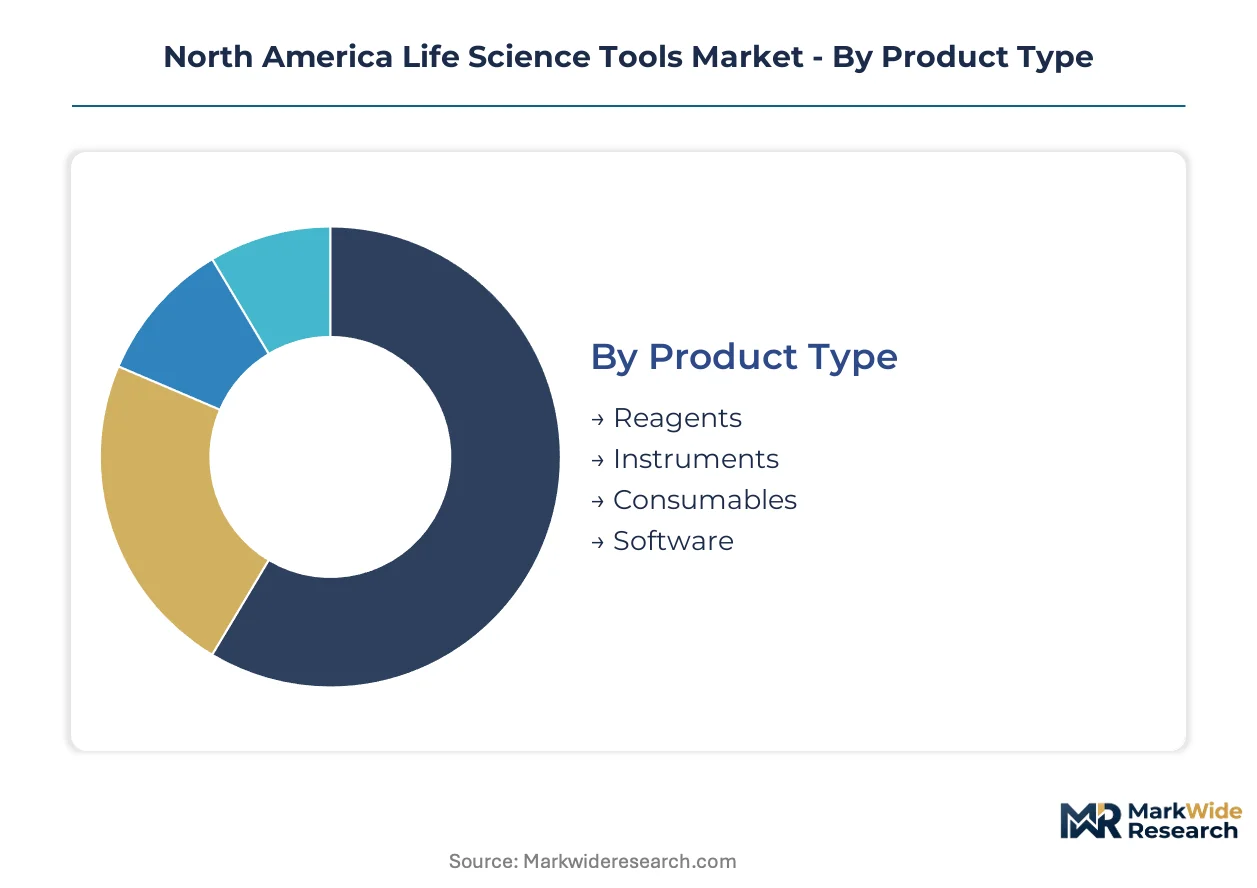
Segmentation in life science tools reveals how procurement power, technical specifications, and regulatory requirements reshape vendor strategies across distinct buyer ecosystems. Understanding these divides exposes where margin stability concentrates versus where price competition intensifies.
Product Type:
Procurement committees weight total cost of ownership differently across capital equipment versus recurring spend categories, with reagent contracts now spanning multi-year enterprise agreements.
- Reagents:Enzymes, buffers, and modified nucleotides formulated to precise activity specifications drive recurring revenue streams with higher margin stability. Demand concentrates in pharmaceutical discovery groups across the Boston-Cambridge corridor, where CRISPR workflows and high-throughput screening protocols consume specialty reagents at scale.
- Instruments:Capital equipment ranging from liquid handlers to mass spectrometers requires extensive qualification timelines and service contract negotiations. The San Francisco Bay Area's academic medical centers and biotechnology firms anchor installed-base expansion, though helium supply volatility disrupts cryogenic system operating costs.
- Consumables:Single-use plastics, tips, and plates designed for specific instrument platforms lock laboratories into vendor ecosystems.
- Software:Laboratory information management systems and bioinformatics pipelines face FDA 21 CFR Part 11 compliance burdens.
Reagents lead on scale; software leads on momentum.
End User:
Volume concentration and technical sophistication diverge sharply across buyer types, with large pharmaceutical houses extracting pricing concessions unavailable to smaller research entities.
- Pharmaceutical Companies:Multi-site R&D organizations with centralized procurement functions negotiate enterprise reagent agreements and instrument fleet standardization. Massachusetts and California facilities drive demand for next-generation sequencing platforms and associated consumable pull-through.
- Biotechnology Firms:Venture-funded discovery shops prioritize speed-to-data over capital efficiency, adopting spatial transcriptomics and multi-omics platforms earlier than institutional counterparts.
- Academic Institutions:Shared core facility models aggregate demand across research groups, with consortia purchasing displacing direct vendor relationships.
- Laboratories:Clinical diagnostics and reference laboratories face tightening FDA analytical validation requirements for tumor mutational burden reporting.
Pharmaceutical companies anchor volume; biotechnology firms drive technology adoption velocity.
Application:
Workflow integration requirements and data output standards fragment vendor positioning across therapeutic development stages.
- Drug Discovery:Target validation and lead optimization workflows demand high-throughput screening infrastructure and CRISPR reagent volumes. The San Francisco Bay Area's discovery biotechnology cluster sustains demand for acoustic dispensing and automated liquid handling.
- Genomics:Next-generation sequencing and spatial transcriptomics platforms generate data volumes exceeding bioinformatics capacity. Clinical laboratories in California and Massachusetts respond to FDA oncology panel guidance by building in-house analytical pipelines.
- Proteomics:Mass spectrometry workflows for biomarker discovery depend on helium-cooled instruments vulnerable to supply disruptions.
- Molecular Biology:PCR maintains deep installed-base penetration across research and clinical settings, with quantitative and digital formats displacing endpoint methods.
Drug discovery commands capital deployment; genomics claims the steepest expansion trajectory.
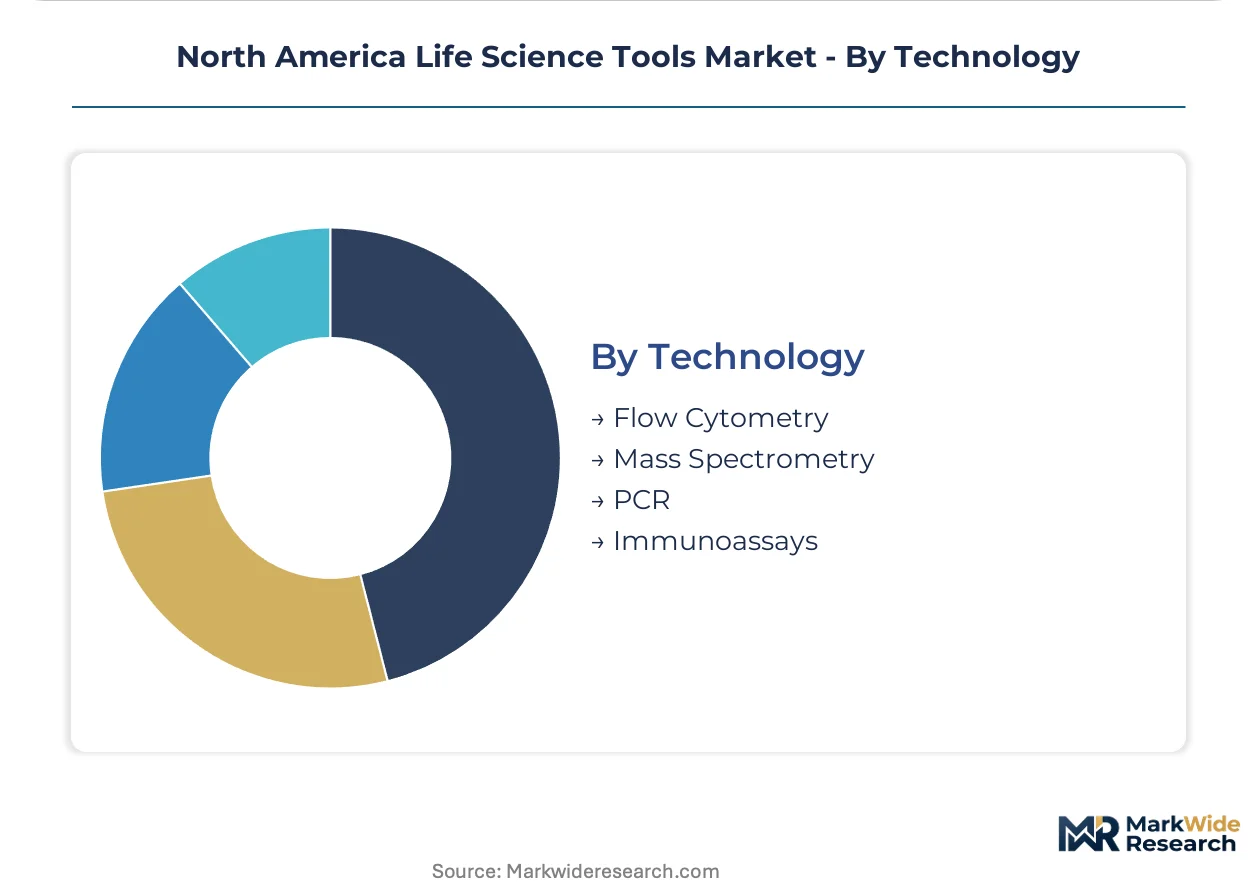
Technology:
Platform-specific consumable economics and cross-vendor compatibility constraints structure competitive dynamics.
- Flow Cytometry:Multi-parameter cell analyzers and sorters with picoliter fluidic precision enable single-cell proteomics workflows. Academic medical centers in Toronto and Montreal adopt spectral cytometry platforms under Health Canada's parallel review programs.
- Mass Spectrometry:High-resolution instruments achieving sub-1 ppm mass accuracy anchor metabolomics and proteomics discovery. Helium dependency for cryogenic cooling exposes operators to price volatility and service contract renegotiation.
- PCR:Thermal cycling infrastructure spans quantitative, digital, and isothermal formats with extensive installed-base depth.
- Immunoassays:Enzyme-linked and chemiluminescent detection systems serve clinical diagnostics and biomarker quantification.
Mass spectrometry leads on analytical specification; flow cytometry leads on clinical adoption momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater procurement volume than Canada, though Canadian regulatory pathways now attract accelerated platform launches for sequencing and cell analysis technologies.
United States
Pharmaceutical discovery groups and contract research organizations drive reagent consumption at scale, particularly for CRISPR workflows and high-throughput screening protocols. FDA quality system regulation and predicate device pathways for next-generation sequencing tools compress market entry timelines for innovative diagnostic platforms. The Boston-Cambridge corridor and San Francisco Bay Area concentrate demand for spatial transcriptomics and multi-omics instrumentation.
Canada
Health Canada's parallel review programs for breakthrough devices enable faster regulatory clearance for sequencing and cell analysis platforms compared to standard FDA timelines. Toronto and Montreal clusters attract biomanufacturing expansion as pharmaceutical houses seek diversified North American production capacity. Academic medical centers in Ontario and Quebec adopt spectral cytometry platforms under accelerated device review frameworks.
Mexico
Contract manufacturing organizations serving US pharmaceutical clients expand analytical quality control capabilities to support regional drug substance production. COFEPRIS regulatory alignment with FDA standards facilitates cross-border instrument qualification and reagent importation. The Mexico City metropolitan area and Nuevo León host growing laboratory services infrastructure for clinical trial sample analysis.
North America Life Science Tools Market Key Industry Players
US-based producers anchor the premium instrumentation tier; European specialists hold dominant positions in reagent and consumables workflows. Market structure concentrates around integrated reagent-instrument ecosystems that lock laboratories into recurring consumable purchases. Three archetypes define competitive positioning: diversified conglomerates with full-stack portfolios, platform specialists dominating genomics or proteomics layers, and regional reagent manufacturers serving price-sensitive segments. Dominant competitive moves include multi-year enterprise supply agreements that compress vendor margins while securing volume commitments, and strategic partnerships between instrument makers and bioinformatics providers to address data interpretation bottlenecks.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify integrated ecosystem strategies that bind customers through consumable pull-through economics. Illumina, Inc. occupies a specialist position anchored in sequencing instrumentation and platform-specific reagent dependency. These three entities represent distinct competitive vectors: full-stack integration, operational excellence in consumables workflows, and technology-layer dominance in genomics applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Agilent Technologies |
| Illumina, Inc. |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Merck KGaA |
| QIAGEN |
| Others |
Cost & Logistics Intelligence
CRISPR reagent manufacturing automation in South Korea and Singapore is compressing per-unit production costs while simultaneously concentrating high-activity enzyme supply among three dominant fermentation facilities. This dual shift tightens vendor margins for North American distributors even as it secures multi-year volume commitments from pharmaceutical procurement committees.
Pricing Analysis
Capacity additions in Singapore and South Korea are reshaping price floors for modified nucleotides and recombinant enzymes. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA quality system certification tier and helium-cooled instrument compatibility. Cost compression in standard-grade reagents is intensifying because CROs aggregate demand through enterprise purchasing agreements. Academic core facilities demonstrate highest price sensitivity; large pharmaceutical houses extract steepest volume discounts.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai and Busan to Long Beach directly inflates landed costs for temperature-controlled enzyme shipments. Critical inputs draw from concentrated Asian fermentation hubs in China, South Korea, and Singapore, with modified nucleotides and high-fidelity polymerases anchoring import dependency. Single-source vulnerability persists for helium supply extraction from Qatar and Algeria. Distribution runs through authorized distributor networks serving GPO-aggregated academic consortia and direct enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America life science tools function as a stable compounder, with recurring reagent pull-through economics generating predictable cash flows anchored to FDA-regulated diagnostic validation requirements.
For Market Incumbents: Deploy consumable-lock contracts to secure multi-year reagent commitments before CRISPR manufacturing automation commoditizes standard-grade enzymes. Defensive moves include acquiring regional reagent formulators to control buffer formulation IP and expanding Toronto-Montreal service infrastructure to capture Health Canada parallel review advantages. Threat: acoustic dispensing platforms from emerging automation specialists erode liquid handler installed bases.
For New Entrants and Emerging Players: Group purchasing organizations represent the most penetrable channel for specialty reagent introductions. White-space targets include aqueous buffer formulations serving EPA green chemistry mandates and biodegradable consumable materials for hazardous waste reduction. Go-to-market angle: direct contracting with San Francisco Bay Area academic consortia bypassing incumbent distributor markups.
For Investors and Strategic Acquirers: Roll-up economics work for regional reagent formulators because FDA predicate device pathways create sticky validation relationships that resist vendor switching. Long-term viability centers on consumable-recurring revenue models with 5-10 year instrument placement horizons. Acquisition target archetype: mid-scale CRISPR reagent manufacturers with proprietary high-activity enzyme strains. Signal to watch: Health Canada breakthrough device designation velocity as indicator of accelerated North American platform adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Manufacturing Automation | South Korean fermentation capacity lowers per-unit costs for CRISPR enzymes supplied to Boston-Cambridge discovery groups. |
| Health Canada Parallel Review Pathway | Accelerated regulatory clearance in Toronto-Montreal clusters attracts sequencing platform launches ahead of standard FDA timelines. |
| Enterprise Purchasing Agreement Consolidation | CRO volume aggregation compresses vendor margins while locking in multi-year reagent supply commitments. |
| EPA Green Chemistry Compliance | Aqueous buffer formulations reduce hazardous disposal costs for California and Massachusetts clinical laboratories. |
| Bioinformatics Pipeline Integration | Strategic partnerships between instrument makers and computational biology providers address data interpretation bottlenecks. |
Research Approach
Direct dialogue with pharmaceutical procurement directors, CRO laboratory operations managers, FDA regulatory affairs leads, and academic core facility directors grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, Health Canada device license databases, EPA hazardous waste stream reports, and GPO contract disclosure records. Bottom-up reagent volume estimates triangulated against top-down instrument installed-base projections.
Bottom-up modeling segmented demand by product type, end-user archetype, and application workflow, with technology-layer cross-validation. The analytical framework incorporated helium supply volatility scenarios, tariff exposure assumptions, and regulatory pathway timing differentials across the projection horizon. CAGRs derived from instrument replacement cycles and consumable pull-through rates calibrated to pharmaceutical R&D spending patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CRISPR manufacturing automation pace, helium supply disruption frequency, and FDA guidance evolution for next-generation sequencing oncology panels. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Ultracentrifuges Market