
 Biotherapeutics Virus Removal Filters Market | 2026-2036
Biotherapeutics Virus Removal Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Biotherapeutics Virus Removal Filters Market Outlook
Asset-light leasing models for single-use filtration systems is rewriting competitive entry barriers for mid-size biotech firms. Sartorius AG leverages its disposable platform architecture to capture flexible manufacturing demand. Merck Group anchors European supply through membrane production scale in Germany. Danaher Corporation competes via integrated workflow bundling across Pall filtration and Cytiva separation portfolios.
Biotherapeutics virus removal filters are sterilizing-grade membranes, typically 20 nanometer pore-rated, designed to retain retroviruses and parvoviruses while permitting protein passage during downstream bioprocessing. Ultrafiltration Membranes dominate installed base volume due to platform standardization across monoclonal antibody workflows. Virus Filtration Columns represent the fastest-growing product type as gene therapy manufacturers adopt orthogonal clearance strategies. Tangential Flow Filtration occupies the premium margin tier where high-value plasma-derived therapies require validated continuous processing.
FDA viral clearance guidance and EMA's Note for Guidance on Virus Validation Studies mandate demonstrable log reduction values, forcing filter vendors to invest in redundant testing infrastructure. ISO 13485 quality management systems and PDA Technical Report 41 establish harmonized performance benchmarks that accelerate cross-border product registration. Stakeholders must weigh single-use adoption rates against reusable system total cost of ownership as sustainability audits intensify across pharmaceutical supply chains.

Market Dynamics
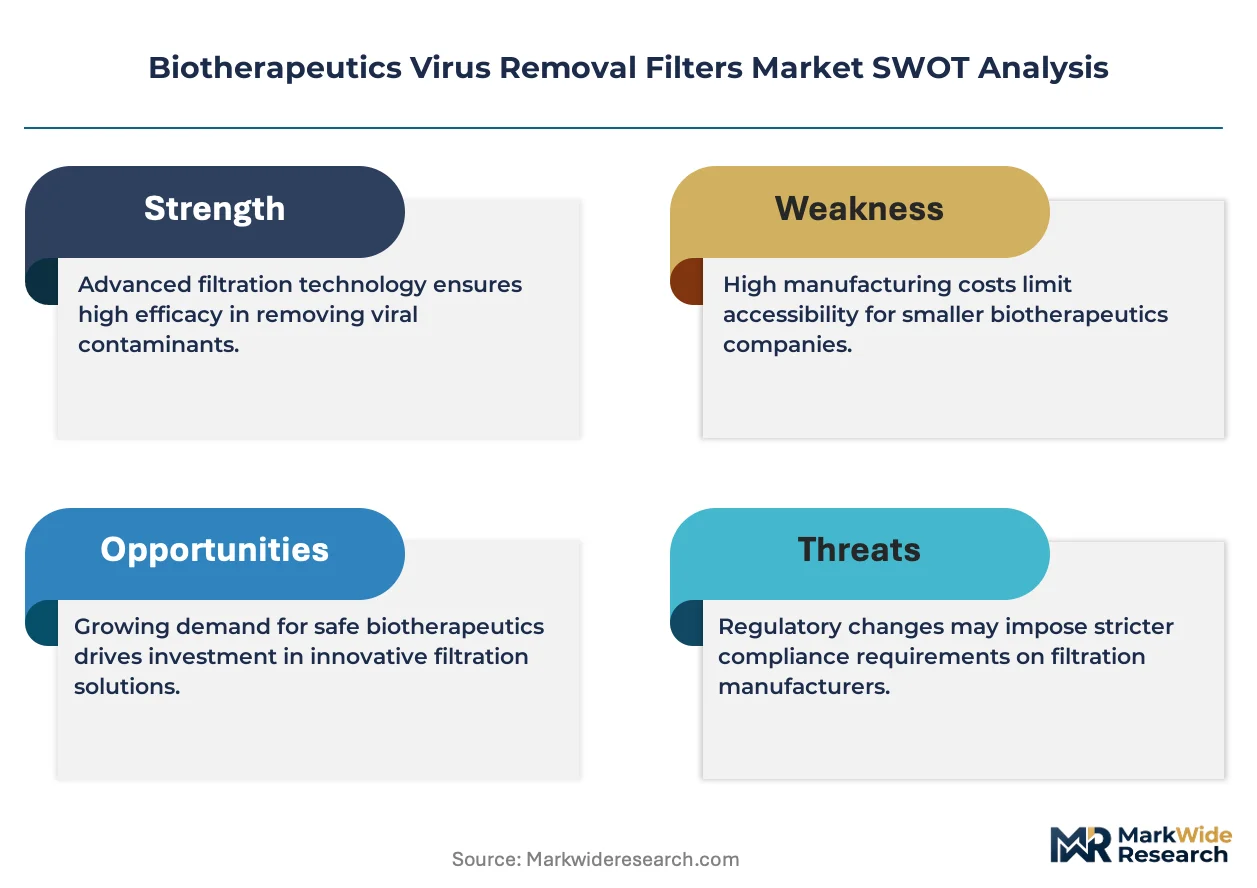
Single-use filtration architectures are compressing capital barriers for biologics manufacturers, forcing incumbent suppliers to reconfigure pricing models around consumable recurring revenue rather than capital equipment sales.
Growth Catalysts
- EMA Note for Guidance on Virus Validation Studies:Tightened log reduction mandates compel filter vendors to expand redundant testing infrastructure, pulling demand for high-performance membranes.
- Monoclonal antibody production clusters:Concentrated biomanufacturing corridors around Boston and San Francisco generate sustained procurement volume for sterilizing-grade filtration.
- Tangential Flow Filtration:Continuous processing adoption for plasma-derived therapies validates premium membrane configurations and expands addressable workflow value.
Market Restraints
- PVDF membrane resin supply:Polyvinylidene fluoride feedstock concentration among Asian chemical producers exposes filter manufacturers to input cost volatility and dual-use export controls.
- Validation timeline compression:FDA viral clearance guidance demands extended qualification studies, stretching working capital cycles for mid-tier biotech firms.
- Reusable stainless-steel systems:Sustainability audit pressures in European pharmaceutical supply chains sustain competitive threat to single-use adoption rates.
Strategic Opportunities
- Gene therapy manufacturing:Viral vector production workflows require orthogonal clearance strategies, opening demand for Virus Filtration Columns in emerging cell therapy facilities.
- India biologics manufacturing:CDSCO regulatory alignment with ICH guidelines positions domestic CMOs for viral clearance filter procurement acceleration.
- Continuous bioprocessing integration:Convergence of perfusion cell culture with inline virus filtration enables real-time release paradigms and reduces downstream hold tank requirements.
Industry Challenges
- Filtration train integration:Legacy chromatography skids require mechanical retrofitting to accommodate new membrane housing geometries, complicating facility upgrade timelines.
- Process analytical technology staffing:Scarce expertise in real-time virus titer monitoring constrains validation throughput for contract manufacturing organizations scaling gene therapy capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotherapeutics Virus Removal Filters Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrafiltration Membranes, Virus Filtration Columns, Depth Filters, Tangential Flow Filtration End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturing Organizations, Research Laboratories Technology: Filtration, Membrane Technology, Adsorption Technology, Chromatography Application: Monoclonal Antibodies, Vaccines, Gene Therapies, Blood Products |
| Companies Covered | Merck Group, Sartorius AG, Pall Corporation, Lonza Group, Asahi Kasei Corporation, Thermo Fisher Scientific, GE Healthcare, Bio-Rad Laboratories, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotherapeutics Virus Removal Filters Market Strategic Shifts
Membrane chemistry advances and regulatory data integrity mandates are compressing product development cycles while elevating performance benchmarking transparency across supplier ecosystems.
Multilayer composite membranes integrating charged surface modifications with size exclusion are rendering obsolete conventional 20-nanometer rated single-layer PVDF configurations. Gene therapy manufacturers adopting these architectures achieve higher parvovirus log reduction values without flux degradation. The technology is rendering obsolete legacy qualification protocols that relied on surrogate virus panels rather than actual product-specific spike studies.
FDA's updated guidance on viral clearance validation for biotechnology products now mandates bracketing studies across worst-case protein concentrations. This forces filter suppliers to maintain expanded virus stock libraries and redundant QA personnel. Contract manufacturing organizations in the United States are responding by consolidating supplier relationships to reduce qualification burden duplication.
Leasing arrangements for single-use filtration hardware are displacing traditional capital purchase models among emerging biotech firms. Equipment financiers now bundle membrane consumables with hardware access fees, capturing lifetime value previously retained by filter manufacturers. This restructuring is most visible in Massachusetts and California, where venture-backed cell therapy startups prioritize cash flow preservation over asset ownership.
Biotherapeutics Virus Removal Filters Market Segmentation
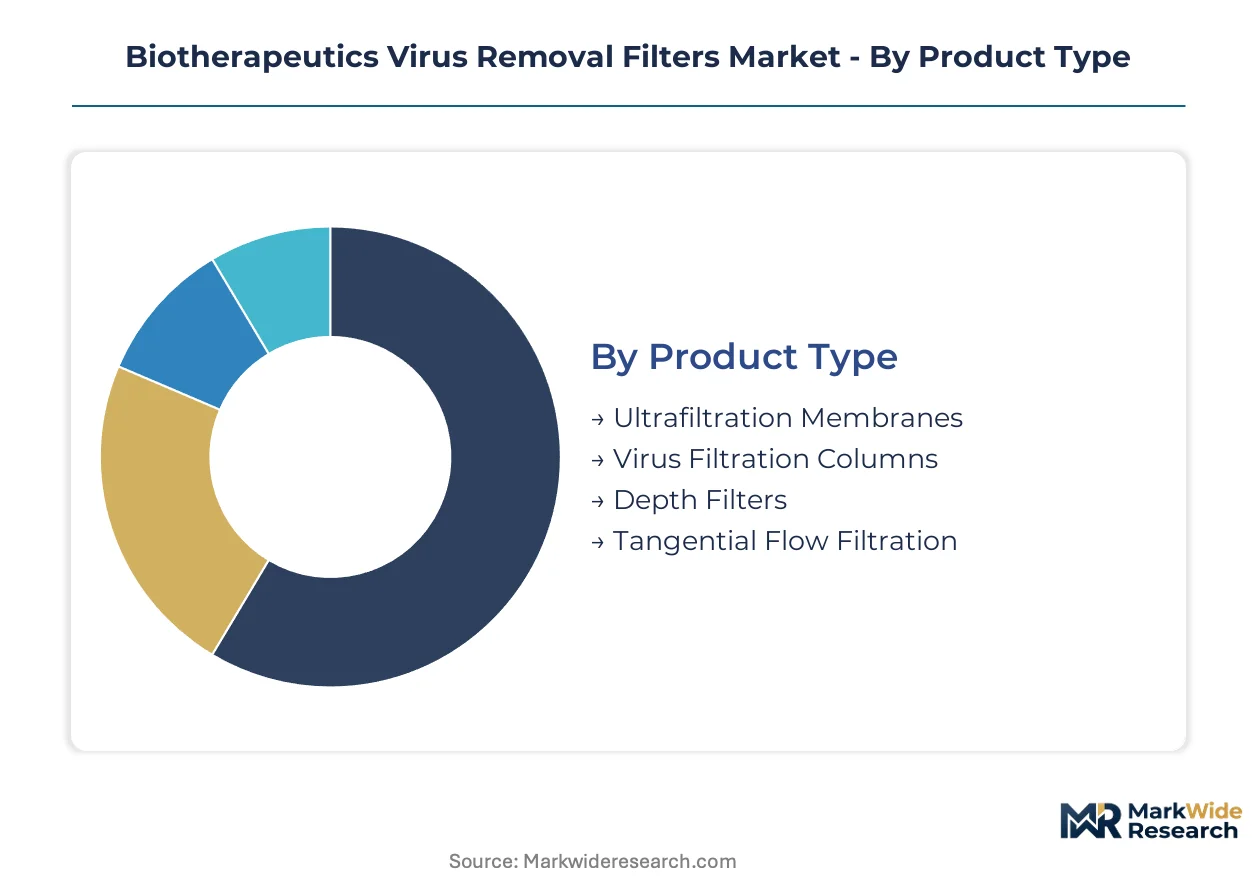
Virus removal filter procurement varies dramatically by workflow stage and therapeutic modality, with cycle times ranging from standardized platform purchases to multi-year custom validation programs. Understanding segment turnover velocity enables suppliers to align inventory and technical service deployment with actual buying rhythms.
Product Type:
Ultrafiltration Membranes turn over fastest through platform standardization, while Tangential Flow Filtration systems cycle slowest due to extended qualification timelines for plasma-derived therapies.
- Ultrafiltration Membranes:20-nanometer pore-rated PVDF or PES sterilizing-grade membranes dominate monoclonal antibody downstream processing as the default viral clearance step. Procurement concentrates among Boston and San Francisco corridor manufacturers running fed-batch platforms, with FDA viral clearance guidance driving predictable replacement schedules.
- Virus Filtration Columns:Pre-packed, single-use column formats enable orthogonal clearance strategies in gene therapy viral vector production. Demand clusters at emerging cell therapy facilities in Massachusetts and California where CDMOs prioritize rapid facility reconfiguration over permanent infrastructure.
- Depth Filters:Cellulose-based prefilters protect downstream membranes from fouling in high-titer antibody harvests.
- Tangential Flow Filtration:Continuous processing configurations for plasma-derived therapies require validated cassette geometries with extended performance documentation cycles.
Ultrafiltration Membranes anchors the volume base while Virus Filtration Columns gains share at the steepest rate.
End User:
Procurement sophistication stratifies sharply across customer types, with Contract Manufacturing Organizations demanding the most intensive technical support and Research Laboratories operating on expedited evaluation timelines.
- Pharmaceutical Companies:Large-scale biologics manufacturers maintain captive filtration qualification labs and multi-year supply agreements. Investment concentrates at legacy monoclonal antibody sites where FDA compliance history reduces regulatory friction for process changes.
- Contract Manufacturing Organizations:CDMOs face compressed validation timelines as gene therapy clients demand rapid tech transfer. CDSCO-aligned Indian CMOs are expanding viral clearance capacity to capture biologics outsourcing from Western sponsors.
- Biotech Firms:Venture-backed developers prioritize single-use leasing models to preserve cash flow.
- Research Laboratories:Academic and government labs drive early-stage membrane screening with small-volume procurement.
Pharmaceutical Companies dominates absolute spend while Contract Manufacturing Organizations expands most quickly as biologics pipelines deepen.
Technology:
Technology selection tracks directly to log reduction validation requirements, with Membrane Technology commanding premium pricing for size-exclusion certainty and Adsorption Technology recovering ground through charged surface innovations.
- Filtration:Size-exclusion remains the primary viral clearance mechanism, with 20-nanometer ratings standardized across monoclonal antibody workflows. EMA Note for Guidance on Virus Validation Studies mandates demonstrable performance across worst-case protein concentrations, forcing redundant testing infrastructure investment.
- Membrane Technology:Multilayer composite configurations integrating charged surface modifications with size exclusion achieve higher parvovirus log reduction values. Gene therapy manufacturers in California adopt these architectures for viral vector clearance without flux degradation.
- Adsorption Technology:Charged depth filters and membrane adsorbers provide orthogonal clearance for small non-enveloped viruses.
- Chromatography:Resin-based viral clearance steps complement filtration in legacy antibody purification trains.
Membrane Technology commands the margin premium while Adsorption Technology climbs the fastest as multilayer composites displace single-layer configurations.
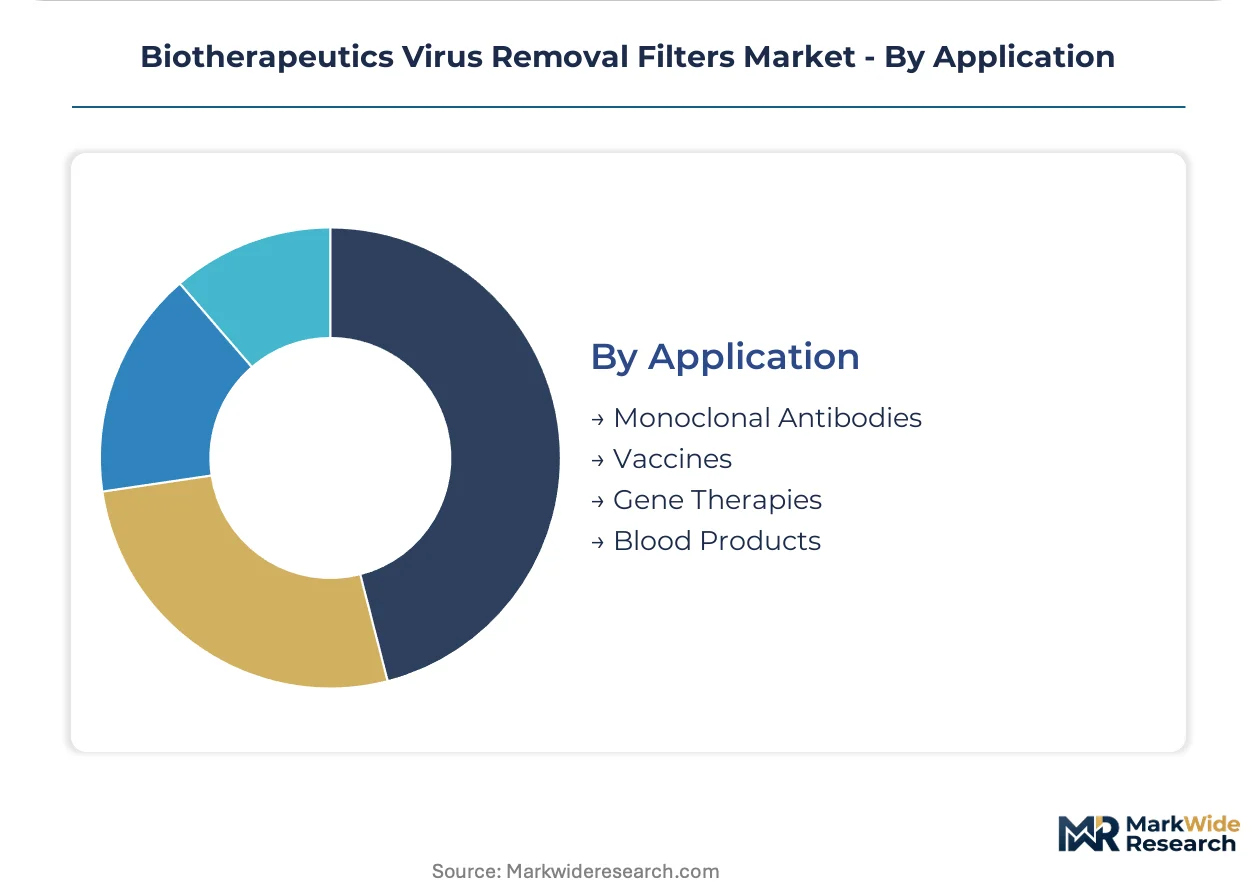
Application:
Application demand correlates with therapeutic complexity and regulatory scrutiny intensity, with Gene Therapies requiring the most extensive validation documentation and Vaccines operating on accelerated pandemic-response procurement.
- Monoclonal Antibodies:Mature therapeutic category with standardized platform filtration across fed-batch and perfusion processes. Production gravity concentrates in United States coastal corridors where established CDMO networks reduce supplier qualification burden duplication.
- Gene Therapies:Viral vector manufacturing demands orthogonal clearance strategies combining filtration with chromatography. Massachusetts and California cell therapy startups drive demand for pre-validated single-use formats that compress facility buildout timelines.
- Vaccines:Pandemic preparedness programs sustain surge capacity requirements for egg-based and cell culture platforms.
- Blood Products:Plasma-derived therapies require continuous processing validation for albumin and immunoglobulin purification.
Monoclonal Antibodies sustains the installed base while Gene Therapies demonstrates the steepest expansion trajectory as viral vector manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in virus removal filters tilt toward manufacturing economies with membrane resin production and biologics consumption centers with deep CDMO networks. The United States runs the largest procurement deficit in sterilizing-grade membranes, sourcing PVDF feedstock from Asian chemical producers while concentrating downstream filter demand in coastal biotech corridors.
United States
FDA viral clearance guidance mandates demonstrable log reduction values across worst-case protein concentrations, compelling domestic biologics manufacturers to maintain redundant filter qualification labs. The Boston and San Francisco biotech corridors generate sustained procurement volume for 20-nanometer rated membranes as monoclonal antibody production clusters deepen. Venture-backed cell therapy startups in Massachusetts and California increasingly adopt single-use leasing models to preserve cash flow during facility buildout.
Germany
EMA's Note for Guidance on Virus Validation Studies tightens validation requirements for filter performance, pulling demand for high-performance membranes from German biologics manufacturers. Merck Group anchors European supply through domestic membrane production scale, reducing import dependency for sterilizing-grade configurations. The Rhine-Main and Upper Bavaria regions concentrate CDMO capacity serving Western European gene therapy sponsors seeking orthogonal clearance strategies.
India
CDSCO regulatory alignment with ICH guidelines positions domestic CMOs for accelerated viral clearance filter procurement as Western sponsors outsource biologics manufacturing. Contract manufacturing organizations in Hyderabad and Bengaluru expand viral clearance capacity to capture gene therapy and monoclonal antibody production contracts. Indian filter distributors report compressed validation timelines as international clients demand rapid tech transfer for pipeline assets.
Japan
PMDA harmonization with FDA viral clearance standards drives adoption of multilayer composite membranes achieving higher parvovirus log reduction values without flux degradation. Domestic biologics manufacturers in the Kanto and Kansai regions upgrade filtration trains to accommodate gene therapy viral vector production workflows. Asahi Kasei Corporation leverages domestic chemical processing expertise to supply charged surface modifications for orthogonal clearance applications.
Switzerland
Swissmedic enforcement of ISO 13485 quality management systems accelerates cross-border product registration for filter vendors serving the Basel and Zurich biopharma clusters. The country's concentration of large-cap biologics innovators sustains demand for validated continuous processing configurations in plasma-derived therapy manufacturing. Swiss CDMOs specialize in high-value filtration qualification services for sponsors seeking dual FDA-EMA regulatory submissions.
Biotherapeutics Virus Removal Filters Market Competitive Environment
On the supply side, the industry is consolidating around integrated life sciences conglomerates with captive membrane manufacturing and standalone filtration specialists with platform-specific expertise. Three strategic archetypes dominate: diversified laboratory and process technology conglomerates with workflow bundling capabilities, pure-play bioprocessing equipment vendors with disposable platform architectures, and diversified chemical and materials companies with upstream polymer science capabilities. Competitive moves concentrate on strategic partnerships between filter manufacturers and CDMOs to co-develop qualification protocols, alongside capacity expansion in multilayer composite membrane production to serve gene therapy viral vector demand.
Within the diversified conglomerate tier, Danaher Corporation and Thermo Fisher Scientific exemplify integrated workflow bundling strategies spanning filtration, separation, and analytical technologies. Merck Group and Sartorius AG occupy positions at opposite ends of the vertical integration spectrum, with the former controlling upstream membrane resin production and the latter specializing in disposable platform architectures for flexible manufacturing demand. Lonza Group represents the CDMO-forward archetype, leveraging captive filtration capacity to compress client validation timelines.
| Leading Market Players |
|---|
| Merck Group |
| Sartorius AG |
| Pall Corporation |
| Lonza Group |
| Asahi Kasei Corporation |
| Thermo Fisher Scientific |
| GE Healthcare |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
Hyderabad's expanding viral clearance capacity pulls membrane procurement decisions toward Indian CMOs, compressing pricing power for European suppliers serving Western sponsors. Cost compression in sterilizing-grade configurations intensifies as CDSCO-aligned facilities demand rapid tech transfer timelines.
Pricing Analysis
Pharmaceutical companies anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on FDA validation documentation and ISO 13485 certification completeness. Price differentiation hinges on membrane chemistry sophistication and after-sales technical support bundling. Margins are tightening due to single-use leasing model proliferation among Massachusetts and California cell therapy startups. Emerging biotech firms exhibit highest price sensitivity, while plasma-derived therapy manufacturers demonstrate lowest sensitivity given continuous processing validation requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for PVDF membrane resin procurement. Manufacturing concentrates in Germany, Japan, and the United States for final filter assembly, while polyvinylidene fluoride feedstock draws from Asian chemical producers. Dual-use export controls on fluoropolymer precursors create single-source vulnerability for multilayer composite membrane production. Distribution runs through authorized distributor networks serving Boston and San Francisco biotech corridors, with direct procurement relationships reserved for top-tier pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biotherapeutics virus removal filters market sits in early-cycle recovery, with gene therapy manufacturing expansion providing demand foundation across the analysis window.
For Market Incumbents: Insulate qualification protocol relationships from emerging membrane chemistry specialists by deepening backward integration into charged surface modification production. Expand redundant testing infrastructure in Germany to preempt EMA validation timeline compression. Prioritize certification investment in ISO 13485 quality management systems to accelerate cross-border product registration against Asian competitors. For New Entrants and Emerging Players: Indian biologics manufacturing offers the most penetrable geography, with CDSCO regulatory alignment creating procurement acceleration for viral clearance filter vendors. Target gene therapy CDMOs in Hyderabad and Bengaluru seeking orthogonal clearance strategies for viral vector production. Pursue co-development partnerships with Western sponsors outsourcing biologics manufacturing to compress validation burden duplication. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane chemistry specialists with multilayer composite capabilities displacing single-layer PVDF configurations. Long-term viability centers on gene therapy viral vector demand scaling across the projection horizon. Acquisition targets should demonstrate captive charged surface modification expertise and established FDA qualification history. Watch PMDA harmonization progress with FDA viral clearance standards as inflection indicator for Japanese market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Composite Membrane Development | Gene therapy manufacturers in California achieve higher parvovirus log reduction without flux degradation. |
| Redundant Testing Infrastructure Expansion | EMA Note for Guidance on Virus Validation Studies mandates demonstrable performance across worst-case protein concentrations. |
| Single-Use Leasing Model Proliferation | Venture-backed cell therapy startups in Massachusetts prioritize cash flow preservation over asset ownership. |
| CDSCO Regulatory Alignment Investment | Indian CMOs in Hyderabad capture biologics outsourcing from Western sponsors seeking cost compression. |
| Continuous Processing Validation Programs | Plasma-derived therapy manufacturers require validated cassette geometries for albumin and immunoglobulin purification. |
Study Parameters
The analysis maps ultrafiltration membranes, virus filtration columns, depth filters, and tangential flow filtration configurations, each validated through membrane R&D directors, CDMO procurement leads, regulatory affairs specialists, and viral clearance validation scientists. Primary interviews with bioprocessing engineers and downstream technology heads combined with secondary triangulation against FDA guidance documents, EMA submissions, ISO 13485 audit records, and PDA Technical Report 41 standards. Bottom-up segment sizing and top-down market reconciliation ensured cross-validation across product type, end user, technology, and application dimensions.
Assumptions held fixed include EMA and FDA viral clearance guidance stability, PVDF resin supply continuity, and gene therapy manufacturing capacity expansion rates across the projection horizon. The analytical framework modeled membrane technology adoption curves, adsorption technology recovery trajectories, monoclonal antibody production cluster concentration, and gene therapy viral vector scaling patterns. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution, with inputs including CDSCO regulatory alignment timelines and PMDA harmonization progress.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by diversified chemical conglomerates would shift outcomes. Material shifts in dual-use export controls on fluoropolymer precursors, EMA validation timeline compression severity, or gene therapy clinical trial failure rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Cryopreservation Freezer Market