
 Global Competent Cells Market | 2026-2036
Global Competent Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Global Competent Cells Market Foresight
CRISPR-Cas9 integration into standard molecular biology workflows is rewriting how competent cells are designed, screened, and manufactured for precision editing applications. Thermo Fisher Scientific leverages its broad reagent portfolio and distribution network to sustain leadership across both research and commercial production segments. Merck KGaA anchors its position through deep backward integration into raw plasmid and enzyme supply chains. New England Biolabs specializes in high-efficiency strains engineered for complex DNA assembly protocols, differentiating its catalog from commodity alternatives.
Competent cells are bacterial strains rendered permeable to foreign DNA through chemical treatment, electroporation, or genetic modification, typically achieving transformation efficiencies between 10^8 and 10^10 colony-forming units per microgram of plasmid DNA for cloning and protein production applications. Chemically competent cells occupy the largest volume share due to their stability in frozen vial formats and compatibility with routine subcloning workflows, while electroporated competent cells command premium positioning for large-insert and CRISPR editing applications where efficiency thresholds exceed standard chemical protocols. Synthetic biology applications are expanding fastest among end-user segments as pharmaceutical developers and agricultural biotech firms adopt modular DNA assembly platforms requiring specialized competent cell strains with reduced recombination backgrounds.
The US FDA and the European Medicines Agency enforce Good Manufacturing Practice standards that constrain which competent cell strains qualify for plasmid DNA used in clinical gene therapies, effectively filtering market access toward suppliers with documented quality systems. China's National Medical Products Administration and Japan's Ministry of Economy, Trade and Industry are aligning their biologics reagent frameworks with OECD principles on genetically modified organism containment, adding compliance layers for cross-border shipments. Stakeholders must monitor how emerging gene therapy approvals reshape demand specifications for clinical-grade competent cells versus research-grade alternatives.
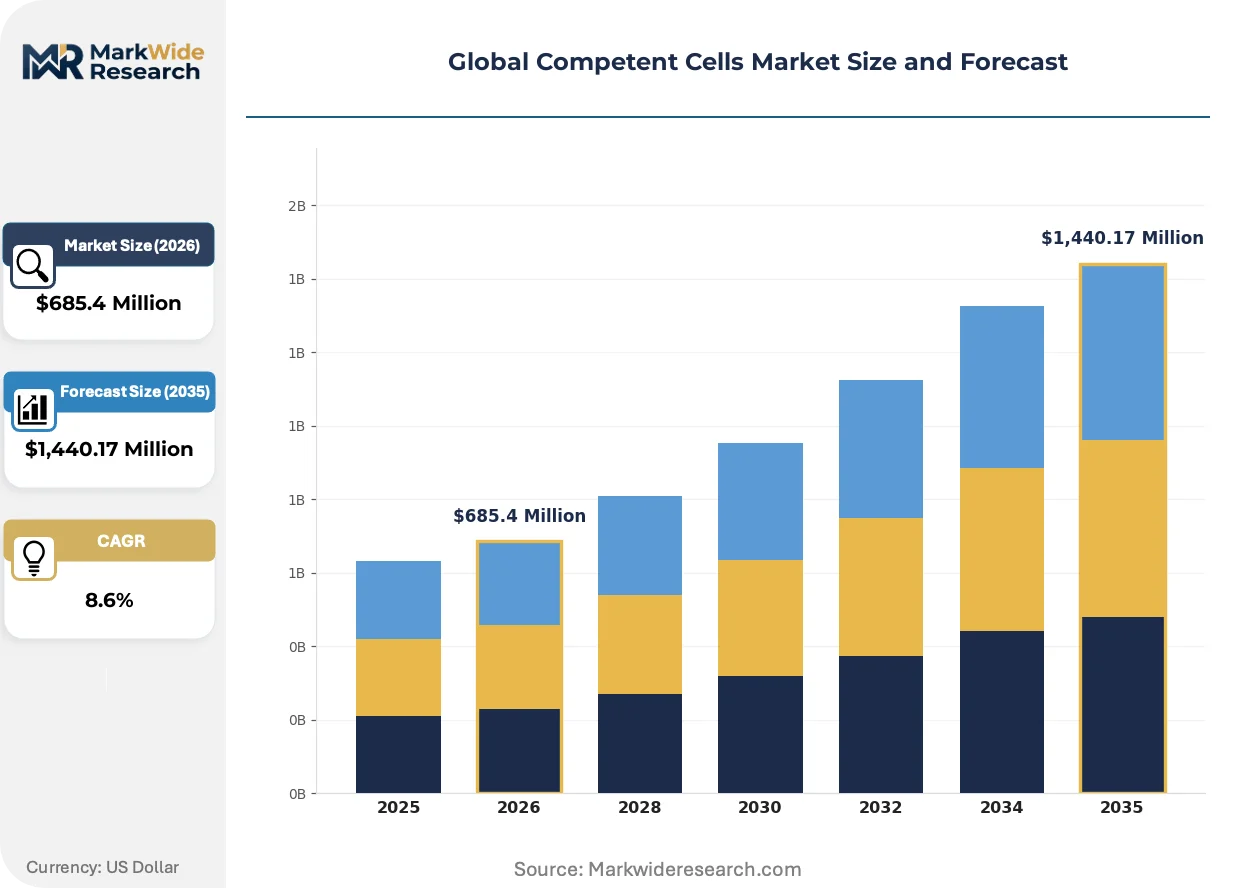
Market Dynamics
CRISPR-Cas9 workflows are compressing transformation efficiency thresholds, forcing manufacturers to engineer specialized strains that achieve 10^10 CFU/μg plasmid DNA for precision editing applications while maintaining GMP documentation for clinical-grade supply.
Growth Catalysts
- Synthetic biology platforms:Pharmaceutical developers and agricultural biotech firms are adopting modular DNA assembly systems requiring reduced-recombination competent cell backgrounds.
- FDA gene therapy guidance:Tightening quality benchmarks for cell-derived reagents are filtering procurement toward suppliers with documented quality management systems.
- China NMPA alignment:Biologics reagent frameworks harmonizing with OECD containment principles are standardizing cross-border shipment protocols for genetically modified organisms.
Market Restraints
- Plasmid DNA cost volatility:Raw nucleic acid feedstock prices fluctuate with fermentation capacity constraints and pharmaceutical-grade purification demand.
- German supply concentration:Merck KGaA's backward integration into enzyme and plasmid supply chains creates dependency risk for non-integrated competitors.
- Chemical protocol efficiency ceiling:Standard calcium chloride heat-shock methods plateau below electroporation thresholds needed for large-insert cloning.
Strategic Opportunities
- India CDSCO pathway expansion:Emerging biopharma clusters in Hyderabad and Bangalore are building CRISPR infrastructure without entrenched supplier relationships.
- Cell-free protein synthesis convergence:Coupling high-efficiency competent cells with in vitro transcription-translation systems enables rapid prototyping workflows.
- Direct-to-lab distribution:Cold-chain logistics platforms are bypassing traditional distributor markups for frozen aliquot shipments to academic core facilities.
Industry Challenges
- Strain engineering talent scarcity:Competent cell optimization requires rare expertise in bacterial genetics, fermentation science, and regulatory documentation simultaneously.
- GMP certification timelines:FDA and EMA facility audits for clinical-grade competent cell production extend 18-24 months, delaying market entry for new entrants.
- Legacy inventory incompatibility:Research-grade strain collections lack traceability documentation required for gene therapy manufacturing transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Competent Cells Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,440.17 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemically Competent Cells, Electroporated Competent Cells, Physically Treated Cells, Genetically Modified Cells Application: Gene Cloning, Protein Expression, Plasmid Isolation, CRISPR Editing, Synthetic Biology End User: Biotechnology Firms, Research Institutions, Pharmaceutical Developers, Agricultural Biotech, Contract Research Organizations Delivery Format: Frozen Vials, Lyophilized Powder, Ready-to-Use Plates, Bulk Liquids |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, New England Biolabs, Agilent Technologies, Takara Bio, Promega Corporation, QIAGEN, GenScript, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Competent Cells Market Shifts & Advancements
Competent cell engineering is bifurcating into two tracks: commodity strains optimized for cost-per-transformation in high-throughput screening, and precision strains engineered for CRISPR editing fidelity where efficiency thresholds dictate protocol selection.
Electroporation-competent cells with engineered cell wall permeability are rendering obsolete chemical heat-shock methods for large-insert and multiplexed editing applications. Gene therapy developers at contract manufacturing organizations are specifying electroporation protocols for clinical-grade plasmid production, compressing demand for standard chemically competent alternatives in regulated workflows.
EMA's evolving Good Manufacturing Practice standards for starting materials are constraining which bacterial strains qualify for plasmid DNA used in advanced therapy medicinal products. Suppliers must now document master cell bank provenance, genetic stability, and absence of adventitious agents across extended production runs. European gene therapy developers are consolidating procurement toward vendors with pre-qualified regulatory packages.
Core facility managers at US research universities are consolidating vendor relationships around single-source contracts with performance-based pricing tied to transformation efficiency guarantees. Thermo Fisher Scientific and New England Biolabs are competing on technical support integration and lot-to-lot consistency metrics rather than catalog breadth alone. This concentration is most visible in Boston and San Francisco biotech corridors where shared resource laboratories process thousands of monthly transformations.
Global Competent Cells Market Segmentation
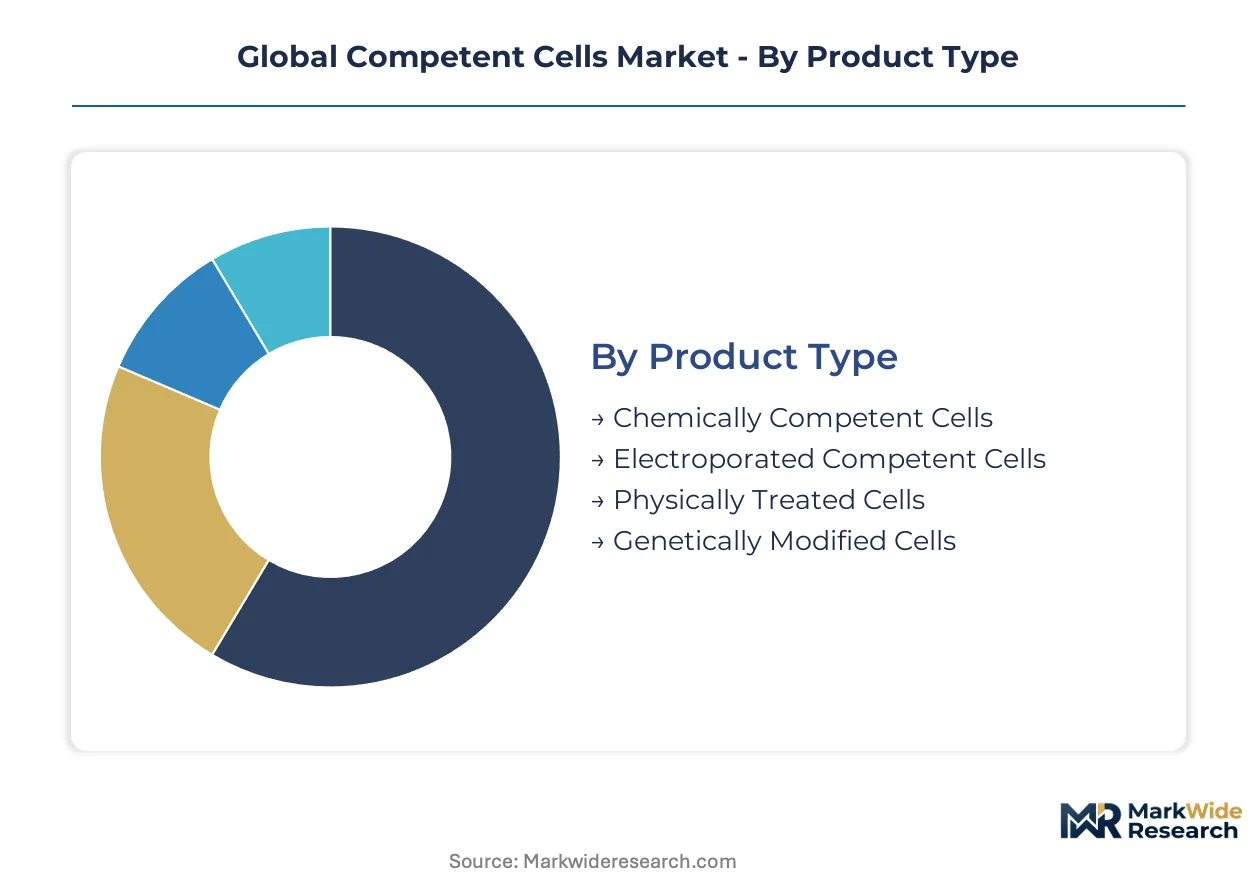
Segmentation in the competent cells market reveals how technical specifications, regulatory requirements, and workflow integration shape procurement decisions across research and clinical environments. Understanding these divides exposes where suppliers can defend margin through specialization versus where scale economies dominate.
Product Type:
Cost tier stratification separates commodity chemical protocols from premium electroporation systems engineered for precision applications.
- Chemically Competent Cells:Bacterial strains rendered permeable through calcium chloride or rubidium chloride treatment achieve transformation efficiencies of 10^8 to 10^9 CFU/μg plasmid DNA. Research institutions in the United States and Germany purchase these in frozen vial formats for routine subcloning where cost-per-transformation governs selection.
- Electroporated Competent Cells:Engineered cell wall permeability enables efficiency thresholds exceeding 10^10 CFU/μg, mandatory for large-insert cloning and multiplexed CRISPR editing. Gene therapy developers at contract manufacturing organizations specify these for clinical-grade plasmid production.
- Physically Treated Cells:Mechanical or thermal permeabilization methods serve niche applications in agricultural biotech field trials.
- Genetically Modified Cells:Reduced-recombination backgrounds with engineered endonuclease deficiencies support complex DNA assembly in synthetic biology platforms.
Chemically competent cells command the established base. The steepest expansion runs through electroporated competent cells.
Application:
Application focus determines whether customers prioritize throughput volume, editing precision, or regulatory documentation depth.
- Gene Cloning:Standard molecular biology workflows requiring stable transformation of plasmid vectors into E. coli hosts. Academic core facilities in Boston and San Francisco process thousands of monthly transformations with efficiency guarantees as the primary selection criterion.
- CRISPR Editing:Precision genome engineering demands specialized strains with reduced recombination backgrounds and high electroporation efficiency. Pharmaceutical developers integrate these into automated screening platforms for therapeutic target validation.
- Protein Expression:Codon-optimized strains with rare tRNA supplementation enable heterologous protein production for structural biology.
- Plasmid Isolation:High-copy number vectors require endA-negative strains to prevent nuclease degradation during purification.
- Synthetic Biology:Modular DNA assembly platforms exploit recombination-deficient backgrounds for multi-part construct building.
Gene cloning retains the volume base. CRISPR editing applications are climbing the fastest as therapeutic pipelines mature.
End User:
Customer type dictates pricing tolerance, technical support requirements, and documentation sophistication.
- Biotechnology Firms:Mid-stage companies prioritize lot-to-lot consistency and rapid technical support integration over catalog breadth. Shared resource laboratories in Cambridge and South San Francisco consolidate around single-source contracts with performance-based pricing.
- Pharmaceutical Developers:Large molecule and gene therapy divisions require GMP-documented strains with master cell bank provenance and genetic stability data across extended production runs.
- Research Institutions:University core facilities balance transformation efficiency guarantees against per-reaction cost constraints.
- Agricultural Biotech:Field trial regulations in Brazil and Argentina drive demand for containment-compliant strain documentation.
- Contract Research Organizations:High-throughput screening services value ready-to-use formats that minimize hands-on time.
Research institutions anchor volume demand. Pharmaceutical developers represent the fastest-growing customer tier as gene therapy manufacturing scales.
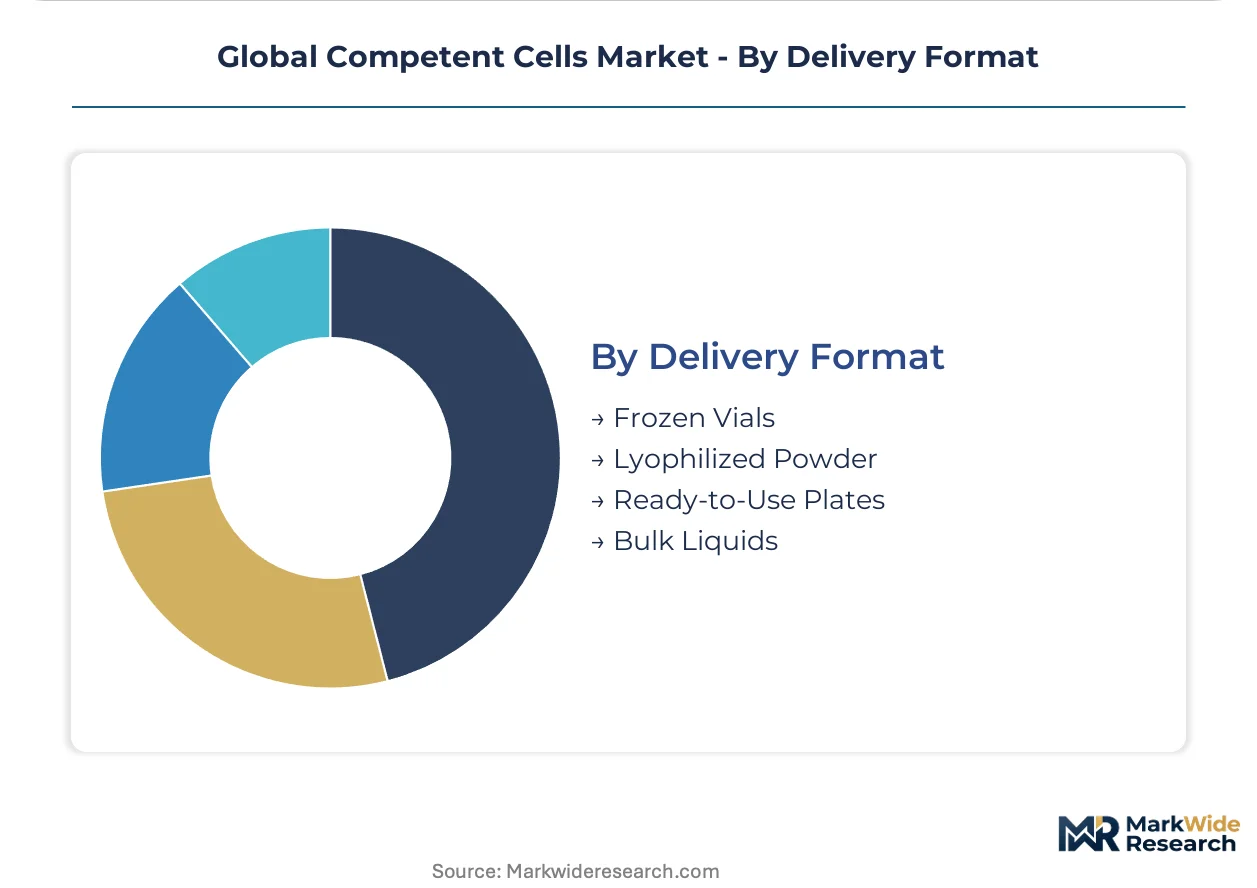
Delivery Format:
Supply chain configuration shapes margin capture through cold-chain logistics versus shelf-stable alternatives.
- Frozen Vials:Standard -80°C storage format dominates high-efficiency electroporation cells where membrane integrity degrades at ambient temperatures. Cold-chain logistics platforms now bypass traditional distributor markups for direct-to-lab shipments.
- Lyophilized Powder:Ambient-stable formats eliminate frozen shipping costs for remote field stations and developing economy research sites.
- Ready-to-Use Plates:Pre-aliquoted 96-well formats integrate with automated liquid handling in pharmaceutical screening operations.
- Bulk Liquids:Large-volume fermentation harvests serve contract manufacturers with in-house aliquoting and quality control capabilities.
Frozen vials command the established installed base. Lyophilized powder formats are gaining share fastest in distributed research networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers export electroporation-competent cells to gene therapy developers in the United States and China, establishing the primary trade corridor for clinical-grade reagents.
United States
FDA gene therapy manufacturing guidance tightens quality benchmarks for plasmid DNA starting materials. Boston and San Francisco biotech corridors host shared resource laboratories processing thousands of monthly transformations. Academic core facilities consolidate procurement around single-source contracts with efficiency guarantees.
Germany
EMA Good Manufacturing Practice standards constrain which bacterial strains qualify for advanced therapy medicinal products. Merck KGaA anchors supply chains through backward integration into enzyme and plasmid feedstocks. The Rhine-Main cluster concentrates gene therapy contract manufacturing requiring documented master cell bank provenance.
China
NMPA biologics reagent frameworks harmonize with OECD genetically modified organism containment principles. Synthetic biology startups in Shenzhen and Shanghai adopt modular DNA assembly platforms. Government funding for precision medicine infrastructure accelerates CRISPR workflow adoption.
Japan
METI alignment with OECD biotechnology containment standards standardizes cross-border shipment protocols. Pharmaceutical developers in Kanto and Kansai regions specify electroporation protocols for clinical-grade plasmid production. Rare tRNA-supplemented strains enable structural biology protein expression contracts.
India
CDSCO pathway expansion for gene therapy manufacturing attracts contract development investments. Hyderabad and Bangalore biopharma clusters build CRISPR infrastructure without entrenched supplier relationships. Lyophilized powder formats gain share in distributed research networks lacking cold-chain logistics.
Global Competent Cells Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: diversified life science conglomerates with global distribution networks, specialized molecular biology reagent houses with strain engineering expertise, and regional suppliers serving price-sensitive academic markets. Strategic archetypes include full-portfolio integrators, precision-strain specialists, and emerging-market cost competitors. Dominant competitive moves encompass regulatory pre-qualification investments for GMP documentation and direct-to-lab distribution partnerships that bypass traditional distributor markups.
Among diversified conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify full-portfolio positioning through extensive reagent catalogs and distribution infrastructure. New England Biolabs occupies a specialist tier, representing precision-strain engineering capabilities for complex DNA assembly protocols. These three entities anchor the competitive structure, with regional players in China and India challenging on cost for research-grade segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| New England Biolabs |
| Agilent Technologies |
| Takara Bio |
| Promega Corporation |
| QIAGEN |
| GenScript |
| Bio-Rad Laboratories |
| Others |
Supply & Pricing Matrix
Rhine-Main to Boston air freight corridors carry electroporation-competent cells under controlled cold-chain protocols, with per-kilogram logistics costs shaping how German suppliers price clinical-grade strains against research-grade alternatives in the United States market. This freight dynamic concentrates pricing power with backward-integrated manufacturers who absorb temperature-controlled shipping costs into bundled contracts, while forcing smaller competitors to either absorb margin erosion or cede high-value gene therapy accounts.
Pricing Analysis
Electroporation-competent cells command three to fivefold premiums over chemically competent alternatives, with next-generation CRISPR-optimized strains entering at price points that displace prior-generation large-insert cloning products. Pricing stratifies across GMP-certified clinical tiers, ISO-documented research tiers, and economy-grade bulk formats for high-throughput screening. Cost compression in research-grade chemical protocols intensifies as Chinese suppliers expand lyophilized powder alternatives that eliminate frozen shipping overhead. Academic core facilities demonstrate highest price sensitivity, while gene therapy contract manufacturers prioritize lot-to-lot consistency guarantees over per-unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning as NMPA containment documentation requirements add compliance layers to cross-border enzyme and plasmid feedstock movements. Manufacturing concentrates in Germany, the United States, and Japan, with raw nucleic acid fermentation drawing from captive bioreactor capacity and pharmaceutical-grade purification resin supplies. Single-source vulnerability runs through Merck KGaA's integrated enzyme-plasmid supply chain, which anchors European production. Distribution runs through direct-to-lab cold-chain platforms that bypass traditional distributor markups for academic core facilities in Boston and San Francisco.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR therapeutic pipelines are compressing transformation efficiency thresholds and rewriting procurement specifications for clinical-grade competent cells, creating a high-growth disruption window where regulatory pre-qualification investments separate winners from commodity suppliers.
For Market Incumbents: Insulate GMP-certified strain portfolios by accelerating master cell bank documentation investments ahead of FDA gene therapy manufacturing guidance tightening. Deepen backward integration into plasmid feedstock fermentation to neutralize raw nucleic acid cost volatility that threatens research-grade margin structures. Lock in multi-year single-source contracts with Boston and San Francisco shared resource laboratories before Chinese suppliers achieve cold-chain reliability parity. For New Entrants and Emerging Players: Build out lyophilized powder manufacturing capabilities targeting India's distributed research networks in Hyderabad and Bangalore, where cold-chain infrastructure gaps create penetrable white space. Establish technical support partnerships with CRISPR infrastructure builders in Shenzhen and Shanghai before entrenched supplier relationships solidify. Pursue direct-to-lab distribution alliances with academic core facilities seeking to bypass distributor markups on frozen aliquot shipments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core reagent portfolios amid R&D restructuring. Long-term viability hinges on exposure to clinical-grade gene therapy manufacturing rather than research-grade commoditization. Watch for FDA advanced therapy medicinal product approvals as the inflection signal that reshapes demand specifications and consolidates procurement toward pre-qualified regulatory packages.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | FDA facility audits for clinical-grade competent cell production extend 18-24 months, creating defensive moats. |
| Direct-to-Lab Distribution Partnership | Cold-chain logistics platforms bypass traditional distributor markups for frozen aliquot shipments to academic core facilities. |
| Backward Integration into Plasmid Supply | Captive fermentation capacity neutralizes raw nucleic acid feedstock price volatility from pharmaceutical-grade purification demand. |
| Lyophilized Format Development | Ambient-stable powder eliminates frozen shipping costs for distributed research networks in developing economy clusters. |
| CRISPR-Optimized Strain Engineering | Specialized reduced-recombination backgrounds achieve 10^10 CFU/μg thresholds mandatory for multiplexed editing workflows. |
Research Methodology
Initial hypotheses were tested against primary input from gene therapy manufacturing executives, academic core facility managers, regulatory affairs leads at reagent suppliers, and fermentation science directors, then refined through secondary validation against FDA guidance documents, EMA Good Manufacturing Practice standards, NMPA biologics reagent frameworks, and OECD genetically modified organism containment principles. Bottom-up demand modeling from end-user transformation volume estimates was triangulated against top-down supply capacity assessments from identified fermentation facilities.
Demand-supply balance dynamics across the analysis window were modeled through segmented projections by product type, application workflow, end-user category, and delivery format, with CAGRs derived from elasticity-adjusted growth rate synthesis. Forecast inputs incorporated CRISPR therapeutic pipeline maturation timelines, synthetic biology platform adoption curves, and regulatory harmonization progress across FDA, EMA, and NMPA jurisdictions.
Practitioners should monitor FDA gene therapy manufacturing guidance revisions, NMPA OECD alignment implementation schedules, and raw nucleic acid fermentation capacity expansions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market