
 Automated Cell Culture Equipment Market | 2026-2036
Automated Cell Culture Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Cell Culture Equipment Market Analysis
Buyer concentration among contract development and manufacturing organizations is recalibrating procurement patterns for automated cell culture systems. Thermo Fisher Scientific leverages its integrated bioproduction portfolio to serve multi-site CDMO networks with standardized automation architectures. Danaher Corporation anchors its position through subsidiary-level specialization in cell analysis and liquid handling workflows. Sartorius AG competes on single-use bioreactor integration with upstream automation platforms.
Automated cell culture equipment comprises electromechanical systems that maintain controlled environmental parameters for in vitro cell propagation, typically operating within temperature ranges of 37°C, 5% CO₂, and 95% humidity with closed-loop media exchange. These systems serve biopharmaceutical manufacturing and research by eliminating manual passage variability and enabling continuous culture monitoring. Bioreactors capture the largest value pool as perfusion-enabled systems displace fed-batch platforms in commercial cell therapy production. High-throughput screening applications within stem cell research represent the fastest-expanding technology segment as phenotypic assay automation reduces compound screening cycles. Media preparators remain a margin-dense niche where closed-system formulation reduces contamination risk in GMP environments.
FDA guidance on cell and gene therapy chemistry, manufacturing, and controls shapes equipment validation requirements for closed-system operation and data integrity compliance. EMA's ATMP regulatory framework and ISO 14644 cleanroom classifications further define product specifications for European market access. China's NMPA cell therapy technical guidelines and GMP annex provisions for biological products create additional certification layers for equipment vendors. Stakeholders must monitor evolving regulatory convergence between FDA, EMA, and NMPA on automated process analytical technology requirements as this determines platform redesign priorities and regional market entry sequencing.
Market Dynamics
Perfusion-enabled bioreactors are compressing fed-batch timelines in commercial cell therapy manufacturing, forcing equipment vendors to reengineer platforms for continuous culture protocols and integrated process analytical technology.
Growth Catalysts
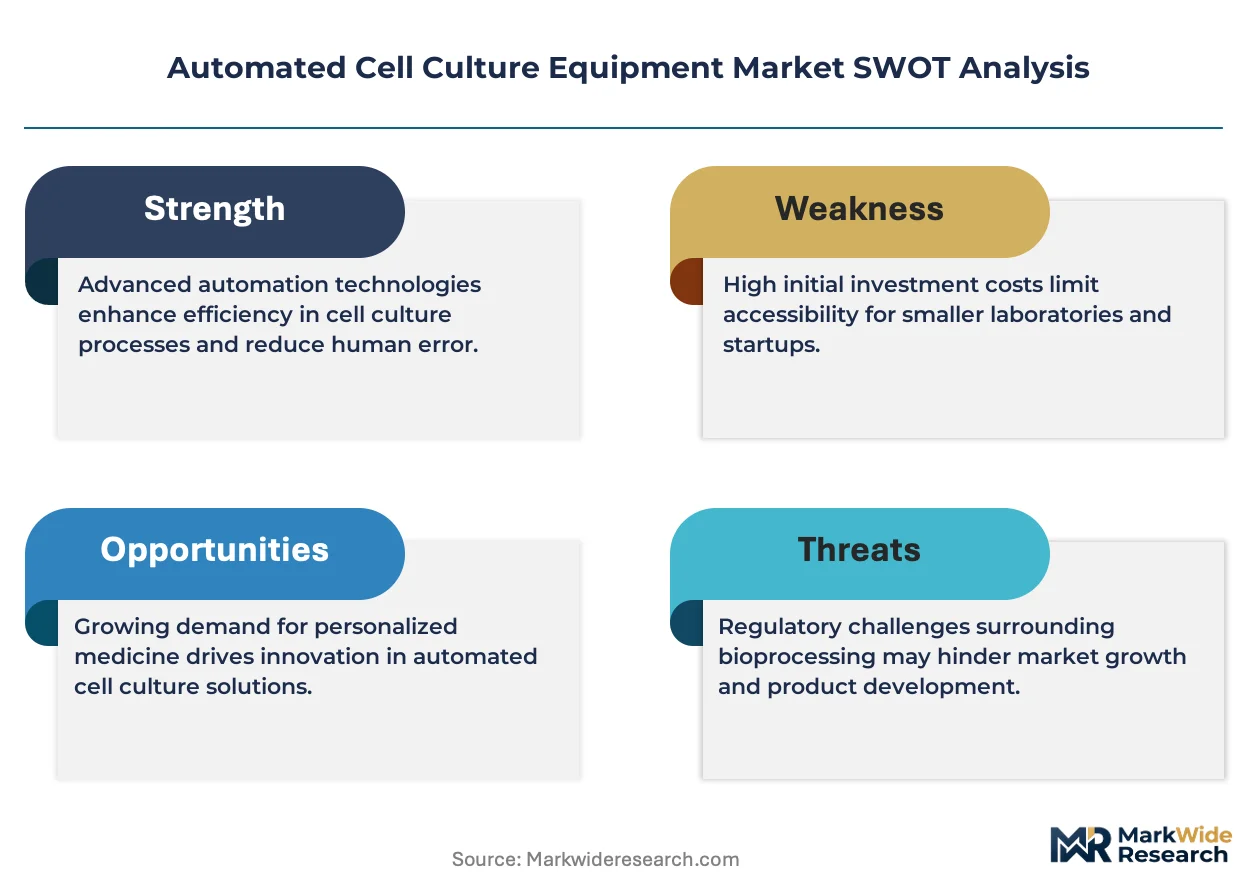
- EMA ATMP Framework:The regulatory pathway accelerates advanced therapy medicinal product approvals, compelling manufacturers to install closed-system automation that satisfies chemistry, manufacturing, and controls documentation requirements.
- Cell Therapy CDMO Expansion:Contract development and manufacturing organizations in the United States, Germany, and China are consolidating multi-site networks, creating pooled procurement demand for standardized automated platforms.
- Process Analytical Technology Integration:Real-time metabolite monitoring and automated feedback control loops reduce manual sampling interventions, cutting contamination risk in GMP-grade cell culture workflows.
Market Restraints
- Stainless Steel Component Supply:Precision-grade bioreactor vessels and sensor housings depend on specialized European and Japanese metalworking suppliers, creating lead time volatility for equipment manufacturers.
- Validation Protocol Burden:FDA guidance on cell and gene therapy CMC requirements imposes extensive installation, operational, and performance qualification documentation, extending sales-to-revenue cycles by six to eighteen months.
- Single-Use Plastic Costs:Bioprocess bags and tubing assemblies face petroleum-derived resin price swings that compress margins on consumables-integrated automation platforms.
Strategic Opportunities
- India Biopharma Manufacturing:The country's PLI scheme for pharmaceuticals and expanding CDMO footprint create first-mover advantage for automated platform vendors establishing local service infrastructure.
- Organoid and 3D Culture Automation:High-content screening workflows for patient-derived tumor models require specialized bioreactor geometries that incumbent perfusion systems do not address.
- ISO 14644-1 Cleanroom Convergence:Harmonized airborne particulate classification standards across FDA, EMA, and NMPA jurisdictions enable modular platform designs that reduce regional customization costs.
Industry Challenges
- GMP Automation Engineering Talent:The intersection of cell biology, software controls, and pharmaceutical validation creates acute hiring scarcity for field service and application scientist roles.
- Legacy Equipment Integration:Brownfield manufacturing facilities require protocol bridges between decades-old supervisory control systems and modern automated bioreactor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Cell Culture Equipment Market |
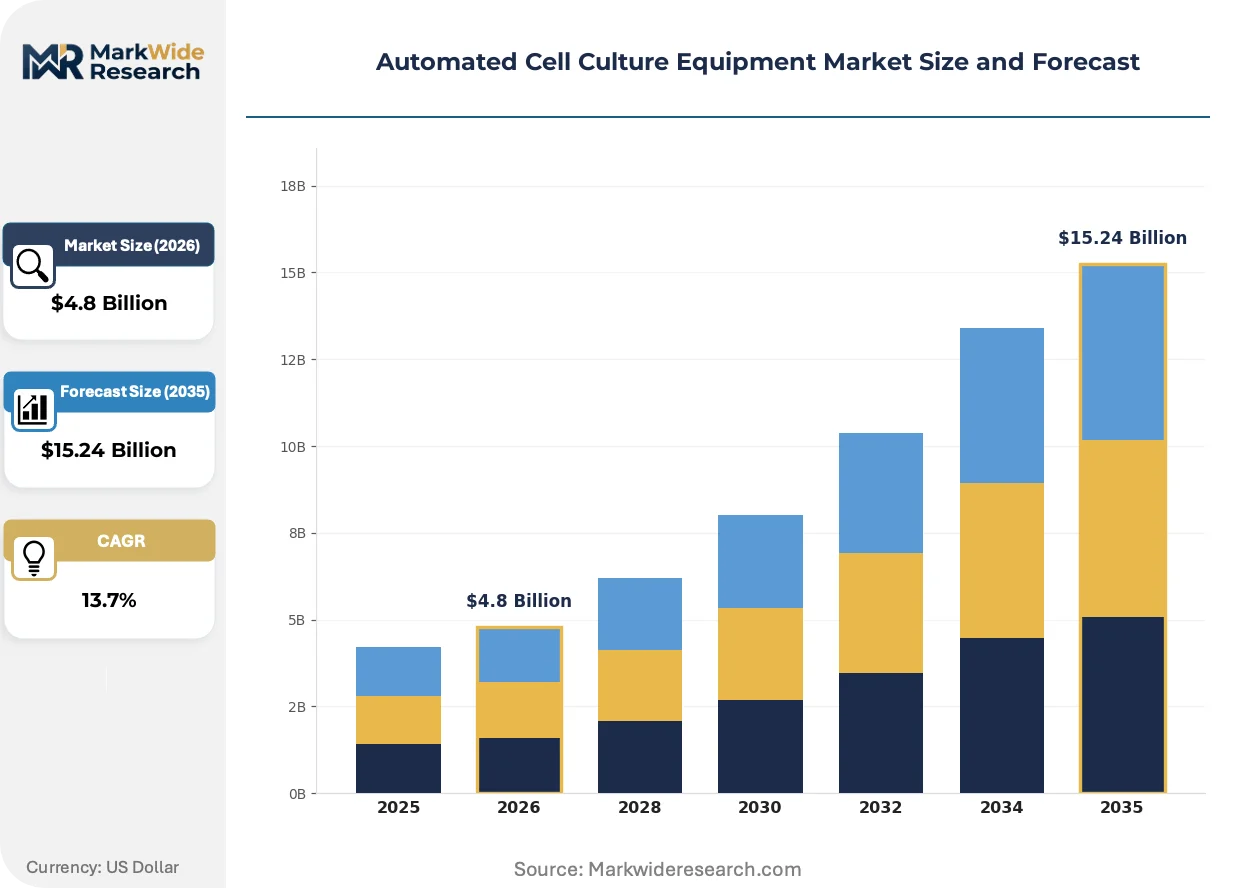
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Incubators, Cell Counters, Media Preparators Technology: Microbial Culture, Stem Cell Research, Tissue Engineering, High-Throughput Screening End User: Research Laboratories, Biotechnology Companies, Pharmaceutical Firms, Academic Institutions Application: Drug Development, Vaccine Production, Genetic Engineering, Cell Therapy |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Corning Incorporated, Lonza Group, Sartorius AG, Danaher Corporation, Becton, Dickinson and Company, Tecan Group, Eppendorf SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Cell Culture Equipment Market Emerging Trajectories
Artificial intelligence-driven process control and modular hardware architectures are compressing the gap between research-scale flexibility and commercial-scale reliability in automated cell culture systems.
Closed-system perfusion bioreactors with integrated cell retention devices are absorbing the workload previously handled by repeated manual passage operations in autologous cell therapy manufacturing. Academic research groups and early-stage biotechnology firms adopt these platforms to reduce operator-induced variability. The technology is absorbing intermediate-scale production volumes that neither static flask culture nor full commercial stainless steel systems efficiently serve.
FDA draft guidance on computer software assurance for manufacturing equipment elevates data integrity requirements for automated cell culture platforms. The policy compels vendors to implement audit trail architectures and electronic signature workflows that satisfy 21 CFR Part 11 compliance. European manufacturers targeting US market entry are accelerating software qualification investments to preempt regulatory review delays.
CDMO procurement teams now unbundle capital equipment purchases from multi-year service contracts, pressuring vendors to compete on discrete maintenance pricing and spare parts availability. This behavior shift fragments vendor revenue streams and elevates aftermarket service capabilities as a competitive differentiator. The pattern is most pronounced among US-based contract manufacturers managing distributed manufacturing networks across multiple states.
Automated Cell Culture Equipment Market Segmentation
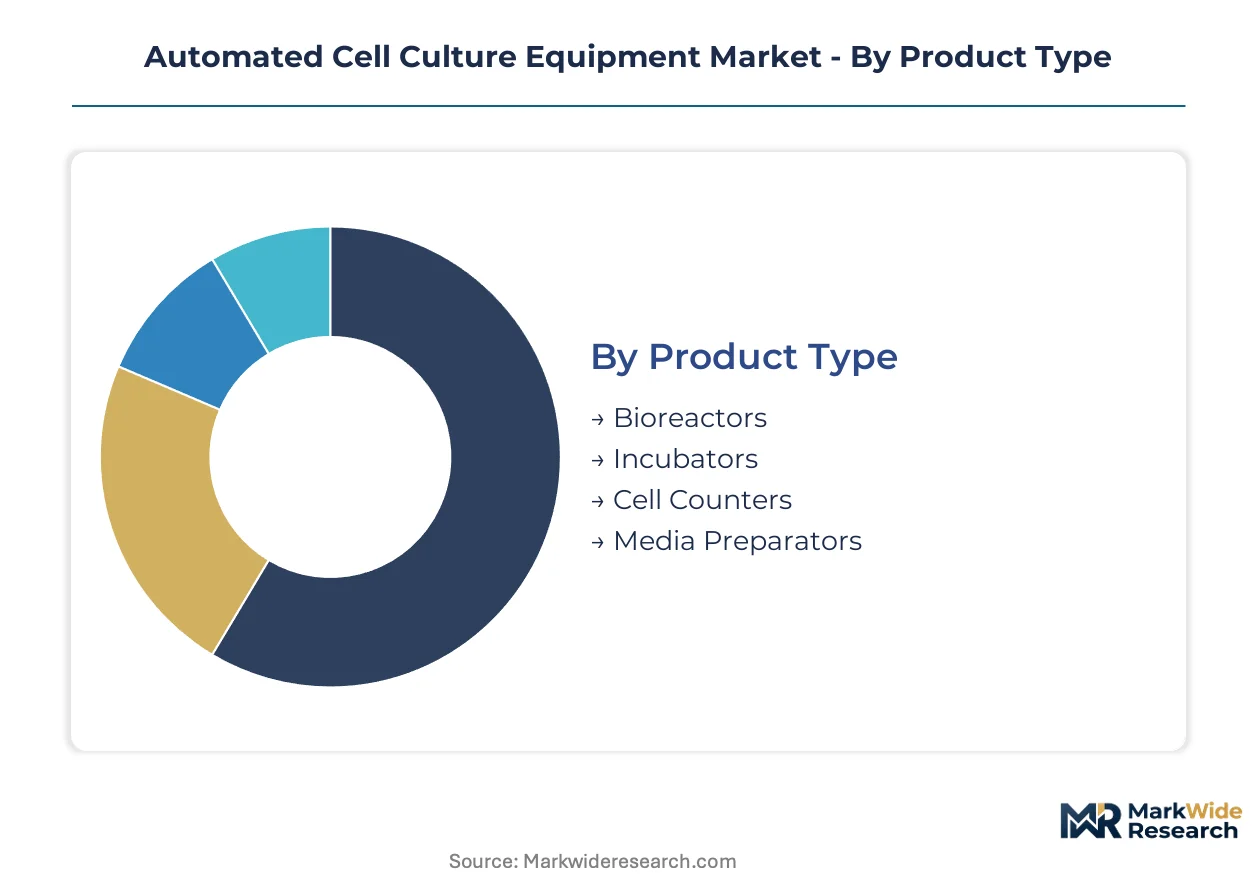
Automated cell culture equipment segments diverge sharply by capital intensity and regulatory burden. Bioreactor buyers prioritize perfusion capability and PAT integration, while research laboratories optimize for throughput flexibility and footprint efficiency.
Product Type:
Capital deployment thresholds separate institutional buyers from contract manufacturers in this category.
- Bioreactors:Perfusion-enabled systems with integrated cell retention devices dominate commercial cell therapy manufacturing. Demand concentrates among United States-based CDMOs scaling autologous therapy production, constrained by stainless steel component lead times from European and Japanese suppliers.
- Incubators:Closed-loop environmental control systems maintain 37°C, 5% CO₂, and 95% humidity parameters with automated door-locking protocols. Biotechnology companies in Germany favor these platforms for GMP-compliant stem cell expansion workflows ahead of EMA ATMP submissions.
- Cell Counters:Automated viability analysis systems reduce manual hemocytometer variability in high-throughput screening workflows.
- Media Preparators:Closed-system formulation equipment commands premium pricing in pharmaceutical manufacturing environments.
Volume sits with bioreactors; growth tilts toward media preparators.
Technology:
Application maturity determines automation architecture requirements across research and commercial settings.
- Stem Cell Research:Phenotypic assay automation platforms enable high-content screening of pluripotent cell lines with integrated imaging modules. Academic institutions in China deploy these systems under NMPA technical guidelines for cell therapy precursor studies, accelerating compound screening cycles.
- High-Throughput Screening:Parallel bioreactor arrays with automated liquid handling compress lead identification timelines. Contract research organizations in the United States adopt these platforms to serve pharmaceutical client portfolios, though software qualification burdens extend procurement cycles.
- Microbial Culture:Traditional fermentation automation serves vaccine production and industrial enzyme manufacturing.
- Tissue Engineering:Specialized scaffold-perfusion systems address organoid and 3D culture geometries.
Stem cell research commands the steepest expansion trajectory; microbial culture retains the largest installed base.
End User:
Procurement authority and validation expertise create distinct purchasing patterns across buyer types.
- Pharmaceutical Firms:Integrated bioproduction platforms with standardized automation architectures support multi-site manufacturing networks. These buyers in Germany leverage EMA guidance to enforce closed-system validation protocols across CDMO partnerships.
- Biotechnology Companies:Modular platforms with research-scale flexibility and commercial-upgrade pathways dominate capital planning. Early-stage firms in the United States prioritize equipment with 21 CFR Part 11-compliant software to preempt FDA review delays.
- Research Laboratories:Footprint-constrained systems with open API architectures enable custom workflow integration.
- Academic Institutions:Cost-optimized platforms with shared-service access models spread capital burden across investigator groups.
Pharmaceutical firms drive average transaction value; biotechnology companies expand the fastest.
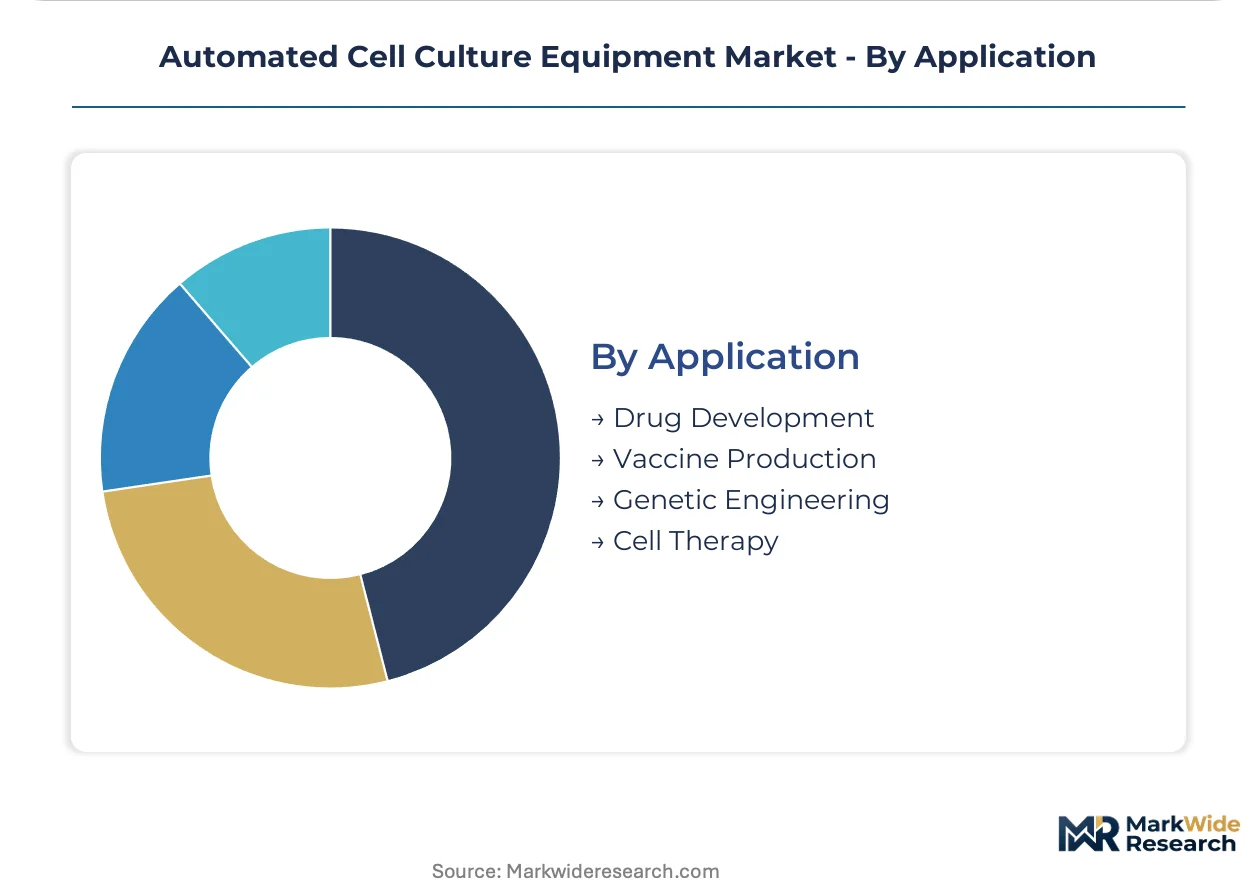
Application:
Regulatory pathway complexity shapes equipment specification requirements and sales cycle duration.
- Cell Therapy:Closed-system perfusion bioreactors with automated cell retention displace manual passage operations in autologous manufacturing. FDA chemistry, manufacturing, and controls guidance tightens validation documentation for these platforms, extending sales-to-revenue cycles.
- Vaccine Production:Fed-batch and perfusion bioreactor systems serve viral vector and recombinant protein manufacturing. Chinese manufacturers under NMPA GMP annex provisions for biological products drive regional demand concentration.
- Drug Development:High-throughput screening automation reduces compound characterization timelines in early-phase research.
- Genetic Engineering:Precision editing workflows require specialized incubation and analysis platforms.
Cell therapy absorbs premium platform investment; vaccine production sustains volume demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy manufacturing investments concentrate in three countries that together host the majority of GMP-certified production facilities and active clinical trial infrastructure for advanced therapeutic products.
United States
FDA chemistry, manufacturing, and controls guidance drives CDMO procurement of closed-system automation for autologous therapy production. The agency's draft guidance on computer software assurance elevates data integrity requirements for 21 CFR Part 11 compliance. Greater Boston and the San Francisco Bay Area anchor the highest density of cell therapy manufacturing facilities under active FDA review.
Germany
EMA's ATMP regulatory framework accelerates advanced therapy approvals, compelling manufacturers to install validated closed-system equipment. EMA guidance on chemistry, manufacturing, and controls documentation shapes equipment specification requirements for European market access. The Rhine-Main and Munich clusters concentrate CDMO networks serving EMA-submitted cell therapy programs.
China
NMPA cell therapy technical guidelines and GMP annex provisions for biological products create certification layers for equipment vendors entering the market. The regulator's evolving process analytical technology requirements determine platform redesign priorities for regional entry. Shanghai and Suzhou industrial parks host the largest concentration of NMPA-registered cell therapy manufacturing investments.
United Kingdom
MHRA alignment with EMA ATMP standards post-Brexit maintains equipment validation continuity for manufacturers serving both markets. The regulator's innovation passport pathway accelerates access for automated platforms targeting rare disease therapies. The Golden Triangle biotech corridor between London, Oxford, and Cambridge sustains demand for research-scale automation with commercial-upgrade pathways.
India
The PLI scheme for pharmaceuticals and expanding CDMO footprint create procurement opportunities for automated platform vendors establishing local service infrastructure. CDSCO guidelines for cell therapy products are converging with international GMP standards for biological manufacturing. Hyderabad and Bengaluru biotech clusters are attracting contract manufacturing investments that require GMP-grade automation infrastructure.
Automated Cell Culture Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular architectures and single-use integration to differentiate positioning. The market structure consolidates around diversified life science conglomerates with integrated bioproduction portfolios alongside specialized automation vendors. Three archetypes dominate: full-stack bioproduction platforms, precision liquid handling specialists, and single-use consumables-integrated systems. Competitive moves concentrate on strategic partnerships with CDMO networks and geographic expansion through localized service infrastructure.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify integrated platform strategies spanning upstream cell culture through downstream processing. Sartorius AG occupies a position as the specialized single-use integration archetype, anchoring competitive dynamics around consumables-recurring revenue models. These three companies collectively represent the strategic positioning that shapes procurement negotiations with multi-site CDMO networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Corning Incorporated |
| Lonza Group |
| Sartorius AG |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Tecan Group |
| Eppendorf SE |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up CDMO networks in the United States and Germany exercise consolidated procurement power, compressing capital equipment margins while extending payment terms to equipment vendors. This ownership pattern feeds pricing discipline back into supplier selection, favoring vendors with captive consumables revenue and regional service infrastructure.
Pricing Analysis
Volume concentrates with bioreactor systems while margin density sits with media preparators and single-use consumables bundles. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated platforms with 21 CFR Part 11 software from research-grade configurations. Pricing pressure stems from CDMO procurement teams unbundling service contracts from capital purchases. Biotechnology companies exhibit the highest price sensitivity due to constrained venture funding, while pharmaceutical firms prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with precision-grade stainless steel bioreactor vessels and sensor housings from specialized European and Japanese metalworking suppliers. Component sourcing draws from Germany, Japan, and Switzerland for precision machining, with bioprocess bags and tubing assemblies anchored in petroleum-derived resin supply chains. Tariff exposure on precision metal components creates lead time volatility for equipment manufacturers. Distribution runs through direct sales teams serving multi-site CDMO networks, supplemented by specialized distributors for research laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perfusion-enabled bioreactors with integrated process analytical technology are displacing fed-batch platforms in commercial cell therapy manufacturing, creating a technology-transition window for repositioning. This substitution dynamic compresses timelines for legacy equipment obsolescence.
For Market Incumbents: Acquire field service and application scientist capabilities to offset unbundling pressure on equipment margins. Consolidate aftermarket parts distribution in the United States and Germany to preempt emerging entrants from establishing service footholds. CDMO procurement centralization threatens installed-base retention, making captive consumables integration the critical defensive lever. For New Entrants and Emerging Players: Capture organoid and 3D culture automation white space where incumbent perfusion geometries fail to address scaffold-perfusion requirements. Target India's expanding CDMO footprint under the PLI scheme before established vendors complete local service infrastructure buildout. Position around modular hardware architectures with research-scale flexibility and commercial-upgrade pathways to bypass validation protocol barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized single-use integration specialists with consumables-recurring revenue models in European manufacturing clusters. The five-to-ten year viability window favors platforms with software qualification investments already completed for FDA computer software assurance guidance. Monitor EMA-NMPA regulatory convergence on automated process analytical technology requirements as the inflection signal for platform redesign priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Bioreactor Platform Launch | Closed-system automation satisfies FDA chemistry, manufacturing, and controls documentation for autologous therapies. |
| Regional Service Infrastructure Expansion | Local application scientist presence in India and China preempts CDMO procurement consolidation. |
| Single-Use Consumables Integration | Recurring revenue streams offset capital equipment margin compression from unbundled procurement. |
| 21 CFR Part 11 Software Qualification | Preemptive compliance with FDA computer software assurance guidance accelerates sales-to-revenue cycles. |
| Organoid Bioreactor Geometry Development | Specialized scaffold-perfusion systems address patient-derived tumor models outside incumbent platform coverage. |
Methodological Framework
Multi-period observation of CDMO capital expenditure patterns, clinical trial enrollment trajectories, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with bioprocess engineers, GMP validation specialists, CDMO procurement directors, and regulatory affairs leads at cell therapy developers. Secondary validation drew from FDA guidance documents, EMA ATMP assessment reports, NMPA technical guidelines, ClinicalTrials.gov protocol registries, and SEC filings of diversified life science conglomerates. Bottom-up equipment shipment tracking and top-down pharmaceutical manufacturing capacity modeling were triangulated to cross-verify segment sizing.
Input-output matrices mapped bioreactor unit deployments against cell therapy manufacturing capacity expansion across the projection horizon. Segmentation dimensions modeled include product type, technology application, end-user archetype, and regional regulatory cluster. CAGRs were derived from curve-fitting observed adoption rates against manufacturing capacity buildout schedules. Industry-specific forecast inputs incorporated stainless steel component lead time volatility and CDMO network consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA-NMPA regulatory convergence timing and petroleum-derived resin price trajectories. Forecasts reflect documented assumptions regarding CDMO procurement centralization and software qualification burden evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Amino Acid Analyzer Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Cell Separation Bead Market