
 Analytical Instrumentation in Life Science Market | 2026-2036
Analytical Instrumentation in Life Science Market Size, Share, and Industry Trends Forecast 2026-2036
Analytical Instrumentation in Life Science Market Insights
Asset-light leasing and managed-service contracts for chromatography suites is tilting competitive dynamics toward vendors with balance-sheet capacity to carry instrument fleets. Thermo Fisher Scientific leverages its captive financing arm to place Orbitrap systems at contract research organizations without upfront capital burden. Danaher Corporation sustains instrument pull-through via recurring consumable revenue streams that lock in multi-year customer relationships. Bruker Corporation differentiates through high-field NMR placements that command premium service attach rates in academic core facilities.
Analytical instrumentation in life science encompasses chromatography systems, spectroscopy devices, mass spectrometers, and electrophoresis equipment engineered to resolve, quantify, and characterize biomolecules at detection thresholds reaching picogram sensitivity for proteomic and metabolomic workflows. HPLC and mass spectrometry platforms dominate current installed bases due to their centrality in drug-substance purity verification and impurity profiling under pharmacopeial standards. Spectroscopy devices occupy mature replacement cycles where FTIR upgrades are driven by portable form-factor adoption in at-line quality control environments. Electrophoresis equipment competes for share in capillary formats as clinical laboratories transition from slab-gel methods to automated separation for diagnostic protein analysis.
FDA method-validation guidelines and EMA ICH Q2(R1) revisions compel pharmaceutical companies to requalify legacy chromatography platforms, directly stimulating replacement demand for compliant systems. ISO 17025 accreditation requirements for testing laboratories further tighten calibration and documentation protocols that favor vendors with integrated compliance software ecosystems. Stakeholders must monitor how EPA and REACH expansion into per- and polyfluoroalkyl substance analytics redirects R&D investment toward specialized mass spectrometry configurations capable of trace-level fluorinated compound detection.
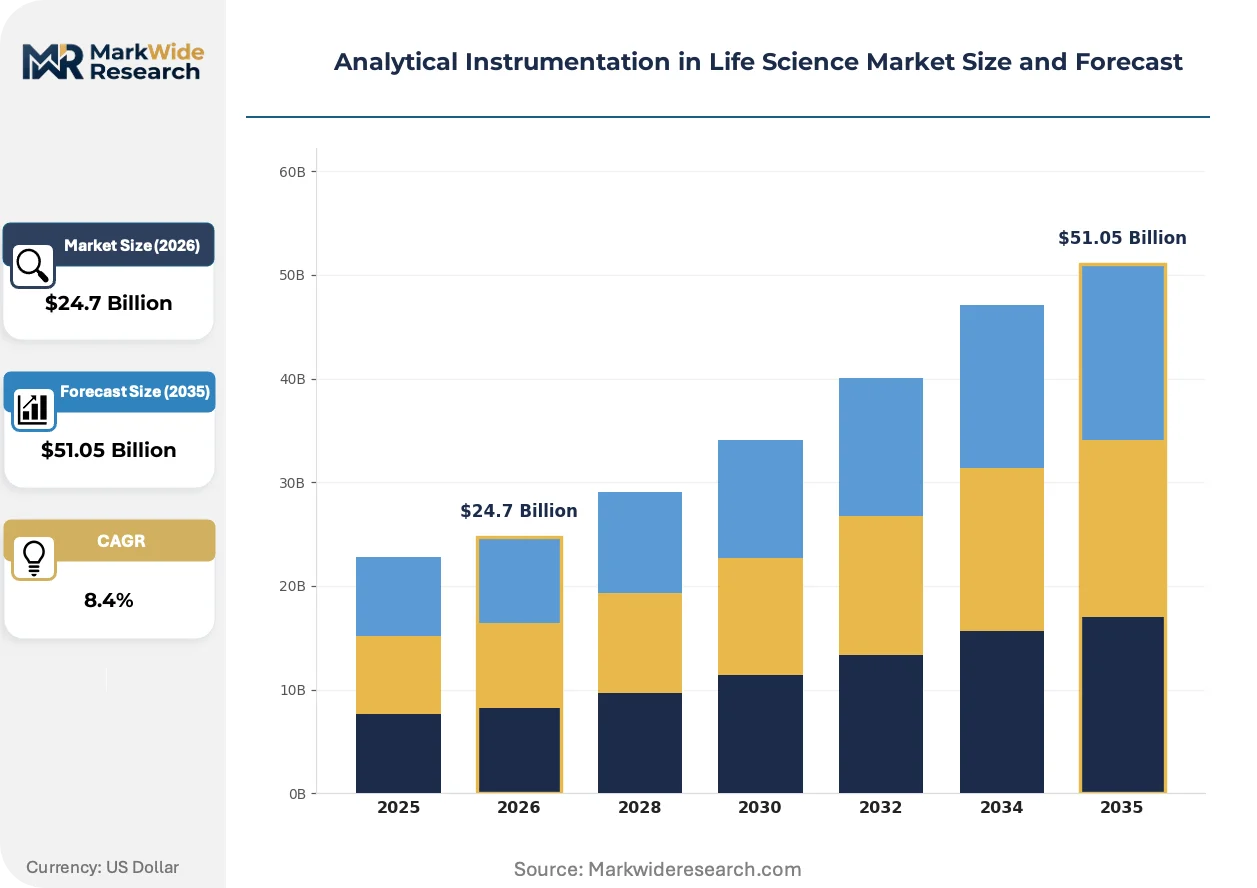
Market Dynamics
Asset-light leasing structures are compressing capital barriers for contract research organizations while concentrating vendor balance-sheet risk among instrument manufacturers with captive financing capacity.
Growth Catalysts
- ICH Q2(R1) Revisions:EMA-mandated requalification of legacy chromatography platforms is forcing pharmaceutical manufacturers into systematic replacement cycles for compliant separation systems.
- NIH Funding Expansion:United States federal research budget growth is directing capital deployment into high-resolution mass spectrometry at academic core facilities and national laboratories.
- Biologics Characterization Demand:Monoclonal antibody and cell therapy pipelines require picogram-sensitivity detection thresholds that only advanced Orbitrap and Q-TOF configurations can deliver.
Market Restraints
- Helium Supply Concentration:Mass spectrometry and NMR operations depend on helium-3 and helium-4 sourcing concentrated in Qatar and Russia, exposing instrument uptime to geopolitical supply disruptions.
- Consumable Cost Structure:Chromatography column and solvent recurring expenses lock laboratories into vendor ecosystems with limited third-party alternatives, inflating total cost of ownership.
- Technical Talent Scarcity:Specialized expertise in mass spectrometer maintenance and method development concentrates in Boston and San Diego metropolitan clusters, constraining facility expansion elsewhere.
Strategic Opportunities
- Per- and Polyfluoroalkyl Substance Analytics:EPA expansion into PFAS trace detection is redirecting R&D investment toward specialized triple-quadrupole configurations with fluorinated compound specificity.
- At-Line Quality Control Migration:Portable FTIR and Raman systems are penetrating pharmaceutical manufacturing floors, displacing centralized laboratory workflows with real-time release testing.
- India CRO Consolidation:Contract research organization mergers in Hyderabad and Bengaluru are creating instrument fleet standardization opportunities for vendors with localized service infrastructure.
Industry Challenges
- ISO 17025 Accreditation Timelines:Testing laboratories face 12-18 month certification cycles for calibration documentation protocols, delaying revenue recognition on new instrument deployments.
- Legacy Data System Integration:Pharmaceutical quality control networks struggle to interface 21 CFR Part 11-compliant software with decades-old chromatography data stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytical Instrumentation in Life Science Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Systems, Spectroscopy Devices, Mass Spectrometers, Electrophoresis Equipment Technology: HPLC, NMR, GC, FTIR End User: Research Laboratories, Academic Institutions, Pharmaceutical Companies, Clinical Laboratories Application: Quality Control, Drug Development, Environmental Testing, Clinical Diagnostics |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Agilent Technologies Inc., PerkinElmer Inc., Waters Corporation, Shimadzu Corporation, Bruker Corporation, Bio-Rad Laboratories Inc., Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytical Instrumentation in Life Science Market Trends and Innovations
Artificial intelligence is penetrating analytical workflows from method optimization to predictive maintenance, compressing the skill gap between specialist operators and routine laboratory staff.
Cloud-native chromatography data systems are digitizing instrument fleet management across multi-site pharmaceutical networks. Pfizer and AstraZeneca operations teams in the United States and United Kingdom are deploying these platforms to centralize method transfer and reduce compliance documentation burden. The technology is digitizing how quality control laboratories coordinate release testing across geographically distributed manufacturing sites.
EMA's F-Gas Regulation is accelerating replacement of helium-cooled NMR systems with closed-cycle cryogen-free alternatives in European academic facilities. The policy mandates phased reduction in fluorinated greenhouse gas emissions from scientific equipment, directly impacting high-field magnet installations. German and Swiss core facilities are responding with procurement specifications that exclude conventional helium infrastructure.
Service unbundling is fragmenting traditional instrument vendor relationships in the United States clinical laboratory segment. Quest Diagnostics and LabCorp are separating hardware acquisition from maintenance contracts, engaging third-party field service organizations for mass spectrometer uptime guarantees. This pattern is most visible in California and Texas metropolitan markets where independent service engineer networks have achieved critical density.
Analytical Instrumentation in Life Science Market Segmentation
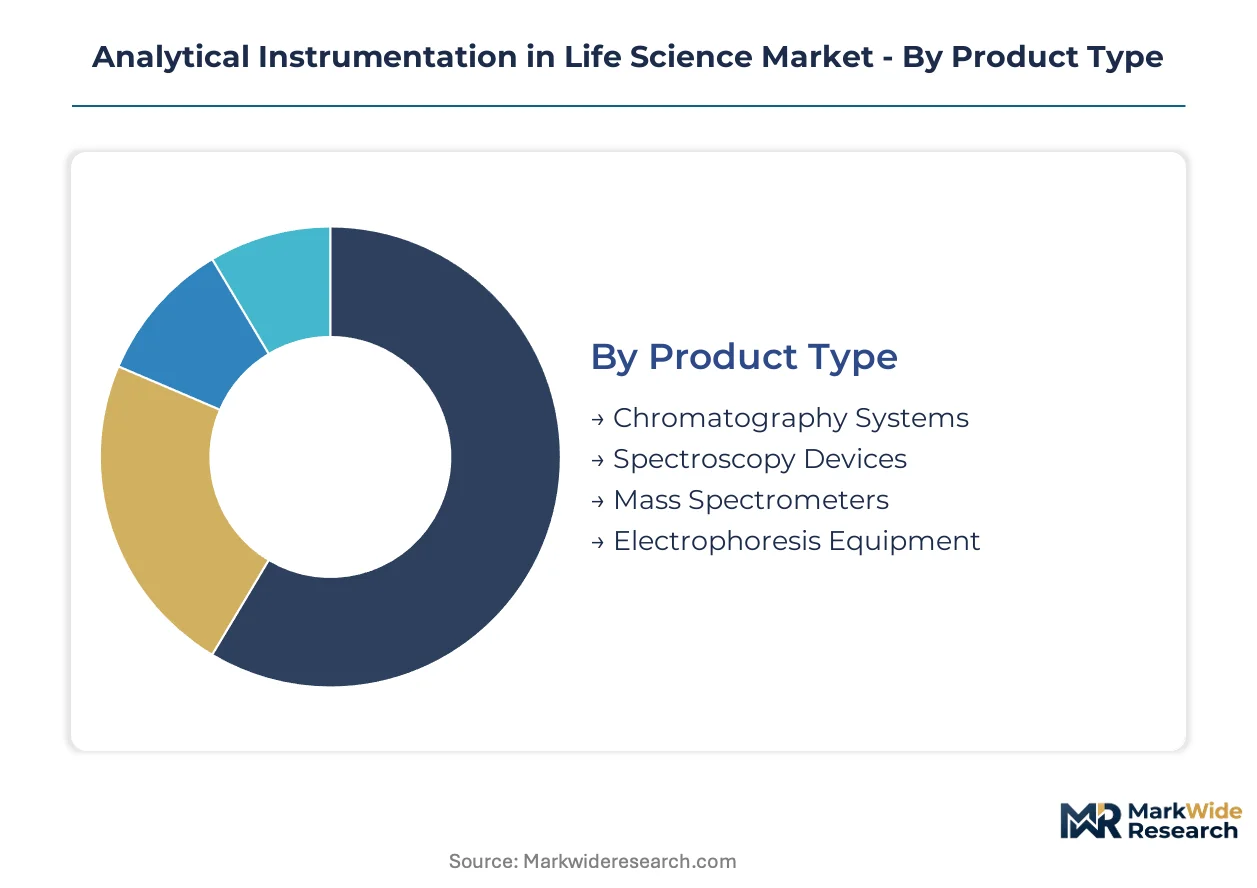
Segmentation in analytical instrumentation reveals how vendor business models must adapt across divergent customer economics. Service attach rates, consumable pull-through, and replacement cycles vary dramatically by product category and end-use intensity.
Product Type:
After-sales-service intensity peaks with mass spectrometers and NMR platforms, where annual maintenance contracts often exceed 15% of instrument purchase value and field engineer density determines account retention.
- Chromatography Systems:HPLC and UPLC configurations dominate pharmaceutical quality control floors with method-transfer requirements that lock customers into vendor-specific column chemistries. United States contract research organizations in Boston and San Diego metropolitan clusters drive replacement demand as FDA method-validation guidelines tighten.
- Mass Spectrometers:Orbitrap and triple-quadrupole platforms command premium service ecosystems due to vacuum system complexity and ion source maintenance protocols. NIH funding expansion at academic core facilities concentrates demand for high-resolution configurations capable of picogram-sensitivity proteomic workflows.
- Spectroscopy Devices:FTIR and Raman systems compete on portable form-factor adoption for at-line pharmaceutical manufacturing applications.
- Electrophoresis Equipment:Capillary formats displace slab-gel methods in clinical laboratories automating diagnostic protein separation.
By volume, chromatography systems lead. By growth pace, mass spectrometers are expanding most quickly.
Technology:
Technology selection directly determines consumable revenue streams and customer switching costs, with HPLC and GC platforms generating recurring solvent and column purchases that sustain multi-year vendor relationships.
- HPLC:Ultra-high-pressure configurations achieve sub-2-micron particle resolution for biologics impurity profiling under pharmacopeial standards. Pharmaceutical manufacturers in Germany and Switzerland face EMA F-Gas Regulation pressures that favor solvent-efficient method transfers.
- NMR:High-field magnets require helium-3 and helium-4 sourcing concentrated in Qatar and Russia, exposing European academic facilities to geopolitical supply disruptions and accelerating cryogen-free alternatives adoption.
- GC:Gas chromatography platforms serve environmental testing laboratories confronting EPA expansion into per- and polyfluoroalkyl substance trace detection requirements.
- FTIR:Fourier-transform infrared systems penetrate pharmaceutical manufacturing floors through portable configurations enabling real-time release testing.
By installed base, HPLC dominates. By margin structure, NMR commands the steepest service premiums.
End User:
Customer procurement authority varies sharply across end-user categories, with pharmaceutical companies consolidating fleet standardization decisions at headquarters while academic institutions delegate to individual principal investigators.
- Pharmaceutical Companies:Quality control networks demand 21 CFR Part 11-compliant data systems with centralized method transfer capabilities across United States and United Kingdom manufacturing sites. Cloud-native chromatography platforms from Pfizer and AstraZeneca operations teams illustrate this consolidation pattern.
- Research Laboratories:National laboratories and core facilities prioritize detection sensitivity specifications that justify high-resolution mass spectrometry capital deployment.
- Academic Institutions:German and Swiss universities respond to EMA F-Gas Regulation with procurement specifications excluding conventional helium-cooled NMR infrastructure.
- Clinical Laboratories:Quest Diagnostics and LabCorp in California and Texas markets unbundle hardware acquisition from maintenance contracts, engaging third-party field service organizations for uptime guarantees.
By spending concentration, pharmaceutical companies lead. By volume growth, clinical laboratories are gaining share fastest.
Application:
Application focus determines regulatory exposure and compliance documentation burden, with quality control and drug development facing the most stringent method-validation requirements.
- Quality Control:Drug-substance purity verification and impurity profiling under FDA and EMA pharmacopeial standards compel systematic replacement of legacy chromatography platforms. ISO 17025 accreditation timelines of 12-18 months delay revenue recognition on new instrument deployments.
- Drug Development:Monoclonal antibody and cell therapy pipelines require picogram-sensitivity detection thresholds that drive Orbitrap and Q-TOF configuration demand at United States biotechnology clusters.
- Environmental Testing:EPA expansion into PFAS analytics redirects R&D investment toward specialized triple-quadrupole mass spectrometry with fluorinated compound specificity.
- Clinical Diagnostics:Automated capillary electrophoresis displaces manual slab-gel methods for diagnostic protein analysis in high-throughput laboratory settings.
By revenue stability, quality control leads. By investment intensity, drug development shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal research budget expansion and tightening pharmacopeial standards are redirecting capital deployment toward high-resolution analytical platforms across major life science clusters.
United States
NIH funding growth is accelerating Orbitrap and Q-TOF placements at academic core facilities in Boston and San Diego. FDA method-validation guidelines compel pharmaceutical manufacturers into systematic chromatography platform replacements. The Greater Boston biotechnology corridor concentrates demand for picogram-sensitivity mass spectrometry serving monoclonal antibody pipelines.
Germany
EMA F-Gas Regulation mandates are forcing cryogen-free NMR adoption at Bavarian and North Rhine-Westphalian university facilities. REACH compliance documentation requirements favor vendors with integrated calibration software ecosystems. The Munich-Stuttgart academic corridor leads procurement specifications excluding conventional helium-cooled magnet infrastructure.
Switzerland
Swissmedic quality standards and ISO 17025 accreditation timelines drive pharmaceutical quality control instrument standardization decisions. Federal environmental regulations redirect R&D investment toward specialized PFAS detection configurations. The Basel-Zurich pharmaceutical manufacturing belt concentrates service unbundling trends among clinical laboratory networks.
China
NMPA biologics approval pathway expansion is stimulating domestic chromatography fleet growth at contract research organizations in Shanghai and Suzhou. National standards for pharmaceutical impurity profiling tighten method-validation requirements. The Yangtze River Delta life science corridor attracts capital deployment into automated separation systems for cell therapy characterization.
India
CDSCO quality guideline harmonization with ICH standards is compelling CRO instrument fleet upgrades in Hyderabad and Bengaluru. PLI scheme incentives for pharmaceutical manufacturing support capital investment in compliant analytical infrastructure. The Hyderabad-Bengaluru contract research corridor presents standardization opportunities for vendors with localized field service density.
Analytical Instrumentation in Life Science Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument financing, consumable lock-in, and service attach rate vectors. The vendor base concentrates among diversified life science conglomerates with captive financing arms and pure-play analytical instrument specialists with premium technology positioning. Three archetypes dominate: balance-sheet-heavy lessors carrying instrument fleets, consumable-anchored platforms generating recurring revenue streams, and high-field technology specialists commanding service premiums. Competitive dynamics center on M&A consolidation of CRO service networks and backward integration into critical component supply.
Among the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify channel-control strategies through captive financing and consumable ecosystems. Bruker Corporation occupies a position within the high-field technology specialist archetype, anchoring premium service relationships in academic core facilities. These three entities represent distinct competitive positioning vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| Waters Corporation |
| Shimadzu Corporation |
| Bruker Corporation |
| Bio-Rad Laboratories Inc. |
| Sartorius AG |
| Others |
Pricing and Supply Chain Analysis
Qatar and Russia's concentration of helium-3 and helium-4 isotopes funnels margin capture toward instrument manufacturers with captive cryogen logistics and long-term offtake contracts. Mass spectrometer and NMR vendors absorb supply risk into service attach rates that laboratories cannot easily substitute.
Pricing Analysis
Certification level creates the primary spread, with FDA-grade and ISO 17025-compliant systems commanding 25-40% premiums over standard laboratory configurations. Three-tier pricing structure across premium, standard, and economy levels reflects method-validation stringency and software ecosystem integration depth. Pricing pressure stems from CRO consolidation in Boston and San Diego, where volume purchasing agreements compress list prices for chromatography suites. Academic core facilities exhibit highest price sensitivity due to grant-funded capital cycles, while pharmaceutical quality control networks prioritize compliance over unit cost.
Supply Chain Analysis
Export-control regimes restricting high-field magnet and precision ion optic technologies limit flows from Germany, Japan, and the United States to Chinese and Russian end-users. Superconducting wire production concentrates in Japan and Germany, while vacuum system components source predominantly from United States and European specialty suppliers. Single-source vulnerability in helium isotope supply exposes European academic facilities to geopolitical disruption. Distribution runs through direct field service organizations in mature markets and authorized distributors with technical certification requirements in emerging clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through CRO consolidation in United States biotechnology corridors and pharmaceutical fleet standardization decisions migrating to headquarters procurement functions.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance software that raises switching costs for chromatography and mass spectrometry platforms. Deepen backward integration into critical consumables—proprietary column chemistries and certified reference standards—to capture recurring spend that third-party suppliers cannot replicate. Counter third-party field service unbundling in California and Texas clinical laboratory markets with uptime guarantee contracts that bundle hardware and maintenance. For New Entrants and Emerging Players: Build out cryogen-free NMR configurations targeting German and Swiss academic facilities responding to EMA F-Gas Regulation mandates, where incumbents carry legacy helium infrastructure stranded costs. Penetrate India CRO consolidation in Hyderabad and Bengaluru through localized service engineer density and PLI scheme-aligned financing structures. Lead with cloud-native data systems that reduce ISO 17025 documentation burden as the primary go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward consumable-anchored platform specialists with recurring revenue visibility exceeding 60% of total sales and demonstrated pull-through from instrument placement to recurring spend. Long-term viability across the analysis window favors vendors with balance-sheet capacity to carry leasing portfolios and absorb helium supply volatility. Monitor CDSCO and NMPA biologics approval pathway acceleration as the signal indicating inflection in Asia-Pacific capital deployment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free NMR Product Launch | EMA F-Gas Regulation compliance opens replacement cycles at German and Swiss core facilities. |
| Cloud-Native Data System Integration | Pfizer and AstraZeneca operations teams prioritize centralized method transfer across manufacturing networks. |
| Backward Integration into Column Chemistry | Proprietary consumables lock pharmaceutical quality control laboratories into multi-year vendor relationships. |
| Localized Service Infrastructure Expansion | Hyderabad and Bengaluru CRO consolidation demands field engineer density for fleet standardization wins. |
| PFAS-Specific Mass Spectrometry Development | EPA expansion into fluorinated compound trace detection redirects environmental testing laboratory procurement. |
Research Methodology
A spread of perspectives from instrument vendor sales directors, pharmaceutical quality control managers, academic core facility directors, and CRO procurement leads converged on the working assumptions shaping demand forecasts. Primary fieldwork across Boston, San Diego, Munich, and Basel clusters was cross-validated against FDA method-validation guideline revisions, EMA F-Gas Regulation implementation timelines, NIH funding appropriation documents, and SEC 10-K instrument revenue disclosures. Bottom-up installed base modeling and top-down addressable market sizing were reconciled through iterative triangulation.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, technology platform, end-user procurement authority, and application regulatory exposure. CAGRs were derived from replacement cycle analysis, funding trajectory assessment, and compliance-driven upgrade elasticity. Forecast inputs incorporated helium supply scenario stress-testing and cloud-native platform adoption curves in pharmaceutical manufacturing networks.
Sensitivities concentrate around NIH funding appropriation volatility, EMA F-Gas Regulation enforcement timing, and helium supply disruption severity. Forecasts reflect documented assumptions regarding CRO consolidation pace and biologics pipeline expansion. Material shifts in United States federal research budget trajectory or Qatar-Russia helium export policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Cryopreservation Equipment Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market