
 Global Industrial Enclosures Market | 2026-2036
Global Industrial Enclosures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Enclosures Market Outlook
NEMA 4X-grade corrosion resistance is unwinding legacy procurement patterns across oil and gas, marine, and coastal utility sectors. Rittal sustains manufacturing scale through its vertically integrated German production footprint. Eaton leverages broad electrical distribution channel control to bundle enclosures with switchgear and power management systems. ABB differentiates through digital integration, embedding thermal monitoring and predictive maintenance sensors directly into enclosure architectures.
Industrial enclosures are sealed housings fabricated from cold-rolled steel, aluminum, polycarbonate, or fiberglass-reinforced polymers, designed to protect electrical and electronic components from dust, moisture, corrosive agents, and thermal stress in ambient temperatures ranging from -40°C to +80°C. Their primary purpose is ensuring operational continuity of control systems, power distribution equipment, and communication infrastructure in harsh industrial environments. Wall-mounted enclosures dominate volume shipments across manufacturing floors due to space constraints and accessibility requirements, while rack mounts capture premium positioning in telecommunication and data center applications where standardized 19-inch mounting and cable density management command higher margins. Metal enclosures retain structural leadership in heavy-industry energy and transportation deployments, though plastic and composite alternatives are gaining specification share where weight reduction and electromagnetic transparency matter.
NEMA ratings administered by the National Electrical Manufacturers Association govern North American ingress protection and hazardous location standards, while IEC 60529 IP codes and CE marking under the EU's Low Voltage Directive shape European product compliance and market access pathways. China's GB standards and compulsory CCC certification enforce localized testing protocols that foreign suppliers must navigate for domestic project participation. Stakeholders must monitor evolving cybersecurity mandates for connected enclosures and assess material substitution strategies as carbon-border adjustments begin affecting steel and aluminum sourcing economics.
Market Dynamics
NEMA 4X corrosion-resistant specifications are rewiring procurement protocols across marine terminals and coastal utility installations, forcing specification engineers to abandon legacy carbon-steel enclosures in favor of stainless-steel and fiberglass-reinforced polymer alternatives that withstand salt-laden atmospheric exposure.
Growth Catalysts
- Hyperscale data center construction:Operators in India and Southeast Asia are specifying IP65-rated outdoor enclosures for substations and switchgear housings to support 24/7 uptime guarantees in monsoon-prone climates.
- EU F-Gas Regulation phase-down:The refrigerant containment mandate is accelerating demand for hermetically sealed electrical housings in commercial cooling infrastructure across Germany, France, and the Netherlands.
- Stainless-steel substitution:Coastal wind farm developers are specifying 316-grade enclosures to replace painted carbon-steel units that fail within 18 months of salt-air exposure.
Market Restraints
- Aluminum price volatility:Sheet metal input costs fluctuate with LME trading patterns, compressing margin stability for fabricators serving renewable energy projects.
- Supply concentration in China:GB-standard certified enclosure production clusters in Jiangsu and Zhejiang provinces, creating single-source vulnerability for Western project EPCs.
- Polycarbonate UV degradation:Extended solar exposure in Arizona and Australian desert installations limits polymer enclosure lifecycle to 7-10 years versus 25-year metal alternatives.
Strategic Opportunities
- Modular data center penetration in Indonesia:Colocation providers are sourcing NEMA 3R walk-in enclosures for rapid-deployment edge facilities outside Jakarta and Surabaya.
- EU CSRD carbon disclosure:The Corporate Sustainability Reporting Directive creates specification pull for enclosures with verified recycled-aluminum content and EPD-certified supply chains.
- 5G small-cell densification:Telecom infrastructure OEMs are integrating thermal management and cable routing into compact pole-mounted housings for urban right-of-way deployment.
Industry Challenges
- Multi-standard certification timelines:Simultaneous UL, CE, and CCC testing for a single enclosure platform extends product launch cycles by 14-18 months.
- Legacy SCADA integration:Digital enclosure sensor suites from ABB and Eaton require protocol translation layers to communicate with 1990s-era control systems in brownfield manufacturing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Enclosures Market |
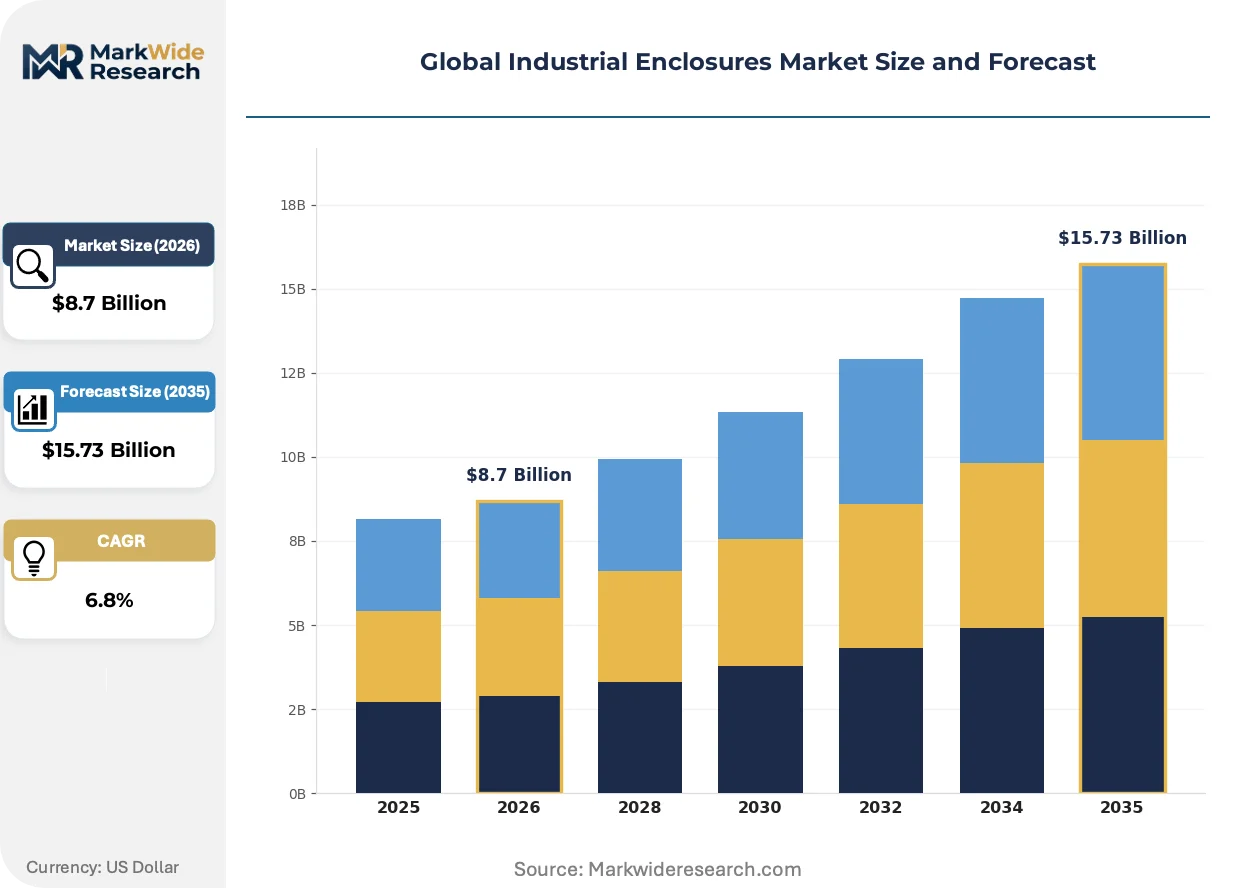
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Rack Mounts, Junction Boxes, Wall-Mounted Enclosures Material: Metal, Plastic, Composite, Fiberglass Protection Rating: IP54, IP65, NEMA 4, NEMA 12 Application: Telecommunication, Manufacturing, Energy, Transportation |
| Companies Covered | Schneider Electric, Eaton, Rittal, ROSE Systemtechnik, Hubbell, nVent HOFFMAN, ABB, Siemens, Hammond Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Enclosures Market Strategic Shifts
Active thermal management and predictive sensor integration are transforming industrial enclosures from passive protective shells into intelligent infrastructure nodes that report operational status to centralized asset management platforms.
Phase-change material cooling systems are supplanting traditional fan-and-filter ventilation in outdoor telecom enclosures. European mobile network operators are deploying these passive thermal solutions across Mediterranean and Middle Eastern markets to eliminate moving parts and reduce field service calls. The technology is compressing total-cost-of-ownership calculations for remote site operators who previously budgeted for quarterly filter replacement cycles.
China's GB/T 4208-2017 standard harmonization with IEC 60529 is streamlining market access for foreign enclosure manufacturers. The MIIT-mandated alignment reduces redundant testing burdens for suppliers seeking CCC certification. Multinational electrical distributors are responding by consolidating Asia-Pacific SKU portfolios around dual-certified product families that satisfy both domestic and export requirements.
Specification authority is migrating from purchasing departments to engineering consultants and EPC firms who control master equipment lists. Oil and gas majors in the Permian Basin and North Sea are delegating enclosure selection to third-party design firms who bundle housings within integrated electrical package contracts. This channel shift is compressing direct manufacturer relationships and privileging distributors with technical specification support capabilities.
Global Industrial Enclosures Market Segmentation
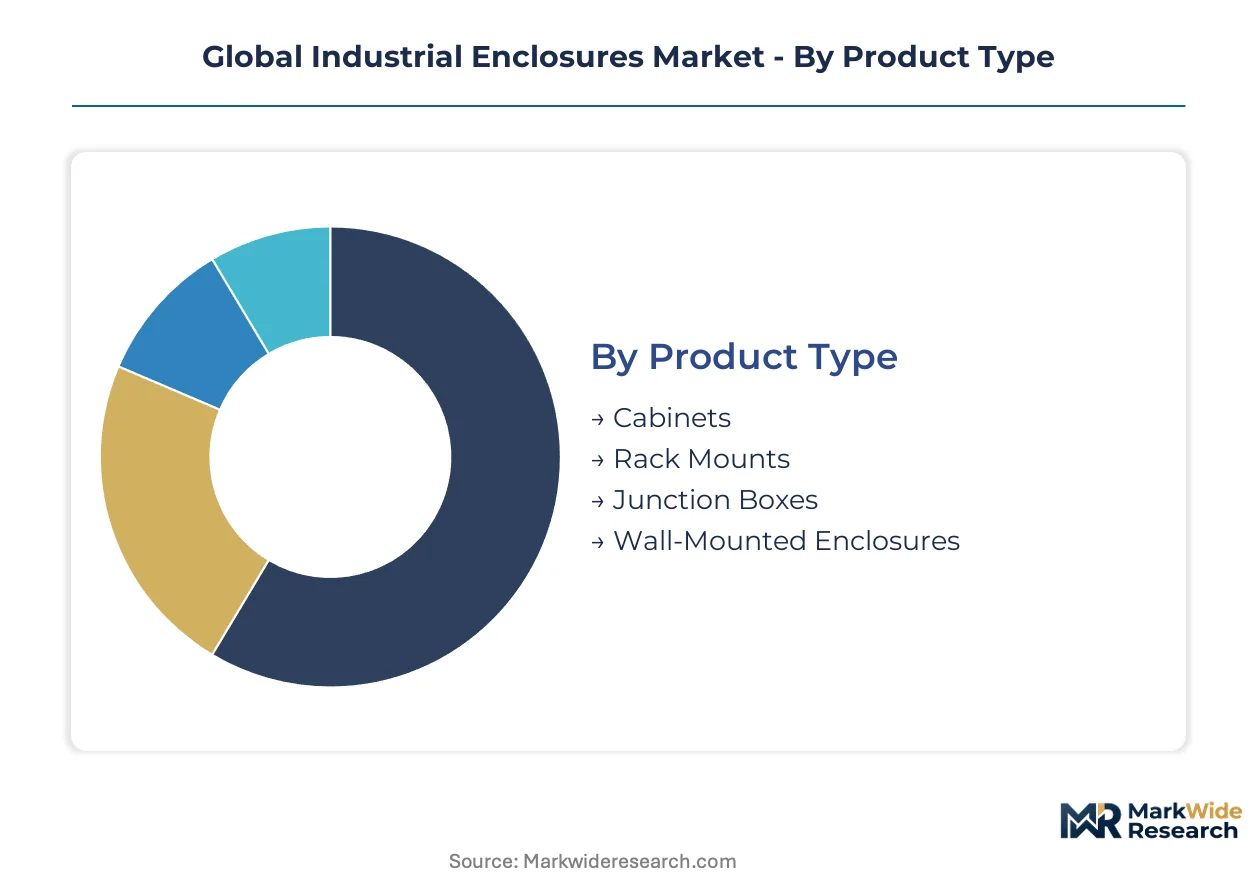
Industrial enclosure specifications diverge sharply by operating environment, with material selection and protection ratings determining project eligibility across coastal utilities, desert solar farms, and humid data center clusters. Procurement teams segment demand through technical compliance filters that eliminate incompatible suppliers before price negotiation begins.
Product Type:
Domestic manufacturing bases in Germany, China, and the United States supply cabinets and wall-mounted units for regional infrastructure projects, while rack mounts and specialized junction boxes flow through export channels to Southeast Asian and Middle Eastern markets.
- Cabinets:Floor-standing housings fabricated from cold-rolled steel or stainless steel accommodate power distribution panels and motor control centers in heavy-industrial settings. Demand concentrates in German automotive plants and Chinese steel mills where NEMA 12 dust-tight specifications protect against metal particulate infiltration.
- Rack Mounts:Standardized 19-inch chassis designed for server and networking equipment feature integrated cable management and thermal ducting. Hyperscale data center operators in India and Indonesia specify these units for switchgear integration, with IP65 sealing mandatory for monsoon-exposed outdoor substations.
- Junction Boxes:Compact terminal housings for field-wired connections serve process industries across Texas petrochemical corridors and Rotterdam port facilities.
- Wall-Mounted Enclosures:Space-efficient housings dominate retrofit installations in aging European manufacturing floors where floor space commands premium valuations.
Cabinets command the established base. The steepest expansion runs through rack mounts.
Material:
Cost stratification separates premium-grade stainless steel from commodity carbon steel and polymer alternatives, with raw material volatility compressing margins most severely in aluminum-intensive renewable energy applications.
- Metal:Cold-rolled steel and aluminum alloys deliver structural integrity for transportation and energy infrastructure. Carbon-steel enclosures face displacement in coastal zones where 316-grade stainless steel from German and Japanese mills outlasts painted alternatives in salt-air exposure.
- Plastic:Polycarbonate and ABS housings reduce weight for telecom pole-mounted applications. Australian and Arizona desert installations expose UV degradation limits, capping service life below metal alternatives.
- Composite:Fiberglass-reinforced polymers combine corrosion immunity with electromagnetic transparency for coastal wind farm sensor housings.
- Fiberglass:Non-conductive shells serve utility substations where arc-flash protection and chemical resistance outweigh thermal conductivity requirements.
Metal retains volume leadership across heavy-industry deployments. Composite materials are climbing the fastest as offshore wind developers abandon carbon-steel maintenance cycles.
Protection Rating:
Application severity dictates specification tiers, with outdoor infrastructure mandates driving migration from indoor-rated housings toward hermetically sealed alternatives.
- IP54:Dust-protected and splash-resistant enclosures serve indoor manufacturing environments with controlled atmospheric conditions. European machinery OEMs specify these for factory-floor control panels where washdown exposure remains minimal.
- IP65:Dust-tight and jet-water-resistant housings have become baseline for outdoor electrical infrastructure. Indian data center operators and Southeast Asian telecom providers require this rating for 24/7 uptime guarantees in tropical precipitation regimes.
- NEMA 4:Watertight and dust-tight standards govern North American outdoor installations including wastewater treatment plants and parking structure lighting controls.
- NEMA 12:Indoor dust-tight and drip-tight ratings persist in legacy manufacturing specifications where oil and coolant mist protection suffices.
IP65 specifications command the established base. The steepest expansion runs through NEMA 4X-grade corrosion-resistant variants.
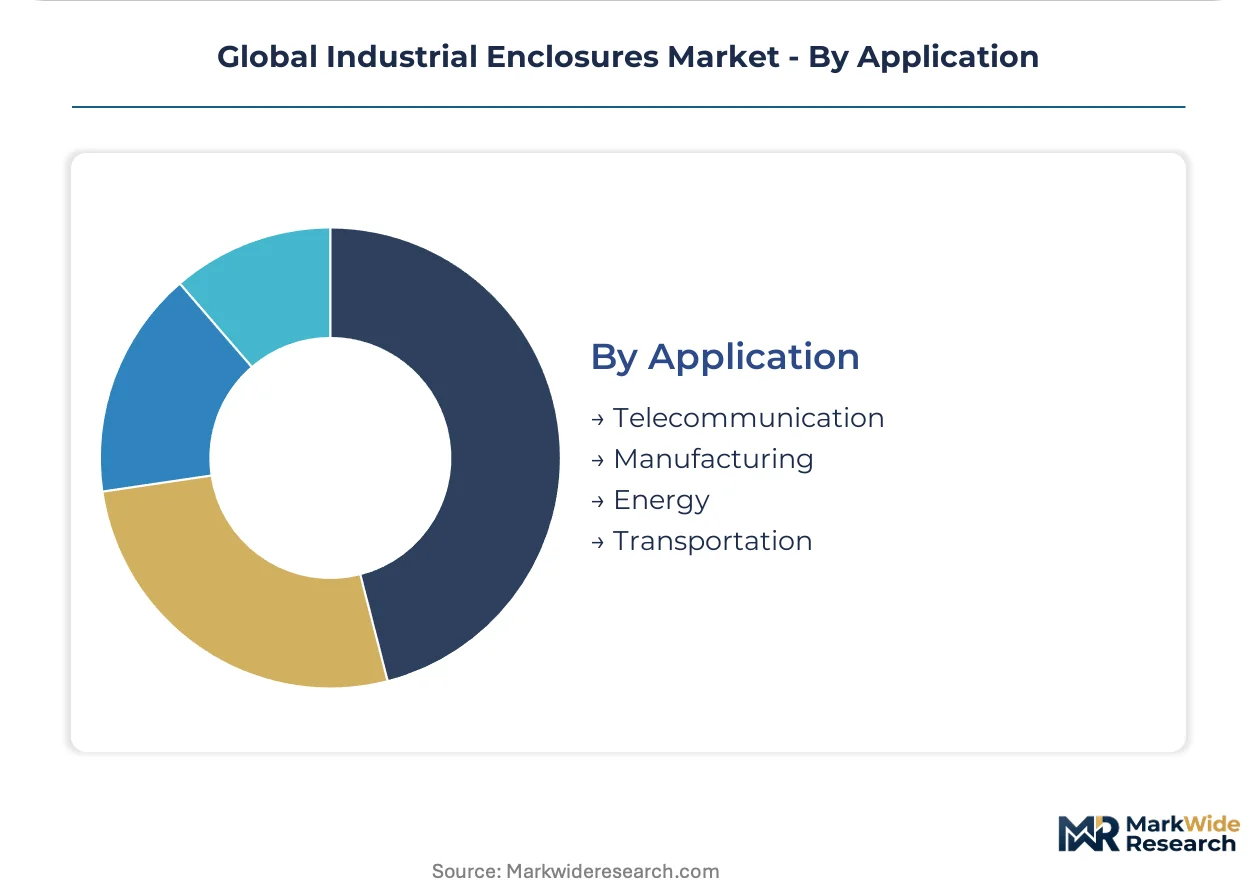
Application:
Customer-type concentration varies by sector maturity, with telecommunications and data center buildouts attracting specialized distributors while manufacturing and energy sectors favor bundled electrical package procurement.
- Telecommunication:5G small-cell densification and fiber backhaul expansion drive demand for compact, thermally managed pole-mounted housings. European mobile network operators deploy phase-change material cooling across Mediterranean markets to eliminate fan maintenance.
- Manufacturing:Brownfield automation retrofits and greenfield facility construction sustain demand for control system enclosures. German automotive and Chinese electronics producers specify wall-mounted units for PLC and HMI integration.
- Energy:Solar inverter housings and wind turbine nacelle enclosures face material substitution pressure as developers weigh aluminum price volatility against 25-year service life requirements.
- Transportation:Railway signaling and electric vehicle charging infrastructure specify vibration-resistant housings with extended temperature ranges from -40°C to +80°C.
Manufacturing commands the established base. The steepest expansion runs through telecommunication infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German enclosure manufacturers export stainless-steel housings to North Sea wind farm developers, while Chinese fabricators supply GB-certified cabinets to Southeast Asian data center operators. This trade-flow pattern concentrates specification authority in three manufacturing clusters.
United States
Hyperscale data center construction in Virginia and Texas drives demand for NEMA 4X-rated outdoor substation housings. EPA stormwater regulations and FERC interconnection standards mandate corrosion-resistant electrical infrastructure for coastal and flood-prone installations. Houston petrochemical corridors specify explosion-proof enclosures under OSHA Process Safety Management directives.
Germany
Automotive electrification and industrial automation sustain demand for IP65-rated control system housings. EU F-Gas Regulation phase-down accelerates hermetically sealed electrical enclosures for commercial cooling infrastructure. Bavarian manufacturing clusters around Munich and Nuremberg specify wall-mounted units for PLC integration in smart factory retrofits.
China
Dual carbon goals and renewable energy buildouts propel demand for 316-grade stainless enclosures in offshore wind installations. MIIT-mandated GB/T 4208-2017 harmonization with IEC 60529 streamlines CCC certification for foreign suppliers. Jiangsu and Zhejiang production clusters dominate domestic supply for GB-standard certified cabinets.
India
Hyperscale facility multiplication across Mumbai and Chennai requires IP65-rated outdoor switchgear housings for monsoon-exposed substations. BIS certification and CEA grid codes enforce localized testing protocols for electrical infrastructure. Telangana and Karnataka data center corridors specify rack-mount enclosures with integrated thermal management.
Indonesia
Colocation expansion outside Jakarta and Surabaya drives procurement of NEMA 3R walk-in enclosures for rapid-deployment edge facilities. Ministry of Communication and Informatics regulations mandate telecommunications infrastructure resilience standards. Batam and Surabaya industrial zones concentrate specification activity for modular data center penetration.
Global Industrial Enclosures Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and technical specification capabilities. The vendor base organizes around three tiers: multinational electrical conglomerates with distribution channel control, mid-cap fabricators with vertical production integration, and regional specialists serving localized certification requirements. Two dominant competitive moves define positioning: backward integration into steel and aluminum supply chains to compress input cost volatility, and strategic partnerships with EPC firms to secure placement on master equipment lists.
Among German-based fabricators, Rittal GmbH & Co. KG exemplifies the vertically integrated archetype with captive production of precision sheet metal housings. Eaton Corporation plc and ABB Ltd represent the multinational tier, leveraging broad electrical distribution networks to bundle enclosures with adjacent power management systems. These three anchors illustrate the competitive spectrum from specialized manufacturing depth to integrated solution portfolios.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton |
| Rittal |
| ROSE Systemtechnik |
| Hubbell |
| nVent HOFFMAN |
| ABB |
| Siemens |
| Hammond Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Captive sheet-metal capacity in Germany and China compresses unit economics for precision-fabricated enclosures, concentrating pricing power among vertically integrated fabricators while forcing smaller competitors toward commodity-grade carbon-steel offerings. This scale asymmetry shapes both supply concentration and price floors across protection-rated product tiers.
Pricing Analysis
Current-generation NEMA 4X stainless-steel enclosures command substantial premiums over legacy carbon-steel housings, while next-generation sensor-integrated smart enclosures are pricing at additional uplifts for predictive maintenance capability. Three-tier pricing structure across premium corrosion-resistant, standard IP65-rated, and economy indoor-grade tiers reflects certification complexity and material grade differentiation. Pricing pressure stems from aluminum LME volatility squeezing renewable energy project margins. Data center operators exhibit lowest price sensitivity due to uptime guarantee requirements, while municipal utilities face acute budget constraints.
Supply Chain Analysis
Inventory cycles for 316-grade stainless steel extend lead times beyond standard cold-rolled alternatives, forcing project planners to buffer specifications. Supply concentrates in Germany, China, and the United States for certified enclosure fabrication. Raw material dependencies center on cold-rolled steel, aluminum sheet, and polycarbonate resin. Single-source vulnerability in GB-standard certified Chinese production clusters creates exposure for Western EPCs. Distribution runs through electrical distributors bundling enclosures with switchgear and power management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial enclosures market is recovering from cyclical lows as hyperscale data center construction accelerates across India and Southeast Asia, driven by cloud migration and AI training infrastructure buildouts.
For Market Incumbents: Fortify specification authority by embedding thermal monitoring and predictive maintenance sensors directly into enclosure architectures, countering emerging digital-native competitors. Deepen backward integration into precision sheet-metal supply to compress input cost volatility from aluminum and steel markets. Prioritize CCC certification alignment under MIIT-mandated GB/T 4208-2017 harmonization to defend position in Chinese offshore wind procurement. For New Entrants and Emerging Players: Anchor in Indonesia's modular data center penetration outside Jakarta and Surabaya, where colocation providers seek rapid-deployment NEMA 3R walk-in enclosures with limited incumbent saturation. Target EU CSRD carbon disclosure compliance as a specification wedge, offering EPD-certified recycled-aluminum content that legacy fabricators lack. Pursue direct EPC relationships rather than distributor channels to bypass entrenched electrical conglomerate control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated mid-cap specialists with captive German or Japanese stainless-steel supply and established EPC master equipment list placement. Five-to-ten year viability favors fabricators with dual-certified product families spanning NEMA and IP rating systems. Monitor hyperscale data center construction permit approvals in Telangana and Karnataka as inflection indicators for rack-mount enclosure demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Sheet Metal | Captive supply of cold-rolled steel and aluminum compresses margin volatility from LME trading patterns. |
| Dual-Certification Portfolio Consolidation | GB/T 4208-2017 and IEC 60529 alignment streamlines CCC access for Chinese offshore wind developers. |
| Sensor-Embedded Smart Enclosure Launch | ABB and Eaton are embedding thermal monitoring to transform passive housings into predictive maintenance nodes. |
| EPD-Certified Recycled-Aluminum Supply Chain | EU CSRD carbon disclosure creates specification pull for verified sustainable content in German automotive clusters. |
| Direct EPC Partnership Development | Oil and gas majors in the Permian Basin delegate enclosure selection to third-party design firms bundling integrated electrical packages. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association publications. Primary interviews engaged plant engineers at German automotive manufacturers, procurement leads at Indian data center operators, EPC contractors specifying North Sea wind farm infrastructure, and aftermarket service heads at electrical distributors. Secondary validation drew from SEC 10-K disclosures of listed electrical conglomerates, BIS certification registries, MIIT GB standard documentation, and EU F-Gas Regulation implementation guidance. Bottom-up demand modeling triangulated against top-down market sizing from production capacity and trade flow analysis.
Segmentation dimensions modeled span product type, material grade, protection rating tier, and application vertical across the projection horizon. Analytical framework derived CAGRs from historical shipment trajectories, capacity expansion announcements, and specification trend analysis. Industry-specific forecast inputs incorporated hyperscale data center construction pipelines in India and Indonesia, EU refrigerant containment mandate timelines, and coastal wind farm developer material substitution patterns from carbon-steel to 316-grade stainless.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale facility construction, continued aluminum price volatility, and stable regulatory certification requirements; material deviation in any assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Fluid Dispensing Equipment Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Precision Machine Market