
 Electromechanical Relay Market | 2026-2036
Electromechanical Relay Market Size, Share, and Industry Trends Forecast 2026-2036
Electromechanical Relay Market Analysis
The EU Green Deal is expanding compliance obligations for energy-efficient switching components across European industrial supply chains. Panasonic leverages its vertical integration in contact materials to sustain cost leadership in high-cycle relay production. Siemens anchors its position through IEC-certified product lines that dominate European rail and building automation procurement.
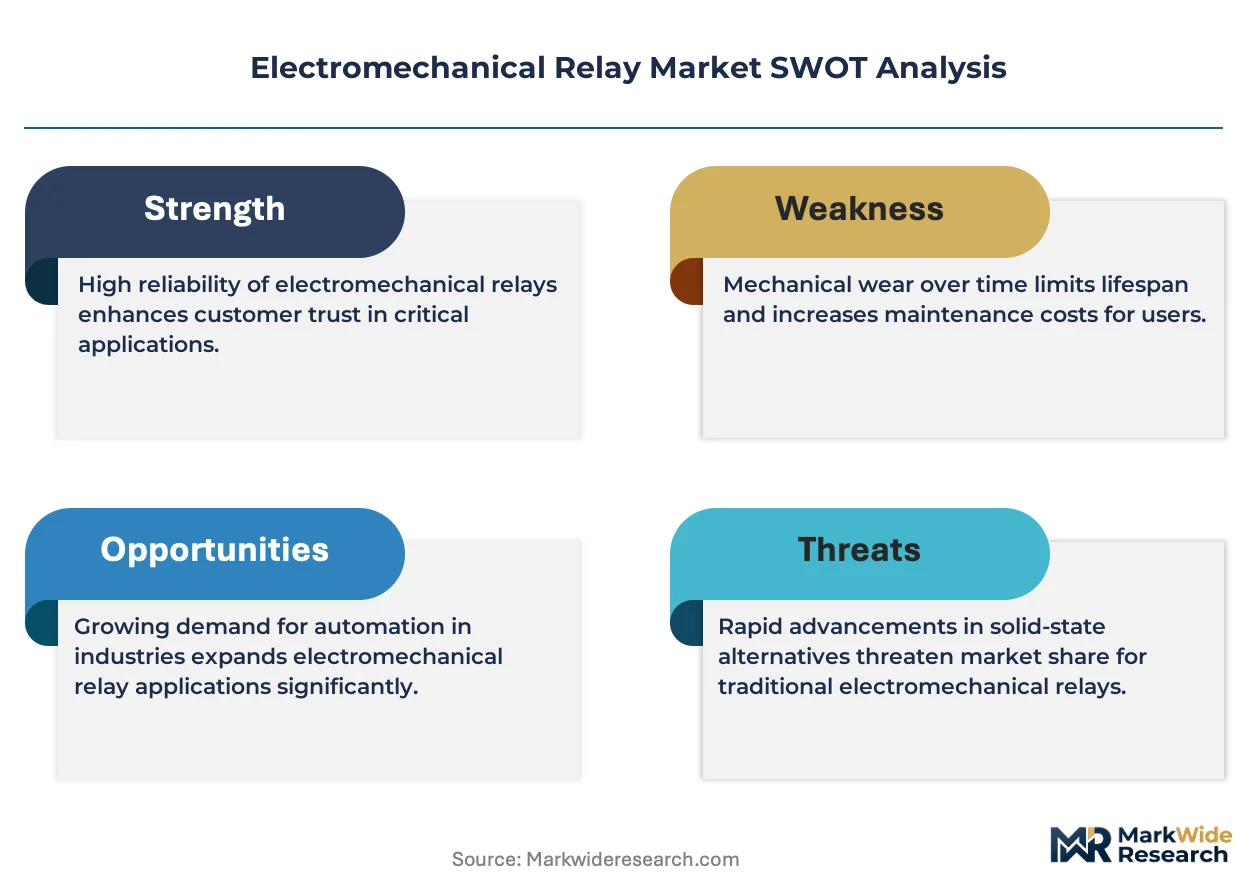
An electromechanical relay is a switch operated by an electromagnetic coil, typically rated for currents from milliamps to hundreds of amps, using silver-nickel or silver-cadmium oxide contacts to complete or interrupt circuits under load. Its primary purpose is to enable low-power control signals to isolate and switch higher-power circuits in industrial and transportation systems. Power relays occupy the largest value share due to their deployment in heavy-load energy infrastructure, while automotive relays represent the fastest-expanding segment as vehicle electrification multiplies switching points per platform. Signal relays command premium margins in telecommunications base stations where contact reliability determines network uptime.
IEC standards, UL certifications, and China's GB standards collectively define product access rules across the three largest manufacturing blocs. The EU's F-Gas Regulation and REACH compliance further constrain material choices for contact plating and coil insulation in exports to Europe. Stakeholders must monitor evolving efficiency mandates and regional certification divergence when allocating R&D and production capacity across supply chain nodes.
Market Dynamics
Automotive electrification is multiplying switching points per vehicle platform, forcing relay manufacturers to recalibrate contact material specifications and thermal management architectures for high-voltage DC circuits.
Growth Catalysts
- EV Power Management:Battery electric vehicles require 40-80 relays per platform for charging, thermal management, and power distribution, creating sustained pull from automotive OEMs.
- IEC 61810 Harmonization:Tightening international performance benchmarks for electromechanical relays is accelerating replacement cycles in industrial automation and rail infrastructure.
- China's Industrial Clustering:Concentrated automotive and automation manufacturing in the Yangtze River Delta and Pearl River Delta generates localized demand density for high-cycle relay production.
Market Restraints
- Silver Price Volatility:Contact materials incorporating silver-nickel and silver-cadmium oxide face input cost pressure from precious metal commodity swings.
- Semiconductor Relay Substitution:Solid-state relays are capturing switching applications below 100A where thermal management and cycle life requirements permit silicon-based alternatives.
- REACH Compliance Friction:EU restrictions on cadmium, lead, and certain insulation materials constrain contact plating options and coil encapsulation chemistries for European-bound production.
Strategic Opportunities
- India Manufacturing Incentives:PLI scheme allocations for automotive components and industrial automation equipment are drawing relay assembly capacity toward Gujarat and Tamil Nadu industrial corridors.
- Grid-Scale Energy Storage:Battery energy storage systems for utility-scale solar and wind integration require high-ampacity DC switching at 1500V, opening new performance tiers.
- Rail Electrification Mandates:European and Chinese commitments to railway network expansion are generating procurement volumes for signaling and traction power relays with 30-year service life requirements.
Industry Challenges
- Contact Material Engineering Talent:Scarce expertise in arc-quenching alloy formulation and wear-rate modeling constrains R&D throughput for next-generation high-voltage designs.
- Multi-Certification Parallel Tracks:Simultaneous pursuit of IEC, UL, and GB approvals for global product launches extends time-to-revenue by 8-14 months.
- Legacy System Integration:Retrofit deployments in existing industrial control systems require mechanical and electrical compatibility with 20-30 year-old relay footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromechanical Relay Market |
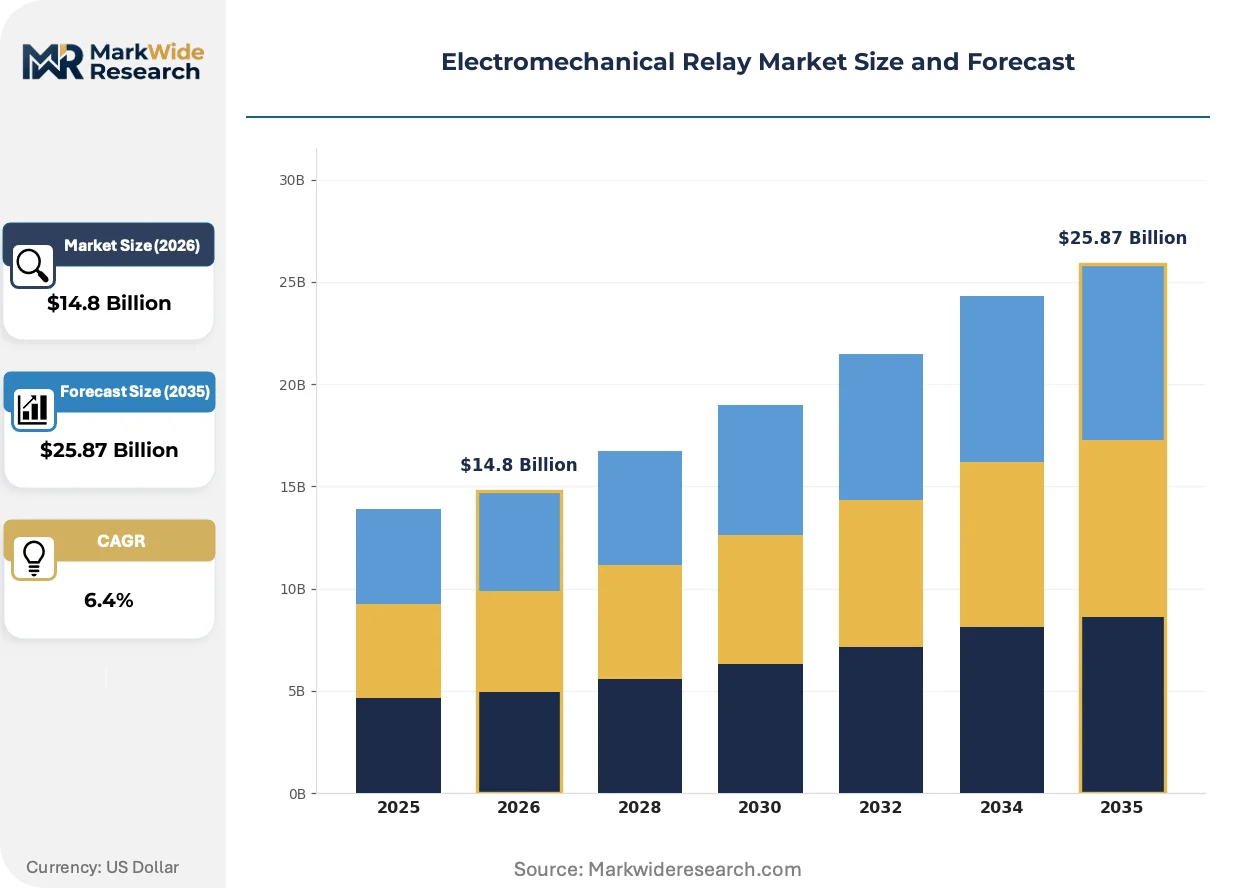
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Relay, Power Relay, Signal Relay, Automotive Relay Technology: Electromagnetic, Solid State, Hybrid, Bimetallic End User: Automotive, Industrial Equipment, Telecommunications, Home Appliances Application: Control Systems, Power Distribution, Safety Devices, Automation |
| Companies Covered | Panasonic, Schneider Electric, HONGFA, ABB, Zettler Group, Omron, Siemens, Fuji Electric, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromechanical Relay Market Emerging Trajectories
Contact material science and coil optimization are converging to extend electromechanical relay service intervals in high-cycle applications, compressing total cost of ownership calculations against solid-state alternatives.
Silver-tin oxide and silver-nickel composite contact materials are overtaking traditional silver-cadmium oxide formulations in automotive and industrial power relays. Tier-1 suppliers are qualifying these alloys for 10 million mechanical operations at 400A interrupt capacity. The shift is overtaking incumbent material specifications in procurement tenders for electric vehicle platforms and renewable energy inverters.
REACH and the EU F-Gas Regulation are tightening material disclosure requirements for contact plating and coil insulation systems exported to Europe. Manufacturers must document substance composition down to 0.1% weight thresholds and secure SCIP database entries for complex articles. Automotive and building automation OEMs with European assembly operations are now requiring full material transparency as a qualification gate.
Consolidated procurement by automotive OEMs and utility-scale EPC contractors is compressing supplier bases and extending contract durations. Tier-1 relay manufacturers are securing 5-7 year supply agreements with volume commitments and joint development clauses for platform-specific designs. This concentration is most visible in Germany's automotive supply chain and China's state-grid procurement for transmission infrastructure.
Electromechanical Relay Market Segmentation
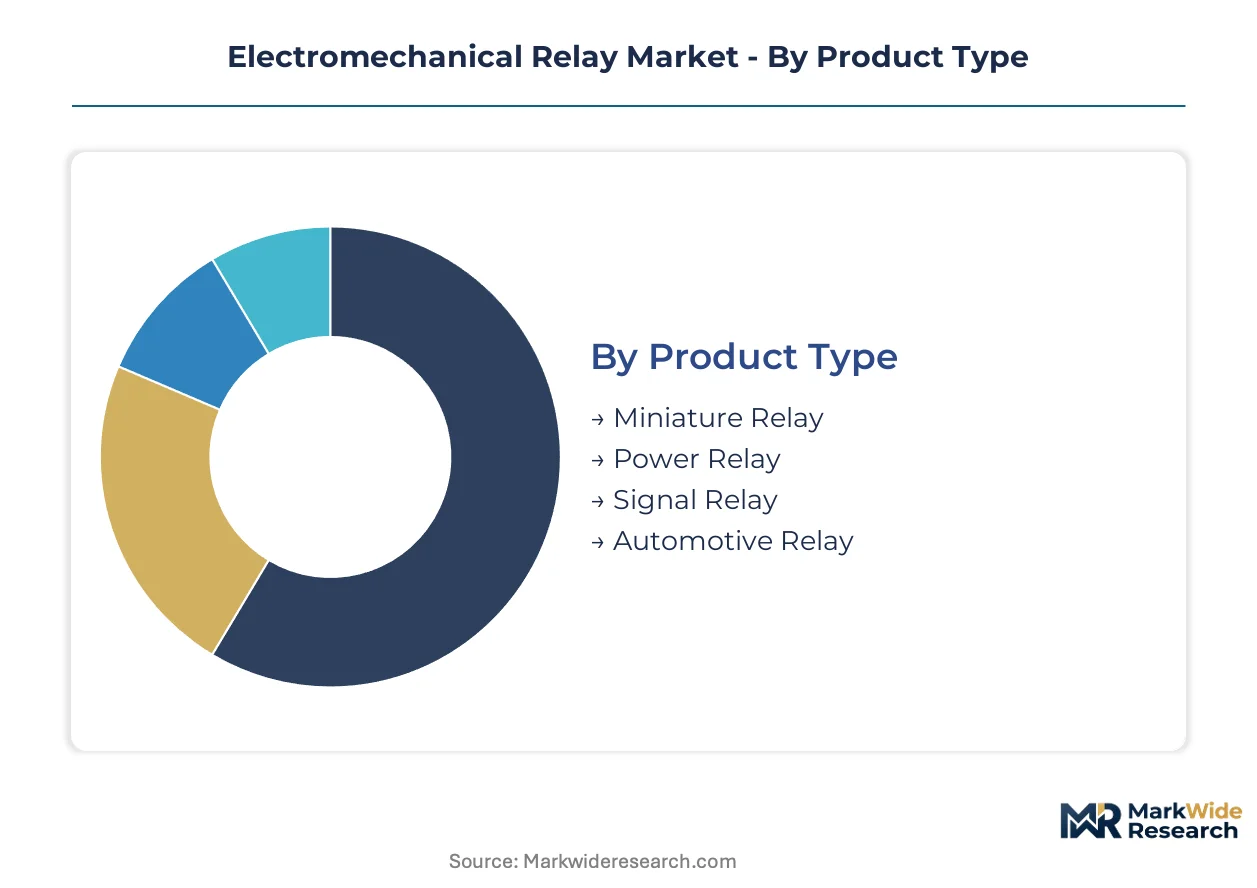
Electromechanical relay segmentation reveals divergent performance requirements across voltage classes and duty cycles. Product architecture and end-use specifications determine material selection, certification pathways, and manufacturing scale.
Product Type:
Contact rating and physical envelope dimensions define the competitive terrain across relay categories.
- Power Relay:Heavy-duty switching devices rated for 10A to 100A+ interrupt capacity, deploying silver-nickel or silver-tin oxide contacts in welded hermetic enclosures. Demand concentrates in China's state-grid transmission infrastructure and Germany's industrial automation retrofit programs, driven by 1500V DC solar inverter integration and railway traction power requirements.
- Automotive Relay:Compact 12V-48V switching modules engineered for 100,000+ electrical cycles under hood-temperature thermal stress. Platform electrification across Tesla's Austin assembly operations and BYD's Shenzhen manufacturing complex multiplies switching points per battery electric vehicle to 40-80 units, forcing contact material recalibration for high-voltage DC circuits.
- Miniature Relay:Sub-5A signal switching in PCB-mount packages for consumer electronics and building automation controllers.
- Signal Relay:Low-level switching below 2A with gold-plated contacts for telecommunications base station redundancy and test equipment signal routing.
Power Relay leads on scale; Automotive Relay leads on momentum.
Technology:
Actuation mechanism determines thermal performance, electrical isolation, and lifecycle economics across switching applications.
- Electromagnetic:Coil-driven armature mechanisms using copper windings and ferromagnetic cores to achieve mechanical contact closure, dominating applications above 10A where arc-quenching and galvanic isolation remain critical. Procurement volumes from India's Tamil Nadu automotive corridor and Japan's METI-funded railway electrification projects sustain manufacturing scale despite solid-state encroachment at lower amperages.
- Solid State:Silicon-controlled rectifier and triac-based switching with zero-crossing detection, eliminating mechanical wear and enabling silent operation. Data center UPS systems and semiconductor fabrication equipment in South Korea's Gyeonggi Province and Arizona's Phoenix metro area drive qualification programs for 100A+ thyristor modules.
- Hybrid:Electromechanical contact pairs paralleled with MOSFET snubbing circuits to combine low on-resistance with arc suppression.
- Bimetallic:Thermal actuation through differential expansion of bonded metal strips for overcurrent protection in motor control and HVAC compressor applications.
Electromagnetic technology anchors installed base economics; Solid State technology gains share fastest in sub-100A precision switching.
End User:
Customer verticals impose distinct reliability specifications, volume profiles, and certification requirements.
- Automotive:OEM-directed qualification protocols spanning AEC-Q200 stress testing and ISO 26262 functional safety for powertrain and body electronics modules. Tier-1 supplier consolidation around Bosch, Denso, and Panasonic has compressed qualified vendor lists to 8-12 global relay manufacturers with captive testing laboratories.
- Industrial Equipment:PLC integration and motor starter applications requiring IEC 60947 conformity and 10 million mechanical cycle endurance. Germany's Ruhr industrial belt and China's Pearl River Delta factory automation retrofits generate replacement demand for 24V control relays in legacy Siemens and Mitsubishi systems.
- Telecommunications:Base station redundancy switching and central office power distribution with 20-year service life specifications.
- Home Appliances:Cost-optimized 10A switching for refrigerator compressors, washing machine motors, and HVAC contactors in white goods manufacturing clusters.
Industrial Equipment leads on replacement volume; Automotive leads on specification intensity.
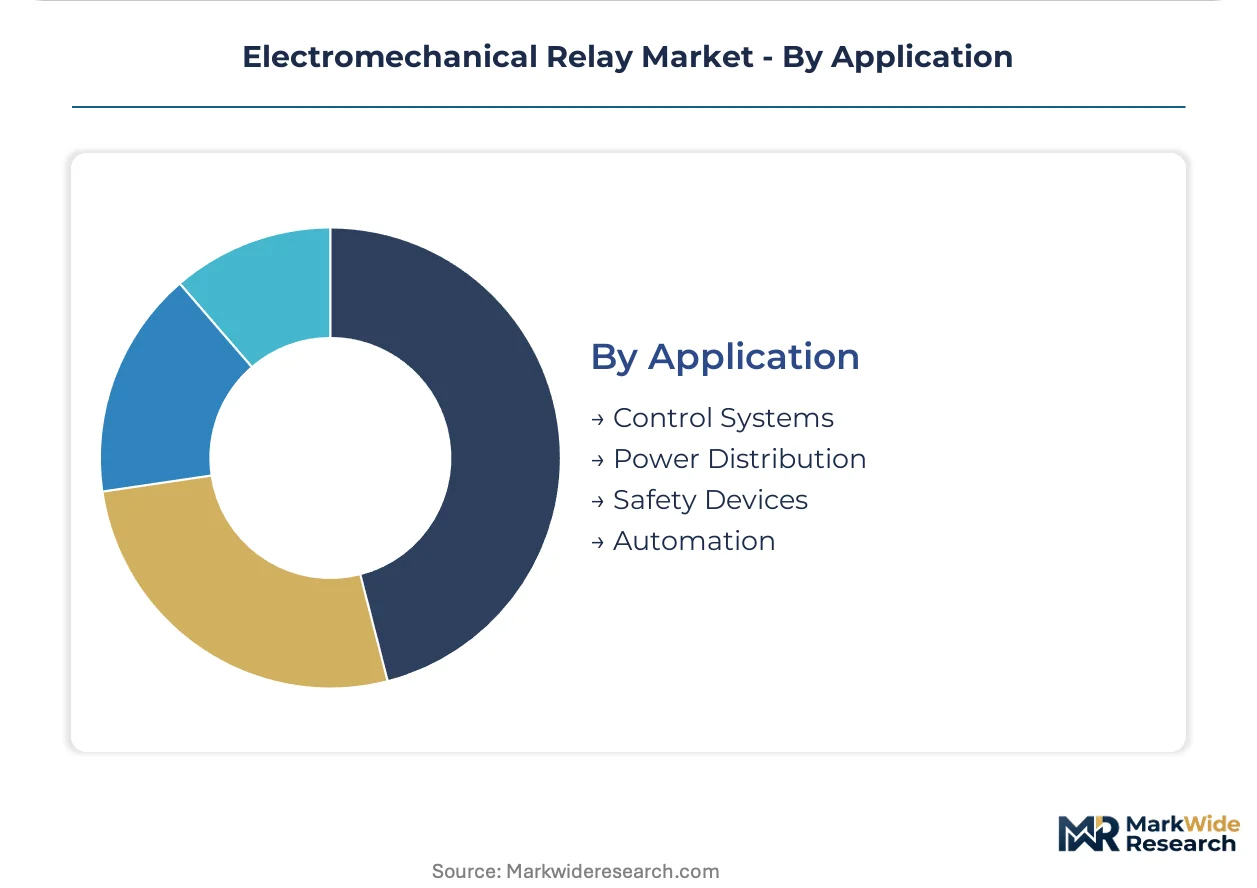
Application:
Functional deployment context determines contact material, coil voltage, and enclosure sealing requirements.
- Power Distribution:High-ampacity switching in solar string inverters, battery energy storage systems, and electric vehicle charging infrastructure. Utility-scale EPC contractors in Texas ERCOT territory and China's Qinghai Province solar bases specify 1500V DC rated relays with 10,000+ electrical cycle endurance for 20-year project financing terms.
- Automation:Discrete manufacturing control systems integrating relay logic with programmable controllers for conveyor sequencing and robotic workcell safety interlocks. Japanese automotive transplants in Kentucky and Tennessee and German-owned suppliers in Mexico's Bajío region sustain demand for 24V DC miniature relays in lean production layouts.
- Control Systems:Process industry signal routing and alarm annunciation in petrochemical and water treatment facilities.
- Safety Devices:Emergency stop circuits and fire suppression system activation requiring force-guided contact configurations and redundant contact pairs.
Power Distribution leads on amperage scaling; Automation leads on unit volume density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electromechanical relay industry traces its industrial-scale origins to German engineering conglomerates that standardized electromagnetic switching for railway and factory automation in the early twentieth century.
China
Domestic automotive electrification and state-grid transmission buildouts absorb the highest relay volumes globally. GB standards and MIIT industrial policy enforce local content requirements for critical infrastructure switching components. The Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate production capacity for both domestic consumption and export assembly.
Germany
Railway electrification mandates and industrial automation retrofits sustain premium-grade relay procurement. The EU Green Deal and REACH compliance frameworks constrain material choices for contact plating and coil insulation. The Ruhr industrial belt and Bavarian automation corridors host qualification laboratories serving European OEM supply chains.
United States
Utility-scale solar and battery energy storage deployments drive high-voltage DC switching demand. FERC grid interconnection standards and state-level renewable portfolio requirements shape procurement specifications. Texas ERCOT territory and Arizona's Phoenix metro area concentrate EPC contractor activity for 1500V-rated power distribution relays.
Japan
METI-funded railway modernization and automotive transplant supply chains anchor high-cycle relay consumption. JIS standards and domestic certification protocols maintain technical barriers for imported alternatives. The Kanto region around Tokyo and Chubu industrial zone near Nagoya host integrated manufacturing for contact material and coil winding operations.
India
Automotive component PLI incentives and industrial automation equipment subsidies are drawing assembly capacity toward domestic manufacturing. BIS certification requirements and CEA electrical safety regulations govern product access. The Tamil Nadu automotive corridor and Gujarat industrial zones are emerging as relay qualification hubs for export-oriented production.
Electromechanical Relay Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity and contact material engineering depth. The vendor base separates into three functional tiers: integrated materials specialists with captive contact alloy production, scale-focused assemblers serving high-volume automotive programs, and regional fabricators competing on delivery speed for replacement markets. Dominant competitive moves include backward integration into silver-nickel contact material supply and simultaneous multi-certification tracks for IEC, UL, and GB approvals.
Within the integrated materials tier, Panasonic and HONGFA occupy positions exemplifying vertical control over contact science and high-cycle production economics. Siemens anchors the European premium segment through IEC-certified product lines that dominate rail and building automation procurement. TE Connectivity represents the scale-driven archetype, leveraging global distribution infrastructure to serve utility-scale EPC contractors across multiple voltage classes.
| Leading Market Players |
|---|
| Panasonic |
| Schneider Electric |
| HONGFA |
| ABB |
| Zettler Group |
| Omron |
| Siemens |
| Fuji Electric |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between IEC 61810-compliant premium tiers and commodity-grade unbranded alternatives manifests in pricing spreads exceeding 3x for equivalent ampacity ratings, while simultaneously driving supply chain fragmentation between captive contact-material operations serving automotive OEMs and outsourced assembly networks feeding replacement markets in Southeast Asia.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement frameworks, with differentiation anchored in UL/IEC certification tier and silver-nickel contact purity grade. Cost compression in economy-tier PCB-mount relays is intensifying because Chinese domestic brands are flooding Southeast Asian distribution channels. Automotive OEMs exhibit lowest price sensitivity due to platform-qualification lock-in, while industrial maintenance buyers in India's secondary cities drive aggressive spot-market negotiation.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian wire-drawing facilities supplying copper magnet wire to Japan's Kanto relay manufacturers. Raw material procurement draws from Chilean silver concentrates, Indonesian nickel matte, and German ferromagnetic core stampings. Tariff exposure on Chinese-manufactured hermetic enclosures threatens margin stability for European-bound production. Distribution runs through authorized distributor networks serving OEM qualification programs alongside gray-market channels supplying unbranded replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electromechanical relay market functions as a stable compounder, with automotive electrification generating irreversible platform-specification pull that sustains replacement-cycle economics across multiple decades.
For Market Incumbents: Lock in multi-year supply agreements with BYD and Tesla that embed joint-development clauses for 800V DC platform designs, while accelerating backward integration into silver-tin oxide contact casting to offset precious metal volatility. Solid-state relay substitution below 100A amperage represents the primary technology threat requiring defensive patent positioning. For New Entrants and Emerging Players: Begin with India's Tamil Nadu automotive corridor, where PLI scheme subsidies and BIS certification gaps create qualification windows for 48V mild-hybrid relay supply. Grid-scale battery energy storage systems for Texas ERCOT utility contractors offer the most penetrable application segment, with EPC procurement teams actively seeking second-source validation for 1500V DC switching. For Investors and Strategic Acquirers: Consolidation pressure builds where contact-material engineering talent scarcity constrains R&D throughput for next-generation arc-quenching alloys. Five-to-ten-year viability hinges on exposure to electrification-exposed automotive platforms versus legacy industrial replacement markets. The signal to monitor is qualification velocity at Chinese state-grid procurement tenders, where domestic manufacturer preference policies may abruptly reshape competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Alloys | Captive silver-tin oxide production insulates Panasonic and HONGFA from London Metal Exchange volatility. |
| Multi-Certification Parallel Tracks | Simultaneous IEC, UL, and GB approvals compress time-to-revenue for automotive platform launches. |
| Joint Development Agreements | Tier-1 supplier consolidation around Bosch and Denso demands embedded R&D collaboration clauses. |
| Regional Manufacturing Footprint | Gujarat and Tamil Nadu assembly capacity captures PLI incentives for export-oriented automotive supply. |
| REACH Compliance Program | Full material transparency documentation secures qualification gates for European-bound production. |
Methodological Framework
Multiple input streams — primary interviews with Tier-1 supplier procurement directors, relay manufacturer R&D heads, and automotive platform engineers — were reconciled against secondary validation from IEC certification databases, customs trade records, and SEC filings from publicly traded component suppliers. Bottom-up production volume estimates from China's Yangtze River Delta manufacturing clusters were triangulated with top-down demand modeling from vehicle production databases and state-grid transmission investment disclosures.
Historical shipment patterns were cross-referenced against panel input from industry participants to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include contact rating tier, actuation technology, end-use vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive electrification content-per-vehicle trajectories and utility-scale solar deployment pipelines.
Several conditions sit outside the modeled scope, including abrupt semiconductor relay technology breakthroughs, geopolitical trade restrictions on silver concentrate flows, and retroactive REACH substance bans. Forecasts reflect documented assumptions about certification timeline stability and automotive platform lifecycle continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
USB Charger Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Global Suction Tube Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Safety Relay Market
Electronic Components
Radiation Hardened Electronics Market
Electronic Components
Power Resistor Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Discrete Capacitors Market
Electronic Components
Data Bus Market
Electronic Components
Audio DSP Market
Electronic Components
Intel Motherboards Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Fuel Pump Driver Module Market