
 Europe PCB Market | 2026-2036
Europe PCB Market Size, Share, and Industry Trends Forecast 2026-2036
Europe PCB Market Analysis
Direct procurement from large EMS providers is tilting toward specialized PCB fabricators with captive substrate capabilities. AT&S AG leverages its Austrian manufacturing base to dominate high-density interconnect supply for automotive Tier-1s. Würth Elektronik anchors the German industrial mid-market through vertically integrated laminate-to-board production. Schweizer Electronic AG specializes in embedding power semiconductors, a niche where few European competitors sustain comparable R&D intensity.
A printed circuit board is a laminated sandwich structure of conductive copper layers and insulating substrate, typically fabricated through photolithographic etching, drilling, and electroplating processes, designed to mechanically support and electrically connect electronic components. Multilayer boards command the deepest margin pools in European production, driven by telecommunications infrastructure and medical imaging equipment requirements. Flexible circuit technology is displacing rigid alternatives in aerospace cable harnesses, where weight reduction and spatial conformity justify premium unit economics. Surface mount technology dominates assembly flows across consumer electronics and smart home device manufacturing, though through-hole methods persist in industrial equipment where mechanical joint reliability outweighs density gains.
REACH compliance through ECHA and the EU Green Deal's embodied carbon thresholds are forcing substrate suppliers to reformulate halogen-free resins and document supply chain provenance. CE marking under the EU's Radio Equipment Directive shapes market access for boards integrating RF modules in telecommunications and automotive radar applications. Stakeholders must monitor how the EU AI Act's hardware transparency requirements will reshape documentation burdens for PCB suppliers serving medical device and gaming segments.
Market Dynamics
Automotive electrification is compressing PCB qualification cycles across European Tier-1 supply chains, forcing fabricators to synchronize substrate development with power module roadmaps.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Substrate suppliers reformulating halogen-free resins gain preferential access to German automotive OEM procurement panels.
- Medical imaging equipment:Multilayer board demand from precision manufacturing clusters in southern Germany accelerates as diagnostic device OEMs onshore production.
- France:Aerospace cable harness contracts are pivoting toward flexible circuit technology to achieve weight reduction targets in next-generation aircraft programs.
Market Restraints
- Copper and resin input cost volatility:laminate suppliers face margin compression when commodity spikes coincide with fixed-price automotive contracts.
- High-density interconnect capability concentration:Austrian and German fabricators control advanced production, creating supply risk for Tier-1s requiring rapid scale-up.
- REACH chemical compliance timelines:ECHA substance evaluation delays force reformulation cycles that extend new product introduction by 12-18 months.
Strategic Opportunities
- Eastern European manufacturing expansion:Greenfield substrate facilities in Poland and Czechia can serve German industrial demand with lower logistics exposure.
- Embedded power semiconductor technology:Fabricators mastering chip embedding capture value from electrification trends in traction inverters and onboard chargers.
- EU AI Act hardware transparency mandates:PCB suppliers documenting supply chain provenance for medical device and gaming segments gain certification premiums.
Industry Challenges
- Photolithography and electroplating specialist scarcity:German industrial regions face recruitment gaps for precision process engineers as fabs expand capacity.
- CE marking under Radio Equipment Directive:RF-integrated boards for automotive radar require extended testing protocols that delay revenue recognition.
- Legacy through-hole assembly integration:Industrial equipment OEMs demand hybrid board designs that complicate surface-mount production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe PCB Market |
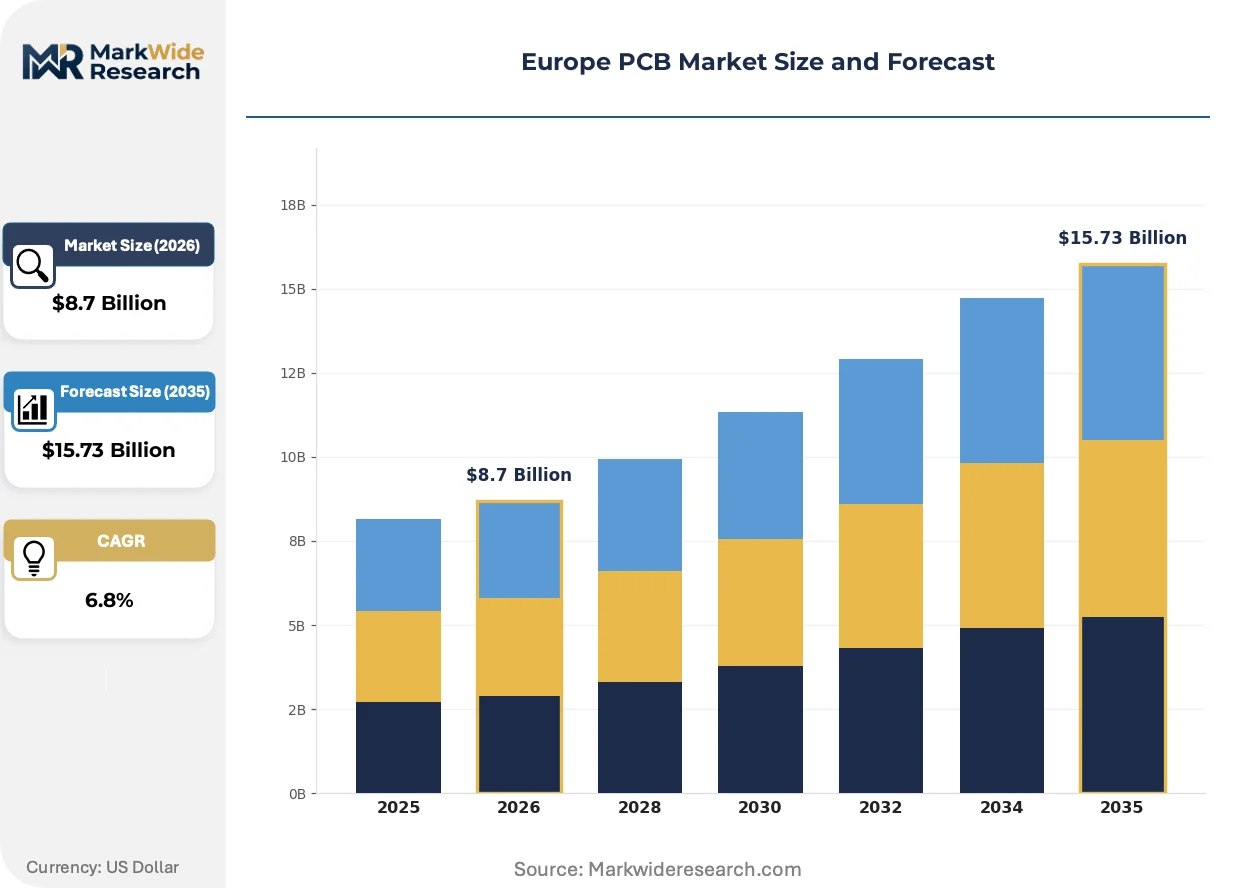
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Multilayer, Rigid Technology: Surface Mount Technology, Through-Hole Technology, Mixed Technology, Flexible End User: Consumer Electronics, Automotive, Aerospace, Industrial Equipment Application: Telecommunications, Medical Devices, Smart Home, Gaming |
| Companies Covered | AT&S AG, Würth Elektronik, Schweizer Electronic AG, Elvia PCB, NCAB Group, Cicor Group, Trackwise Designs, Unimicron Germany, KSG GmbH & Co, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe PCB Market Emerging Trajectories
European PCB manufacturing is pivoting from commodity volume toward engineered substrates that satisfy concurrent regulatory, thermal, and reliability specifications.
Flexible circuit technology is rendering obsolete rigid board architectures in aerospace cable harness applications. Airbus and Safran suppliers are qualifying polyimide-based flexible circuits at accelerated pace. This transition is rendering obsolete traditional wire-to-board connector assemblies that added weight and assembly labor.
REACH through ECHA is tightening substance restrictions on halogenated flame retardants in laminate formulations. Substrate suppliers must now document full material provenance to maintain German automotive qualification status. Medical device PCB fabricators face the steepest compliance burden as MDR and REACH overlap in biocompatibility documentation.
Direct engagement between automotive OEMs and specialized fabricators is collapsing traditional EMS intermediary layers. Tier-1 powertrain suppliers now mandate substrate co-development agreements that bypass standard component distribution channels. This pattern is most visible in Germany's industrial corridor where captive supply relationships dominate electrification programs.
Europe PCB Market Segmentation
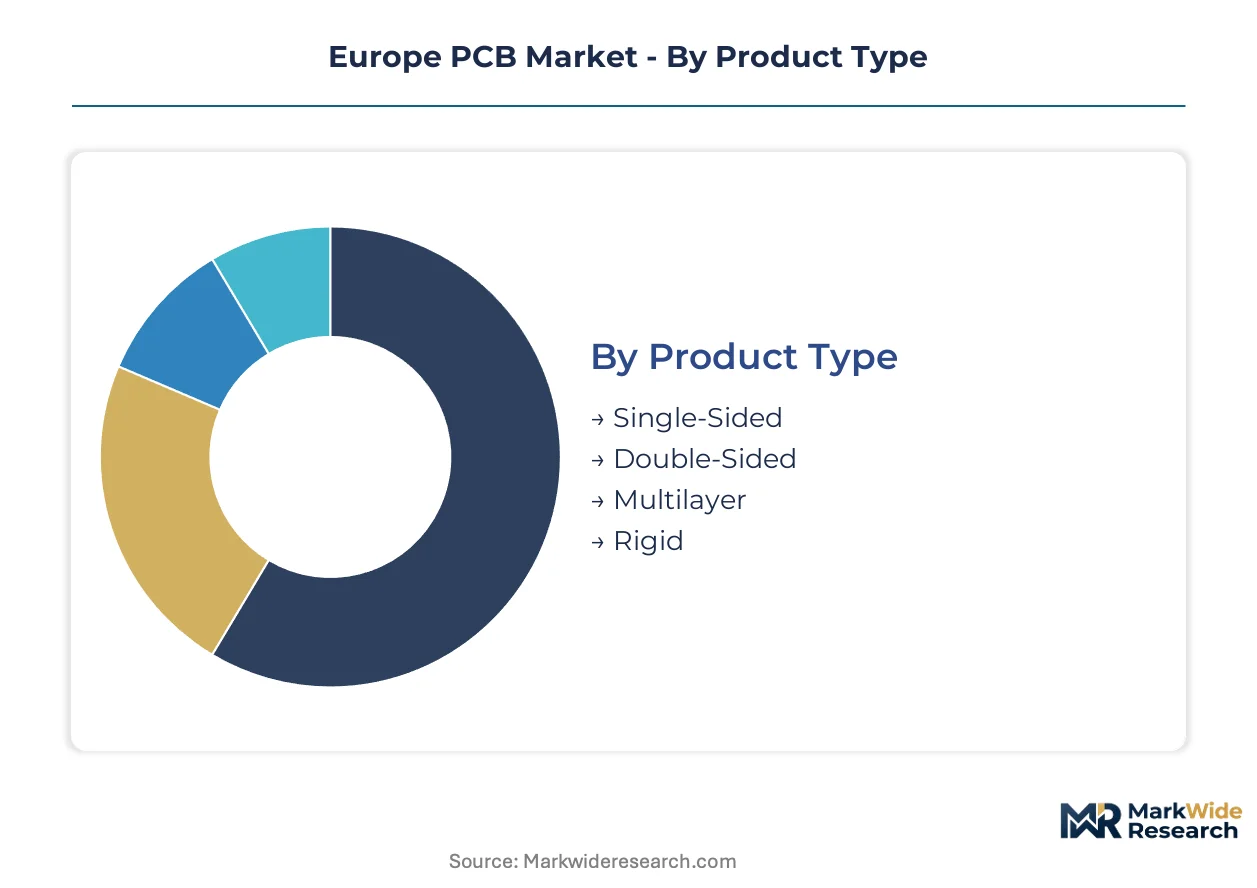
PCB segmentation in Europe reflects divergent qualification timelines across automotive, medical, and aerospace supply chains. Fabricators must align substrate development cycles with end-user certification requirements that range from months to years.
Product Type:
Single-sided boards turn inventory fastest while multilayer qualification cycles stretch across automotive powertrain development timelines.
- Single-Sided:Copper traces etched on one substrate surface serve cost-sensitive industrial sensors and basic consumer electronics. German mid-tier EMS providers source these for appliance control modules where functional density requirements remain minimal.
- Double-Sided:Conductive layers on both surfaces connected by plated through-holes expand routing flexibility for automotive body electronics. French Tier-1s specify these for climate control and lighting modules where moderate complexity meets strict cost targets.
- Multilayer:Laminated stacks of conductive and insulating layers enable high-density interconnect for medical imaging and telecommunications infrastructure. Southern German precision clusters dominate European production of these margin-rich boards.
- Rigid:Standard fiberglass-reinforced epoxy constructions persist in industrial equipment where mechanical stability outweighs flexibility requirements.
Multilayer boards anchor the volume base while flexible alternatives gain share at the steepest rate in aerospace cable harness applications.
Technology:
Assembly method selection tracks the tension between density demands and mechanical reliability requirements across European end-use segments.
- Surface Mount Technology:Automated placement of components directly onto board surfaces dominates consumer electronics and smart home device manufacturing. German automotive suppliers deploy SMT for infotainment modules where space constraints are severe.
- Through-Hole Technology:Component leads inserted through drilled holes and soldered on opposite sides persist in industrial power equipment. Czech and Polish fabricators maintain through-hole lines for heavy machinery OEMs requiring joint mechanical integrity under vibration.
- Mixed Technology:Hybrid assemblies combining surface-mount and through-hole methods serve industrial automation controllers. French and Italian equipment manufacturers specify these for motor drives where high-current components need mechanical anchoring alongside dense signal processing.
- Flexible:Polyimide-based circuits conform to irregular geometries in aerospace and medical devices. Airbus suppliers in France and Safran partners across the region are qualifying these for next-generation aircraft weight reduction programs.
Surface mount technology captures the highest assembly volume while flexible circuits expand most quickly in aerospace applications.
End User:
Customer concentration varies sharply, with automotive procurement panels consolidating supplier bases while aerospace maintains fragmented qualification lists.
- Consumer Electronics:High-volume, short-lifecycle products drive demand for cost-optimized double-sided and multilayer boards. Eastern European EMS hubs in Romania and Hungary source these for smartphone and tablet assembly.
- Automotive:Electrification programs across German and French OEMs are compressing PCB qualification cycles. Tier-1 powertrain suppliers now mandate substrate co-development agreements that bypass traditional distribution channels.
- Aerospace:Stringent reliability standards and extended certification timelines characterize demand from Airbus and Safran supply chains. Flexible circuit adoption is accelerating as weight reduction targets override historical cost sensitivities.
- Industrial Equipment:Hybrid technology boards serve motor controls and automation systems where mechanical joint reliability outweighs density optimization. German industrial corridor fabricators anchor supply relationships in this segment.
Automotive electrification anchors the volume base while aerospace flexible circuits climb the fastest as platform refresh cycles accelerate.
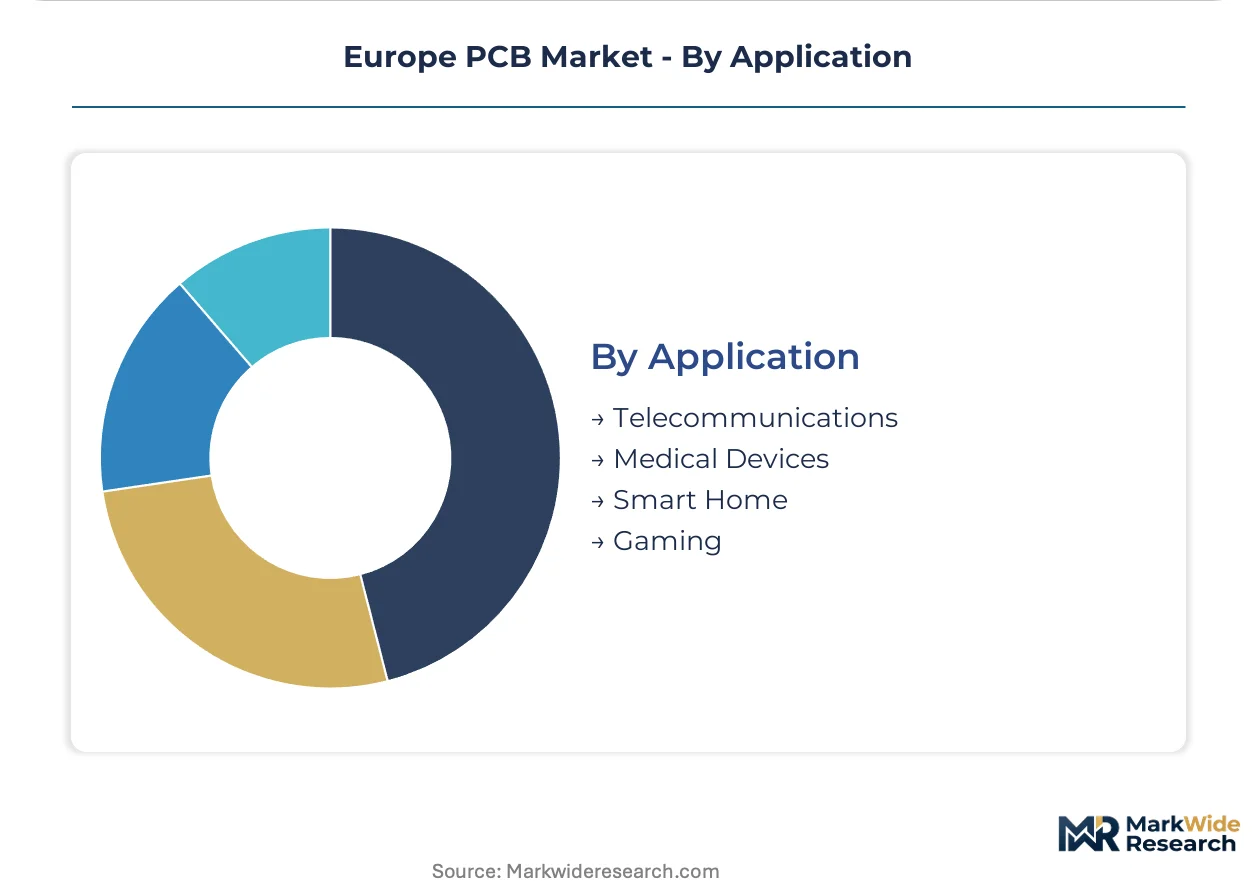
Application:
Application-specific requirements fragment demand across regulatory regimes, with medical and telecommunications imposing distinct compliance burdens on substrate suppliers.
- Telecommunications:Multilayer boards with controlled impedance support 5G infrastructure and data center switching equipment. CE marking under the EU Radio Equipment Directive shapes market access for RF-integrated designs.
- Medical Devices:MDR and REACH overlap creates the steepest documentation burden for PCB fabricators. Diagnostic imaging OEMs in southern Germany are onshoring production, driving multilayer demand from regional precision manufacturing clusters.
- Smart Home:Cost-optimized surface-mount assemblies serve connected appliance and security device manufacturers. Polish and Czechia facilities capture volume production for this price-sensitive segment.
- Gaming:High-performance computing boards face emerging hardware transparency requirements under the EU AI Act. Suppliers documenting supply chain provenance gain certification premiums in this evolving regulatory environment.
Telecommunications infrastructure anchors the volume base while medical devices gain share fastest as diagnostic OEMs onshore European production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's PCB logistics efficiency, connecting Bavarian fabrication clusters to North Sea ports and Black Sea manufacturing zones.
Germany
Automotive electrification programs at BMW and Volkswagen compress substrate qualification cycles for powertrain Tier-1s. REACH through ECHA mandates halogen-free resin documentation for laminate suppliers serving KBA-certified vehicle programs. The industrial corridor spanning Bavaria and Baden-Württemberg hosts precision manufacturing clusters where multilayer board fabricators supply diagnostic imaging OEMs.
France
Airbus and Safran supply chains accelerate flexible circuit qualification for next-generation aircraft weight reduction targets. CE marking under the EU Radio Equipment Directive shapes market access for RF-integrated boards in automotive radar applications. The Île-de-France and Occitanie aerospace clusters concentrate polyimide-based circuit development for cable harness replacement programs.
Austria
High-density interconnect capability concentrates around Leoben and Vienna for automotive Tier-1 supply. The EU Green Deal's embodied carbon thresholds drive substrate suppliers toward documented supply chain provenance. AT&S AG anchors captive substrate production serving German OEM electrification roadmaps with synchronized development cycles.
Poland
Eastern European manufacturing expansion captures cost-optimized consumer electronics assembly flows from Romanian and Hungarian EMS hubs. ECHA compliance documentation requirements extend reformulation timelines for halogen-free laminate introductions. The Silesian and Greater Poland voivodeships attract greenfield substrate facilities targeting German industrial demand with reduced logistics exposure.
Switzerland
Medical device PCB fabricators face overlapping MDR and REACH biocompatibility documentation burdens. Swissmedic certification requirements concentrate diagnostic imaging board supply relationships with southern German precision clusters. The Zurich and Basel metropolitan areas anchor specialized substrate development for implantable device applications.
Europe PCB Market Vendor Landscape
On the supply side, the industry is bifurcated between scale-driven substrate producers and specialized technology developers. Tier-1 automotive procurement panels consolidate supplier bases around fabricators with captive laminate capabilities. Three archetypes dominate: vertically integrated laminate-to-board producers, embedded power semiconductor specialists, and high-density interconnect technology leaders. Competitive moves center on substrate co-development agreements with automotive OEMs and capacity expansion into Eastern European manufacturing zones.
Among Austria-based fabricators, AT&S AG occupies a position exemplifying high-density interconnect technology leadership. Würth Elektronik represents the vertically integrated archetype with in-house laminate production serving German industrial mid-market demand. Schweizer Electronic AG anchors the embedded power semiconductor specialist tier where few European competitors sustain comparable R&D intensity.
| Leading Market Players |
|---|
| AT&S AG |
| Würth Elektronik |
| Schweizer Electronic AG |
| Elvia PCB |
| NCAB Group |
| Cicor Group |
| Trackwise Designs |
| Unimicron Germany |
| KSG GmbH & Co |
| Others |
Supply Flow & Price Mechanics
Austrian and German laminate suppliers concentrate high-density interconnect substrate production, anchoring margin capture in automotive Tier-1 procurement panels while forcing Eastern European fabricators into cost-competitive consumer electronics tiers.
Pricing Analysis
Volume-discount tiering separates automotive co-development agreements from spot-market consumer electronics procurement. Pricing stratifies across automotive qualification premiums, industrial mid-market standard tiers, and cost-optimized economy levels for appliance modules. Cost compression in consumer electronics tiers intensifies as Romanian and Hungarian EMS hubs consolidate purchase volumes. Automotive OEMs exhibit lowest price sensitivity due to synchronized substrate-roadmap dependencies, while smart home device manufacturers drive hardest bargain terms.
Supply Chain Analysis
AT&S AG and Würth Elektronik hold captive laminate-to-board capacity across Austria and Germany. Raw material flows draw from copper smelters in Poland, epoxy resin producers in the Netherlands, and glass fiber weavers in the Czech Republic. Single-source vulnerability concentrates in halogen-free resin formulations where ECHA compliance documentation creates qualification bottlenecks. Distribution runs through direct OEM engagement for automotive, EMS aggregation for consumer electronics, and specialized aerospace distributors for Airbus supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Printed circuit board incumbents face substitution pressure from embedded die packaging and system-in-package technologies that displace traditional board-level interconnect in power electronics.
For Market Incumbents: Build captive substrate capability moats through backward integration into halogen-free resin formulation. Secure KBA automotive qualification status before REACH substance evaluation deadlines tighten. Anchor German industrial corridor relationships through co-development agreements that synchronize substrate roadmaps with power module releases.
For New Entrants and Emerging Players: Pursue greenfield substrate facilities in Poland's Silesian voivodeship serving German automotive demand with reduced logistics exposure. Target medical device PCB fabrication where MDR-REACH documentation overlap creates incumbent compliance fatigue. Enter through embedded power semiconductor technology partnerships with traction inverter developers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier EMS providers lacking captive laminate capabilities. Five-to-ten year viability hinges on automotive electrification sustaining multilayer board demand against packaging substitution. Monitor ECHA substance evaluation timelines as inflection signals for reformulation cost spikes and qualification delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Co-Development Agreement | Synchronizes laminate formulation with BMW and Volkswagen powertrain roadmaps. |
| Halogen-Free Resin Certification | Secures REACH compliance documentation for German automotive qualification panels. |
| Eastern European Capacity Expansion | Positions Polish facilities to serve German industrial demand with lower logistics exposure. |
| Embedded Power Semiconductor R&D | Captures value from electrification trends in traction inverters and onboard chargers. |
| Flexible Circuit Qualification | Enables Airbus and Safran cable harness replacement programs for weight reduction targets. |
Methodological Framework
Cross-validation between procurement director interviews and customs trade data anchors the qualitative findings. Primary fieldwork engaged substrate R&D leads at Austrian fabricators, Tier-1 automotive procurement managers, ECHA regulatory affairs specialists, and aerospace qualification engineers. Secondary sources combined REACH substance registration databases, KBA vehicle certification records, and Bavarian precision manufacturing cluster directories. Bottom-up fabrication capacity estimates triangulate against top-down automotive electronics spend allocations.
Calibration against historical automotive PCB adoption curves and medical device onshoring patterns shapes the projection framework. Segmentation modeling spans product type tiers, end-use industry verticals, technology assembly methods, and regional production clusters. CAGRs derive from substrate demand elasticity against vehicle electrification rates and diagnostic imaging equipment capital expenditure cycles. Copper price volatility assumptions and ECHA evaluation timeline scenarios feed sensitivity testing.
Sensitivities concentrate around REACH substance restriction accelerations, automotive platform standardization shifts toward system-in-package integration, and aerospace program delays affecting flexible circuit qualification volumes. Forecasts embed assumptions regarding German OEM electrification commitments and medical device MDR compliance timelines. Cross-checking against IHS Markit vehicle production databases and EMA medical device registration flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Buffered Encoders and Decoders Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Industrial Relays Market
Electronic Components
Flexible Heater Market
Electronic Components
Touchless Tubes Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Wireless Charging Stand Market
Electronic Components
Audio DSP Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Trackpad Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Speaker Membranes Market
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Distribution Components Market