
 Global Image Signal Processor Market | 2026-2036
Global Image Signal Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Image Signal Processor Market Outlook
A shift from captive in-house ISP design toward multi-source procurement is broadening vendor access across smartphone and automotive tiers. Qualcomm Technologies leverages its Snapdragon platform integration to anchor premium mobile sockets. STMicroelectronics specializes in automotive-grade ISPs with AEC-Q100 qualification. Sony Corporation dominates image sensor-ISP co-design for camera modules.
An image signal processor is a dedicated digital signal processor that converts raw pixel data from image sensors into viewable formats through demosaicing, noise reduction, tone mapping, and color space transformation, typically operating at clock speeds exceeding 1 GHz and supporting 10-bit or higher color depth for professional imaging pipelines. Its primary commercial purpose is enabling real-time visual output in devices where latency, power consumption, and image fidelity determine user experience and safety certification. Embedded ISPs lead unit volume by residing inside application processors for smartphones and tablets, while standalone ISPs command margin pools in automotive and machine vision where functional safety isolation from host CPUs is mandatory. HDR Imaging technology is accelerating fastest as multi-exposure fusion becomes standard in ADAS cameras and surveillance systems operating under extreme dynamic range conditions.
FCC equipment authorization requirements shape ISP electromagnetic compatibility testing for US-bound consumer electronics, while EU REACH and RoHS restrictions constrain material selection in European automotive camera modules. China's GB standards and MIIT certification mandate specific electromagnetic emission profiles for vehicle electronics entering domestic supply chains. Stakeholders must monitor divergence between ISO 26262 functional safety tiers for automotive and consumer-grade reliability benchmarks as product lines bifurcate.
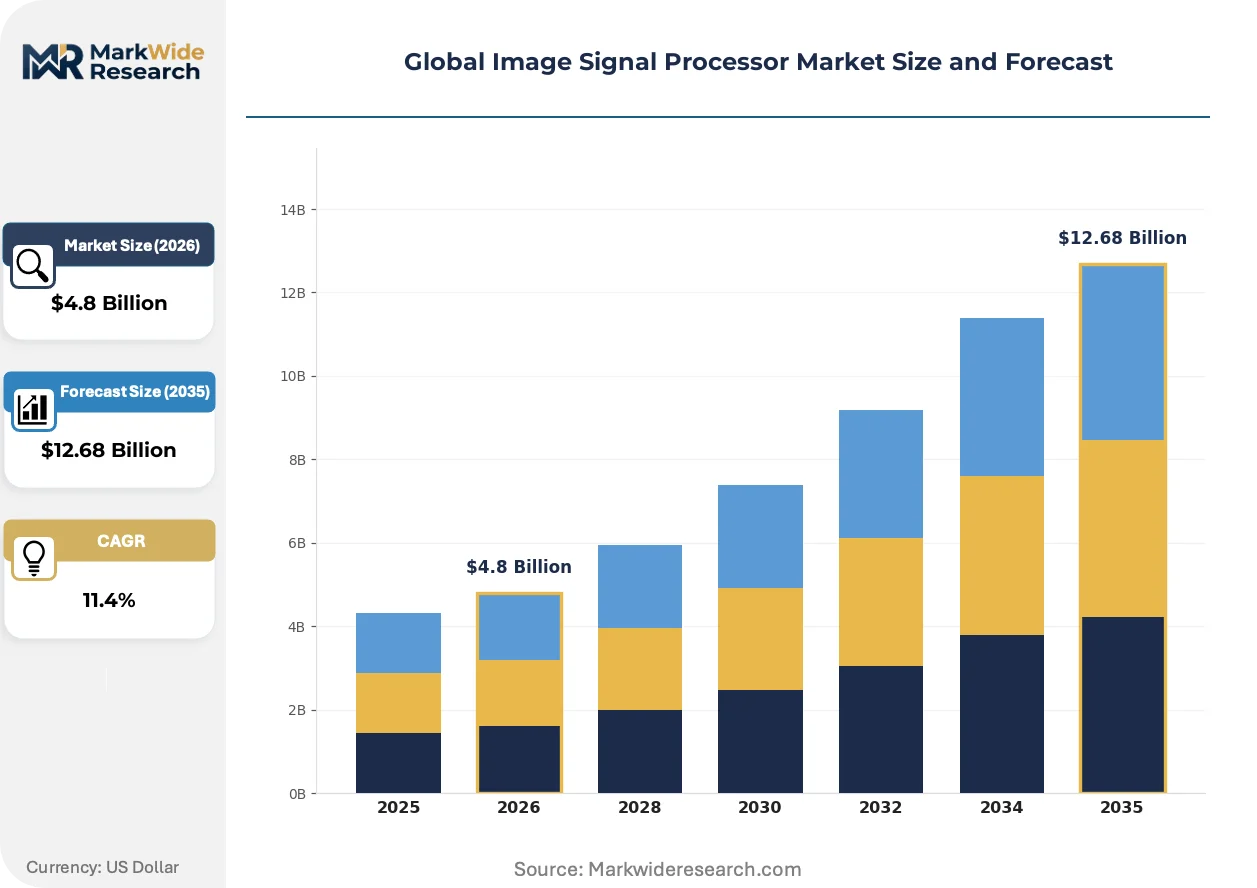
Market Dynamics
Automotive OEMs are dismantling captive ISP architectures as functional safety mandates force isolation between image processing and host compute, opening procurement to specialized vendors across ADAS and cabin monitoring tiers.
Growth Catalysts
- GB Standard Enforcement:China's MIIT mandates electromagnetic emission profiles for vehicle electronics, compelling domestic and foreign suppliers to certify ISPs against GB/T standards and accelerating replacement cycles in automotive camera modules.
- Multi-Exposure Fusion:HDR imaging pipelines now fuse three or more exposure brackets in real time, enabling ADAS cameras to resolve detail in simultaneous shadow and highlight regions where single-exposure architectures fail.
- Suwon-Pyeongtaek Cluster:Samsung Electronics and SK Hynix concentration in South Korea's semiconductor corridor anchors foundry capacity for stacked-die ISP packages serving mobile and automotive sockets.
Market Restraints
- AEC-Q100 Qualification Burden:Automotive-grade ISP validation requires 1,000-hour high-temperature operating life testing and fault coverage metrics that extend development timelines 18-24 months beyond consumer equivalents.
- Advanced Node Concentration:Sub-7nm finFET capacity for high-performance ISPs concentrates at three foundry complexes in Taiwan and South Korea, creating geographic supply vulnerability.
- Host Processor Integration:Snapdragon and Exynos application processors embed increasingly capable ISPs, compressing addressable market for standalone discrete solutions in premium smartphones.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor and automotive component manufacturing are attracting ISP packaging and test investments targeting domestic vehicle electrification and export markets.
- Edge AI Convergence:Neural network accelerators are merging with ISP datapaths to enable on-device object detection and scene classification without host CPU intervention, opening machine vision and robotics sockets.
- EU AI Act Compliance:Biometric identification restrictions in public spaces are redirecting surveillance camera demand toward privacy-preserving edge processing architectures where raw image data never leaves the device.
Industry Challenges
- ISO 26262 Talent Scarcity:Functional safety engineering expertise for ASIL-B and ASIL-D ISP designs remains concentrated among veterans of automotive microcontroller and powertrain domains, constraining vendor scaling.
- Legacy Vehicle Integration:ADAS retrofit programs for existing fleets require ISPs to bridge MIPI CSI-2 and older parallel interface standards, multiplying SKU complexity and validation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Image Signal Processor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded, Standalone, Hybrid, Integrated Technology: 2D Processing, 3D Processing, HDR Imaging, Image Recognition End User: Consumer Electronics, Automotive, Security Systems, Medical Devices Application: Photography, Surveillance, Computer Vision, Augmented Reality |
| Companies Covered | Texas Instruments, NXP Semiconductors, STMicroelectronics, ON Semiconductor, Analog Devices, Qualcomm Technologies, Sony Corporation, Fujitsu, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Image Signal Processor Market Strategic Shifts
Computational photography pipelines are migrating from centralized application processors to distributed camera modules, compressing latency and enabling new optical form factors across mobile and automotive deployments.
Edge-based neural processing units are decentralizing ISP functionality by embedding denoising, demosaicing, and tone mapping within camera modules themselves. Automotive Tier-1 suppliers are adopting these architectures for surround-view systems where cable length and electromagnetic interference constraints favor localized processing. This topology is decentralizing the traditional host-processor-centric imaging pipeline and fragmenting vendor hierarchies.
EU REACH substance restrictions are constraining material selection in automotive camera module housings and flex circuits, with ECHA candidate list updates targeting flame retardants and plasticizers common in connector molding compounds. German KBA type approval processes now require documented compliance cascades from ISP die packaging through module assembly. Suppliers are responding by qualifying halogen-free laminates and tin-bismuth solder alternatives for European-bound production lines.
Camera module makers are unbundling after-sales calibration and tuning services from hardware shipments, converting one-time component sales to recurring revenue streams tied to software-defined imaging pipelines. This model is displacing fixed-specification procurement in fleet management and industrial inspection verticals where lighting conditions vary across deployment sites. The shift is most visible in North American warehouse automation and Japanese precision manufacturing sectors.
Global Image Signal Processor Market Segmentation
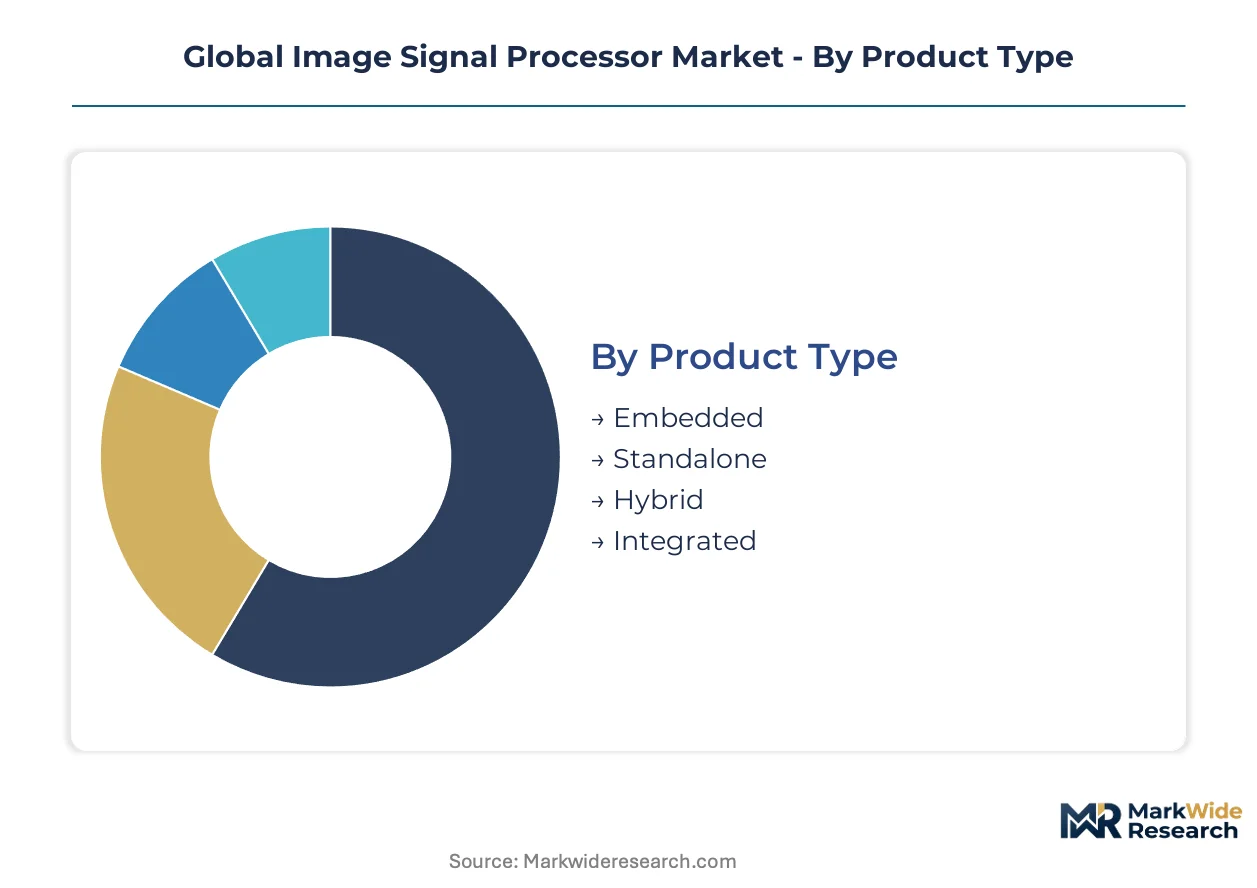
ISP procurement patterns diverge sharply across product architectures and end-use verticals. Upgrade cycles in automotive ADAS and smartphone camera modules are fragmenting vendor hierarchies as functional safety mandates and computational photography demands reshape specification requirements.
Product Type:
Replacement cycles accelerate where host processor integration conflicts with functional safety isolation requirements.
- Embedded:These ISPs reside within application processors from Qualcomm and MediaTek, handling demosaicing and noise reduction at clock speeds exceeding 1 GHz. Consumer electronics manufacturers in South Korea and Taiwan dominate procurement volumes as smartphone camera pipelines demand real-time processing without discrete components. The Snapdragon platform anchors premium mobile sockets where space and power constraints eliminate standalone alternatives.
- Standalone:Discrete architectures isolate image processing from host CPUs to satisfy ISO 26262 ASIL-B and ASIL-D tiers. Automotive OEMs across Germany, Japan, and the United States are dismantling captive designs to source these from STMicroelectronics and Renesas as ADAS camera counts per vehicle multiply.
- Hybrid:Split architectures partition preprocessing in camera modules while delegating final rendering to host processors. Surveillance system deployers favor this topology for edge-cloud balance.
- Integrated:Full-stack solutions combine sensor, ISP, and output interface in single packages. Medical device manufacturers specify these for endoscope and dermatology applications where sterilization constraints limit component count.
Embedded ISPs sit at the top of the volume ranking, with standalone architectures climbing the fastest as automotive functional safety mandates harden.
Technology:
Cost tiers separate legacy 2D pipelines from premium multi-exposure fusion architectures commanding qualification premiums.
- 2D Processing:Established planar algorithms handle single-frame demosaicing and color correction for cost-sensitive applications. Security camera OEMs in China specify these for mass-market residential installations where dynamic range requirements remain modest.
- 3D Processing:Depth-map generation from stereo or structured-light inputs enables spatial awareness for robotics and AR headsets. Machine vision integrators in Japan and Germany are the primary demand concentration as factory automation and warehouse logistics adopt volumetric sensing.
- HDR Imaging:Real-time fusion of three or more exposure brackets resolves simultaneous shadow and highlight detail. ADAS camera modules for surround-view and forward-facing systems now mandate this capability as NHTSA and Euro NCAP test protocols incorporate low-sun-angle scenarios.
- Image Recognition:Neural network acceleration within ISP datapaths enables on-device classification without host CPU intervention. EU AI Act biometric restrictions are redirecting surveillance demand toward these privacy-preserving edge architectures.
HDR Imaging commands the steepest expansion trajectory as multi-exposure fusion becomes standard in automotive and professional imaging tiers.
End User:
Customer type determines certification burden and pricing structure across consumer, automotive, and regulated medical verticals.
- Consumer Electronics:Smartphone and tablet manufacturers drive unit volume through application processor integration. Samsung Electronics and Apple anchor demand concentration in South Korea and the United States respectively, with annual camera specification escalations forcing ISP capability upgrades.
- Automotive:Tier-1 suppliers and OEMs specify AEC-Q100 qualified components with fault coverage metrics extending development timelines. The German KBA and U.S. NHTSA type approval processes require documented compliance cascades from die packaging through module assembly.
- Security Systems:Enterprise and government surveillance deployments prioritize low-light performance and edge analytics. China's GB standards and MIIT certification mandate specific electromagnetic emission profiles for domestic installations.
- Medical Devices:Endoscopy, ophthalmology, and surgical imaging require sterilization-compatible packaging and FDA or CE marking. ISO 13485 quality management systems constrain vendor pools to established medical imaging specialists.
Consumer Electronics maintains volume leadership, with Automotive gaining share fastest as camera counts per vehicle escalate from four to twelve or more.
Application:
Geographic deployment patterns concentrate computational photography demand in East Asia while computer vision adoption accelerates in North American logistics.
- Photography:Smartphone camera pipelines demand real-time multi-frame processing for portrait mode and night sight algorithms. South Korea's Suwon-Pyeongtaek semiconductor cluster anchors foundry capacity for the stacked-die packages serving this segment.
- Surveillance:City-scale deployments in China and smart city initiatives across India and the United Arab Emirates drive demand for edge-processing cameras. EU AI Act biometric restrictions are fragmenting procurement toward privacy-preserving architectures.
- Computer Vision:Industrial inspection and warehouse automation require sub-millisecond latency for robotic pick-and-place operations. Amazon and Walmart fulfillment networks in the United States specify these capabilities for automated sortation systems.
- Augmented Reality:Head-mounted displays for enterprise maintenance and consumer gaming fuse spatial mapping with passthrough video. Meta and Apple product roadmaps in the United States are concentrating engineering investment in low-power ISP-NNP convergence.
Photography occupies the top volume position, with Computer Vision expanding most quickly as logistics automation penetrates North American and European distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suwon-Pyeongtaek semiconductor corridor anchors global ISP foundry capacity, with Samsung Electronics and SK Hynix concentration driving stacked-die packaging for mobile and automotive sockets. Regulatory divergence across major economies is fragmenting certification requirements and procurement patterns.
United States
Automotive Tier-1 suppliers and smartphone OEMs drive demand for high-performance ISPs with neural acceleration. FCC equipment authorization mandates electromagnetic compatibility testing for consumer electronics, while NHTSA type approval processes govern ADAS camera modules. Engineering investment concentrates in California and Texas around Snapdragon platform development and autonomous vehicle testing fleets.
China
Domestic vehicle electrification and surveillance system deployment absorb substantial ISP volumes across embedded and standalone architectures. MIIT enforces GB/T electromagnetic emission standards for automotive electronics, compelling certification cycles that accelerate replacement timelines. Yangtze River Delta clusters in Shanghai and Suzhou host module assembly operations serving both domestic OEMs and export markets.
Germany
Premium automotive OEMs source AEC-Q100 qualified ISPs for surround-view and forward-facing ADAS systems. KBA type approval requires documented compliance cascades from die packaging through module assembly, extending validation timelines. Baden-Württemberg engineering centers specialize in functional safety integration for ASIL-B and ASIL-D tiers.
South Korea
Smartphone camera specification escalations force annual ISP capability upgrades across Samsung Electronics and domestic supply chains. MFDS certification frameworks govern medical imaging applications, constraining vendor pools for endoscope manufacturers. Seoul Capital Area concentration spans fabless design houses, foundry operations, and camera module assembly.
Japan
Machine vision integrators and factory automation specialists demand sub-millisecond latency ISPs for robotic pick-and-place systems. METI industrial policy supports edge AI convergence in imaging pipelines for logistics and precision manufacturing. Kansai region engineering centers around Osaka anchor 3D processing and depth-map generation expertise.
Global Image Signal Processor Market Competitive Environment
Global majors compete with regional champions across functional safety certification tiers, with automotive-grade qualification separating premium vendors from consumer-focused suppliers. Market structure shows moderate concentration, with Snapdragon platform integration and sensor-ISP co-design creating sticky relationships in mobile and camera module verticals. Three archetypes dominate: semiconductor conglomerates with captive ISP divisions, specialized automotive-grade vendors with AEC-Q100 portfolios, and fabless designers targeting edge AI convergence. Competitive moves center on strategic partnerships for neural processing unit integration and geographic expansion into India PLI scheme jurisdictions.
Among diversified semiconductor conglomerates, Texas Instruments, NXP Semiconductors, and STMicroelectronics occupy positions spanning industrial, automotive, and consumer verticals with broad qualification portfolios. These entities exemplify the scale-driven archetype where manufacturing depth and certification breadth create defensive positioning against specialized entrants. Their geographic distribution across North America and Europe reflects historical customer concentration in German automotive and US industrial automation sectors.
| Leading Market Players |
|---|
| Texas Instruments |
| NXP Semiconductors |
| STMicroelectronics |
| ON Semiconductor |
| Analog Devices |
| Qualcomm Technologies |
| Sony Corporation |
| Fujitsu |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Semiconductor conglomerates with captive ISP divisions anchor pricing discipline through backward integration into foundry capacity, while fabless specialists compete on certification premiums and after-sales software bundles. Taiwan and South Korea concentration in sub-7nm finFET nodes concentrates supply-side leverage among TSMC and Samsung Electronics, compressing margin pools for second-tier vendors dependent on external wafer supply.
Pricing Analysis
Advanced node wafer costs pass through to module pricing with minimal absorption by automotive Tier-1 suppliers facing AEC-Q100 qualification deadlines. Three-tier pricing structure across ASIL-D automotive, ASIL-B industrial, and consumer-grade tiers separates fault-coverage metrics from basic reliability benchmarks. Cost compression in consumer embedded ISPs intensifies because Snapdragon and Exynos integration eliminates standalone socket opportunities. Security camera OEMs in China exhibit highest price sensitivity, while German automotive OEMs accept certification premiums for documented ISO 26262 compliance cascades.
Supply Chain Analysis
Reverse-logistics flows for automotive camera modules center on refurbishment programs for ADAS retrofit fleets, extending component lifecycles through firmware requalification rather than hardware replacement. Foundry supply concentrates in Taiwan, South Korea, and the United States, with stacked-die packaging capacity anchored in the Suwon-Pyeongtaek corridor. Raw material dependencies span silicon wafers, halogen-free laminates, and tin-bismuth solder alternatives for EU REACH compliance. Single-source vulnerability at three sub-7nm foundry complexes creates geographic concentration risk. Distribution runs through camera module assemblers in the Yangtze River Delta and direct Tier-1 supplier contracts for automotive sockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with China's GB/T electromagnetic emission standards and the EU AI Act biometric restrictions accelerating replacement cycles across automotive and surveillance verticals.
For Market Incumbents: To counter host-processor ISP integration threatening standalone discrete volumes, STMicroelectronics and Renesas should expand AEC-Q100 portfolio breadth into cabin monitoring and surround-view tiers. Qualcomm Technologies must deepen Snapdragon platform stickiness through neural processing unit convergence with imaging pipelines. Certification investment in ASIL-D fault coverage metrics defends margin position against consumer-grade entrants. For New Entrants and Emerging Players: India's PLI scheme for semiconductor manufacturing opens a window for packaging and test investments targeting domestic vehicle electrification and export markets. Edge AI convergence in machine vision robotics represents the most penetrable white-space target, with privacy-preserving edge architectures for EU AI Act compliance offering differentiated go-to-market positioning against centralized cloud-analytics incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless designers with automotive functional safety certification gaps but strong neural network acceleration IP. Long-term viability favors vendors with ISO 26262 talent depth and foundry relationships secured through the analysis window. Acquisition targets should display AEC-Q100 qualification momentum and India PLI scheme participation. Practitioners should monitor MIIT GB standard enforcement velocity and EU AI Act implementation timelines for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Qualification Expansion | STMicroelectronics and Renesas extend automotive-grade portfolios into cabin monitoring tiers. |
| Neural Processing Unit Convergence | Qualcomm Technologies merges ISP datapaths with on-device object detection accelerators. |
| India PLI Scheme Manufacturing Entry | Packaging and test investments target domestic vehicle electrification and export markets. |
| Privacy-Preserving Edge Architecture Development | EU AI Act biometric restrictions redirect surveillance demand toward raw-data-localized processing. |
| Halogen-Free Material Qualification | German KBA type approval processes mandate documented compliance cascades for European-bound production. |
Study Parameters
Multiple input streams — primary interviews with automotive Tier-1 procurement officers, ISP fabless design house engineering leads, and camera module assembler operations managers; secondary validation through MIIT GB standard filings, FCC equipment authorization databases, and SEC semiconductor capex disclosures; plus customs trade data for image sensor and ISP die shipments — were reconciled through bottom-up and top-down triangulation. Supply-side estimates drew from foundry capacity announcements and AEC-Q100 qualification registries. Demand-side modeling incorporated OEM platform roadmaps and ADAS camera count specifications across vehicle programs.
Data-stream reconciliation anchored volume projections to vehicle production databases and smartphone shipment forecasts, with value outputs derived from module-level pricing intelligence across consumer, automotive, and medical verticals. Segmentation dimensions spanned product architecture, technology tier, end-user vertical, and application, with additional granularity on functional safety certification level. CAGRs were computed from log-linear trend fitting across the modeling period, with cross-validation against semiconductor industry association reports and hyperscaler imaging pipeline disclosures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry capacity constraints or GB standard enforcement acceleration. Projections reflect assumptions regarding MIIT certification timelines, EU AI Act implementation sequencing, and automotive camera penetration curves. Practitioners should monitor sub-7nm foundry utilization rates and ISO 26262 engineering talent migration patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Holotomographic Imaging Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Chemical Imaging Systems Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Global Digital Photo Frame Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Digital Imaging Market
Imaging
Cooled IR Camera Market
Imaging
TDI Camera Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Photo Kiosk Market
Imaging
Global Camera Module Market
Imaging
Hyperspectral Imaging Camera Market