
 TDI Camera Market | 2026-2036
TDI Camera Market Size, Share, and Industry Trends Forecast 2026-2036
TDI Camera Market Insights
Japanese sensor foundries is broadening output for time-delay-integration architectures serving flat-panel display metrology. Hamamatsu Photonics leverages vertical integration from photodiode crystals to camera modules, sustaining margin control across the imaging stack. Teledyne DALSA anchors North American supply through captive CMOS foundry partnerships and specialized backside-illumination processes. Gpixel Inc. competes on large-format scientific arrays, differentiating through multi-port readout circuits that reduce effective noise floors.
A TDI camera accumulates photoelectrons across multiple pixel rows as the scene moves perpendicular to the sensor axis, achieving signal-to-noise ratios exceeding 80 dB in low-light line-scan applications. The architecture relies on precise synchronization between charge transfer clocking and external motion encoders, enabling continuous inspection of web materials, printed electronics, and cylindrical pharmaceutical labels without motion blur. Line scan cameras occupy the dominant revenue position due to entrenched deployment in lithium-battery electrode coating and solar cell metallization lines. CMOS technology is displacing legacy CCD platforms where rolling-shutter artifacts can be eliminated through correlated double sampling per TDI stage. Medical imaging applications, particularly digital pathology slide scanning, represent the fastest-expanding demand pool as laboratories convert from color-filter array sensors to monochrome TDI configurations for fluorescence multiplexing.
FDA 21 CFR Part 820 quality system regulations govern TDI camera integration into diagnostic device subassemblies, while ISO 13485 certification requirements shape supplier qualification timelines for OEMs serving clinical laboratories. The EU AI Act and MDR framework impose algorithmic transparency obligations on smart camera deployments in automated pathology workflows, redirecting R&D toward explainable defect-classification models. Stakeholders must monitor divergence between FDA software-as-medical-device guidance and European conformity assessment routes, as dual-market camera platforms face escalating documentation burdens that favor modular hardware-software architectures.
Market Dynamics
The migration from CCD to CMOS architectures is restructuring competitive advantage around backside-illumination yield rates and multi-port readout circuit design, compressing replacement cycles in semiconductor wafer inspection and flat-panel display metrology.
Growth Catalysts
- Horizon Europe funding:EU research programs under Horizon Europe are accelerating CMOS sensor development for scientific imaging, channeling grants toward time-delay-integration architectures serving fluorescence microscopy.
- Sub-nanometer defect detection:Semiconductor fabs in Taiwan and South Korea are mandating TDI camera upgrades for advanced packaging inspection, pulling demand from legacy line-scan configurations.
- Digital pathology conversion:Clinical laboratories are abandoning color-filter array sensors for monochrome TDI configurations that enable fluorescence multiplexing in slide scanning workflows.
Market Restraints
- Specialized foundry concentration:Backside-illumination processing capacity concentrates among Japanese and North American captive facilities, creating supply bottlenecks for large-format scientific arrays.
- FDA 21 CFR Part 820 compliance costs:Diagnostic device OEMs face extended qualification timelines for camera subassemblies, inflating upfront certification expenditures before revenue recognition.
- CCD inventory overhang:Legacy sensor stockpiles in industrial automation channels delay CMOS upgrade decisions among price-sensitive battery electrode coating operators.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO-regulated active pharmaceutical ingredient facilities are adopting automated visual inspection systems, opening TDI camera deployment in tablet and vial packaging lines.
- EU AI Act algorithmic transparency:Automated pathology workflows face explainable defect-classification mandates, redirecting R&D toward modular hardware-software architectures that separate inference from image acquisition.
- Printed electronics roll-to-roll processing:Silver nanoparticle and organic semiconductor deposition lines require continuous web inspection without motion blur, matching TDI signal-to-noise capabilities.
Industry Challenges
- Precision motion encoder synchronization:Charge transfer clocking alignment with external encoders demands specialized firmware engineering talent scarce in machine vision system integrators.
- Dual-market documentation divergence:Camera platforms serving both FDA software-as-medical-device pathways and European MDR conformity assessment routes face escalating technical file burdens that fragment product roadmaps.
- Correlated double sampling integration:Eliminating rolling-shutter artifacts per TDI stage requires analog front-end design expertise concentrated among legacy CCD engineering teams approaching retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TDI Camera Market |
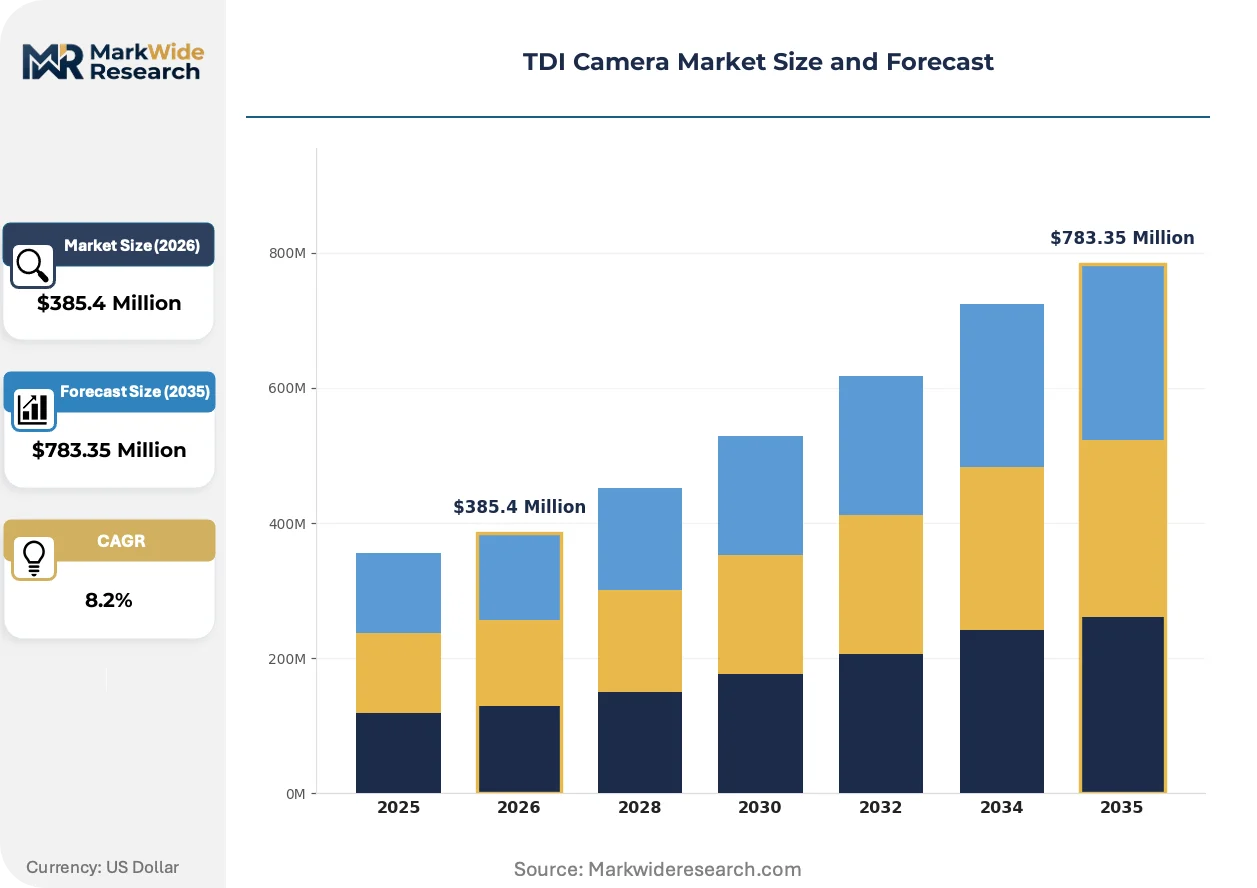
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $783.35 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Line Scan Cameras, Area Scan Cameras, Smart Cameras, High-Speed Cameras Technology: CCD, CMOS, Image Signal Processing, Infrared Imaging End User: Manufacturing, Healthcare, Automotive, Security Application: Quality Control, Industrial Automation, Medical Imaging, Surveillance |
| Companies Covered | STEMMER IMAGING, Detection Technology Plc, Hamamatsu Photonics, FLIR Systems, Canon USA, Inc., Teledyne DALSA, Gpixel Inc., Emergent Vision Technologies, Vieworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TDI Camera Market Trends and Innovations
Three interconnected developments are compressing development cycles and rewiring buyer-supplier relationships across the imaging stack: CMOS process convergence with motion control systems, regulatory algorithmic transparency mandates, and procurement unbundling of hardware from analytics software.
Backside-illuminated CMOS TDI sensors with multi-port readout circuits are converging with precision linear motor stages and interferometric encoders in semiconductor wafer inspection tools. Equipment builders in Taiwan and South Korea are specifying synchronized camera-stage subsystems as single procurement units, collapsing traditional component sourcing boundaries and favoring vendors with motion control firmware capabilities.
The EU AI Act and MDR framework impose explainable defect-classification obligations on smart camera deployments in automated pathology workflows. Diagnostic device OEMs must now document algorithmic decision pathways for fluorescence multiplexing applications, redirecting engineering resources from raw sensor performance toward interpretable inference layers and audit trail architectures.
Buyers in lithium-battery electrode coating and solar cell metallization are unbundling camera hardware purchases from machine vision software licenses. System integrators in East Asia increasingly specify open-architecture GigE Vision and Camera Link interfaces to mix sensor vendors with independent analytics providers, eroding historical vendor lock-in and pressuring margin structures on bundled solutions.
TDI Camera Market Segmentation
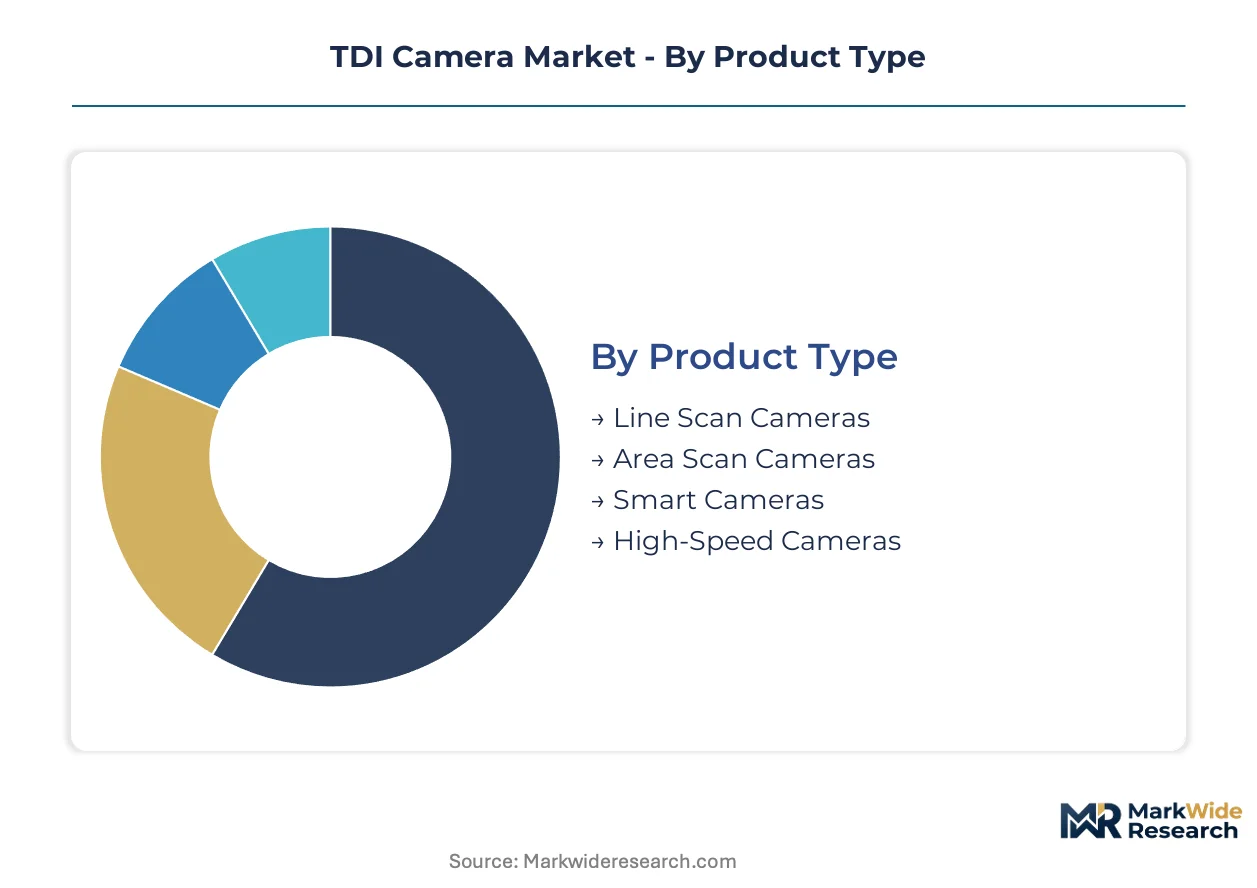
TDI camera procurement splits across sensor architectures, integration levels, and end-use performance requirements. Capital allocation patterns differ sharply between semiconductor fabs seeking sub-nanometer precision and pharmaceutical packaging lines prioritizing throughput economics.
Product Type:
Capital intensity peaks in high-speed configurations requiring custom backside-illumination foundry access, while line-scan variants leverage standardized CMOS processes for volume deployment.
- Line Scan Cameras:Accumulate photoelectrons across multiple pixel rows synchronized to perpendicular motion, achieving signal-to-noise ratios exceeding 80 dB. Lithium-battery electrode coating lines in Taiwan and South Korea anchor demand, driven by continuous web inspection requirements without motion blur.
- Smart Cameras:Embed image signal processing and defect-classification algorithms within the camera housing, reducing host PC dependencies. EU AI Act transparency mandates for automated pathology workflows are redirecting R&D toward modular hardware-software architectures that separate inference from acquisition.
- Area Scan Cameras:Capture two-dimensional fields through TDI row accumulation for cylindrical object inspection.
- High-Speed Cameras:Demand multi-port readout circuits and specialized analog front-end design expertise concentrated among legacy engineering teams.
Most installed capacity flows through Line Scan Cameras. Expansion is steepest in Smart Cameras.
Technology:
Process migration trajectories separate legacy CCD inventory channels from CMOS replacement cycles driven by rolling-shutter elimination and correlated double sampling integration.
- CMOS:Backside-illuminated architectures with multi-port readout circuits are displacing legacy platforms where TDI stage synchronization demands precise charge transfer clocking. Horizon Europe research grants are accelerating sensor development for fluorescence microscopy applications.
- CCD:Remains entrenched in price-sensitive battery electrode coating operations with existing inventory stockpiles delaying upgrade decisions.
- Image Signal Processing:Firmware engineering for motion encoder synchronization represents scarce talent concentrated in Japanese and North American captive facilities.
- Infrared Imaging:Serves specialized thermal inspection applications with limited TDI architecture penetration.
CMOS captures the dominant share of new design wins. CCD retention is highest in legacy industrial automation channels.
End User:
Regulatory compliance burdens fragment procurement patterns between FDA 21 CFR Part 820 diagnostic device pathways and industrial automation quality systems.
- Healthcare:Digital pathology laboratories are converting from color-filter array sensors to monochrome TDI configurations for fluorescence multiplexing. ISO 13485 certification requirements shape supplier qualification timelines for clinical laboratory OEMs.
- Manufacturing:Semiconductor wafer inspection and flat-panel display metrology drive sub-nanometer defect detection requirements.
- Automotive:Battery cell inspection and printed electronics deposition lines require continuous web monitoring capabilities.
- Security:Surveillance applications favor cost-optimized area scan configurations over specialized TDI architectures.
Healthcare commands the highest average selling prices. Manufacturing contributes the largest unit volumes.
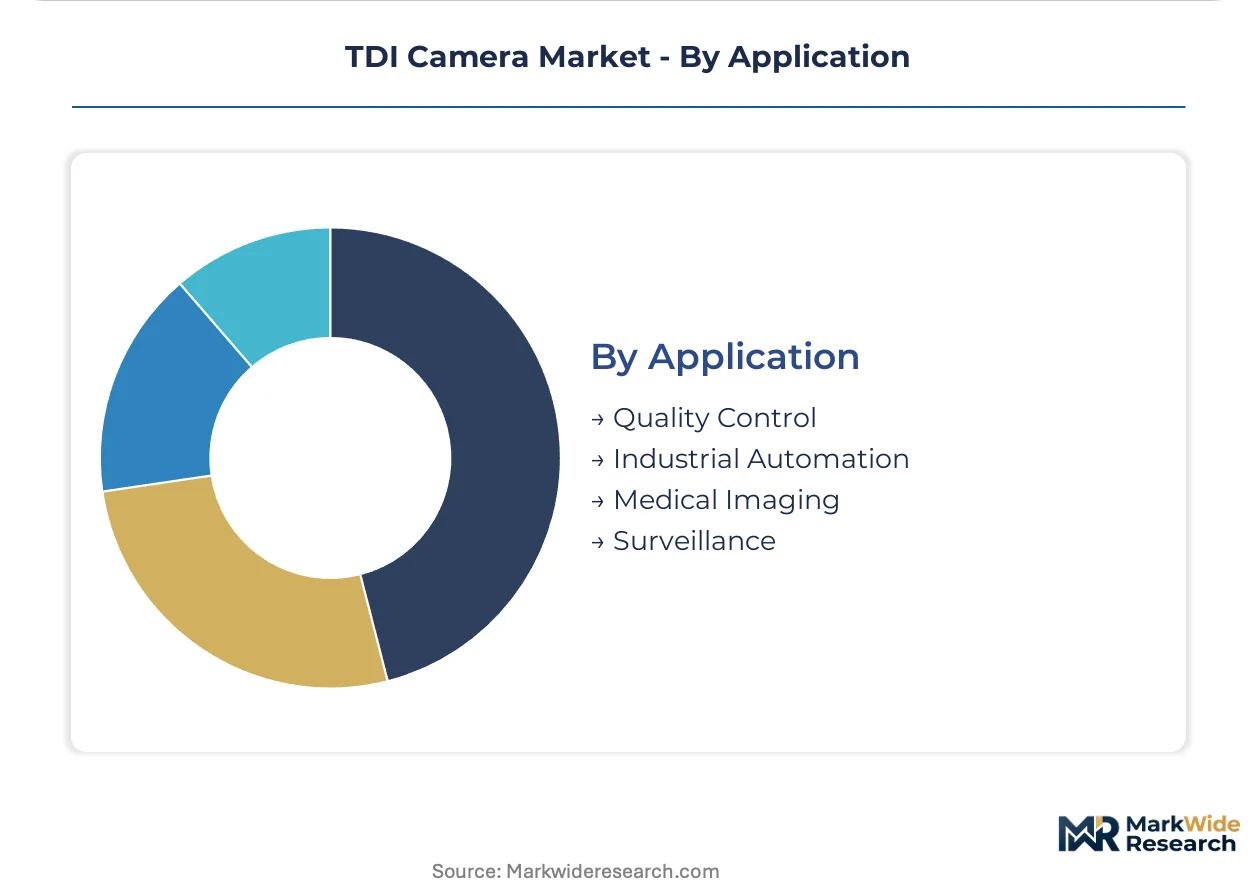
Application:
Performance specifications diverge between medical imaging workflows requiring algorithmic audit trails and industrial automation prioritizing throughput consistency.
- Quality Control:Automated visual inspection systems in pharmaceutical tablet and vial packaging lines are expanding TDI deployment. CDSCO-regulated active pharmaceutical ingredient facilities in India represent emerging demand.
- Medical Imaging:Slide scanning workflows mandate explainable defect-classification models under EU AI Act and MDR framework obligations.
- Industrial Automation:Solar cell metallization and roll-to-roll printed electronics processing require precise motion encoder synchronization.
- Surveillance:Lower-resolution requirements favor standard line-scan alternatives over specialized TDI signal-to-noise capabilities.
Quality Control absorbs the majority of production capacity. Medical Imaging is climbing the fastest on regulatory conversion mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting TDI camera procurement toward jurisdictions with streamlined medical device certification pathways, as diagnostic OEMs seek to bypass the documentation divergence between FDA 21 CFR Part 820 and European MDR frameworks. Production investment clusters where compliance costs are offset by concentrated demand from semiconductor fabrication and pharmaceutical packaging automation.
United States
Diagnostic device manufacturers drive demand through FDA 21 CFR Part 820 quality system requirements for digital pathology slide scanning systems. The IRA's domestic manufacturing incentives are pulling semiconductor metrology equipment investment toward Arizona and Texas fab clusters. Boston-area clinical laboratories anchor early adoption of fluorescence multiplexing configurations.
Germany
Automotive battery cell inspection and flat-panel display metrology sustain industrial automation procurement. ECHA REACH compliance for camera module materials shapes supplier qualification timelines. Bavaria's precision engineering corridor concentrates system integrator activity serving printed electronics roll-to-roll processing lines.
Japan
Hamamatsu Photonics' vertical integration from photodiode crystals to modules anchors domestic sensor foundry capacity. METI's semiconductor revitalization subsidies are expanding backside-illumination processing for scientific imaging arrays. Nagoya industrial automation clusters demand precise motion encoder synchronization for cylindrical pharmaceutical label inspection.
South Korea
Memory manufacturing investments in Pyeongtaek and Yongin are mandating sub-nanometer defect detection upgrades for advanced packaging inspection. MFDS pharmaceutical GMP requirements are accelerating automated visual inspection deployment in vial packaging lines. Seoul-based equipment builders specify synchronized camera-stage subsystems as single procurement units.
India
CDSCO-regulated active pharmaceutical ingredient facilities in Hyderabad and Ahmedabad are adopting TDI-based tablet inspection systems. The PLI scheme for specialty chemicals is expanding pharmaceutical packaging automation investment. Maharashtra's contract manufacturing clusters represent emerging demand for continuous web inspection in roll-to-roll processing.
TDI Camera Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular hardware-software architectures that separate inference from image acquisition. The vendor base stratifies across three maturity levels: integrated sensor foundries with captive fabrication, specialized camera module assemblers, and software-centric smart camera developers. Two strategic archetypes dominate: vertically integrated photonics conglomerates controlling crystal growth through module assembly, and fabless design houses competing on multi-port readout circuit IP. Competitive moves concentrate on strategic partnerships between sensor designers and precision motion control OEMs, plus portfolio diversification into algorithmic transparency-compliant pathology workflows.
Among Japanese and North American sensor specialists, Hamamatsu Photonics, Teledyne DALSA, and Gpixel Inc. occupy distinct positioning archetypes. Hamamatsu represents the fully integrated model spanning photodiode crystals to finished camera modules. Teledyne DALSA exemplifies the captive foundry partnership approach with specialized backside-illumination processes. Gpixel sits within the large-format scientific array segment, differentiated through multi-port readout circuit architectures. These three anchors demonstrate how competitive advantage is restructuring around backside-illumination yield rates and firmware engineering for motion encoder synchronization.
| Leading Market Players |
|---|
| STEMMER IMAGING |
| Detection Technology Plc |
| Hamamatsu Photonics |
| FLIR Systems |
| Canon USA, Inc. |
| Teledyne DALSA |
| Gpixel Inc. |
| Emergent Vision Technologies |
| Vieworks |
| Others |
Pricing and Supply Chain Analysis
Firmware engineering talent scarcity in Nagoya and Boston clusters widens pricing spreads between motion-synchronized premium tiers and standardized line-scan configurations, as labor-cost differentials compound foundry-access premiums.
Pricing Analysis
Distributor margins on smart camera modules absorb 15-25 point spreads before OEM qualification. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 820-certified pathology configurations from industrial automation variants. Cost compression in battery electrode coating channels intensifies because CCD inventory liquidation delays CMOS conversion decisions. Price sensitivity peaks among Taiwanese solar cell metallization operators; diagnostic device OEMs exhibit lowest elasticity due to ISO 13485 recertification costs.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 qualification gating fragments supplier pools into medical-grade and industrial tiers. Backside-illumination processing concentrates in Japan, the United States, and South Korea, drawing from specialized photodiode crystal growth, multi-port readout ASICs, and precision motion encoder firmware. Single-source vulnerability concentrates in large-format scientific array foundry capacity. Distribution runs through system integrator partnerships in East Asia and direct OEM relationships in North American diagnostic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage favors South Korean and Taiwanese production clusters against European regulatory documentation burdens, as MDR conformity assessment timelines inflate working capital requirements relative to FDA 510(k) pathways.
For Market Incumbents: Cement captive foundry partnerships for backside-illumination yield control against fabless design house encroachment. Deepen firmware engineering benches in precision motion synchronization to defend bundled camera-stage subsystem procurement. ISO 13485 certification investment creates switching costs against modular hardware-software disaggregators.
For New Entrants and Emerging Players: Capture CDSCO-regulated pharmaceutical packaging automation in India through localized tablet inspection system integration. The most penetrable white space sits in explainable defect-classification software layers separable from image acquisition hardware. Go-to-market leverage rests on open-architecture GigE Vision compatibility with incumbent sensor vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among fabless multi-port readout circuit design houses with medical imaging pipeline visibility. Long-term viability hinges on EU AI Act algorithmic transparency compliance as a durable moat. Watch MFDS pharmaceutical GMP enforcement intensity in South Korea as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backside-Illumination Foundry Partnership | Captures yield-rate advantages for sub-nanometer wafer inspection applications in Taiwan. |
| Modular Hardware-Software Architecture | Separates inference from acquisition to satisfy EU AI Act transparency mandates in pathology. |
| Motion Control Firmware Acquisition | Consolidates camera-stage subsystem procurement power with Seoul-based equipment builders. |
| CDSCO Regulatory Localization | Opens pharmaceutical packaging automation in Hyderabad and Ahmedabad API facilities. |
| Correlated Double Sampling IP Licensing | Transfers legacy CCD expertise to CMOS rolling-shutter elimination for battery coating lines. |
Research Methodology
Coverage spans East Asia, North America, and Europe, with primary inputs from each combining sensor foundry engineering directors, diagnostic device OEM procurement managers, semiconductor metrology equipment builders, and machine vision system integrators. Secondary validation draws from FDA 510(k) filings, EMA MDR technical documentation, Horizon Europe grant disclosures, and SEC filings of listed photonics conglomerates. Bottom-up unit demand triangulation against top-down wafer inspection capital expenditure patterns anchors value estimates.
Rate-of-change decomposition separates CMOS displacement velocity from CCD inventory liquidation drag across the projection horizon. Segmentation dimensions span sensor architecture, integration level, end-use performance tier, and regional regulatory cluster. CAGRs derive from equipment purchase order backlogs and fab capacity expansion announcements. Industry-specific inputs include correlated double sampling adoption curves and precision motion encoder synchronization firmware availability.
Underlying measurement precision varies by segment; semiconductor wafer inspection and digital pathology carry tighter precision than legacy industrial automation channels. Forecasts reflect assumptions on EU AI Act implementation timelines and FDA software-as-medical-device guidance evolution. A model refresh is warranted upon material change in Horizon Europe funding allocation or MFDS pharmaceutical GMP enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
North America IP Camera Market
Imaging
Gel Imaging Documentation Market
Imaging
Microwave Imaging Market
Imaging
Global Digital Binoculars Market
Imaging
Automotive Compact Camera Module Market
Imaging
Image Based Barcode Reader Market
Imaging
Phosphor Screen Scanner Market
Imaging
Global Microbolometer Market
Imaging
Ultra-Wide Field Imaging Device Market
Imaging
Global Image Processing Systems Market
Imaging
Global 3D Imaging Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Thermal Imaging Systems Market
Imaging
Visualiser Market