
 Global Digital Photo Frame Market | 2026-2036
Global Digital Photo Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Photo Frame Market Foresight
Multi-source panel procurement from Taiwanese and South Korean display suppliers is hardening as brands buffer against single-factory risk. Nixplay leverages its direct-to-consumer channel to sustain premium pricing in North America. Aura Home Inc. anchors its position through cloud-first software architecture that differentiates against hardware-centric rivals. Aluratek competes on value-tier distribution through mass retail partnerships.
A digital photo frame is a standalone electronic display device with integrated storage, typically featuring LCD or LED panels between seven and fifteen inches diagonally, designed to cycle through digital images without requiring a paired computer. Wi-Fi enabled frames and touchscreen variants dominate current revenue as consumers prioritize seamless smartphone photo syncing and interactive controls over passive slideshow functionality. Cloud storage connectivity is displacing USB and SD Card transfer methods among individual consumers, while corporate gifting and retail showcase applications favor HD display frames for visual impact at commercial viewing distances.
FCC electromagnetic emissions standards in the United States, CE marking requirements under EU RoHS and REACH frameworks, and Japan's METI energy efficiency directives collectively shape product design cycles and market access timelines for frame manufacturers. The EU AI Act's emerging provisions on algorithmic content curation may affect frames with automated photo selection features, requiring compliance documentation before European distribution. Stakeholders must monitor how evolving e-waste regulations across key jurisdictions influence modular repairability mandates and material substitution strategies.
Market Dynamics
The EU Green Deal's ecodesign mandates are forcing manufacturers toward lower-power LED panels and recyclable chassis materials, while hospitality and senior living facilities replace static signage with remotely updatable displays.
Growth Catalysts
- Wi-Fi enabled frames:Seamless smartphone photo syncing is displacing USB and SD Card transfer methods among individual consumers.
- Cloud-first software architecture:Interactive touchscreen controls are displacing passive slideshow functionality in premium consumer segments.
- Germany's aging demographics:Dual tailwinds from smart home penetration and elderly care needs are concentrating demand for connected frames.
Market Restraints
- Display panel supply concentration:Heavy reliance on Taiwanese and South Korean suppliers creates single-factory risk exposure.
- EU AI Act compliance friction:Emerging provisions on algorithmic content curation require documentation before European distribution of frames with automated photo selection.
- Smartphone substitution:Large-screen mobile devices and smart displays compete for the same visual-sharing use cases.
Strategic Opportunities
- Corporate gifting and retail showcase applications:HD display frames for visual impact at commercial viewing distances remain underpenetrated versus consumer segments.
- Modular repairability mandates:Evolving e-waste regulations across key jurisdictions favor manufacturers with component-swappable designs.
- Multi-source panel procurement:Buffer strategies against supply disruption open procurement relationships with secondary display suppliers.
Industry Challenges
- FCC electromagnetic emissions certification:United States market access requires testing cycles that compress product launch timelines.
- CE marking under RoHS and REACH:EU chemical restriction compliance demands material substitution strategies that extend design cycles.
- Cloud storage integration complexity:Legacy frame architectures require software re-engineering to support seamless photo syncing services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Photo Frame Market |
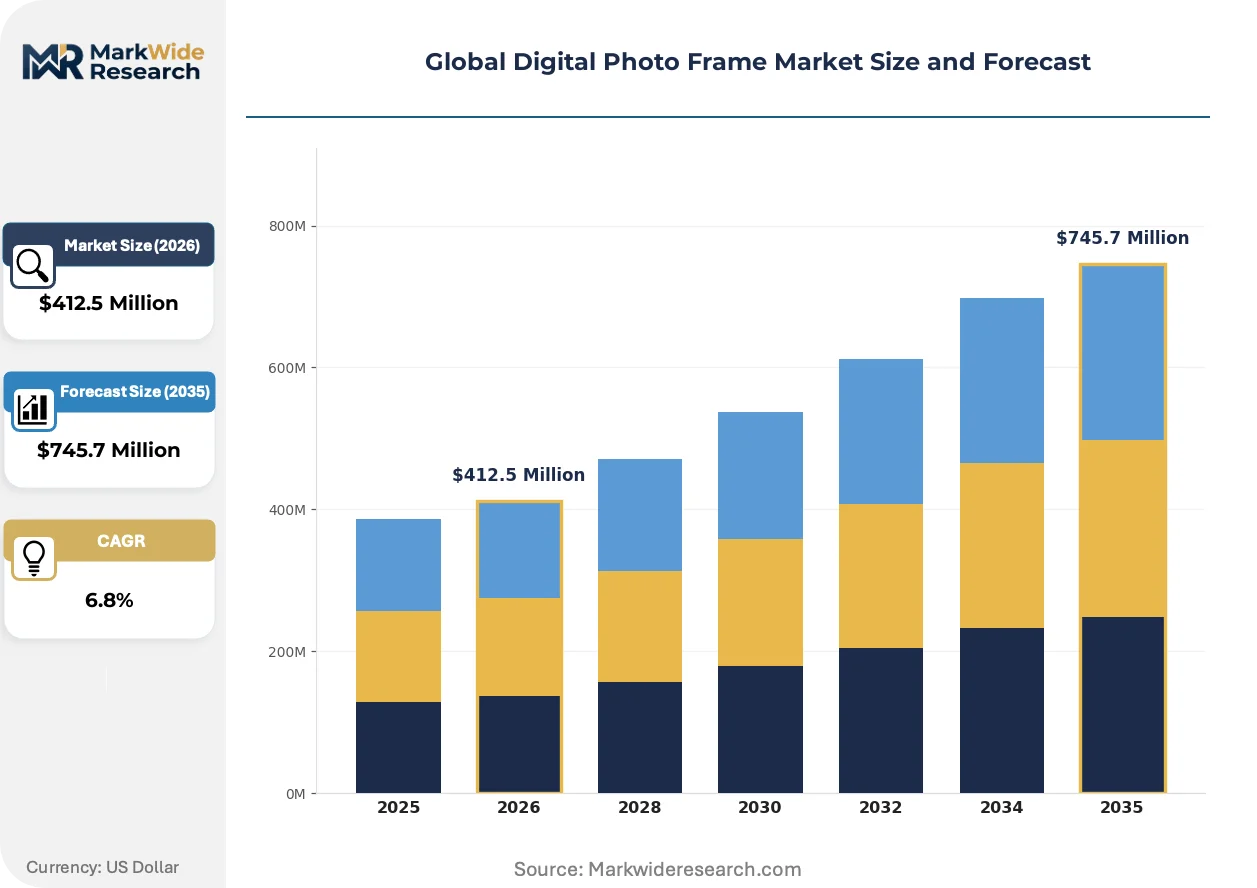
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Digital Frames, Touchscreen Frames, Wi-Fi Enabled Frames, HD Display Frames, Motion Sensor Frames Connectivity Technology: Wi-Fi, Bluetooth, USB, SD Card, Cloud Storage Usage Scenario: Home Decoration, Corporate Gifting, Event Displays, Retail Showcases, Educational Purposes End User: Individual Consumers, Small Businesses, Educational Institutions, Event Planners, Art Galleries |
| Companies Covered | Nixplay, Aura Home Inc., Skylight, Aluratek, ViewSonic Corporation, PhotoSpring Inc., Sungale, Lenovo Group Ltd., Netgear Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Photo Frame Market Shifts & Advancements
Cloud storage connectivity is rewriting how consumers interact with digital photo frames, shifting value from hardware specifications to software ecosystem integration. Three distinct forces are compressing product lifecycles and reshaping competitive differentiation.
Edge AI processing for automated photo curation is rewriting the user experience architecture in premium frames. Senior living facilities and hospitality venues are adopting these systems fastest, drawn to hands-free content management. This capability is compressing the feature gap between passive displays and interactive smart home hubs.
Japan's METI energy efficiency directives are tightening standby power limits for electronic displays sold in that market. Manufacturers must redesign power management circuits to maintain market access. Frames with motion-sensing auto-dim functions are capturing preferential positioning in Japanese retail channels.
Direct-to-consumer channel expansion is fragmenting traditional electronics retail dominance. Mass retail partnerships still anchor value-tier volume, but subscription-linked frame sales are displacing one-time hardware transactions. North American buyers show strongest appetite for bundled cloud storage and hardware financing models.
Global Digital Photo Frame Market Segmentation
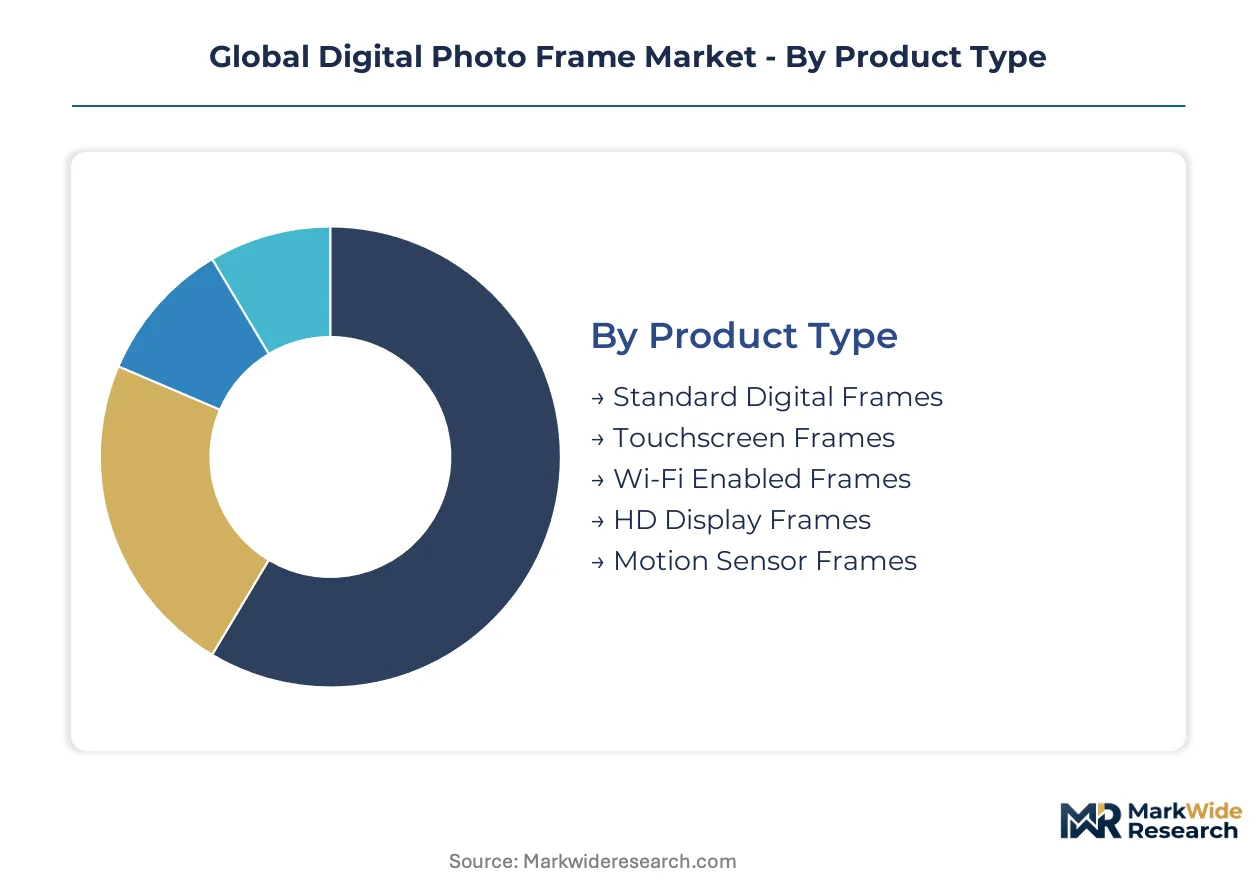
Digital photo frame segmentation reflects divergent paths between mass-market hardware commoditization and premium software-integrated experiences. Manufacturers calibrate feature bundles across product tiers while connectivity architectures determine recurring revenue potential versus one-time sales.
Product Type:
Customization intensity spans from plug-and-play standard units to sensor-integrated smart displays with embedded firmware complexity.
- Wi-Fi Enabled Frames:Cloud-syncing architecture enables over-the-air firmware updates and subscription-linked storage services. Demand concentrates in Germany, where aging populations and smart home penetration create dual adoption tailwinds for remote family photo sharing.
- Touchscreen Frames:Capacitive multi-touch panels support pinch-to-zoom and direct album management without companion apps. Corporate gifting segments in the United States favor these units for executive reception areas where interactivity signals technological sophistication.
- Standard Digital Frames:Basic LCD panels with USB or SD Card inputs serve price-sensitive retail channels.
- HD Display Frames:High-resolution panels target commercial viewing distances in hospitality and retail showcase applications.
- Motion Sensor Frames:Proximity-activated power management extends panel lifespan and reduces standby consumption under Japan's METI efficiency directives.
Leading the category by volume: Standard Digital Frames. Growing fastest: Wi-Fi Enabled Frames.
Connectivity Technology:
Transfer method selection correlates directly with customer lifetime value and aftermarket monetization potential.
- Cloud Storage:Persistent internet-linked libraries enable automatic photo curation and cross-device synchronization. Senior living facilities across France and Germany deploy these systems to reduce staff workload for content updates across hundreds of distributed displays.
- Wi-Fi:Direct smartphone-to-frame streaming bypasses physical media handling. North American direct-to-consumer channels bundle these models with financing plans and storage subscriptions.
- Bluetooth:Short-range pairing suits temporary event deployments with limited infrastructure.
- USB:Wired transfer persists in educational institutions with restricted network policies.
- SD Card:Removable storage remains standard for art galleries requiring offline curation control.
Volume leadership sits with Wi-Fi connectivity. Steepest expansion trajectory: Cloud Storage integration.
Usage Scenario:
Application context dictates durability specifications, content management workflows, and procurement decision-making authority.
- Home Decoration:Aesthetic chassis design and ambient light adaptation drive consumer selection criteria. German households with smart home ecosystems show strongest attachment to frames integrating with existing voice assistant networks.
- Corporate Gifting:Branded packaging and bulk configuration services differentiate B2B suppliers. United States enterprise buyers prioritize HD display quality for executive office installations.
- Event Displays:Temporary deployment models emphasize rapid setup and rental-friendly durability.
- Retail Showcases:High-brightness panels combat store lighting for product visualization.
- Educational Purposes:Ruggedized enclosures and simplified interfaces accommodate institutional procurement budgets.
Home Decoration commands the largest installed base. Corporate Gifting climbs fastest as subscription-linked sales displace one-time transactions.
End User:
Customer sophistication determines support requirements, price elasticity, and software ecosystem integration depth.
- Individual Consumers:Smartphone-native users prioritize seamless photo syncing and touchscreen interactivity. Cloud-first software architecture from direct-to-consumer brands captures premium pricing in this segment.
- Small Businesses:Cost-conscious buyers balance visual impact against IT maintenance overhead. Value-tier distribution through mass retail partnerships serves this group's procurement patterns.
- Educational Institutions:Procurement committees evaluate total cost of ownership including multi-year support contracts.
- Event Planners:Rental-oriented business models demand rapid deployment and retrieval logistics.
- Art Galleries:Color accuracy and anti-glare coatings support professional exhibition standards.
Individual Consumers represent the dominant revenue pool. Small Businesses expand most quickly as hospitality venues replace static signage with remotely updatable displays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display panel fabrication clusters in Taiwan and South Korea anchor upstream supply for frame assembly operations across consumer electronics manufacturing zones worldwide.
United States
Corporate gifting programs and smart home adoption drive procurement of Wi-Fi enabled frames with cloud synchronization. FCC electromagnetic emissions standards mandate pre-market testing cycles that compress product launch windows. California's tech-forward households concentrate demand for touchscreen variants integrating with voice assistant ecosystems.
Germany
Aging demographics and smart home penetration create dual tailwinds for connected frame adoption in senior living and family communication segments. EU Green Deal ecodesign requirements enforce lower-power LED panel specifications and recyclable chassis materials. Bavaria's electronics distribution hubs channel premium-tier products into Central European retail networks.
Japan
METI energy efficiency directives tighten standby power limits for electronic displays, favoring motion-sensing auto-dim functions. Senior care facilities deploy automated photo curation systems to reduce staff workload. Tokyo-Osaka retail corridors position energy-certified frames for preferential shelf placement.
China
Domestic manufacturing scale supports cost-optimized frame production for export markets and local consumption. MIIT standards govern wireless connectivity certification for internet-linked devices. Shenzhen's electronics assembly clusters integrate Taiwanese display panels into finished units for global distribution.
United Kingdom
Home decoration applications dominate consumer purchases as smart home ecosystem integration gains traction. CE marking under RoHS and REACH frameworks restricts hazardous substance use in chassis materials. London's design-conscious households drive demand for aesthetic chassis variants matching interior décor preferences.
Global Digital Photo Frame Market Competitive Landscape
Direct-to-consumer channel expansion dominates the current landscape as brands bypass traditional electronics retail. The vendor base organizes around three strategic tiers: cloud-first software specialists, mass-market hardware commoditizers, and display-technology integrators. Tiered competition separates premium subscription-linked models from value-tier one-time transactions. Geographic expansion and strategic partnerships constitute the primary competitive moves as manufacturers buffer supply chain concentration risks.
Among North American direct-to-consumer specialists, Nixplay and Aura Home Inc. occupy positions emphasizing software ecosystem integration over hardware specifications. Aluratek exemplifies the value-tier archetype through mass retail distribution partnerships. These three anchors illustrate how competitive positioning diverges between recurring-revenue cloud architectures and transaction-focused hardware sales.
| Leading Market Players |
|---|
| Nixplay |
| Aura Home Inc. |
| Skylight |
| Aluratek |
| ViewSonic Corporation |
| PhotoSpring Inc. |
| Sungale |
| Lenovo Group Ltd. |
| Netgear Inc. |
| Others |
Supply & Pricing Matrix
Display panel costs originating from Taiwanese and South Korean fabs cascade through three distinct pricing tiers, with cloud-integrated frames commanding subscription-linked premiums while basic USB-input units compete on landed cost efficiency in mass retail channels.
Pricing Analysis
Warranty and cloud storage bundling separates premium direct-to-consumer frames from unbundled value-tier alternatives sold through big-box retailers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by software ecosystem depth, display resolution grade, and after-sales service coverage. Cost compression in the standard tier is intensifying because mass-market brands are absorbing tariff exposure to maintain shelf placement. Small businesses and educational institutions exhibit highest price sensitivity, while corporate gifting buyers prioritize HD display quality over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from frame assemblers now mandate qualified supplier relationships across both Taiwanese and South Korean display panel manufacturers. Finished goods production draws from China, Vietnam, and Mexico assembly operations. Critical inputs include LCD/LED panels, ARM-based system-on-chips, and recyclable aluminum chassis materials. Single-source vulnerability concentrates around Taiwanese display fab capacity. Distribution runs through direct-to-consumer web channels, electronics retail chains, and B2B procurement platforms serving hospitality and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital photo frame sector is becoming a vertical-integration race, with cloud-first software capabilities emerging as the decisive downstream lever separating recurring-revenue winners from hardware-margin commoditizers.
For Market Incumbents: Acquire cloud storage infrastructure and firmware development talent to deepen software moats against smartphone substitution threats. Prioritize CE marking investment and modular repairability certification to preempt EU e-waste compliance mandates. Secure multi-year panel supply contracts with secondary South Korean suppliers to reduce single-factory risk exposure from Taiwanese concentration. For New Entrants and Emerging Players: Enter via corporate gifting and senior living facility segments, where hospitality venues and elderly care institutions remain underpenetrated versus saturated consumer channels. Target Germany specifically, where aging demographics and smart home penetration create dual adoption tailwinds with limited local competition. Pursue white-label partnerships with display integrators to bypass capital-intensive panel procurement barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor direct-to-consumer specialists with established cloud subscriber bases in North America, where financing-model adoption is accelerating hardware replacement cycles. Five-to-ten year viability hinges on software ecosystem lock-in rather than display specifications alone. Monitor EU AI Act implementation timelines as the critical inflection signal for automated curation feature compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Storage Integration | Subscription-linked revenue models displace one-time hardware transactions in North American direct-to-consumer channels. |
| Multi-Source Panel Procurement | Qualified secondary supplier relationships buffer against Taiwanese fab concentration risk under METI efficiency directives. |
| Modular Repairability Design | Component-swappable architectures preempt EU Green Deal ecodesign mandates for recyclable chassis materials. |
| Edge AI Curation Development | Automated photo selection capabilities compress the feature gap between passive displays and smart home hubs. |
| Direct-to-Consumer Channel Expansion | Web-native distribution bypasses mass retail margin compression while capturing financing-plan adoption. |
Research Methodology
Independent corroboration across primary interviews with digital photo frame product managers, cloud software architects, and hospitality procurement officers, combined with secondary validation through FCC equipment authorization databases, EU Ecodesign directive filings, and METI energy efficiency registrations, underwrites the qualitative findings. Bottom-up assembly cost modeling triangulates against top-down market sizing derived from display panel shipment data and consumer electronics retail audit streams.
Comparable-period anchoring to historical Wi-Fi frame adoption curves and cloud storage subscription attach rates structures the projection methodology across the analysis window. Segmentation dimensions include connectivity architecture, display resolution tier, end-use application, and regional regulatory cluster. CAGRs derive from panel cost trajectory assumptions, smart home penetration elasticity estimates, and senior care facility replacement cycle analysis for static signage.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EU AI Act enforcement acceleration or display fab disruption scenarios. Model outputs reflect documented assumptions regarding cloud service pricing stability and tariff regime continuity. A model refresh is warranted upon material change in Taiwanese panel supply availability or German smart home subsidy policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Digital Photography Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
Mobile Imaging Services Market
Imaging
Global Label-Free Array Systems Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
Document Imaging Market
Imaging
Handheld Retinal Scanners Market
Imaging
APAC Image Sensors Market
Imaging
Global 3D Camera Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
Industrial Machine Vision Market
Imaging
High Dynamic Range Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Vintage Cameras Market
Imaging
Global Thermal Imager Market
Imaging
Thermal Imaging Systems Market