
 Industrial X-Ray Inspection Equipment and Imaging Software Market | 2026-2036
Industrial X-Ray Inspection Equipment and Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial X-Ray Inspection Equipment and Imaging Software Market Intelligence
The gap between premium computed tomography systems and commodity digital radiography units is expanding as aerospace and electronics buyers demand sub-micron resolution while price-sensitive manufacturers settle for basic flaw detection. Nikon Corporation leverages its precision optics heritage to dominate high-end CT installations for turbine blade inspection. YXLON International anchors European market access through deep calibration partnerships with Germany's TÜV certification bodies. Varex Imaging controls the imaging detector supply layer, sustaining margin pools across multiple OEM channels.
Industrial X-Ray Inspection Equipment and Imaging Software encompasses hardware and software systems that generate, capture, and analyze X-ray images to detect internal defects without destroying test subjects, typically operating at tube voltages from 10 kV to 450 kV depending on material density and penetration depth. Digital Radiography now leads technology adoption as flat-panel detectors displace film cassettes, while Computed Tomography captures the fastest growth trajectory as automotive battery manufacturers adopt 3D void analysis for lithium-ion cell validation. Software Solutions increasingly concentrate margin pools as AI-driven defect classification commands recurring licensing fees atop hardware sales.
The FDA enforces 21 CFR Part 820 quality system regulations on medical-device-adjacent inspection workflows, while the EU Machinery Directive mandates CE-marked safety interlocks on all automated X-ray systems deployed in European manufacturing plants. Japan's METI administers NIST-traceable calibration standards that effectively gate market entry for foreign detector suppliers. Stakeholders must monitor how evolving battery safety regulations across multiple jurisdictions reshape CT throughput requirements and service contract structures.
Market Dynamics
The transition from analog film to digital flat-panel detectors has compressed inspection cycle times by an order of magnitude, forcing equipment vendors to rebuild service revenue models around software licensing rather than consumables.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE-marked automated X-ray systems are now compulsory for European manufacturing plants, creating replacement demand across Germany's automotive belt and Northern Italy's machinery clusters.
- Lithium-ion battery CT validation:Automotive battery manufacturers require 3D void analysis for electrode stack integrity, driving throughput upgrades at cell gigafactories in Japan and South Korea.
- Sub-micron resolution demand:Aerospace turbine blade inspection now requires computed tomography systems capable of detecting micro-cracks below 5 microns, pulling premium hardware into maintenance facilities.
Market Restraints
- Detector supply concentration:Amorphous silicon flat-panel production concentrates among three Asian substrate fabricators, exposing OEMs to 16-20 week lead time volatility.
- High-voltage tube import dependencies:Ceramic-metal seal technology for 300kV+ tubes remains captive to German and Japanese specialty vacuum suppliers, constraining system build rates.
- Substitution by ultrasonic phased arrays:Composite aerospace structures increasingly deploy automated ultrasonic testing for delamination detection, displacing X-ray in wing skin applications.
Strategic Opportunities
- India's electronics manufacturing clusters:Smartphone and semiconductor packaging investments under the PLI scheme create first-time demand for automated X-ray inspection in Gujarat and Tamil Nadu.
- AI-driven defect classification software:Machine learning models trained on proprietary void libraries enable recurring SaaS revenue atop hardware installations.
- Extended producer responsibility mandates:EU battery regulations requiring end-of-life material traceability are accelerating CT adoption for recycling feedstock characterization.
Industry Challenges
- Radiation safety officer certification timelines:Qualified personnel shortages in France and Germany delay system commissioning by 8-12 weeks despite installed hardware readiness.
- Legacy film archive digitization:Aerospace maintenance organizations face multi-year projects to convert decades of analog radiographs to DICONDE-compatible formats.
- Multi-modal system integration:Manufacturers struggle to synchronize X-ray CT data streams with coordinate measuring machines for unified dimensional reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial X-Ray Inspection Equipment and Imaging Software Market |
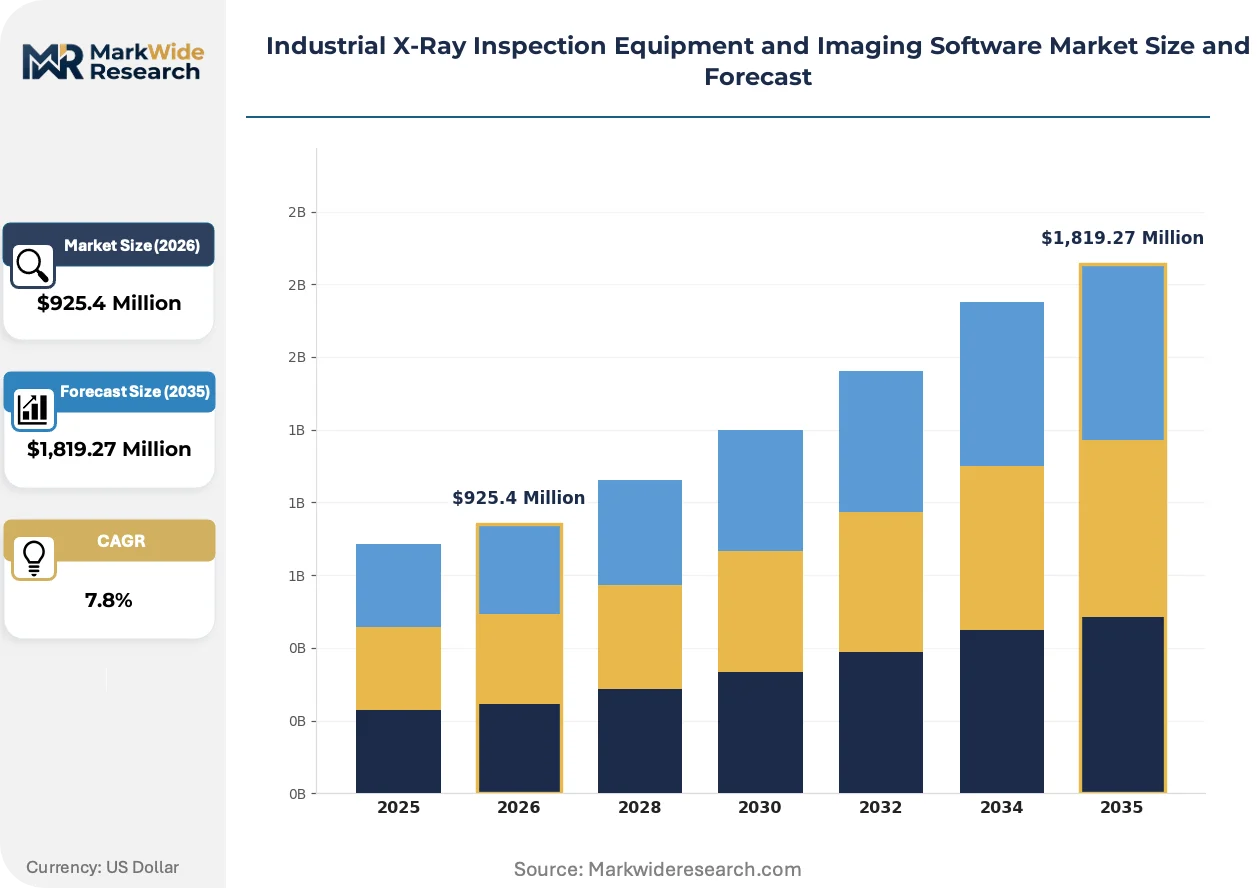
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $1,819.27 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, Software Solutions, Imaging Detectors, Accessories Technology: Digital Radiography, Computed Tomography, Film-based Imaging, Non-Destructive Testing End User: Aerospace, Automotive, Manufacturing, Electronics Application: Quality Control, Research & Development, Maintenance, Safety Inspections |
| Companies Covered | Nikon Corporation, North Star Imaging Inc., YXLON International, Carestream Health, Comet Yxlon, DÜRR NDT GmbH & Co. KG, Hamamatsu Photonics K.K., General Electric Company, Varex Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial X-Ray Inspection Equipment and Imaging Software Market Strategic Shifts & Innovations
Three interconnected developments are restructuring how inspection value is captured: computational methods replacing hardware differentiation, regulatory frameworks mandating digital traceability, and buyer procurement models decoupling capital expenditure from operational output.
Photon-counting detector arrays are decentralizing the traditional hierarchy between premium CT systems and commodity radiography units. These solid-state sensors discriminate X-ray energy levels at the photon level, enabling material-specific imaging without hardware filtration swaps. Battery manufacturers in South Korea are adopting this technology for rapid electrode density mapping, collapsing the functional gap between mid-range and high-end system tiers.
Japan's METI has tightened NIST-traceable calibration requirements for industrial X-ray systems used in medical-device-adjacent supply chains. The revised standards mandate annual third-party verification of dose consistency and geometric magnification accuracy. Foreign detector suppliers now face extended approval timelines, prompting domestic partnerships with JIS-certified calibration laboratories as a market entry prerequisite.
After-sales service unbundling is accelerating among European automotive suppliers. Rather than comprehensive maintenance contracts, buyers now procure tube replacement, detector refresh, and software updates as separate line items through competitive tender. This fragmentation is most pronounced in Germany's Mittelstand machine shops, where finance departments scrutinize inspection equipment total cost of ownership with renewed precision.
Industrial X-Ray Inspection Equipment and Imaging Software Market Segmentation
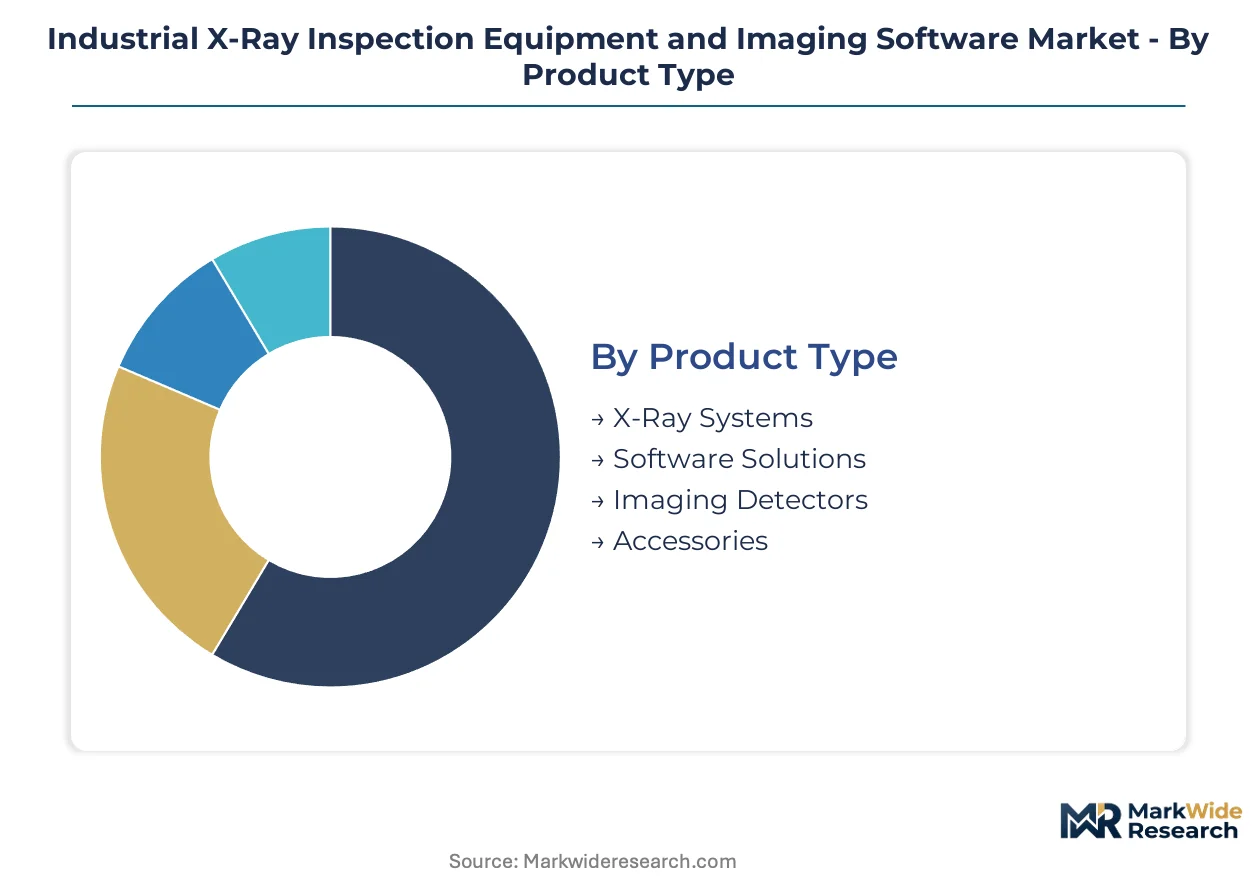
Industrial X-ray inspection markets fragment across hardware, software, and service layers with divergent margin structures. Equipment vendors now capture recurring revenue through detector refresh cycles and AI licensing rather than one-time system sales. Each segment category reflects distinct buyer procurement patterns shaped by regulatory compliance burdens and throughput requirements.
Product Type:
Supply concentration varies sharply across hardware versus software layers, with detector fabrication bottlenecks constraining system build rates while SaaS margins expand unchecked by physical capacity.
- X-Ray Systems:Integrated hardware platforms combining high-voltage tubes, mechanical manipulation stages, and radiation shielding. Aerospace maintenance facilities in Germany and Japan dominate procurement for turbine blade inspection, though ceramic-metal seal supply dependencies from German and Japanese vacuum specialists constrain delivery timelines.
- Software Solutions:AI-driven defect classification platforms commanding recurring licensing fees atop hardware installations. South Korean battery manufacturers drive fastest adoption for electrode void analysis, with machine learning models trained on proprietary image libraries creating customer switching costs.
- Imaging Detectors:Amorphous silicon flat-panel arrays and emerging photon-counting alternatives. Three Asian substrate fabricators control production, exposing OEMs to 16-20 week lead time volatility.
- Accessories:Calibration phantoms, radiation shielding components, and tube replacement units. After-sales unbundling in European automotive supply chains fragments procurement into competitive tender line items.
Today's leader: X-Ray Systems. Tomorrow's challenger: Software Solutions.
Technology:
Cost tier stratification separates premium sub-micron CT installations from commodity radiography units serving price-sensitive manufacturing segments.
- Digital Radiography:Flat-panel detector systems displacing film cassettes across automotive and electronics inspection workflows. Germany's automotive belt concentrates replacement demand as CE-marked automation becomes compulsory under EU Machinery Directive.
- Computed Tomography:3D reconstruction systems enabling internal void mapping without destructive sectioning. Lithium-ion cell gigafactories in Japan and South Korea deploy this technology for electrode stack validation, with throughput requirements reshaping service contract structures.
- Film-based Imaging:Analog radiography with silver halide cassettes and chemical processing. Legacy aerospace maintenance organizations face multi-year digitization projects to convert archives to DICONDE-compatible formats.
- Non-Destructive Testing:Broader modality category encompassing ultrasonic, eddy current, and radiographic methods. Composite aerospace structures increasingly favor automated ultrasonic testing for delamination detection, displacing X-ray in specific wing skin applications.
Digital Radiography holds installed base dominance. Computed Tomography climbs fastest on battery safety validation demand.
End User:
Application maturity diverges across sectors with decades of regulatory precedent versus emerging demand from electrification supply chains.
- Aerospace:Turbine blade inspection and airframe integrity verification with sub-5-micron resolution requirements. Maintenance facilities absorb premium CT hardware despite qualified radiation safety officer shortages delaying commissioning.
- Automotive:Powertrain component validation and battery cell inspection. India's PLI scheme investments in Gujarat and Tamil Nadu create first-time automated X-ray demand from smartphone and semiconductor packaging lines.
- Manufacturing:General industrial quality control across machinery and metal fabrication. Northern Italy's machinery clusters drive CE-marked system replacement under tightened EU safety mandates.
- Electronics:Semiconductor packaging and printed circuit board inspection. Japan's METI NIST-traceable calibration standards gate market entry for foreign detector suppliers.
Aerospace commands premium pricing. Electronics expands most quickly on miniaturization and packaging complexity.
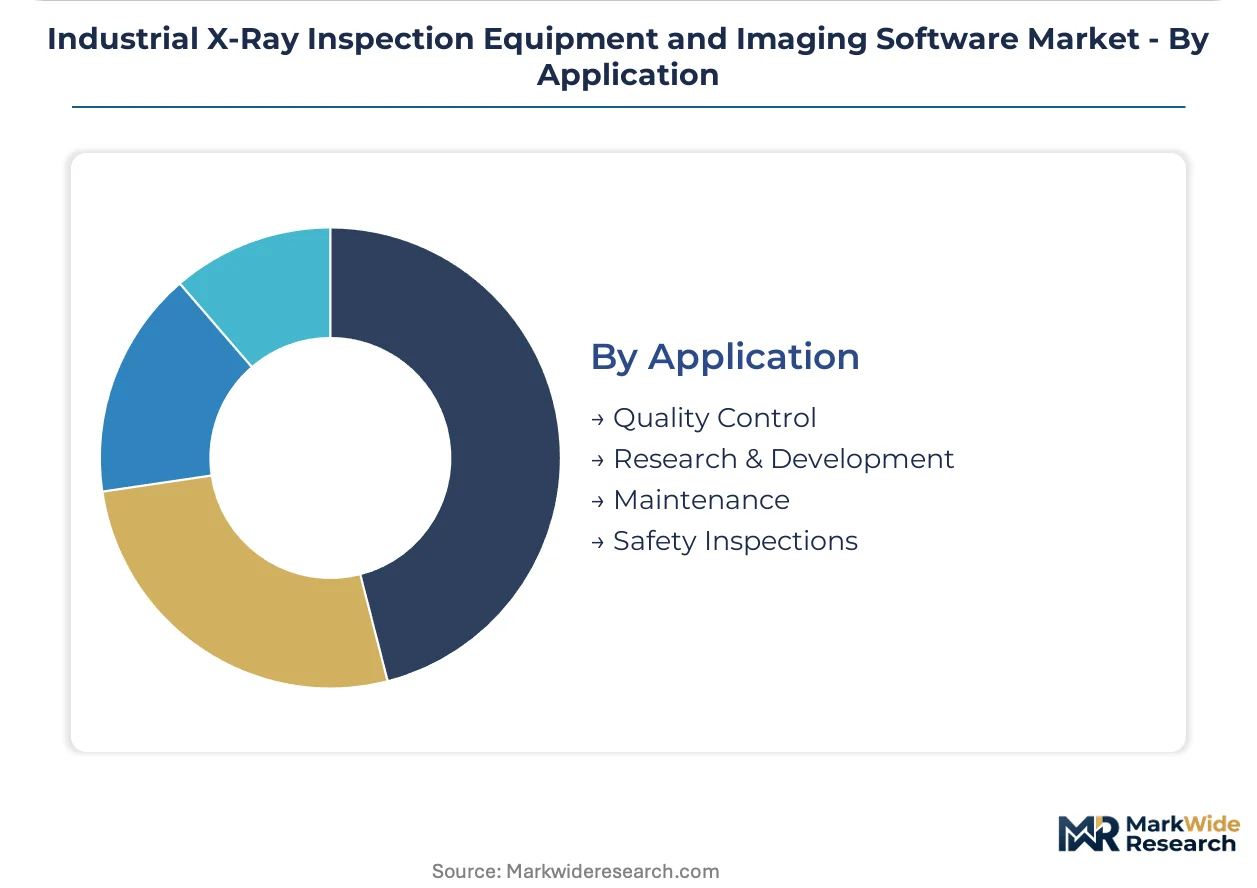
Application:
Customer type separation distinguishes capital-intensive manufacturing integration from research procurement with shorter decision cycles.
- Quality Control:In-line inspection integrated into production workflows. Automated systems with CE-marked safety interlocks dominate European manufacturing plant procurement.
- Research & Development:Materials characterization and prototype validation. Academic and corporate laboratories drive photon-counting detector adoption for material-specific imaging without hardware filtration swaps.
- Maintenance:Post-production defect detection in service environments. Legacy film archive digitization burdens aerospace maintenance organizations with extended conversion timelines.
- Safety Inspections:Regulatory compliance verification and certification support. EU battery regulations requiring end-of-life material traceability accelerate CT adoption for recycling feedstock characterization.
Quality Control anchors revenue volume. Safety Inspections gains regulatory tailwind from circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiation safety officer certification bottlenecks in France and Germany concentrate technical talent constraints, while Japan's precision calibration workforce anchors metrology standards for detector suppliers seeking market entry.
Germany
TÜV certification partnerships gate European market access for detector suppliers, while the EU Machinery Directive mandates CE-marked safety interlocks. Automotive belt manufacturers in Bavaria and Baden-Württemberg drive replacement demand as automated X-ray systems become compulsory in manufacturing plants.
Japan
Battery gigafactories require CT throughput upgrades for electrode stack validation, while METI administers NIST-traceable calibration standards. Precision electronics clusters in Kansai and Chubu face extended approval timelines for foreign detector suppliers, prompting domestic JIS-certified laboratory partnerships.
United States
Aerospace maintenance facilities absorb premium CT hardware for turbine blade inspection, while FDA enforces 21 CFR Part 820 quality system regulations on medical-device-adjacent workflows. Qualified radiation safety officer shortages delay system commissioning by 8-12 weeks despite installed hardware readiness.
South Korea
Automotive battery manufacturers deploy 3D void analysis for lithium-ion cell validation, while photon-counting detector adoption accelerates for electrode density mapping. Cell production facilities in Gyeonggi and Chungnam reshape service contract structures around throughput requirements.
India
Smartphone and semiconductor packaging investments create first-time automated X-ray demand, while the PLI scheme subsidizes electronics manufacturing infrastructure. Gujarat and Tamil Nadu clusters import inspection equipment as domestic fabrication capacity scales under production-linked incentive frameworks.
Industrial X-Ray Inspection Equipment and Imaging Software Market Key Industry Players
Top-tier vendors anchor the premium CT installation segment, while mid-tier specialists populate the digital radiography replacement cycle. The vendor base stratifies across precision optics heritage, European calibration access, and imaging detector supply layer control. Three archetypes dominate: precision equipment manufacturers leveraging optical heritage, regional system integrators with certification body relationships, and component suppliers capturing margin pools across multiple OEM channels. Competitive moves concentrate on strategic partnerships with standards bodies and backward integration into detector substrate fabrication.
Within the precision optics archetype, Nikon Corporation represents Japanese heritage in high-end CT installations. YXLON International and Comet Yxlon exemplify European vendors with deep calibration partnerships anchoring regional market access. Varex Imaging occupies a position within the component supply layer, sustaining margin pools across multiple OEM distribution channels without direct system competition.
| Leading Market Players |
|---|
| Nikon Corporation |
| North Star Imaging Inc. |
| YXLON International |
| Carestream Health |
| Comet Yxlon |
| DÜRR NDT GmbH & Co. KG |
| Hamamatsu Photonics K.K. |
| General Electric Company |
| Varex Imaging |
| Others |
Cost & Logistics Intelligence
High-purity tungsten price volatility cascades through X-ray tube manufacturing into three distinct pricing tiers: premium CT systems absorbing ceramic-metal seal premiums, mid-range radiography units competing on detector refresh cycles, and economy-tier film-based alternatives facing obsolescence pressure from regulatory mandates.
Pricing Analysis
Service bundling unbundling splits the installed base into comprehensive maintenance contracts versus à-la-carte procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked automation commanding hardware premiums and FDA-adjacent workflows sustaining software licensing fees. Cost compression in standard-tier radiography intensifies as Asian detector substrate supply expands. Price-sensitive Mittelstand machine shops in Germany drive procurement fragmentation, while aerospace maintenance facilities show minimal sensitivity to premium CT hardware costs.
Supply Chain Analysis
Freight cost escalation for vacuum-sealed ceramic-metal components from Germany and Japan amplifies lead time premiums on high-voltage tube assemblies. Amorphous silicon flat-panel substrate fabrication concentrates in South Korea, Taiwan, and China, drawing from specialty gas feedstocks and photolithography equipment. Single-source vulnerability around 300kV+ tube ceramic sealing technology exposes OEM build rates to German and Japanese vacuum specialist capacity. Distribution runs through direct OEM channels for premium CT systems and regional integrators for mid-range radiography replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
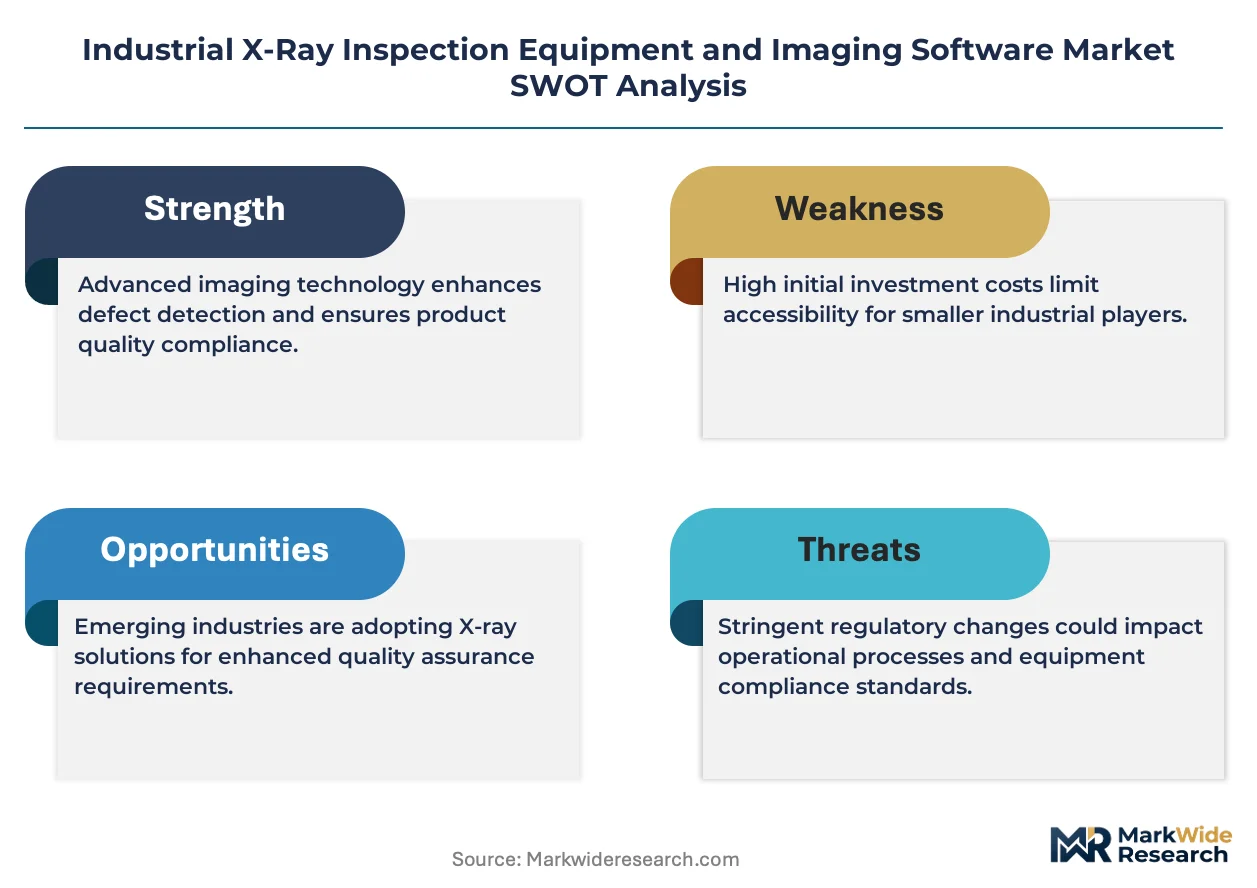
This market compounds steadily as battery safety regulations across multiple jurisdictions institutionalize CT validation into manufacturing workflows, creating recurring replacement demand with limited demand destruction risk.
For Market Incumbents: Anticipate photon-counting detector commoditization collapsing mid-tier hardware margins by deepening calibration partnerships with Japan's JIS-certified laboratories and Germany's TÜV bodies. Backward integration into detector substrate fabrication secures supply continuity against 16-20 week lead time volatility from Asian fabricators. For New Entrants and Emerging Players: AI-driven defect classification software offers the most penetrable wedge, targeting India's PLI-subsidized electronics clusters in Gujarat and Tamil Nadu with SaaS-first go-to-market models that bypass capital-intensive hardware manufacturing. Battery recycling feedstock characterization under EU extended producer responsibility mandates presents adjacent white-space. For Investors and Strategic Acquirers: Consolidation pressure builds where detector supply layer concentration meets fragmented European system integrator bases. Long-term viability favors component suppliers with captive OEM channel relationships over pure-play hardware vendors. Watch photon-counting detector patent filing velocity as inflection indicator for technology tier disruption timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Substrate Fabrication | Captive supply of amorphous silicon panels insulates OEMs from Asian fabricator lead time volatility. |
| AI Defect Classification Platform Launch | SaaS licensing atop hardware installations creates recurring revenue streams in South Korean battery gigafactories. |
| JIS-Certified Calibration Laboratory Partnership | Domestic Japanese partnerships satisfy METI NIST-traceable standards for foreign detector market entry. |
| CE-Marked Automation System Rollout | EU Machinery Directive compliance unlocks replacement demand across Germany's automotive belt. |
| Photon-Counting Detector Product Line Expansion | Material-specific imaging without hardware filtration swaps collapses functional gaps between system tiers. |
Research Approach
Multiple input streams — primary interviews with equipment procurement managers at aerospace maintenance facilities and battery gigafactories, technical discussions with radiation safety officers and calibration laboratory directors, and secondary validation against FDA 21 CFR Part 820 filings and EU Machinery Directive implementation guidance — were reconciled through bottom-up and top-down triangulation. Trade data from German and Japanese vacuum component exports, detector substrate import records, and SEC filings from listed imaging equipment vendors provided volume anchors.
Historical shipment data was cross-referenced against expert panel input from CT system architects and flat-panel detector manufacturing engineers. The analytical framework modeled demand across product type, technology tier, end-use sector, and geographic regulatory cluster throughout the forecast period. CAGRs were derived from segment-level buildups incorporating tube replacement cycle timing, software licensing renewal rates, and detector refresh demand from lithium-ion cell validation workflows.
The model holds under stable regulatory enforcement intensity; deviation in battery safety mandate timelines or photon-counting detector patent litigation outcomes would shift hardware replacement cadences. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Chemiluminescence Imaging Market
Imaging
Global 3D Camera Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Photoacoustic Microscope Market
Imaging
Digital Movie Cameras Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Handheld Retinal Scanners Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Global in Ceiling Camera Market
Imaging
Global Camera Module Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Side View Camera System Market
Imaging
Underwater Camera Market
Imaging
Widefield Imaging Systems Market
Imaging
Small CCTV Camera Market