
 Processor for Smartphones Market | 2026-2036
Processor for Smartphones Market Size, Share, and Industry Trends Forecast 2026-2036
Processor for Smartphones Market Insights
Direct procurement between smartphone OEMs and foundry partners is rewriting traditional semiconductor distribution. Qualcomm leverages its Snapdragon platform to sustain design-win dominance across Android flagships. MediaTek competes aggressively in mid-tier and emerging market segments with density-optimized SoC architectures. Apple anchors vertical silicon strategy through in-house processor design, minimizing external supplier dependency.
A smartphone processor is a system-on-chip integrating CPU cores, GPU, modem, and neural processing unit onto a single die, typically manufactured on sub-5nm process nodes with transistor densities exceeding 100 million per square millimeter, enabling real-time AI inference and 4K video encoding for mobile computing. Application processors lead revenue contribution as OEMs prioritize on-device generative AI capabilities, while AI processors represent the fastest-expanding margin pool as NPU TOPS benchmarks become primary purchase criteria. ARM architecture dominates licensing across the ecosystem, though RISC-V adoption gains traction among cost-sensitive vendors seeking to reduce royalty burdens.
TSMC's fabrication dominance faces scrutiny from US CHIPS Act domestic production incentives and EU Chips Act sovereignty mandates, both reshaping geographic allocation of leading-edge capacity. China's MIIT enforces local content requirements and GB standards compliance for processors deployed in domestic smartphone models, constraining market access for non-certified foreign designs. Stakeholders must monitor foundry node roadmaps, export control classifications, and OEM silicon self-sufficiency timelines to anticipate supply allocation shifts.
Market Dynamics
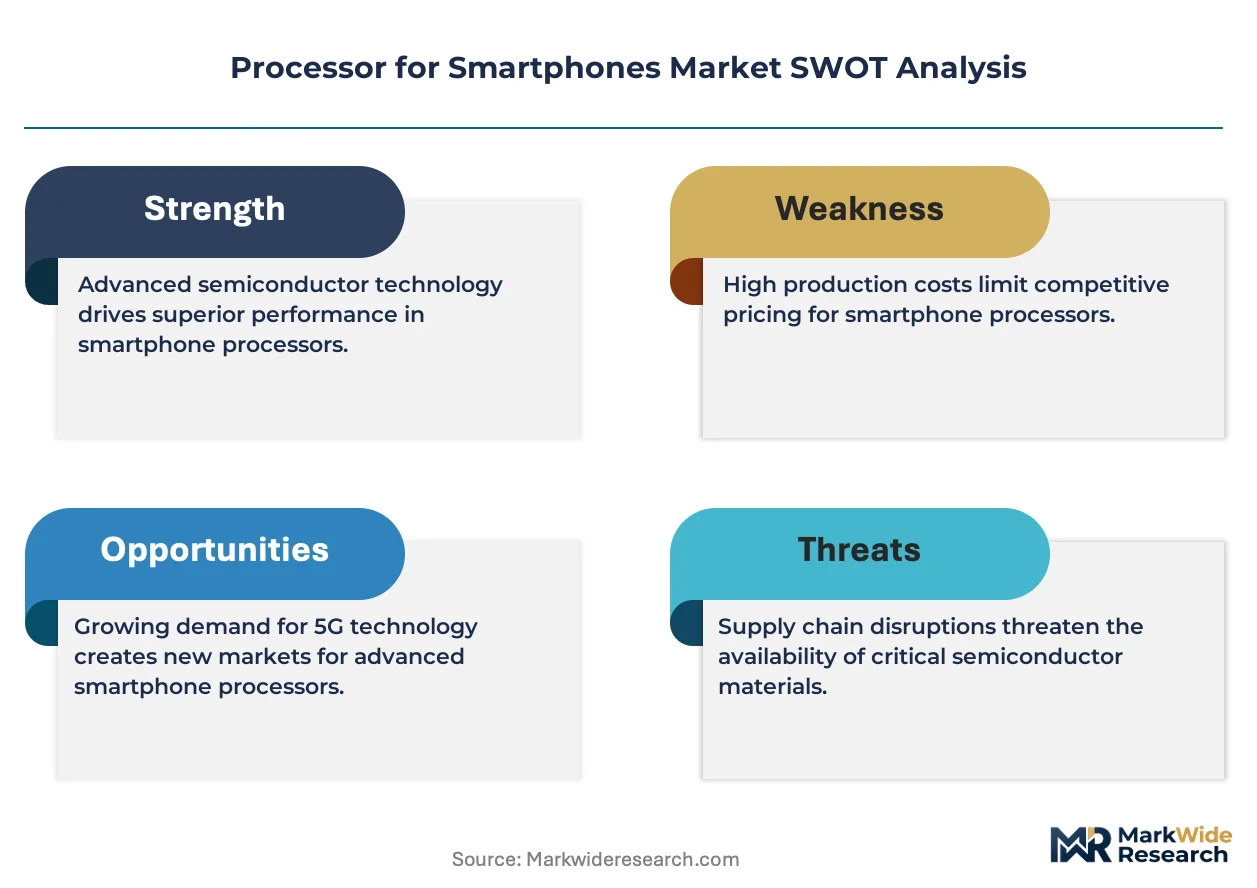
On-device generative AI capabilities are forcing a node shrinkage race among foundry partners, with transistor density benchmarks now determining OEM design-win allocation before silicon tape-out.
Growth Catalysts
- EU CSRD compliance mandates:Semiconductor vendors face disclosure requirements on supply chain emissions, accelerating investment in renewable-powered fabrication facilities across the Netherlands and Ireland.
- Sub-3nm process node maturation:Gate-all-around transistor architectures enable 40% power efficiency gains, pulling flagship OEMs toward annual refresh cycles for AI inference workloads.
- China MIIT local content rules:Domestic certification requirements for processors deployed in PRC smartphone models create captive demand for GB-standard-compliant designs.
Market Restraints
- Extreme ultraviolet lithography equipment concentration:ASML's monopoly on EUV scanners creates single-source dependency for sub-7nm production, constraining capacity expansion timelines.
- Neon and palladium supply volatility:Ukrainian neon purification facilities and Russian palladium exports face geopolitical disruption, inflating input costs for advanced node manufacturing.
- Export control classification friction:US Bureau of Industry and Security restrictions on semiconductor manufacturing equipment complicate technology transfer to specific foundry locations.
Strategic Opportunities
- India PLI scheme incentives:Production-linked incentive structures for electronics manufacturing attract assembly and test operations, creating regional hub potential for mid-tier processor packaging.
- RISC-V open instruction set architecture:Royalty-free licensing models enable cost-sensitive vendors to bypass ARM fees, opening white space in budget smartphone segments.
- Automotive-grade processor crossover:Functional safety certification expertise from automotive SoC design transfers to ruggedized industrial smartphone applications requiring ISO 26262 compliance.
Industry Challenges
- Chiplet integration complexity:Multi-die packaging architectures require new thermal management and interconnect verification workflows, extending time-to-market for heterogeneous designs.
- Advanced packaging talent scarcity:3D stacking and hybrid bonding expertise concentrates among a limited pool of engineers, inflating compensation costs for packaging development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processor for Smartphones Market |
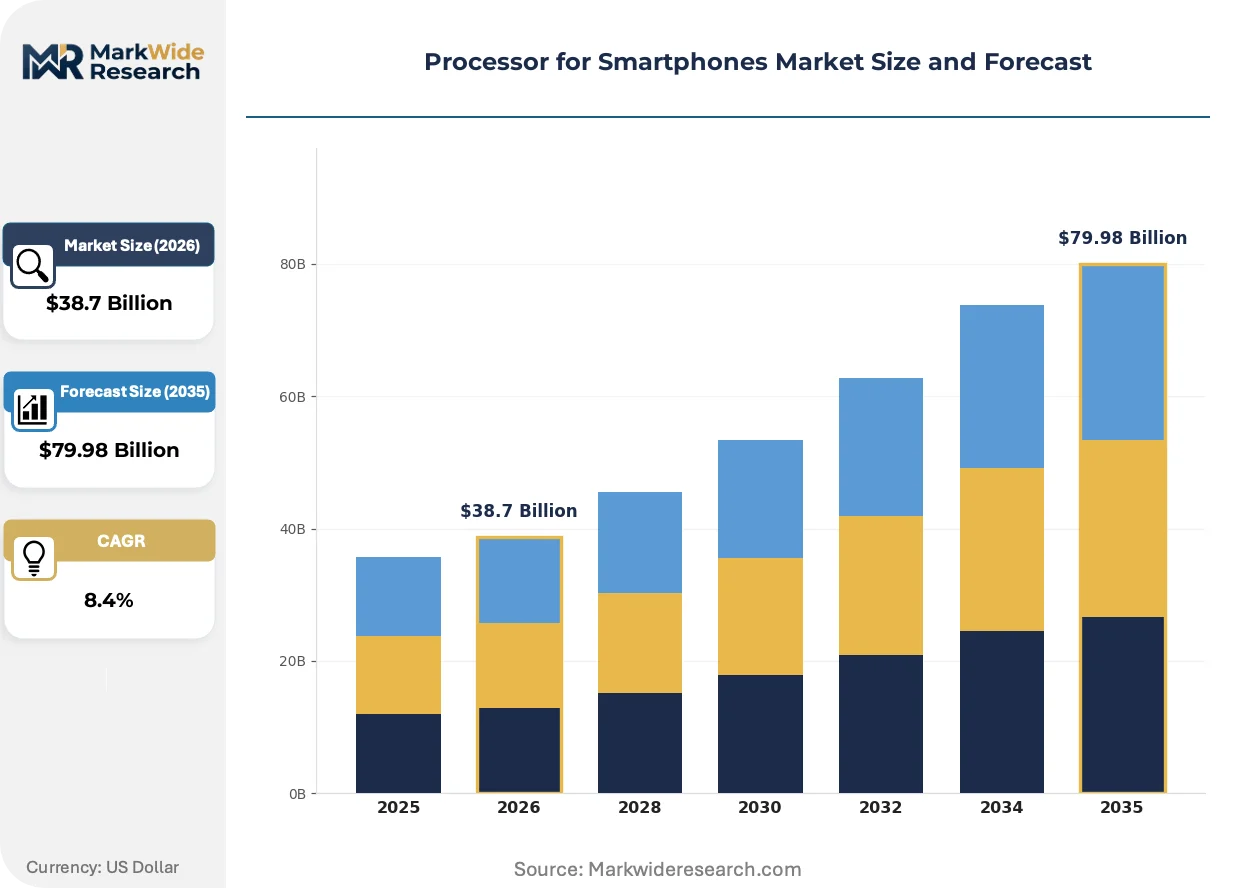
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Application Processor, Modem Processor, Graphics Processor, AI Processor Technology: ARM, x86, RISC, MIPS End User: Consumer Electronics, Enterprises, Developers, OEMs Manufacturing Stage: Wafer Fabrication, Packaging, Testing, Assembly |
| Companies Covered | Qualcomm, MediaTek, Apple, Samsung Electronics, UNISOC, HiSilicon, Google, ARM Holdings, TSMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processor for Smartphones Market Trends and Innovations
Neural processing unit integration is redefining competitive differentiation, with TOPS-per-watt benchmarks displacing raw clock speed as the primary procurement criterion among flagship OEMs.
Gate-all-around transistor technology is rendering obsolete FinFET architectures at nodes below 3nm. Samsung Electronics and TSMC have both committed to GAA roadmaps for 2025-2026 production ramps, with Apple and Qualcomm securing early allocation for premium tier launches. The structural compression of power envelopes is rendering obsolete thermal design constraints that previously limited on-device AI model complexity.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing fluorinated polymer replacements in semiconductor etching processes. ECHA enforcement timelines compress supplier qualification windows, with German and French chemical vendors accelerating PFAS-free precursor development. Advanced node foundries in Belgium and the Netherlands face the highest compliance cost exposure due to existing process chemistry dependencies.
Direct foundry contracting is displacing traditional distributor relationships for high-volume smartphone OEMs. Procurement teams at tier-one Android manufacturers now negotiate wafer starts directly with TSMC and Samsung Foundry, bypassing legacy semiconductor distribution channels. The behavior is most visible in South Korea and Taiwan, where supply security concerns have compressed decision cycles from quarterly to monthly allocation reviews.
Processor for Smartphones Market Segmentation
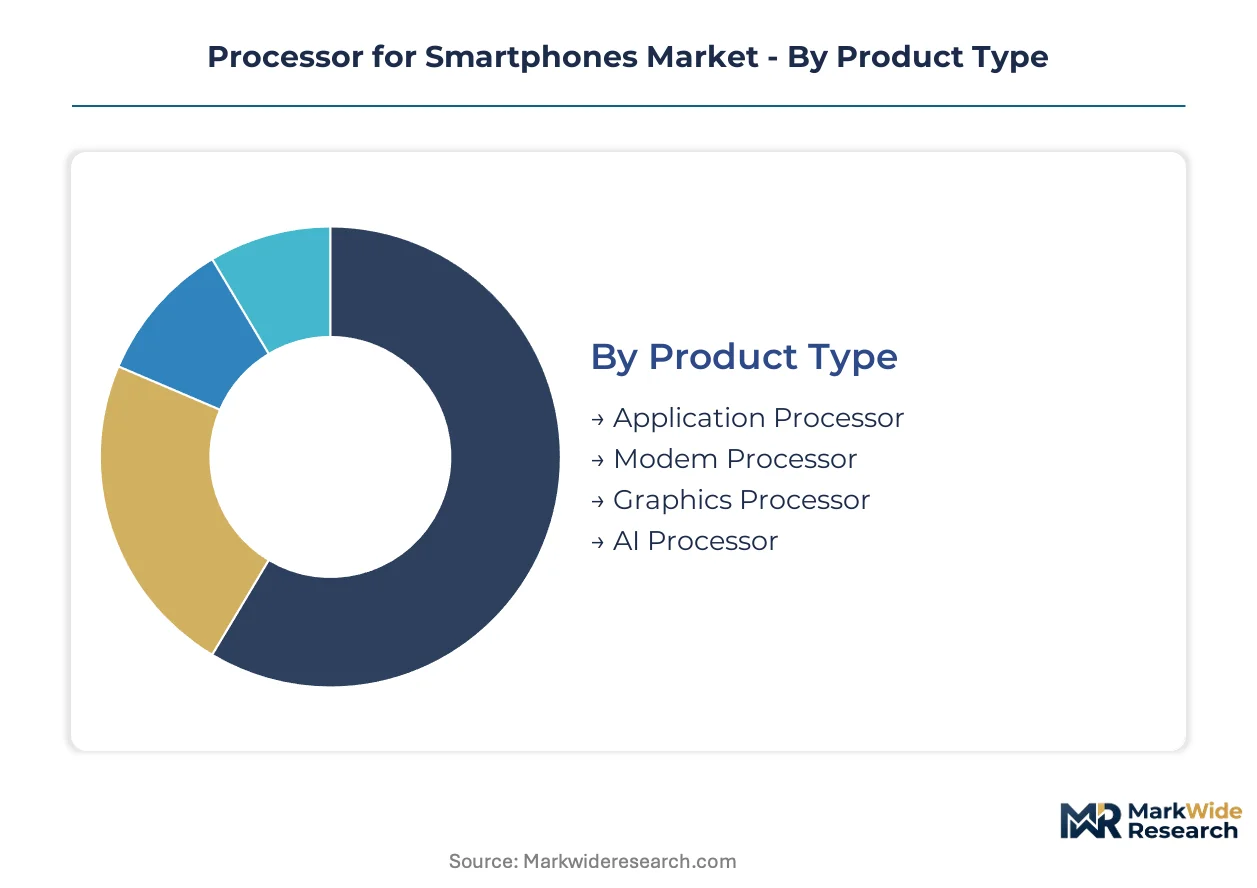
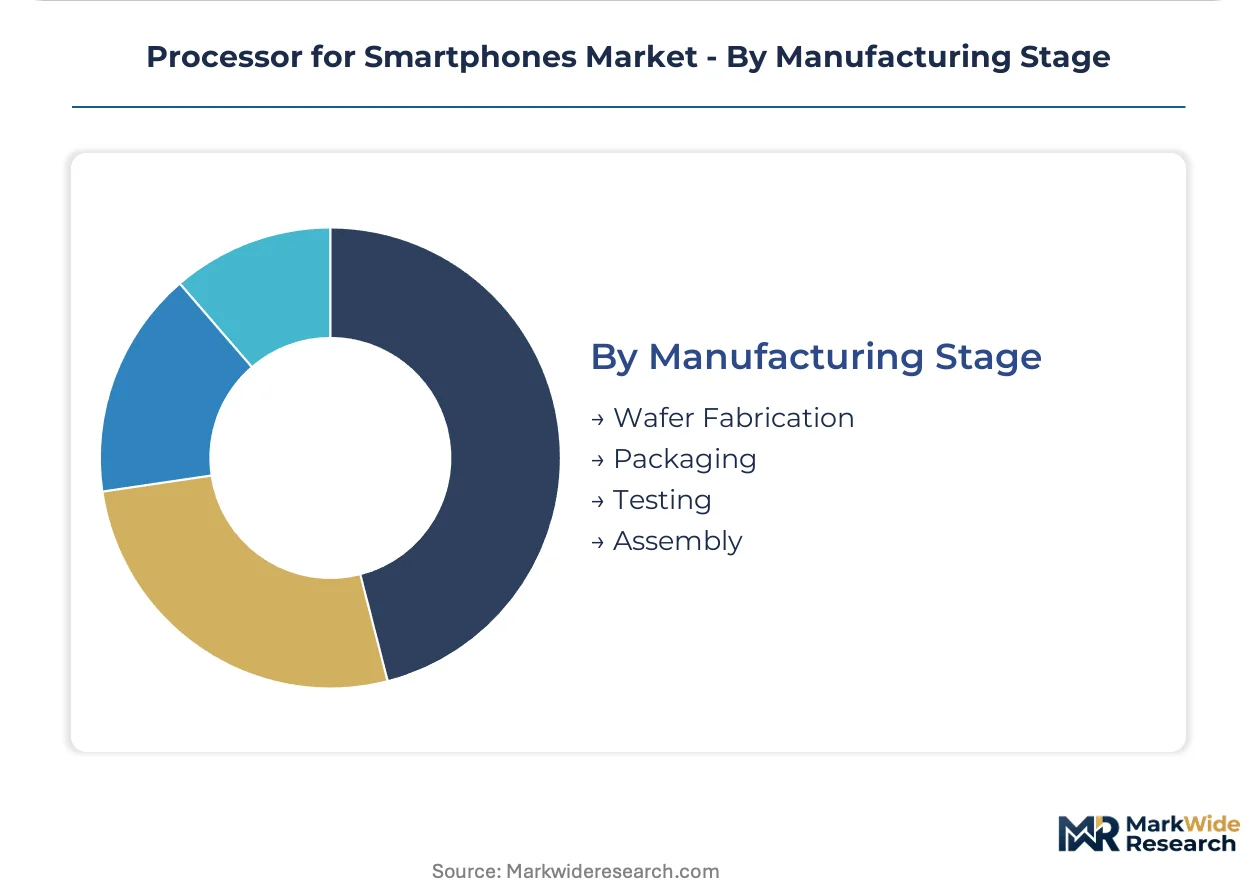
Processor segmentation dictates foundry allocation priority, with product type and manufacturing stage determining which OEMs secure sub-3nm capacity. Technology architecture choices lock vendors into royalty structures that persist across device generations. End-user concentration shapes die size and thermal envelope specifications.
Product Type:
After-sales service intensity varies sharply across processor categories, with AI processors requiring firmware update pipelines and modem processors demanding carrier certification support.
- Application Processor:Central SoC integrating CPU, GPU, and memory controller onto monolithic die. Flagship OEMs in South Korea and Taiwan prioritize on-device generative AI inference capabilities, driving allocation battles for TSMC's leading-edge nodes. By volume, Application Processor leads. By growth pace, AI Processor is ahead.
- AI Processor:Dedicated neural processing unit or AI accelerator die, either discrete or integrated. China's MIIT local content rules create captive demand for GB-standard-compliant NPU designs in domestic smartphone models.
- Modem Processor:Baseband and RF transceiver silicon handling cellular connectivity standards. Qualcomm and MediaTek dominate through integrated modem-AP architectures.
- Graphics Processor:GPU cores for rendering, gaming, and computational photography. Samsung Electronics and Apple secure custom GPU IP for premium tier differentiation.
Margin concentration follows AI acceleration capabilities, with NPU-enabled dies commanding wafer priority at foundries.
Technology:
Instruction set architecture selection determines licensing cost structures and software ecosystem compatibility across the smartphone stack.
- ARM:Dominant RISC architecture licensing across Android and iOS ecosystems. TSMC and Samsung Foundry optimize PDKs for ARM core implementations, capturing volume concentration in China, South Korea, and Taiwan.
- x86:Intel and AMD mobile processor attempts have failed to displace ARM in smartphones. By volume, ARM leads. By growth pace, RISC-V is ahead.
- RISC:Open-source RISC-V gaining traction among cost-sensitive vendors seeking royalty reduction. Indian PLI scheme beneficiaries evaluate RISC-V for mid-tier smartphone targeting.
- MIPS:Legacy architecture with minimal smartphone presence, now concentrated in embedded networking applications.
Architecture migration timelines determine competitive positioning for emerging market entrants.
End User:
Customer type dictates die customization depth, with enterprise and developer segments requiring extended software support commitments.
- Consumer Electronics:Mass-market smartphone OEMs driving volume procurement. Apple, Samsung Electronics, and Xiaomi anchor demand through direct foundry contracting.
- Enterprises:Ruggedized and secure smartphone deployments requiring extended lifecycle support. By volume, Consumer Electronics leads. By growth pace, Developers are ahead.
- Developers:Reference design platforms and dev-kit processors for AI model optimization. Qualcomm and MediaTek maintain developer program investments.
- OEMs:Vertical integrators designing in-house processors, with Apple and Samsung Electronics minimizing external supplier dependency.
Procurement concentration among top-five smartphone OEMs compresses vendor negotiation leverage.
Manufacturing Stage:
Process step specialization determines geographic concentration of value capture, with wafer fabrication anchoring in East Asia.
- Wafer Fabrication:Leading-edge transistor patterning at sub-5nm nodes. TSMC's N3E process dominates flagship allocation, with Samsung Electronics Foundry competing at 3nm GAA.
- Packaging:Advanced substrate and interconnect technologies enabling chiplet integration. By volume, Packaging leads. By growth pace, Wafer Fabrication is ahead.
- Testing:Wafer probe and final test operations for yield verification. ASE and Amkor concentrate OSAT capacity in Taiwan and South Korea.
- Assembly:Die attach, wire bonding, and module integration. India's PLI scheme attracts assembly and test operations for mid-tier processor packaging.
Capital intensity gradients across stages drive foundry and OSAT specialization strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung harbor container throughput anchors East Asia's semiconductor logistics corridor, with dedicated wafer shipment lanes connecting TSMC's Fab 18 to downstream packaging facilities across the Taiwan Strait.
China
Domestic smartphone OEM procurement concentrates on Beijing and Shenzhen design houses. MIIT enforces GB standard certification for processors deployed in PRC smartphone models, constraining market access for non-compliant foreign designs. Yangtze River Delta fabrication clusters in Shanghai and Wuxi expand mature node capacity for local supply security.
South Korea
Samsung Electronics anchors captive demand through vertical silicon integration for Galaxy flagship lines. Korean Ministry of Trade, Industry and Energy (METI) coordinates CHIPS Act alignment funding for domestic foundry expansion. Seoul Capital Area R&D complexes in Suwon and Hwaseong drive gate-all-around transistor process development.
United States
Qualcomm's San Diego headquarters sustains fabless design-win dominance across Android flagships. CHIPS Act domestic production incentives reshape geographic allocation of leading-edge capacity, with Intel Foundry Services securing federal fabrication subsidies. Arizona TSMC Fab 21 construction advances N4 process localization for North American supply security.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor upstream materials and equipment supply chains for advanced node manufacturing. METI coordinates semiconductor supply chain resilience initiatives with US and EU counterparts. Kyushu-based Sony image sensor fabs diversify into co-packaged logic for smartphone camera modules.
India
PLI scheme production-linked incentives attract assembly and test operations for mid-tier processor packaging. Ministry of Electronics and Information Technology (MeitY) mandates phased manufacturing program compliance for domestic smartphone production. Karnataka and Tamil Nadu electronics manufacturing clusters in Bengaluru and Chennai expand OSAT capacity for regional hub development.
Processor for Smartphones Market Competitive Landscape
On the supply side, the industry is consolidating around fabless design houses with direct foundry contracting relationships, compressing traditional semiconductor distribution channels. Two strategic archetypes dominate: vertically integrated OEMs with captive silicon divisions, and pure-play fabless vendors licensing ARM cores for merchant market supply. Competitive moves center on node allocation pre-commitments at TSMC and Samsung Foundry, plus NPU TOPS benchmark escalation for generative AI positioning.
Among fabless semiconductor vendors, Qualcomm, MediaTek, and Apple occupy distinct competitive positions. Qualcomm exemplifies the merchant-market platform vendor archetype through Snapdragon ecosystem licensing. MediaTek represents density-optimized SoC architecture specialization for mid-tier and emerging market segments. Apple anchors the vertical integration archetype through in-house processor design, minimizing external supplier dependency for iOS device silicon.
| Leading Market Players |
|---|
| Qualcomm |
| MediaTek |
| Apple |
| Samsung Electronics |
| UNISOC |
| HiSilicon |
| ARM Holdings |
| TSMC |
| Others |
Pricing and Supply Chain Analysis
TSMC's monopoly on sub-3nm wafer starts concentrates upstream supply power, pushing margin pools downstream toward AI-capable NPU designs and firmware update subscriptions that outpace hardware ASP erosion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with Qualcomm and MediaTek differentiating by NPU TOPS benchmarks and GB standard certification tiers. Price differentiation hinges on volume scale and after-sales firmware support commitments, with flagship OEMs least sensitive and emerging market white-label vendors most exposed. Cost compression in mid-tier 5-7nm nodes is intensifying because MediaTek density-optimized architectures erode per-unit silicon premiums.
Supply Chain Analysis
Neon purification feedstock from Ukrainian facilities and palladium extraction from Russian sources anchor raw material dependencies for EUV lithography and advanced etching chemistry. Wafer fabrication concentrates in Taiwan, South Korea, and the United States, drawing from ASML's single-source EUV scanner monopoly and Shin-Etsu Chemical's silicon wafer supply. Single-source vulnerability on EUV equipment creates capacity allocation chokepoints. Distribution runs through direct foundry contracting that bypasses legacy semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from AI model optimization subscriptions and carrier certification support expands faster than merchant SoC hardware sales, reframing processor vendors as recurring-revenue platforms.
For Market Incumbents: Insulate design-win allocation through pre-commitment contracts at TSMC N3E and Samsung Foundry 3nm GAA nodes, locking capacity before RISC-V entrants achieve process optimization. Backward integration into custom NPU IP reduces ARM royalty exposure. Defensive patent clustering around gate-all-around transistor implementations blocks emerging fabless competitors from sub-3nm parity. For New Entrants and Emerging Players: India's PLI scheme assembly and test clusters offer underpenetrated white space for mid-tier RISC-V SoC packaging, with MeitY phased manufacturing compliance creating captive local demand. Target ruggedized enterprise smartphone segments requiring ISO 26262 functional safety certification, where Qualcomm and MediaTek maintain minimal dedicated investment. Lead with dev-kit platforms that enable AI model optimization services, converting hardware sales into recurring firmware revenue. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed OSAT specialists holding advanced packaging expertise in 3D stacking and hybrid bonding. Five-to-ten year viability favors foundry-adjacent packaging houses with captive demand from Apple and Samsung Electronics vertical integration strategies. Watch NPU TOPS-per-watt benchmark escalation as the inflection signal for generative AI inference capability gaps between tier-one and tier-two fabless vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Contracting | Bypasses legacy distribution and secures sub-3nm wafer allocation for flagship OEMs. |
| NPU IP Development | Reduces ARM royalty burden while enabling on-device generative AI differentiation. |
| RISC-V Architecture Migration | Eliminates instruction set licensing fees for cost-sensitive mid-tier smartphone targeting. |
| Advanced Packaging Capacity Buildout | Captures value from chiplet integration complexity that concentrates expertise among limited OSATs. |
| GB Standard Certification Investment | Unlocks MIIT-compliant processor sales into China's captive domestic smartphone market. |
Research Methodology
Initial hypotheses were tested against primary input from fabless semiconductor design executives, foundry capacity planning directors, smartphone OEM procurement leads, and OSAT operations managers, then refined through secondary validation across TSMC and Samsung Electronics investor disclosures, MIIT GB standard certification databases, SEC semiconductor filings, and EU CHIPS Act implementation reports. Bottom-up die shipment modeling and top-down OEM revenue allocation were triangulated for cross-verification.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, instruction set architecture, manufacturing stage, and end-user concentration. CAGRs were derived from node-specific wafer start projections and NPU-enabled smartphone penetration curves. Forecast inputs incorporated EUV scanner delivery schedules and REACH PFAS restriction compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese foundry entrants or accelerated RISC-V ecosystem maturation would shift outcomes beyond modeled ranges. Cross-checking against SEMI equipment billings and foundry utilization rate disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Singapore Data Center Processor Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Spain Data Center Processor Market
Chipset and Processors
Wearable Processor Market
Chipset and Processors
Power Architecture Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Secure Microcontrollers/Processors Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Edge AI Processor Market