
 Global Anesthesia Gas Blender Market | 2026-2036
Global Anesthesia Gas Blender Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anesthesia Gas Blender Market Foresight
Hospital procurement channels for anesthesia gas blenders is rewriting how manufacturers reach end users, with group purchasing organizations and direct institutional contracts displacing traditional distributor relationships. medin Medical Innovations GmbH leverages its pediatric ventilation specialization to sustain premium positioning in neonatal intensive care settings. Flow-Meter S.p.A. anchors its competitive stance through precision pneumatic engineering capabilities developed across decades of Italian manufacturing. Dameca A/S differentiates via integrated anesthesia workstation ecosystems that bundle blenders with ventilator and monitoring platforms.
An anesthesia gas blender is a precision medical device that combines oxygen, nitrous oxide, and volatile anesthetic agents at controlled flow rates typically ranging from 0.1 to 15 liters per minute to deliver therapeutically accurate gas mixtures to patients during sedation or surgery. The device employs proportional mixing valves, electronic flow sensors, and feedback control loops to maintain target concentrations regardless of downstream pressure fluctuations or supply variations. Continuous blenders dominate current installed bases due to their reliability in high-throughput operating rooms, while electronic technology variants are capturing disproportionate investment as hospitals prioritize digital integration with anesthesia information management systems. Proportioning systems command attention in ambulatory surgery centers seeking compact footprints without sacrificing precision.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation's Class IIa classification requirements impose stringent biocompatibility, electrical safety, and software validation standards that filter market entrants and extend product development cycles. ISO 80601-2-13 standards for anesthetic workstations further constrain design choices around gas mixing accuracy and alarm functionality. Stakeholders must monitor evolving cybersecurity guidance from FDA and notified bodies as networked blender systems become standard in connected operating rooms.
Market Dynamics
Hospital procurement consolidation is concentrating purchasing power among integrated delivery networks, compressing vendor margins while elevating technical specifications for anesthesia gas blenders across tertiary care systems.
Growth Catalysts
- Surgical Volume Recovery:Elective procedure backlogs in the United States and Germany are driving replacement cycles for aging anesthesia infrastructure in high-throughput operating suites.
- EU Medical Device Regulation:MDR Class IIa certification requirements are filtering marginal competitors and expanding addressable market for compliant manufacturers with notified body relationships.
- Digital Integration Mandates:Anesthesia information management systems in Chinese tertiary hospitals are specifying networked blenders with HL7 FHIR connectivity as procurement prerequisites.
Market Restraints
- Precision Component Concentration:Proportional mixing valves and thermal mass flow sensors concentrate among German and Japanese specialty suppliers, creating single-source vulnerability.
- Volatile Anesthetic Agent Pricing:Sevoflurane and desflurane supply contracts with pharmaceutical manufacturers absorb 35-50% of total anesthesia system operating costs, constraining capital equipment budgets.
- ISO 80601-2-13 Validation Burden:Third-party electrical safety and software lifecycle documentation requirements extend product development timelines by 14-18 months for new market entrants.
Strategic Opportunities
- India Tertiary Expansion:Government medical college hospital modernization programs under the Pradhan Mantri Swasthya Suraksha Yojana are creating first-time installed base opportunities in 22 new AIIMS-equivalent institutions.
- Ambulatory Surgery Center Proportioning Systems:Compact footprint blenders with integrated scavenging are capturing outpatient procedural volume migrating from inpatient settings in the United States.
- FDA Cybersecurity Guidance:Premarket submission requirements for networked respiratory devices are creating competitive moat for manufacturers with embedded security engineering capabilities.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Cross-functional expertise combining pneumatic systems, embedded software, and clinical workflow optimization remains concentrated among legacy anesthesia equipment specialists.
- Legacy System Interoperability:Retrofitting electronic blenders into 1990s-era anesthesia workstations requires proprietary adapter development and field validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anesthesia Gas Blender Market |
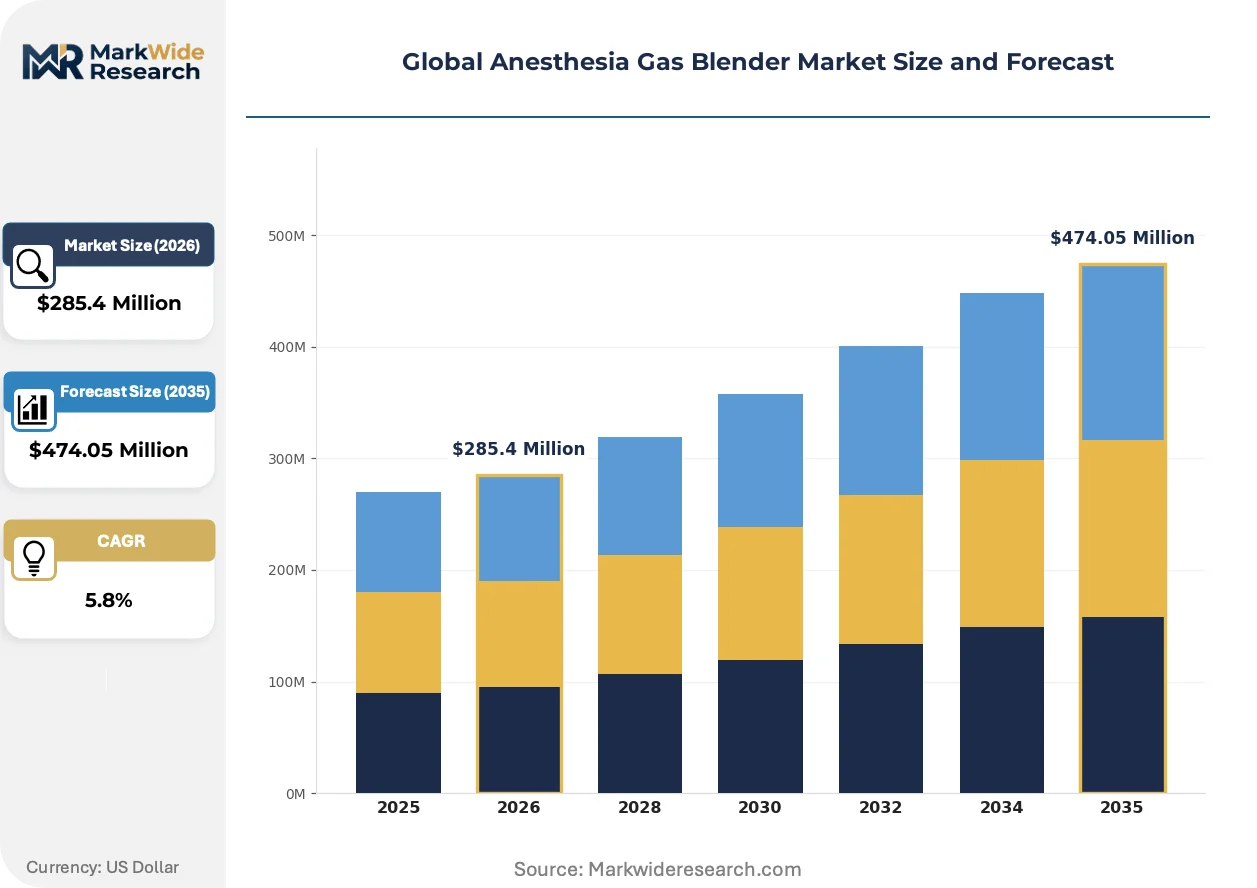
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Blender, Intermittent Blender, Proportioning System, Ventilator Blender Technology: Digital, Analog, Pneumatic, Electronic Application: Surgical Procedures, Dental Procedures, Veterinary Anesthesia, Pain Management End User: Hospitals, Ambulatory Surgery Centers, Dental Clinics, Veterinary Clinics |
| Companies Covered | medin Medical Innovations GmbH, Flow-Meter S.p.A., Dameca A/S, EKU Electronics, Armstrong Medical Inc., HEYER Medical AG, Farstar (Wuxi) Medical Equipment, Bio-Med Devices, Sechrist Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anesthesia Gas Blender Market Shifts & Advancements
Digital convergence is redefining anesthesia gas blender architecture, with software-defined mixing algorithms and predictive maintenance capabilities displacing purely mechanical control systems across premium hospital segments.
Microprocessor-controlled proportional valve arrays are collapsing the functional distinction between continuous flow and electronic blender categories. Tertiary care networks in Germany and the United States are specifying these hybrid systems for new operating room construction. The technology is collapsing aftermarket service revenue models by enabling remote calibration and predictive component replacement.
The FDA's 2023 cybersecurity guidance for networked respiratory devices mandates SBOM documentation and vulnerability disclosure protocols. Manufacturers must revalidate software architectures and supply chain security practices. Class II device submissions from Chinese and Indian exporters face extended review cycles as FDA inspectors assess cybersecurity maturity.
Group purchasing organizations are consolidating anesthesia equipment procurement across multi-hospital systems. Traditional distributor relationships are yielding to direct manufacturer contracts with price transparency requirements. This concentration is most visible in United States integrated delivery networks, where three GPOs control 70% of acute care purchasing volume and specify interoperability standards as contract conditions.
Global Anesthesia Gas Blender Market Segmentation
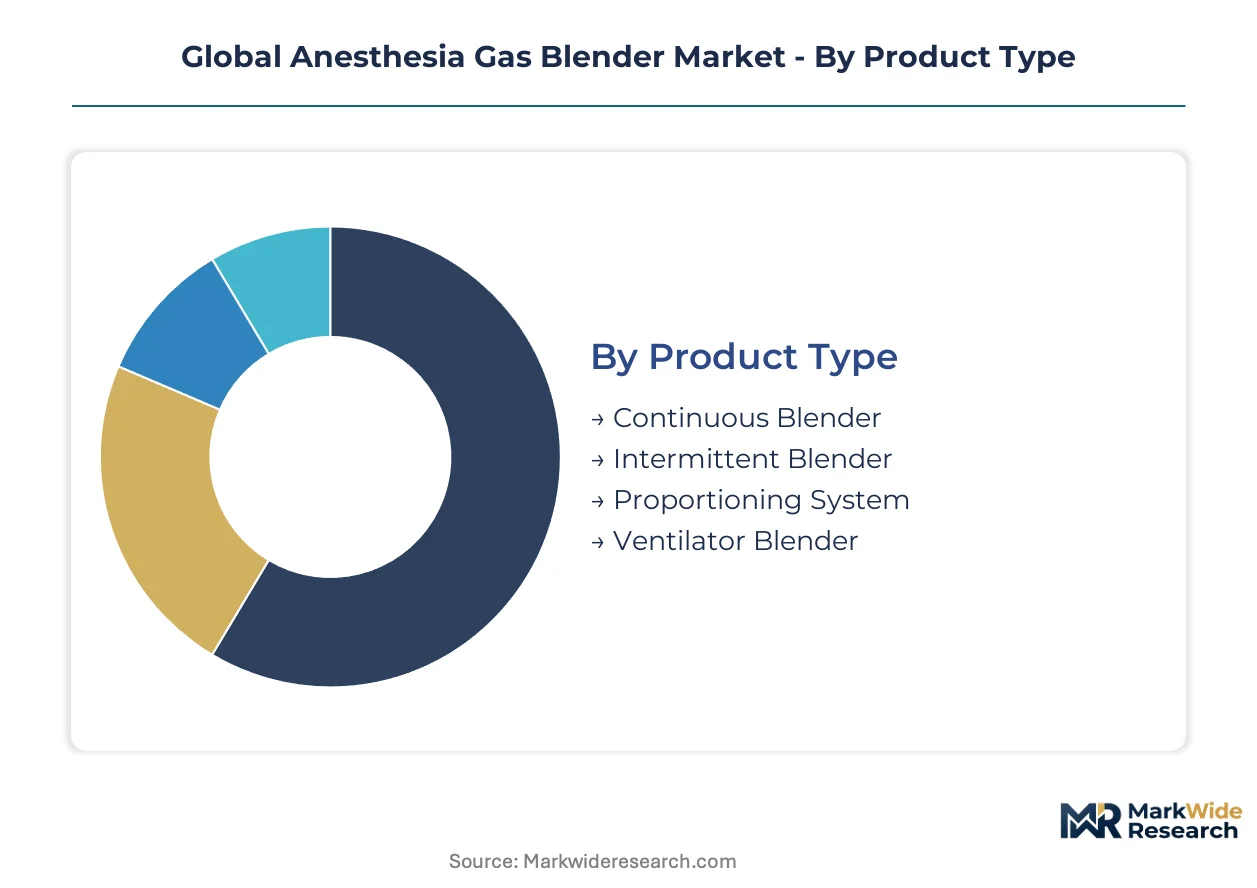
Segmentation in anesthesia gas blenders reveals how procurement priorities diverge across clinical settings and technical architectures. Understanding these divides enables manufacturers to align R&D investment with where purchasing power is actually concentrating.
Product Type:
Cost tier separates the installed base from replacement cycles, with capital intensity and maintenance burden driving hospital procurement decisions.
- Continuous Blender:Delivers uninterrupted gas mixtures through mechanical proportional valves without electronic interruption, prized for reliability in high-throughput United States and German operating rooms where downtime costs exceed equipment depreciation. Demand concentrates in tertiary care networks modernizing legacy infrastructure under group purchasing organization contracts.
- Proportioning System:Compact units integrating gas mixing with scavenging capabilities, capturing ambulatory surgery center volume in the United States as outpatient procedural migration accelerates. Space constraints and capital budget limitations in independent ASCs favor these integrated designs over full workstation purchases.
- Intermittent Blender:Cyclic delivery systems for intermittent positive pressure ventilation applications.
- Ventilator Blender:Dedicated mixing modules integrated into critical care ventilator platforms.
Continuous blenders command the established base. The steepest expansion runs through proportioning systems.
Technology:
Application requirements dictate architecture choice, with digital integration mandates from Chinese hospital information systems reshaping competitive specifications.
- Electronic:Microprocessor-controlled valve arrays with real-time feedback loops and HL7 FHIR connectivity, specified by Chinese tertiary hospitals as procurement prerequisites for anesthesia information management system integration. FDA cybersecurity guidance for networked respiratory devices is extending development timelines for non-compliant architectures.
- Digital:Software-defined mixing algorithms enabling predictive maintenance and remote calibration, displacing mechanical controls in premium German and United States hospital segments seeking to collapse aftermarket service costs.
- Pneumatic:Purely mechanical pressure-driven mixing without electronic components, retaining share in resource-constrained settings.
- Analog:Early electronic designs with limited programmability, concentrated in legacy installed bases.
Electronic platforms capture replacement investment. Digital architectures are climbing the fastest among new construction projects.
Application:
Volume concentration varies dramatically by reimbursement environment and procedural migration patterns across national health systems.
- Surgical Procedures:General anesthesia delivery in operating suites, absorbing the majority of blender procurement value as elective procedure backlogs in the United States and Germany drive replacement cycles for aging infrastructure.
- Veterinary Anesthesia:Companion animal and livestock applications, expanding with specialty veterinary hospital consolidation in the United States and Western Europe where referral centers are upgrading from portable to precision equipment.
- Dental Procedures:Sedation delivery in oral surgery settings, constrained by reimbursement limitations.
- Pain Management:Chronic pain clinic applications with specialized nitrous oxide delivery protocols.
Surgical procedures anchor procurement volume. Veterinary anesthesia is gaining share fastest as specialty practice consolidation accelerates.
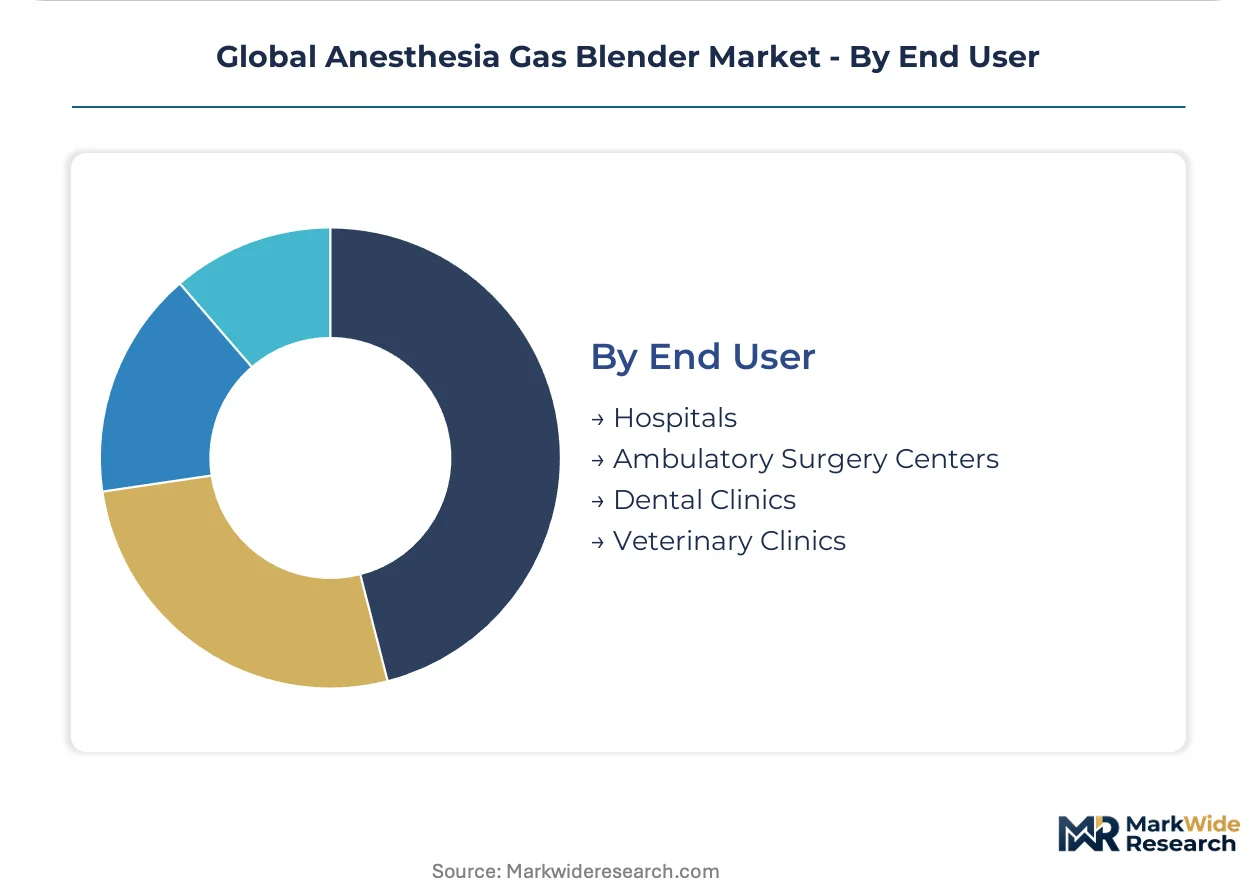
End User:
Customer type determines pricing tolerance and specification complexity, with integrated delivery networks in the United States rewriting vendor engagement models.
- Hospitals:Tertiary care networks and academic medical centers with complex anesthesia workstation ecosystems, where EU MDR Class IIa certification and ISO 80601-2-13 compliance filter vendor pools and extend procurement evaluation cycles.
- Ambulatory Surgery Centers:Independent and hospital-affiliated outpatient facilities in the United States, where group purchasing organization concentration is compressing margins while elevating interoperability requirements as contract conditions.
- Dental Clinics:Solo and group practices with limited capital equipment budgets.
- Veterinary Clinics:Small animal and mixed practices with variable equipment upgrade cycles.
Hospitals retain the dominant installed base. Ambulatory surgery centers are expanding most quickly as procedural volume migrates from inpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical device logistics corridor underwrites Germany's central role in European anesthesia equipment distribution, while Shenzhen's electronics manufacturing cluster powers component supply for Asian blender assembly.
United States
Integrated delivery networks in Texas and Florida are consolidating anesthesia workstation procurement under group purchasing organization contracts. FDA 510(k) premarket notification pathways filter market entrants and extend product development cycles for respiratory device manufacturers. The Greater Boston medical technology cluster hosts precision valve engineering specialists serving tertiary care networks.
Germany
Tertiary care networks in Bavaria and North Rhine-Westphalia are modernizing operating room infrastructure as surgical volumes recover. EU Medical Device Regulation Class IIa certification requirements reshape competitive access for anesthesia equipment suppliers. The Baden-Württemberg precision engineering corridor concentrates proportional mixing valve manufacturing capabilities.
China
Shanghai and Beijing tertiary hospitals are specifying HL7 FHIR connectivity as mandatory procurement criteria for anesthesia information management system integration. NMPA medical device registration requirements extend review timelines for networked respiratory equipment. The Yangtze River Delta electronics manufacturing base supplies thermal mass flow sensors to domestic and export blender assembly operations.
India
AIIMS-equivalent institutions under the Pradhan Mantri Swasthya Suraksha Yojana are creating first-time installed base opportunities in 22 new government medical college hospitals. CDSCO medical device registration requirements filter import-dependent supply chains for anesthesia delivery systems. The Delhi-NCR hospital procurement cluster concentrates demand for mid-tier electronic blender configurations.
Global Anesthesia Gas Blender Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision pneumatic elements to multiple downstream brands. Market structure tilts toward consolidated workstation ecosystems bundling blenders with ventilators and monitoring platforms, though independent component suppliers retain leverage through proprietary valve technologies. Two strategic archetypes dominate: anesthesia workstation integrators pursuing ecosystem lock-in, and precision pneumatic component houses defending margin through specialty engineering. Geographic expansion partnerships and regulatory certification co-development represent the primary competitive moves reshaping vendor relationships.
Among European precision engineering houses, medin Medical Innovations GmbH and Flow-Meter S.p.A. occupy positions exemplifying specialty-focused competitive positioning, while Dameca A/S represents the integrated workstation ecosystem archetype bundling gas mixing with broader anesthesia delivery infrastructure.
| Leading Market Players |
|---|
| medin Medical Innovations GmbH |
| Flow-Meter S.p.A. |
| Dameca A/S |
| EKU Electronics |
| Armstrong Medical Inc. |
| HEYER Medical AG |
| Farstar (Wuxi) Medical Equipment |
| Bio-Med Devices |
| Sechrist Industries |
| Others |
Supply & Pricing Matrix
The Baden-Württemberg precision engineering corridor concentrates proportional mixing valve manufacturing, and its capacity utilization directly shapes margin structures for downstream anesthesia workstation assemblers across European and North American hospital procurement channels.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with group purchasing organizations extracting 15-25% standard concessions above list pricing for multi-system contracts. Three-tier pricing stratifies across premium electronic blenders with HL7 FHIR connectivity, standard continuous flow units for high-throughput operating rooms, and economy proportioning systems for ambulatory surgery centers. Pricing pressure stems from integrated delivery network consolidation in the United States, where three GPOs control the majority of acute care purchasing volume. Ambulatory surgery centers exhibit the highest price sensitivity due to capital budget constraints, while German tertiary care networks prioritize ISO 80601-2-13 compliance over unit cost.
Supply Chain Analysis
Upstream feedstock dependencies center on specialty pneumatic components sourced from Germany, Japan, and Italy. Proportional mixing valves and thermal mass flow sensors draw from Baden-Württemberg and Tokyo precision engineering clusters, while electronic control modules source from Shenzhen manufacturing bases. Single-source vulnerability concentrates in German and Japanese valve suppliers, creating procurement risk for blender assemblers lacking dual-qualified component sources. Distribution runs through direct manufacturer contracts with integrated delivery networks, displacing traditional medical device distributor relationships across United States hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anesthesia gas blender market represents an early-cycle expansion story, with surgical volume recovery across United States and German tertiary care networks creating replacement demand for aging infrastructure installed during prior capital investment waves.
For Market Incumbents: Insulate installed base relationships by embedding predictive maintenance software and remote calibration capabilities that collapse aftermarket service revenue opportunities for competitors. Deepen backward integration into proportional valve manufacturing to reduce exposure to German and Japanese single-source suppliers. Prioritize FDA cybersecurity guidance compliance to extend competitive moats against emerging networked device entrants. For New Entrants and Emerging Players: Mid-market electronic blender configurations for Indian AIIMS-equivalent institutions under the Pradhan Mantri Swasthya Suraksha Yojana represent the most penetrable entry point, with CDSCO registration pathways filtering less committed competitors. Ambulatory surgery center proportioning systems in the United States offer secondary white-space opportunity as procedural volume migrates from inpatient settings. Lead with HL7 FHIR connectivity as a procurement-compliant entry wedge against legacy pneumatic competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized anesthesia equipment divisions lacking dedicated regulatory affairs capabilities for FDA 510(k) and EU MDR Class IIa pathways. Long-term viability favors platform-integrating workstation ecosystems over standalone component suppliers as hospital procurement consolidates around bundled anesthesia delivery infrastructure. Monitor FDA cybersecurity guidance enforcement intensity as an inflection signal for competitive repositioning among networked device architectures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Premarket notification for electronic blender architectures with embedded cybersecurity documentation accelerates United States market access. |
| EU MDR Class IIa Certification | Notified body relationships for anesthetic workstation compliance filter marginal competitors and expand addressable market for qualified manufacturers. |
| Hospital System Partnership | Direct contracts with integrated delivery networks in Texas and Florida displace distributor relationships and lock in replacement cycle volume. |
| Software Companion Development | Predictive maintenance algorithms for proportional valve arrays collapse aftermarket service costs and differentiate premium tier offerings. |
| Reimbursement Strategy | Anesthesia information management system integration specifications in Chinese tertiary hospitals create procurement prerequisites for networked blenders. |
Research Methodology
A spread of perspectives from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and anesthesia workstation integrators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body certification records, hospital procurement databases, and group purchasing organization contract disclosures. Bottom-up demand modeling across product type, technology architecture, application setting, and end-user category triangulated against top-down macro healthcare expenditure trends.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning continuous versus electronic versus proportioning system architectures, surgical versus veterinary versus dental applications, and hospital versus ambulatory surgery center end users. CAGRs derived from installed base replacement cycles, new construction activity in Chinese and Indian tertiary care networks, and procedural volume migration patterns. Industry-specific forecast inputs incorporated volatile anesthetic agent pricing contracts and ISO 80601-2-13 validation timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure budgets, surgical reimbursement rates, or medical device trade policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway timelines and procurement consolidation intensity. Cross-checking against hospital construction pipeline data and anesthesia workstation shipment records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Bowel Management System Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Rectal Catheters Market
Medical Devices
India Medical Devices Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Rapid Infuser Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Brazil Aesthetic Devices Market