
 North America General Surgical Devices Market | 2026-2036
North America General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America General Surgical Devices Market Analytics
Modular instrument bundling is restructuring how purchasing committees evaluate capital outlays for operating suites. Medtronic leverages integrated platform ecosystems to anchor multi-year service contracts with integrated delivery networks. Stryker Corporation sustains manufacturing scale across its Michigan and Texas facilities, competing on instrument durability and surgeon training programs. Johnson & Johnson differentiates through its broad sterilization-to-suture workflow offerings, occupying premium positioning in academic medical centers.
General surgical devices comprise hand-held mechanical instruments, powered units, and disposable accessories manufactured from medical-grade stainless steel, titanium alloys, and polymer composites, designed for tissue manipulation, dissection, cauterization, and wound closure during operative procedures. Electrosurgical technology leads revenue contribution given its consumable blade and generator pairing model, while robotic-assisted systems represent the fastest-expanding segment as hospitals amortize capital costs across higher procedural volumes. Open surgery instruments remain a mature margin pool with stable replacement cycles, though laparoscopic device demand accelerates as outpatient migration continues.
FDA 510(k) clearance requirements and Health Canada Medical Device Licensing impose biocompatibility and electrical safety validation burdens that extend development timelines for novel instrument submissions. The EPA regulates sterilization byproduct emissions from ethylene oxide processing facilities serving device manufacturers, constraining centralized reprocessing capacity expansion. Stakeholders must monitor reimbursement parity shifts between inpatient and ambulatory settings as site-of-service differentials directly influence capital allocation across instrument platforms.
Market Dynamics
Migration toward ambulatory surgical centers is compressing capital equipment replacement cycles and forcing manufacturers to reconfigure service models around decentralized point-of-care logistics.
Growth Catalysts
- Outpatient procedure volume:Ambulatory surgical centers in Texas and California are expanding minimally invasive instrument procurement as payers steer reimbursable cases away from inpatient settings.
- Health Canada Medical Device Licensing streamlining:Accelerated review pathways for predicate devices are shortening commercialization timelines for iterative instrument designs entering Canadian markets.
- Electrosurgical consumable pairing:Generator-blade attachment models create recurring revenue streams that offset capital equipment margin compression across hospital purchasing committees.
Market Restraints
- Ethylene oxide sterilization capacity:EPA emissions regulations constrain centralized reprocessing facility expansion, creating bottlenecks for device manufacturers dependent on outsourced sterilization services.
- Titanium alloy supply concentration:Raw material sourcing for precision instrument forgings remains concentrated among limited North American specialty metal processors.
- FDA 510(k) biocompatibility validation:Extended testing timelines for novel polymer composite submissions delay product launches by 12-18 months versus predicate pathways.
Strategic Opportunities
- Mexico manufacturing expansion:Untapped production capacity near Tijuana medical device clusters offers tariff-advantaged export positioning into US hospital networks.
- Robotic-assisted open surgery hybridization:Convergence of manual instrument tactile feedback with robotic positioning precision addresses surgeon resistance to fully automated platforms.
- Integrated delivery network service contracts:Multi-year preventive maintenance agreements for powered surgical units lock in recurring revenue across consolidating US health systems.
Industry Challenges
- Laparoscopic simulation training infrastructure:Hospital credentialing committees face capacity constraints certifying surgeons on next-generation instrument interfaces.
- Legacy sterilization workflow integration:New low-temperature hydrogen peroxide systems require physical plant modifications that disrupt operating suite scheduling during installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America General Surgical Devices Market |
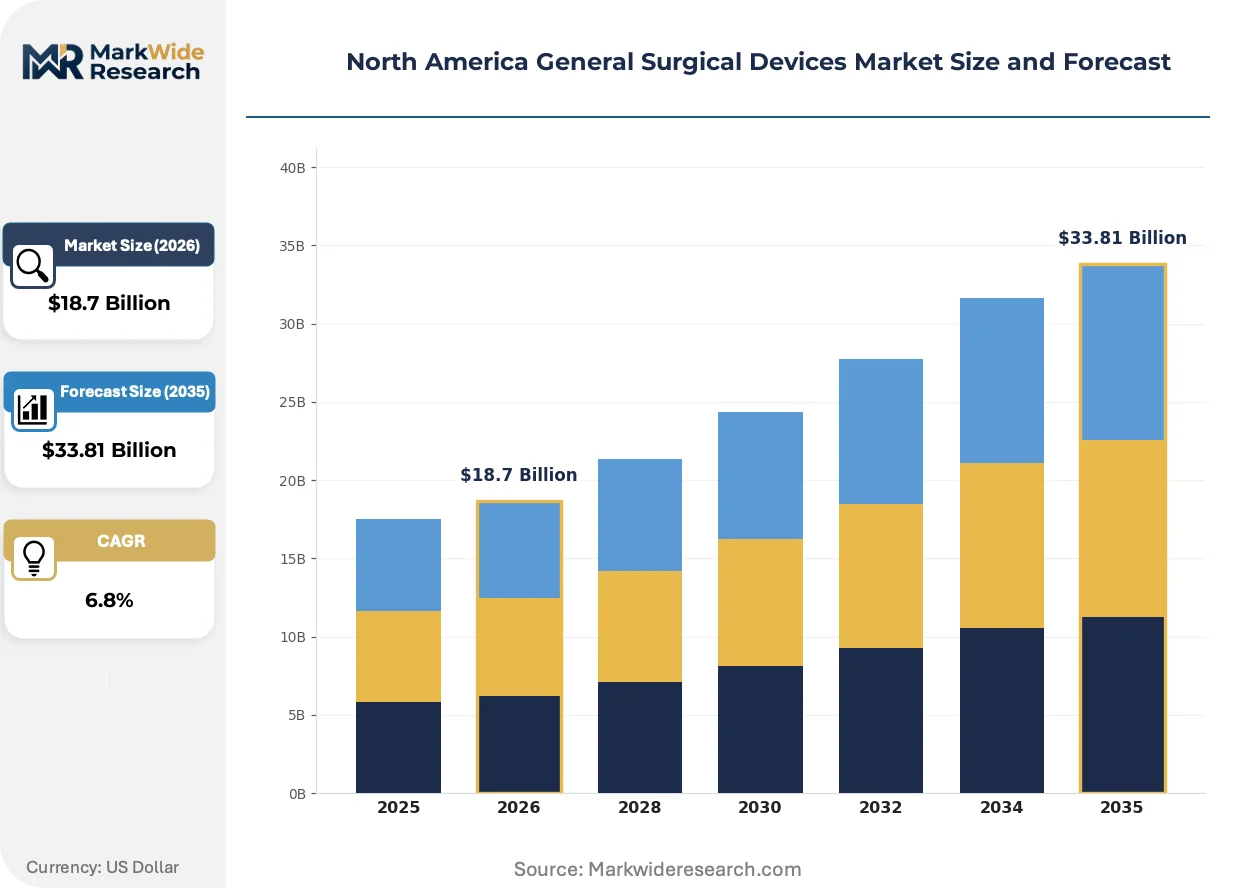
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
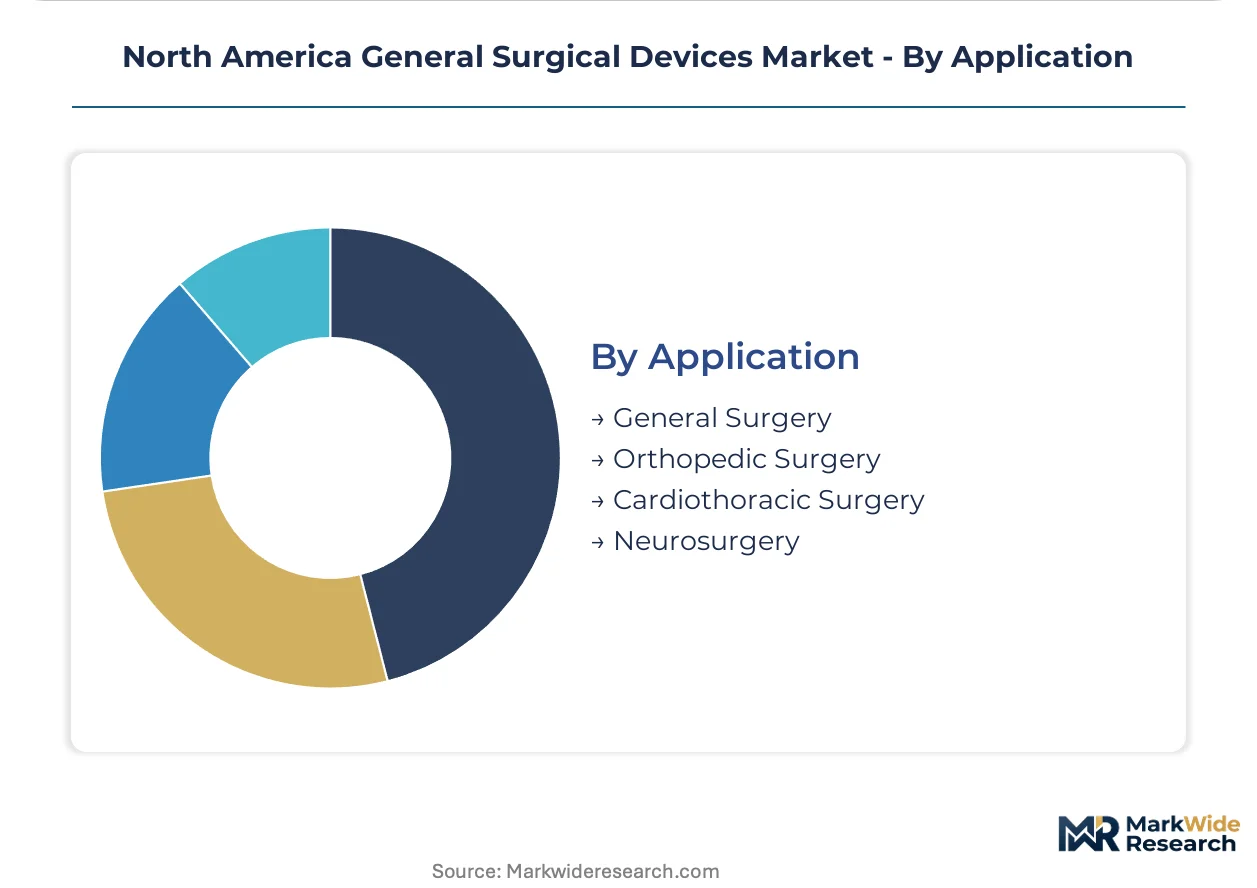
| Segmentation | Product Type: Scalpel, Forceps, Scissors, Clamps End User: Hospitals, Ambulatory Surgical Centers, Clinics, Surgical Facilities Technology: Electrosurgical, Robotic-assisted, Laparoscopic, Open Surgery Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Neurosurgery |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson, Conmed Corporation, Boston Scientific Corporation, B. Braun Melsungen AG, Olympus Corporation, Smith & Nephew, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America General Surgical Devices Market Evolving Landscape
Device architecture is converging around platform ecosystems that tether mechanical instruments to data-capture infrastructure, reshaping how purchasing committees evaluate total cost of ownership across replacement cycles.
Bipolar vessel sealing technology is electrifying soft tissue dissection workflows by integrating energy delivery with mechanical grasping functions. Academic medical centers in California are adopting these systems at twice the rate of community hospitals. The technology is electrifying competitive positioning by compressing the addressable market for standalone electrosurgical pencils and forcing generator manufacturers toward bundled platform architectures.
Health Canada's transition toward MDR-aligned Medical Device Licensing requirements is imposing new clinical evidence standards on Class II surgical instruments previously cleared through abbreviated pathways. Manufacturers must now submit prospective usability data for reusable instrument reprocessing validations. Powered dissection devices face the steepest compliance burden, with several US-based firms delaying Canadian market entry pending quality management system upgrades.
Hospital materials management departments are consolidating supplier rosters through standardized evaluation scorecards that weight instrument durability testing data above list pricing. Group purchasing organizations are replacing individual facility negotiations with multi-hospital system contracts that specify minimum volume commitments. This consolidation is most visible across Texas-based Catholic health networks, where centralized procurement committees now control capital allocation for operating suite renovations.
North America General Surgical Devices Market Segmentation
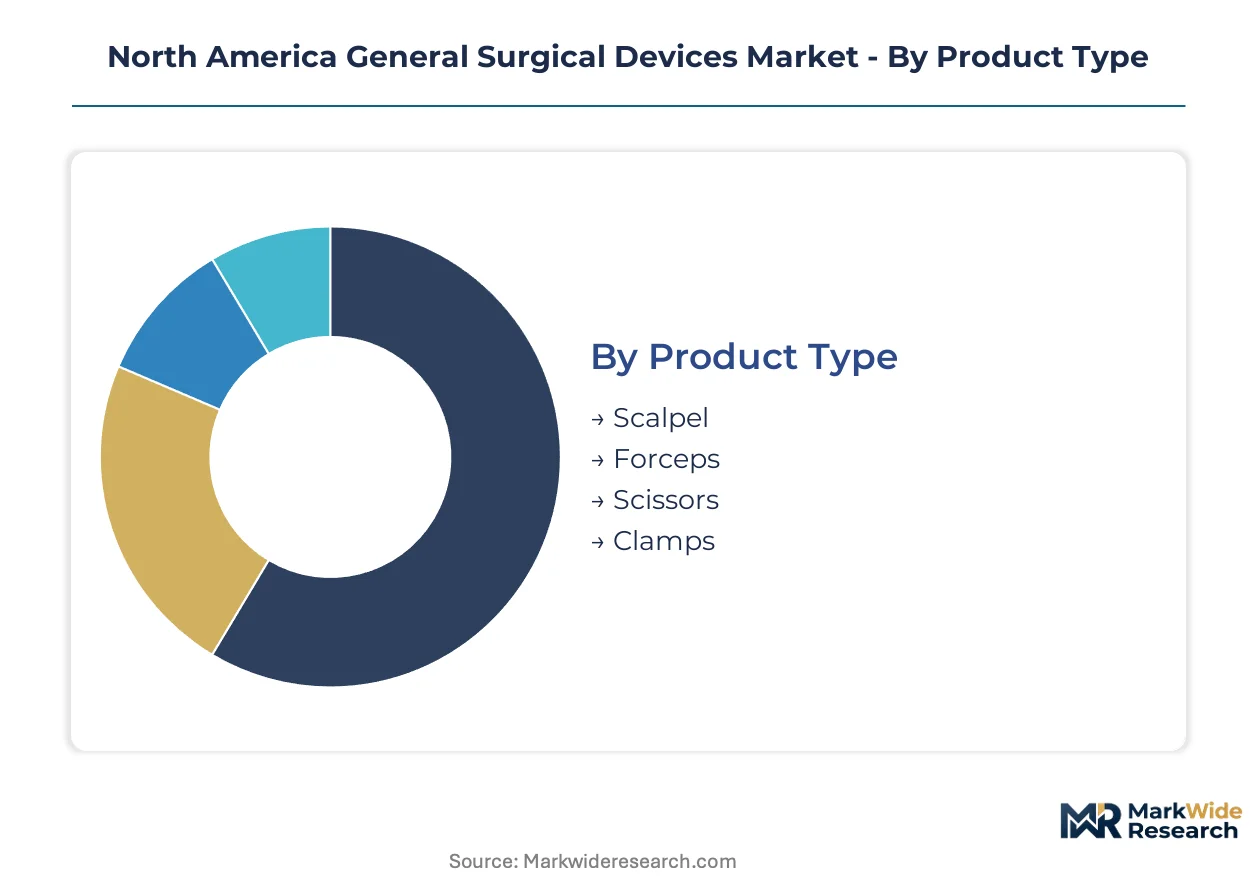
Device selection criteria diverge sharply across care settings in the North American surgical landscape. Purchasing committees weight instrument durability against reprocessing costs in hospitals, while ambulatory operators prioritize compact footprint and rapid turnover compatibility.
Product Type:
Material composition and reprocessing tolerance separate high-volume hospital purchasers from price-sensitive clinic buyers.
- Scalpel:Medical-grade stainless steel and carbon steel variants dominate institutional procurement, with disposable safety-engineered handles gaining preference across California ambulatory networks seeking OSHA bloodborne pathogen compliance. Demand concentrates in high-throughput orthopedic and general surgery service lines where blade change frequency drives consumable attach rates.
- Forceps:Titanium alloy and polymer composite constructions address tactile feedback requirements in microsurgical applications. Texas academic medical centers are expanding ratcheted locking instrument procurement as robotic-assisted procedures require stable tissue grasping during console-controlled manipulation.
- Scissors:Tungsten carbide edge inserts extend cutting cycle longevity for facilities with in-house sharpening capabilities.
- Clamps:Atraumatic jaw designs with silicone inserts reduce vessel trauma in cardiac bypass procedures.
Volume sits with Scalpel; growth tilts toward Forceps.
End User:
Capital allocation authority and case volume thresholds determine pricing elasticity across customer tiers.
- Hospitals:Integrated delivery networks in Texas and California command multi-year service contracts with preventive maintenance clauses. These facilities amortize powered instrument costs across 5,000-plus annual procedures, justifying premium platform acquisitions with demonstrated throughput gains.
- Ambulatory Surgical Centers:Site-of-service reimbursement differentials are accelerating minimally invasive instrument procurement as payers steer reimbursable cases away from inpatient settings. California ASC networks are expanding single-use electrosurgical pencil adoption to eliminate reprocessing bottlenecks.
- Clinics:Limited procedure rooms constrain capital equipment footprints to handheld mechanical instruments.
- Surgical Facilities:Specialty-focused operators in urban corridors concentrate demand for procedure-specific instrument sets.
Revenue concentrates in Hospitals; expansion is steepest in Ambulatory Surgical Centers.
Technology:
Surgeon training infrastructure and generator compatibility shape platform lock-in dynamics.
- Electrosurgical:Generator-blade attachment models create recurring revenue streams through proprietary consumable pairing. Texas hospital networks are consolidating vendor rosters around integrated energy platforms that capture monopolar and bipolar modalities within single capital units.
- Robotic-assisted:Capital cost amortization across higher procedural volumes is displacing manual instrument demand in prostatectomy and hysterectomy service lines. California academic centers are expanding dual-console configurations to enable surgeon training during live procedures.
- Laparoscopic:Insufflation-compatible instrument lengths standardize across 5mm and 10mm port configurations.
- Open Surgery:Mature replacement cycles sustain margin pools in rural community hospitals with limited minimally invasive training infrastructure.
Installed base favors Electrosurgical; share gains are fastest in Robotic-assisted.
Application:
Procedure reimbursement rates and complication risk profiles determine instrument sophistication requirements.
- General Surgery:Appendectomy and cholecystectomy volume sustains demand for mid-tier laparoscopic instrument sets. California ASC networks are migrating these procedures to outpatient settings, compressing capital equipment replacement cycles toward disposable-dominant configurations.
- Orthopedic Surgery:Power tool durability and sterile field maintenance requirements drive premium positioning. Texas hospital systems are consolidating arthroscopy service lines around single-vendor platforms with dedicated technician training programs.
- Cardiothoracic Surgery:Beating-heart procedures demand specialized stabilizing instruments with minimal tissue trauma profiles.
- Neurosurgery:Microscopic precision requirements concentrate demand among limited specialty instrument manufacturers.
Case volume concentrates in General Surgery; complexity premiums are highest in Cardiothoracic Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States and Mexico while Canadian demand depends on import channels. Texas and California hospital networks drive consumption volume. FDA and Health Canada regulatory pathways shape product commercialization timelines differently across the three markets.
United States
Texas Medical Center and California academic networks anchor demand for powered surgical platforms and robotic-assisted systems. FDA 510(k) premarket notification requirements impose biocompatibility validation burdens that extend development timelines for novel polymer composite instruments. Minneapolis and Kalamazoo manufacturing corridors concentrate production of electrosurgical generators and precision-forged hand instruments.
Canada
Ontario and Quebec hospital procurement committees weight instrument durability testing data above list pricing in vendor evaluations. Health Canada Medical Device Licensing requirements are transitioning toward MDR-aligned clinical evidence standards for Class II reusable instruments. Toronto-area academic medical centers are adopting bipolar vessel sealing systems at accelerated rates compared to community hospital networks.
Mexico
Tijuana medical device manufacturing clusters offer tariff-advantaged export positioning into US hospital supply chains. COFEPRIS regulatory alignment with FDA quality system requirements facilitates cross-border production integration for sterilization-to-distribution workflows. Baja California and Chihuahua assembly facilities are expanding capacity for disposable electrosurgical pencil production.
California
Ambulatory surgical center networks in Los Angeles and San Francisco metropolitan areas are migrating general surgery procedures to outpatient settings. State-level OSHA bloodborne pathogen compliance requirements accelerate disposable safety-engineered scalpel handle adoption. Stanford and UCLA health systems anchor demand for next-generation laparoscopic instrument platforms with integrated data-capture capabilities.
Texas
Houston and Dallas-Fort Worth integrated delivery networks command multi-year preventive maintenance contracts for powered surgical units. State hospital licensing requirements for robotic surgery credentialing create training infrastructure demand that shapes instrument procurement decisions. Methodist and Baylor Scott & White health systems are consolidating vendor rosters around single-source energy platform agreements.
North America General Surgical Devices Market Competitive Landscape
The competitive structure tilts toward diversified conglomerates with multi-segment surgical portfolios. Medtronic, Stryker, and Johnson & Johnson anchor tier-one positioning through integrated platform ecosystems and service contract lock-in. Mid-tier specialists compete on instrument durability and surgeon training infrastructure. Dominant competitive moves include multi-year integrated delivery network service agreements and backward integration into titanium alloy forging capacity.
Within the diversified medical technology tier, Medtronic plc and Stryker Corporation exemplify platform-centric positioning that captures recurring revenue through generator-consumable pairing models. Johnson & Johnson occupies premium positioning in academic medical centers through sterilization-to-suture workflow breadth. B. Braun Melsungen AG represents European-origin manufacturing scale with North American distribution infrastructure. These three conglomerates anchor competitive dynamics through purchasing committee relationships and credentialing program influence.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson |
| Conmed Corporation |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Olympus Corporation |
| Smith & Nephew |
| 3M |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA-cleared electrosurgical platforms and non-certified mechanical instruments manifests in both pricing premiums and supply chain sourcing patterns. Premium-tier manufacturers command recurring revenue through generator-consumable pairing models, while commodity instrument suppliers compete on titanium alloy forging costs and sterilization service bundling.
Pricing Analysis
Margin tightening in mechanical instrument tiers reflects Health Canada MDR-aligned licensing upgrades and extended biocompatibility validation timelines. Three-tier pricing structure across premium, standard, and economy levels separates robotic-assisted platforms from laparoscopic sets and disposable open surgery instruments. Cost-down pressure on reusable forceps and clamps accelerates because hospital materials management committees now weight durability testing data above list pricing in vendor scorecards. Ambulatory surgical centers exhibit highest price sensitivity, while Texas academic medical centers absorb premium positioning for integrated energy platforms.
Supply Chain Analysis
Domestic-content mandates under the US Buy American Act and Health Canada localization preferences are reshaping sourcing toward Michigan, Texas, and Baja California manufacturing clusters. Raw material dependencies center on medical-grade stainless steel from Pennsylvania specialty mills, titanium alloy forgings from limited North American processors, and polymer composites from Ohio chemical suppliers. Single-source vulnerability concentrates in ethylene oxide sterilization capacity constrained by EPA emissions regulations. Distribution runs through group purchasing organization contracts with Methodist and Baylor Scott & White health systems in Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) biocompatibility validation and Health Canada MDR-aligned licensing create barrier-to-entry moats for manufacturers with established quality management systems.
For Market Incumbents: Anchor multi-year service contracts with integrated delivery networks by embedding preventive maintenance clauses for powered surgical units. Deepen backward integration into titanium alloy forging capacity to offset raw material supply concentration among limited North American processors. Defend against robotic-assisted platform displacement by hybridizing manual instrument tactile feedback with precision positioning technology. For New Entrants and Emerging Players: Launch via ambulatory surgical center networks in California seeking disposable electrosurgical pencil alternatives to eliminate reprocessing bottlenecks. Target Mexico manufacturing expansion near Tijuana medical device clusters for tariff-advantaged export positioning into US hospital supply chains. Penetrate through bipolar vessel sealing technology adoption gaps in community hospitals outside California academic medical center corridors. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier specialists possessing Health Canada MDR-ready quality management systems given the licensing transition timeline compression. Long-term viability over a five-to-ten year window favors manufacturers with captive sterilization infrastructure insulated from EPA ethylene oxide capacity constraints. Monitor reimbursement parity shifts between inpatient and ambulatory settings as the inflection signal for capital allocation across instrument platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Biocompatibility validation for novel polymer composites extends development timelines by 12-18 months versus predicate pathways. |
| Hospital System Partnership | Multi-year preventive maintenance agreements with Texas integrated delivery networks lock in recurring revenue across consolidating health systems. |
| Software Companion Development | Integrated data-capture capabilities in laparoscopic platforms address Stanford and UCLA health system procurement requirements. |
| Reimbursement Strategy | Site-of-service parity advocacy shapes capital allocation toward ambulatory surgical center instrument configurations. |
| CE Marking Pathway | Health Canada MDR alignment streamlines dual-market entry for Class II reusable instruments with prospective usability data. |
Research Methodology
Document review covered FDA 510(k) clearance databases, Health Canada Medical Device Licensing records, and EPA sterilization emissions filings, complemented by interviews with hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and ambulatory surgical center operators. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement schedules, and integrated delivery network capital expenditure disclosures. Bottom-up instrument shipment modeling and top-down healthcare capital spending triangulation anchored market size estimation.
Output generation across the analysis window employed segmented modeling by product type, end user, technology, application, and state-level regulatory cluster. CAGRs were derived from procedure volume trajectories, capital equipment replacement cycles, and reimbursement migration patterns. Forecast inputs incorporated ambulatory surgical center expansion rates, robotic-assisted platform adoption curves, and sterilization capacity utilization constraints.
The model assumes a particular technology adoption path favoring minimally invasive migration; alternative pathways for open surgery instrument retention would alter the outlook. Forecasts reflect documented assumptions regarding reimbursement parity, regulatory timeline compression, and raw material supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
China Contraceptive Devices Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Catheter Systems Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
China Diabetes Devices Market