
 Europe Biopsy Devices Market | 2026-2036
Europe Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biopsy Devices Market Intelligence
Disposable single-use needle systems is tilting procurement away from reusable surgical instruments in European healthcare systems. Becton, Dickinson and Company leverages its automated manufacturing footprint to supply standardized needle platforms across EU member states. Hologic Inc. anchors its position through dedicated vacuum-assisted biopsy technology leadership in breast tissue sampling. Thermo Fisher Scientific Inc. competes by integrating diagnostic consumables with downstream molecular analysis workflows.
Biopsy devices comprise precision-engineered needles, forceps, and vacuum-assisted systems designed to extract tissue specimens with controlled gauge dimensions and cutting mechanics for histopathological examination. These instruments serve the essential clinical function of obtaining diagnostic material from suspect lesions while minimizing patient trauma and procedural risk. Needle biopsy systems command the largest installed base across European hospitals due to lower per-procedure cost and outpatient compatibility. Vacuum-assisted biopsy technology captures expanding utilization in breast cancer screening programs where larger tissue volumes improve diagnostic accuracy. Ultrasound-guided systems lead technology adoption by enabling real-time visualization without ionizing radiation exposure.
The EU Medical Device Regulation (MDR) and CE marking framework govern market access, with notified bodies now requiring enhanced clinical evidence for reusable device reprocessing validation. Germany's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices (BfArM), coordinates vigilance reporting that shapes manufacturer post-market surveillance obligations. France's ANSM enforces additional sterilization standards for devices used in ambulatory settings. Stakeholders must monitor evolving MDR transition timelines and national reimbursement adjustments for image-guided procedures.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines and forcing manufacturers to rebuild clinical evidence portfolios for reusable instrument reprocessing validation, fundamentally restructuring competitive positioning between single-use and sterilizable platforms.
Growth Catalysts
- MDR clinical evidence mandates:The EU Medical Device Regulation's enhanced post-market surveillance requirements accelerate hospital procurement of pre-validated single-use needle systems that eliminate reprocessing documentation burdens.
- Vacuum-assisted biopsy platforms:Breast cancer screening programs across Western Europe expand adoption of larger-volume tissue extraction systems to improve diagnostic accuracy in mammographic surveillance.
- Germany:Hospital procurement networks in this market centralize high-volume purchasing, creating economies of scale that standardize device specifications across multi-site health systems.
Market Restraints
- Stainless steel input volatility:Precision needle manufacturing depends on surgical-grade steel supply chains concentrated in specific European foundry regions, exposing margins to energy-cost-driven alloy price swings.
- Notified body capacity:EU MDR transition has concentrated conformity assessment among fewer designated bodies, extending certification timelines and delaying product launches.
- Core needle biopsy:Fine needle aspiration techniques retain cost advantages for certain lymphatic and thyroid applications, limiting vacuum-assisted system penetration in outpatient settings.
Strategic Opportunities
- Poland and Romania:Oncology infrastructure expansion in these Central European markets creates first-mover positioning for automated biopsy platforms as screening programs mature.
- Image-guidance convergence:Integration of ultrasound and MRI navigation with disposable needle systems enables real-time lesion targeting without dedicated capital equipment purchases.
- ANSM ambulatory standards:France's national regulator mandates enhanced sterilization protocols for outpatient procedures, tilting procurement toward single-use alternatives in clinic settings.
Industry Challenges
- Biocompatibility testing timelines:Extended cytotoxicity and sensitization studies for new polymer needle coatings delay product launches by 12-18 months under MDR Annex I requirements.
- Legacy sterilization infrastructure:Hospitals with captive central sterile services departments face sunk-cost resistance when evaluating disposable platform conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biopsy Devices Market |
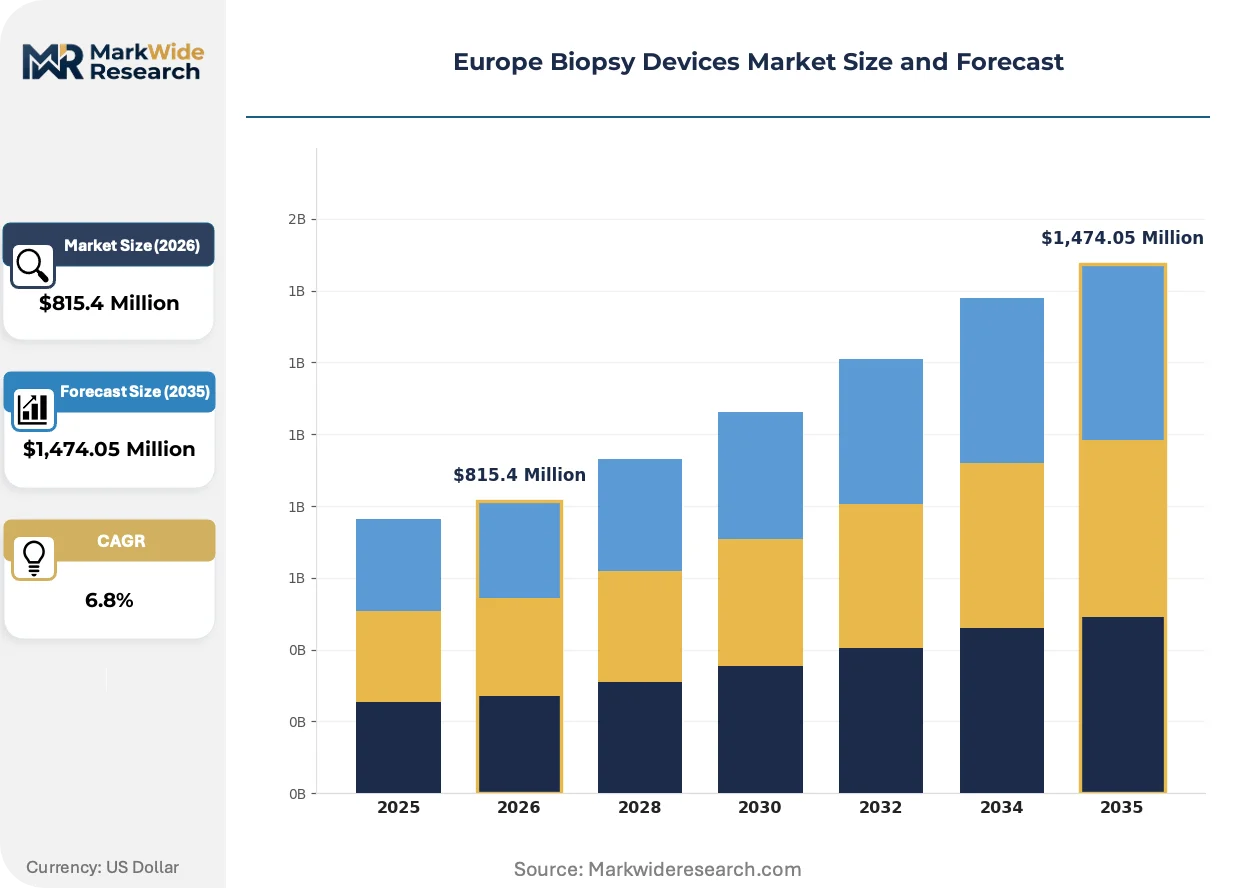
| Market Size in 2026 | $815.4 Million |
| Market Size in 2035 | $1,474.05 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy, Surgical Biopsy, Vacuum-Assisted Biopsy, Fine-Needle Aspiration End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Oncology Clinics Technology: Ultrasound-Guided, CT-Guided, MRI-Guided, Stereotactic Application: Breast Cancer, Lung Cancer, Prostate Cancer, Skin Lesions |
| Companies Covered | Becton, Dickinson and Company, Thermo Fisher Scientific Inc., Boston Scientific Corporation, Hologic Inc., Cook Medical, Medtronic, Argon Medical Devices, Roche Diagnostics, Cardinal Health Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biopsy Devices Market Strategic Shifts & Innovations
Disposable platform architectures are displacing reusable instrument paradigms across European healthcare procurement, driven by regulatory compliance economics and outpatient procedure expansion. Three convergent developments define this transition.
Spring-loaded core needle technology is migrating from manual handheld devices to automated firing mechanisms with adjustable penetration depth controls. Oncology clinics in France and Italy adopt these systems for outpatient liver and renal biopsies, reducing operator-dependent variability and enabling procedure standardization across nursing staff skill levels. The technology is migrating from academic medical centers to community hospital settings, compressing the addressable market for premium reusable forceps.
The EU Medical Device Regulation's Annex XIV post-market clinical follow-up requirements impose systematic surveillance obligations on reusable device manufacturers. BfArM vigilance reporting protocols now mandate documented traceability for each sterilization cycle, increasing administrative overhead that disadvantages metal instrument portfolios. Breast imaging centers in Germany respond by specifying single-use vacuum-assisted systems in tender documents to eliminate reprocessing liability exposure.
Centralized purchasing consortia reshape vendor relationships across German hospital networks. Procurement directors negotiate multi-year framework agreements that lock in standardized needle gauges and platform configurations, displacing fragmented department-level ordering. This consolidation concentrates supplier selection authority within specialized acquisition committees, compressing margins for manufacturers lacking automated production scale.
Europe Biopsy Devices Market Segmentation
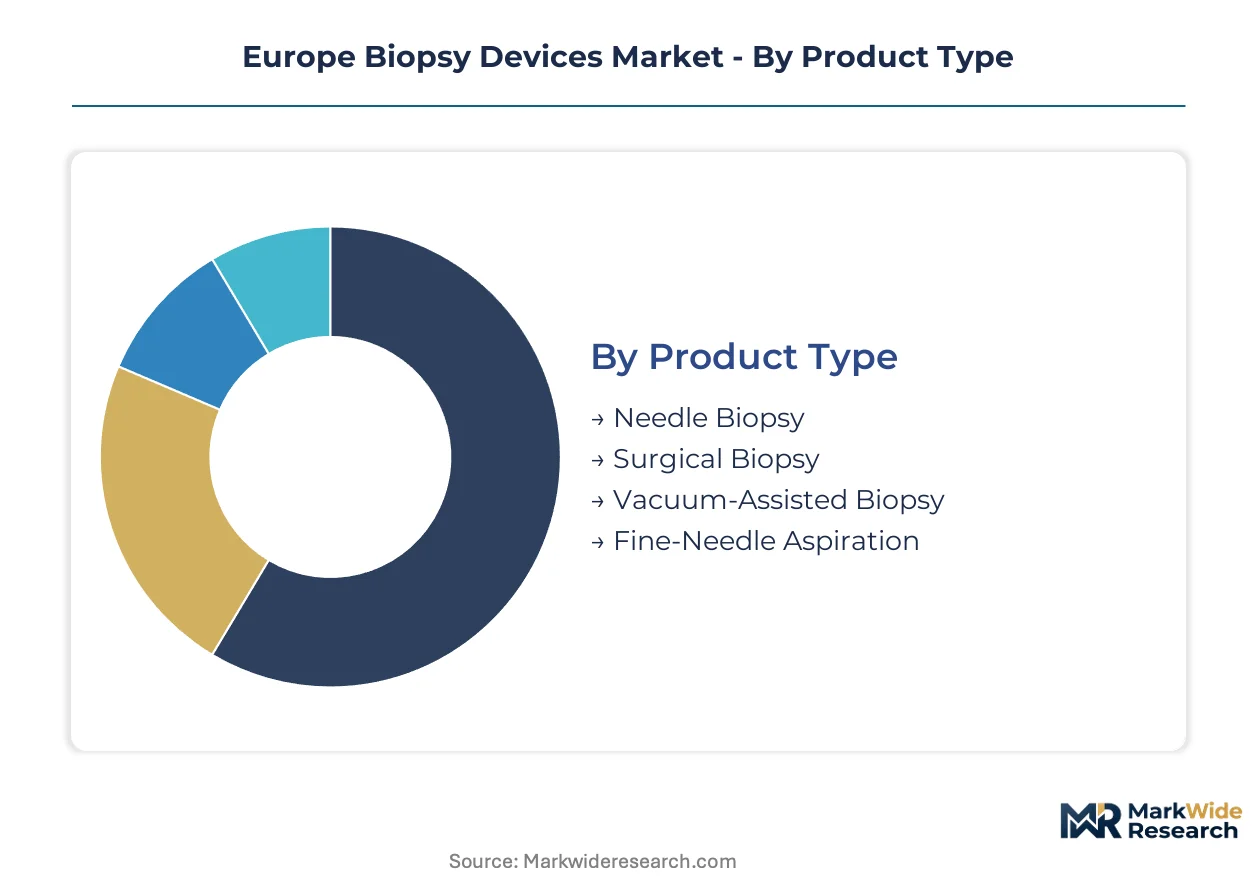
Biopsy device segmentation reflects divergent clinical workflows across European healthcare systems. Procurement patterns vary sharply between centralized hospital networks and distributed ambulatory settings. Technology integration requirements differ by cancer screening program maturity.
Product Type:
Use cases span from outpatient diagnostic sampling to complex surgical tissue extraction, with reimbursement codes and facility capabilities determining platform selection.
- Needle Biopsy:Spring-loaded core needle systems extract tissue specimens through percutaneous entry with controlled gauge dimensions. German hospital procurement networks specify these platforms for high-volume liver and renal sampling due to outpatient compatibility and lower per-procedure cost structures.
- Vacuum-Assisted Biopsy:Continuous suction mechanisms harvest larger tissue volumes through single needle insertion. Breast cancer screening programs across France and Italy adopt these systems to reduce sampling insufficiency rates in mammographic surveillance.
- Surgical Biopsy:Open excisional techniques retain utility for lesions inaccessible to percutaneous approaches. France's ANSM mandates enhanced sterilization documentation for reusable forceps in ambulatory settings.
- Fine-Needle Aspiration:Cytology-focused sampling employs smaller-gauge needles for lymphatic and thyroid applications. Cost advantages sustain demand in Eastern European outpatient clinics with limited pathology infrastructure.
The dominant share belongs to Needle Biopsy, while Vacuum-Assisted Biopsy is closing the gap fastest.
End User:
Facility type dictates capital equipment requirements, sterilization protocols, and procedure volume economics across European markets.
- Hospitals:Centralized sterile services departments and multi-disciplinary tumor boards coordinate complex sampling workflows. Germany's hospital procurement networks concentrate purchasing authority for high-volume needle system contracts.
- Oncology Clinics:Dedicated cancer centers integrate biopsy services with immediate pathology consultation. Western European screening program expansion drives minimally invasive platform adoption in these settings.
- Diagnostic Laboratories:Reference pathology providers influence upstream device selection through specimen quality requirements. EU MDR post-market surveillance obligations extend to laboratory partners in integrated health systems.
- Ambulatory Surgical Centers:Same-day discharge protocols favor single-use platforms eliminating reprocessing documentation. France's ANSM sterilization standards tilt procurement toward disposable alternatives.
Hospitals command the installed base majority, though Oncology Clinics are expanding most quickly.
Technology:
Imaging modality selection balances real-time visualization capabilities against capital expenditure and radiation exposure considerations.
- Ultrasound-Guided:Real-time soft tissue visualization without ionizing radiation enables outpatient breast and thyroid procedures. Italian and Spanish clinics lead adoption for cost-effective lesion targeting.
- CT-Guided:Cross-sectional imaging provides access to thoracic and deep abdominal lesions. Lung cancer screening programs in Poland and Romania deploy these systems as oncology infrastructure matures.
- MRI-Guided:Magnetic resonance navigation targets lesions invisible to other modalities. Premium pricing limits deployment to academic medical centers in Germany and Switzerland.
- Stereotactic:Three-dimensional coordinate systems enable precise breast tissue sampling. Mammography suite integration drives placement in dedicated screening centers.
Ultrasound-Guided systems hold the volume lead, while CT-Guided platforms are gaining share fastest.
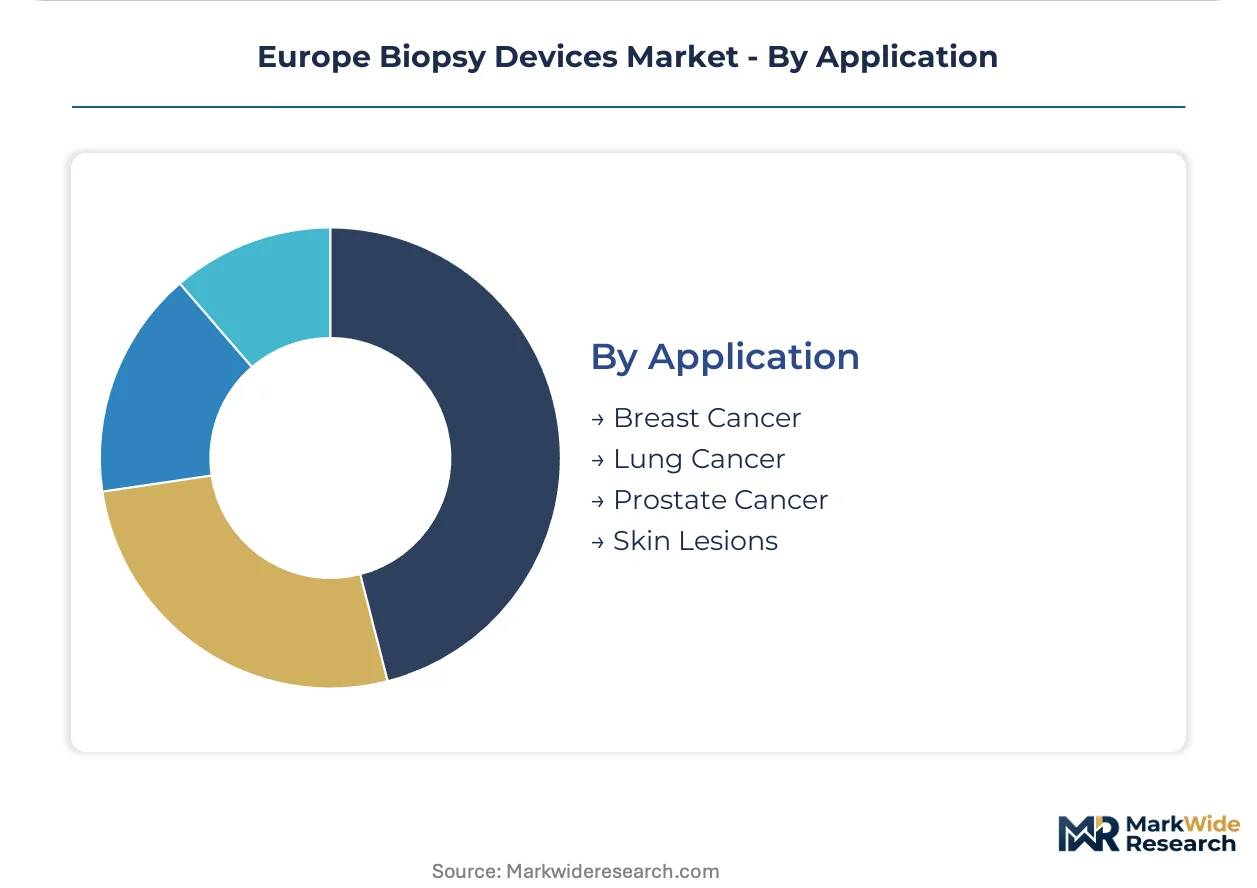
Application:
Cancer type determines tissue volume requirements, needle gauge specifications, and coordination with staging protocols.
- Breast Cancer:Screening program density and reimbursement generosity concentrate device demand. Vacuum-assisted platforms dominate where large-volume sampling improves diagnostic accuracy.
- Lung Cancer:Transthoracic approaches require CT navigation and pneumothorax management capabilities. Central European infrastructure expansion creates new placement opportunities.
- Prostate Cancer:Transrectal ultrasound guidance with systematic sampling templates defines standard of care. MRI fusion techniques are penetrating tertiary referral centers.
- Skin Lesions:Punch and shave biopsy tools serve dermatology outpatient workflows. Melanoma surveillance programs sustain steady device consumption.
Breast Cancer applications generate the highest procedure volumes, with Lung Cancer showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe maintains a modest trade surplus in biopsy devices, with German and Swiss manufacturers exporting precision-engineered instruments to Central European and Middle Eastern markets while importing specialized polymer components from Asian suppliers.
Germany
Hospital procurement networks in Bavaria and North Rhine-Westphalia centralize high-volume needle system purchasing, creating economies of scale that standardize device specifications across multi-site health systems. The Federal Institute for Drugs and Medical Devices (BfArM) coordinates vigilance reporting protocols that shape manufacturer post-market surveillance obligations. Berlin-Brandenburg hosts several notified bodies designated under the EU MDR, concentrating conformity assessment capacity.
France
Breast cancer screening program expansion drives vacuum-assisted biopsy adoption in Île-de-France and Auvergne-Rhône-Alpes. The national regulator ANSM enforces enhanced sterilization standards for devices used in ambulatory settings, tilting procurement toward single-use alternatives. Lyon and Paris clusters house major pathology laboratory networks that influence upstream device selection through specimen quality requirements.
Italy
Oncology clinics in Lombardy and Emilia-Romagna expand minimally invasive biopsy services for outpatient liver and renal sampling. Italian notified bodies participate actively in MDR transition, though capacity constraints extend certification timelines for reusable instrument portfolios. Milan's medical device district supports regional distribution networks serving Southern European markets.
United Kingdom
NHS procurement frameworks standardize needle gauge specifications across England's hospital trusts, concentrating supplier selection authority. The Medicines and Healthcare products Regulatory Agency (MHRA) maintains post-Brexit regulatory alignment with EU MDR while operating independent conformity assessment procedures. London and Southeast clusters integrate biopsy services with major cancer center networks.
Poland
Oncology infrastructure expansion in Warsaw and Kraków creates placement opportunities for automated biopsy platforms as national screening programs mature. Polish hospitals import precision needle systems primarily from German and Swiss suppliers while developing domestic distribution capabilities. EU structural funds support medical equipment modernization in regional hospitals.
Europe Biopsy Devices Market Key Industry Players
On the supply side, the industry is consolidating around automated manufacturing platforms and disposable system architectures. Tiered competitive positioning separates multinational instrument manufacturers from regional sterilization service providers and specialized needle fabricators. Two strategic archetypes dominate: vertically integrated device-diagnostics conglomerates and focused single-use platform specialists. Competitive moves concentrate on M&A for molecular diagnostics integration and capacity expansion in automated needle production lines.
Among US-based medical technology conglomerates, Becton, Dickinson and Company and Boston Scientific Corporation occupy positions anchored in automated manufacturing scale and interventional device portfolios. Hologic Inc. represents the specialized platform archetype through its dedicated vacuum-assisted biopsy technology focus. Thermo Fisher Scientific Inc. exemplifies the integrated diagnostics model, connecting upstream device supply with downstream laboratory analysis workflows.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Thermo Fisher Scientific Inc. |
| Boston Scientific Corporation |
| Hologic Inc. |
| Cook Medical |
| Medtronic |
| Argon Medical Devices |
| Roche Diagnostics |
| Cardinal Health Inc. |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp freight corridor channels surgical-grade steel shipments from German foundries to precision needle fabricators, with transport cost volatility compressing margins for manufacturers lacking automated production scale while amplifying price differentiation between standardized disposable platforms and customized reusable instrument portfolios.
Pricing Analysis
Technology-generation pricing gaps separate automated vacuum-assisted biopsy systems from manual spring-loaded core needles and next-generation MRI-integrated navigation platforms. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier differentiation and volume procurement scale under German hospital network frameworks. Pricing pressure stems from centralized purchasing consortia standardizing specifications and squeezing supplier margins. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge reimbursement constraints, while academic medical centers in Switzerland and Germany demonstrate lowest sensitivity for premium navigation-integrated systems.
Supply Chain Analysis
Extended payment terms from German hospital procurement networks and supply-chain finance facilities from Swiss component suppliers stabilize working capital for precision needle manufacturers. Surgical-grade stainless steel concentrates in German and Austrian foundry regions, while polymer needle coatings source from specialized chemical suppliers in Switzerland and the Netherlands. Single-source vulnerability exists for vacuum-assisted biopsy pump mechanisms sourced from concentrated precision engineering clusters in Southern Germany. Distribution runs through regional medical device distributors serving hospital networks and direct contracts with oncology clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against liquid biopsy and circulating tumor DNA testing platforms that threaten tissue-based diagnostic volumes. Incumbents must fortify positions through workflow integration and regulatory compliance architecture.
For Market Incumbents: Build regulatory compliance moats by pre-validating single-use platform sterilization documentation under EU MDR Annex XIV requirements, eliminating reprocessing liability exposure for hospital customers. Consolidate manufacturing scale through automated needle production line expansion in Bavaria and Baden-Württemberg to match German procurement network volume demands. Anchor hospital system relationships through multi-year framework agreements that lock in standardized gauge specifications and lock out competitors.
For New Entrants and Emerging Players: Build out Poland and Romania oncology infrastructure as white-space targets, positioning automated biopsy platforms ahead of national screening program maturation. Target ambulatory surgical centers in France where ANSM sterilization standards tilt procurement toward single-use alternatives with limited incumbent penetration. Pursue pathology laboratory partnerships as go-to-market angle, influencing upstream device selection through specimen quality requirements and integrated diagnostic workflows.
For Investors and Strategic Acquirers: Specialized single-use platform manufacturers with EU MDR certification completion and automated production capabilities represent priority acquisition targets for diagnostics conglomerates seeking vertical integration. Long-term viability hinges on molecular diagnostics convergence and downstream laboratory analysis workflow capture. Watch liquid biopsy reimbursement decisions by national health technology assessment bodies as inflection indicator for tissue-based diagnostic volume erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity assessment completion unlocks German hospital procurement network access. |
| Hospital System Partnership | Multi-year framework agreements with Bavaria procurement consortia standardize device specifications. |
| Software Companion Development | Image-guidance integration with ultrasound and MRI navigation enables real-time lesion targeting. |
| Reimbursement Strategy | National coding alignment for image-guided procedures secures outpatient clinic placement. |
| Backward Integration | In-house polymer coating production reduces biocompatibility testing timeline exposure under MDR Annex I. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and pathology laboratory directors across Germany, France, Italy, and Poland; and secondary validation against EU MDR notified body filings, hospital procurement databases, GPO contract repositories, and BfArM vigilance reporting records. Bottom-up procedure volume modeling and top-down manufacturer shipment analysis were triangulated for convergence.
Forecast inputs incorporated product type segmentation across needle biopsy, vacuum-assisted biopsy, surgical biopsy, and fine-needle aspiration platforms; end-user facility categories spanning hospitals, oncology clinics, diagnostic laboratories, and ambulatory surgical centers; and technology modalities including ultrasound-guided, CT-guided, MRI-guided, and stereotactic systems. CAGRs were derived from procedure volume growth trajectories, reimbursement code expansion patterns, and screening program maturity curves across the projection horizon.
Stress conditions across EU MDR transition timeline delays, surgical-grade steel alloy price volatility, and liquid biopsy reimbursement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding screening program expansion rates and procurement centralization trajectories. Macroeconomic contraction, regulatory deviation from MDR enforcement patterns, or disruptive liquid biopsy technology breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Global Holter ECG Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Bare Metal Stents Market