
 Stick Welding Electrode Market | 2026-2036
Stick Welding Electrode Market Size, Share, and Industry Trends Forecast 2026-2036
Stick Welding Electrode Market Analytics
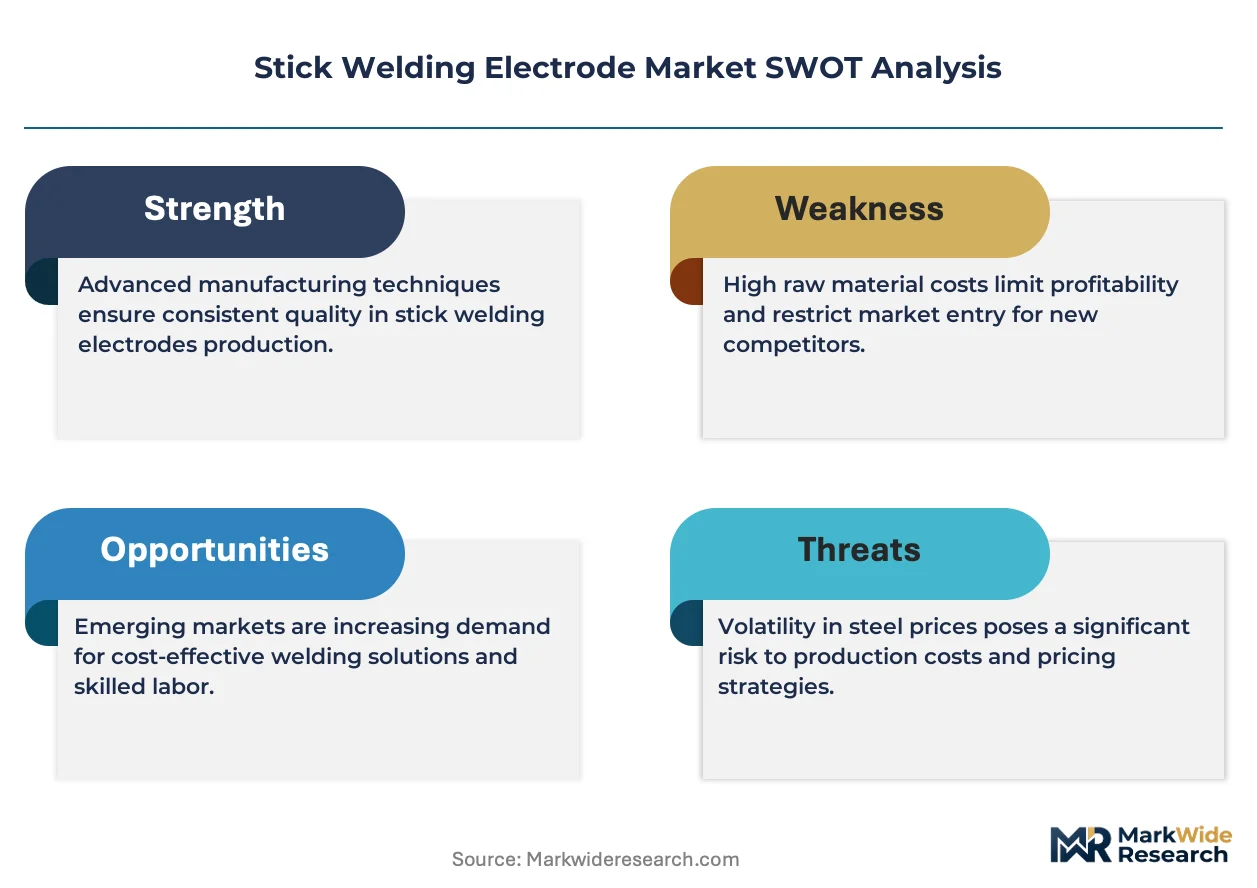
Aftermarket service revenue from electrode storage, handling, and flux conditioning is tilting margin pools away from pure product sales toward technical support contracts. Lincoln Electric Holdings, Inc. leverages its distributor network and training infrastructure to capture this recurring income stream. ESAB Group, Inc. competes through specialized product lines for extreme-service environments. Kobe Steel Ltd. anchors its position with integrated steelmaking and proprietary wire-to-electrode conversion capabilities.
Stick welding electrodes are flux-coated metal rods designed for manual arc welding, where the coating generates shielding gas and slag to protect the molten weld pool from atmospheric contamination; typical formulations employ rutile, basic, or cellulosic flux systems with coating factors ranging from 1.25 to 1.6 times the core wire diameter. Low hydrogen electrodes dominate structural steel and pressure vessel applications where crack resistance is mandatory, while rutile electrodes sustain broader appeal in general fabrication for their ease of use and all-position handling. Cellulosic electrodes occupy a specialized niche in pipeline root pass welding, where deep penetration and fast freezing slag support high-deposition downhill procedures on X80 and X100 grade line pipe.
AWS A5.1 and ISO 2560 standards govern mechanical property classifications and diffusible hydrogen limits, with the latter specification tightening to H4 and H8 designations for critical infrastructure applications. OSHA welding fume standards and the EU Chemical Agents Directive are forcing fabricators to reassess ventilation systems and electrode selection protocols. Stakeholders must monitor how regional decarbonization mandates reshape steel sourcing and whether electrode manufacturers can secure low-carbon feedstock certifications without sacrificing arc stability or deposit chemistry.
Market Dynamics
Offshore wind farm construction is pulling electrode demand toward low-hydrogen formulations as steel monopile fabrication scales, while the EU F-Gas Regulation and OSHA welding fume standards force simultaneous reformulation and ventilation upgrades across fabricators.
Growth Catalysts
- EU F-Gas Regulation:Tightening industrial emissions frameworks are pushing fabricators toward low-hydrogen electrode formulations that reduce fume exposure and meet diffusible hydrogen limits for critical infrastructure welds.
- India infrastructure build-out:Domestic shipyard expansion and national highway construction are absorbing record electrode volumes, drawing supply from both local manufacturers and imported sources.
- Offshore wind monopile fabrication:Steel foundation production for North Sea and East Asian wind farms requires high-deposition, crack-resistant electrodes in 700E and 800E strength grades.
Market Restraints
- Flux mineral volatility:Rutile and ilmenite concentrate prices fluctuate with titanium pigment demand, compressing margins for rutile electrode producers during supply tightness.
- Supply concentration in China:Over 60% of global flux coating raw materials and specialty core wire originate from Chinese integrated steelmakers, creating single-source vulnerability.
- Wire feed substitution:Solid and flux-cored wire processes are capturing general fabrication volume from stick electrodes in automated and semi-automated shop environments.
Strategic Opportunities
- India domestic production gap:Local electrode capacity lags behind shipyard and infrastructure demand, creating import substitution potential for manufacturers establishing regional compounding facilities.
- EU Green Deal steel certification:Low-carbon feedstock mandates are creating premium positioning for electrodes produced with scrap-based or hydrogen-reduced steel wire.
- Digital distributor platforms:B2B procurement marketplaces are disintermediating traditional welding supply houses, enabling direct technical support relationships between manufacturers and mid-sized fabricators.
Industry Challenges
- Certified welder shortage:Pipeline and pressure vessel contractors face 18-24 month backlogs for qualified stick electrode operators, constraining project execution timelines.
- Dual certification complexity:Fabricators serving both AWS A5.1 and ISO 2560 markets must maintain separate electrode inventories and testing protocols, inflating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stick Welding Electrode Market |
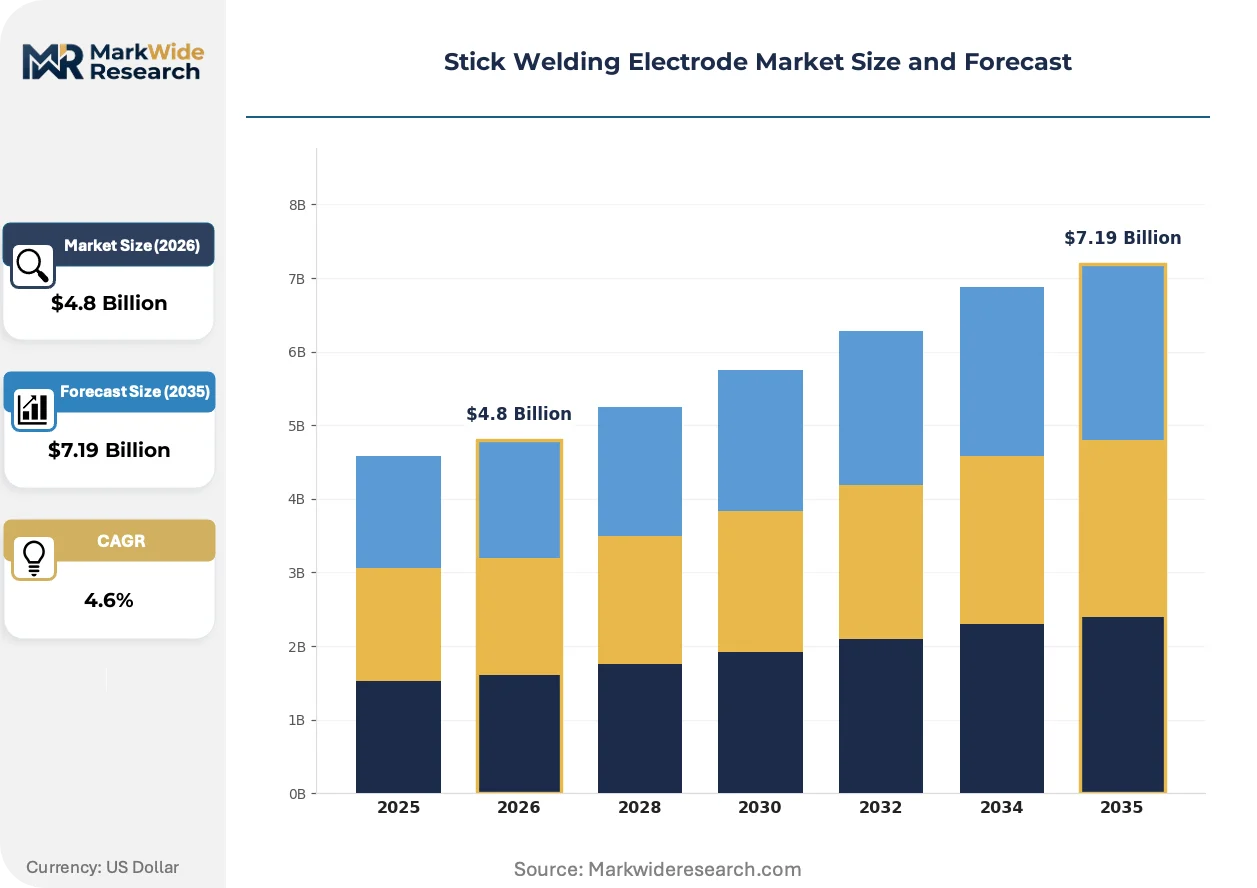
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Electrode Type: Cellulosic, Basic, Rutile, Low Hydrogen Application: Construction, Shipbuilding, Pipeline, Automotive End User: Fabricators, Manufacturers, Energy, Aerospace Size: 1/8 inch, 3/32 inch, 5/32 inch, 3/16 inch |
| Companies Covered | Lincoln Electric Holdings, Inc., ESAB Group, Inc., Kobe Steel Ltd., voestalpine Böhler Welding, Tianjin Golden Bridge Welding Materials Group, Ador Welding Limited, Jiangsu Boda Welding Group, Kiswel Co., Ltd., Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stick Welding Electrode Market Evolving Landscape
Electrode technology is converging with digital process control and sustainable material sourcing, reshaping how fabricators specify, procure, and consume manual arc welding consumables across heavy industrial applications.
Advanced flux formulations is hybridizing basic and rutile characteristics to deliver low-hydrogen mechanical properties with all-position handling ease. Offshore wind contractors in the North Sea and Taiwan Strait are specifying these hybrid electrodes for monopile circumferential welds. The technology is compressing the traditional trade-off between crack resistance and operator productivity.
The EU F-Gas Regulation and Chemical Agents Directive are mandating fume extraction upgrades and electrode substitution protocols in member state fabrication shops. German and Dutch shipyards are retrofitting ventilation systems and shifting to H4-classified electrodes ahead of enforcement deadlines. Pressure vessel and bridge construction segments face the steepest compliance costs and longest qualification timelines.
Buyer concentration among national oil companies and wind farm developers is consolidating procurement authority at the project consortium level. Long-term electrode supply agreements now bundle technical training, storage conditioning, and weld procedure qualification services. This bundled purchasing model is most advanced in Danish and German offshore wind clusters, where EPC contractors negotiate multi-project electrode frameworks.
Stick Welding Electrode Market Segmentation
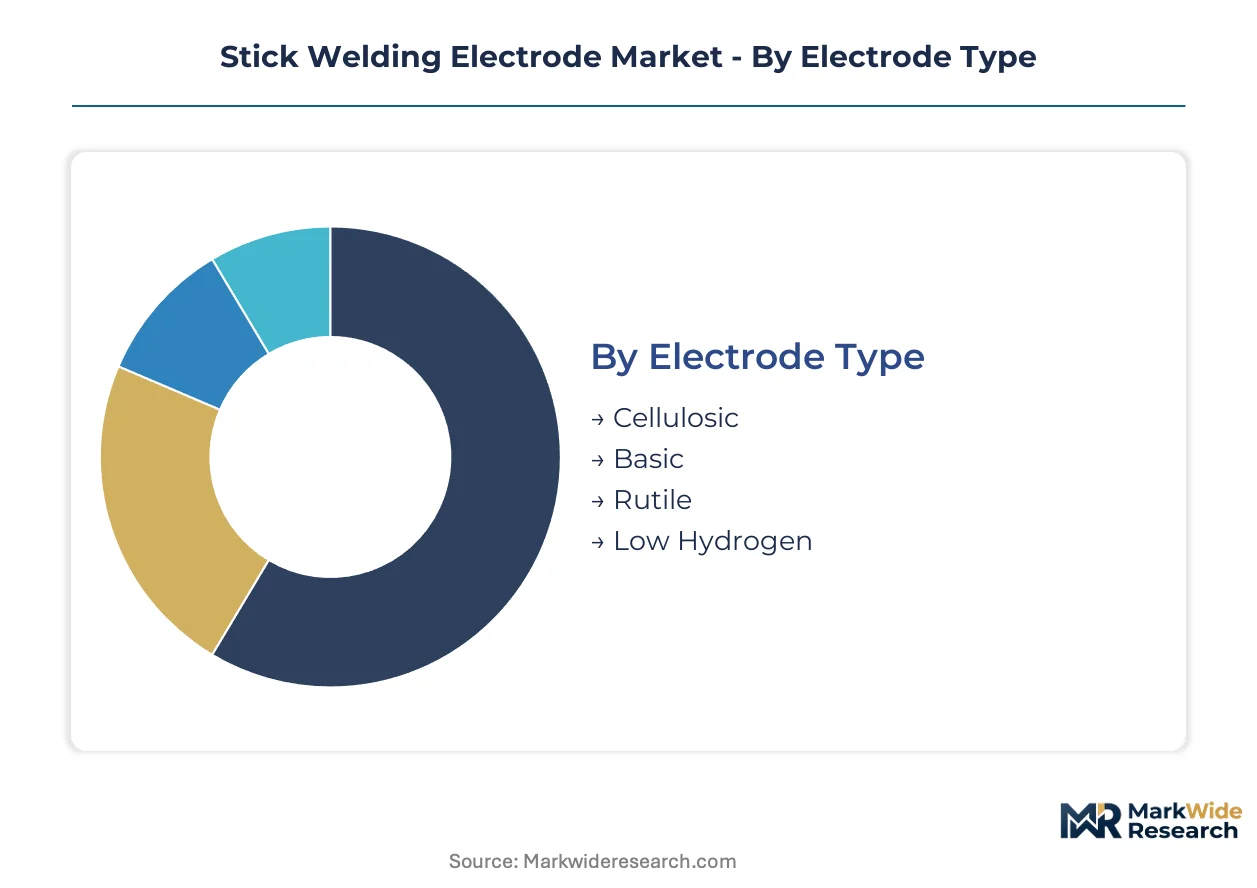
Stick welding electrode segmentation reveals distinct inventory velocity patterns across formulation types and dimensional specifications. Fabricators manage working capital differently by segment, with some electrodes turning weekly and others sitting for quarters awaiting specialized contracts.
Electrode Type:
Cellulosic electrodes turn fastest due to pipeline seasonality, while low-hydrogen formulations sit longest as projects await qualification approvals.
- Cellulosic:Deep-penetration coating systems using organic binders that generate forceful arc characteristics for root pass welding. X80 and X100 grade pipeline construction in the Permian Basin and Alberta oil sands drives concentrated offtake during narrow construction windows.
- Low Hydrogen:Basic flux formulations with moisture-controlled coatings delivering H4 and H8 diffusible hydrogen ratings for crack-critical welds. Offshore wind monopile fabrication in the North Sea and Taiwan Strait absorbs volume as fabricators stockpile ahead of multi-year foundation contracts.
- Basic:Calcium-fluoride rich coatings for high-tensile strength deposits in structural steel applications.
- Rutile:Titanium dioxide-based coatings offering smooth arc behavior and easy slag removal for general fabrication shops.
Low Hydrogen dominates installed base value. Cellulosic is where expansion concentrates during pipeline construction surges.
Application:
Cost tier separation is pronounced, with shipbuilding and pipeline commanding premium formulations while construction tolerates standard grades.
- Construction:High-volume general fabrication with mixed-position welding requirements. Indian national highway expansion and commercial building frameworks in Southeast Asian urban centers sustain steady consumption of rutile and basic electrodes.
- Shipbuilding:Classification society-certified deposits demanding lot-traceable consumables for hull and tank welding. South Korean and Chinese shipyards specify dual-certified electrodes as newbuild contracts recover from orderbook lows.
- Pipeline:Circumferential girth welding with cellulosic root passes and low-hydrogen fill caps. North American shale gathering systems and Middle East export lines drive seasonal procurement spikes.
- Automotive:Limited stick electrode use concentrated in prototype shops and specialty vehicle modification.
Construction holds the broadest installed base. Shipbuilding shows the steepest expansion trajectory as naval and commercial orderbooks rebuild.
End User:
Customer type determines technical service intensity, with energy and aerospace demanding embedded welding engineers while fabricators self-serve.
- Fabricators:Job shops and structural steel contractors with mixed-process capability. German and Dutch metalworking clusters maintain stick electrode inventory for field repair work and legacy equipment compatibility.
- Energy:Oil majors and wind farm developers specifying electrode brands at the EPC contract level. Long-term supply agreements now bundle storage conditioning and welder certification services.
- Manufacturers:Original equipment producers with captive welding operations for machinery and industrial components.
- Aerospace:Maintenance repair organizations with narrow specification windows and extensive qualification protocols.
Fabricators represent the deepest installed base. Energy sector procurement is gaining share fastest as project bundling consolidates purchasing authority.
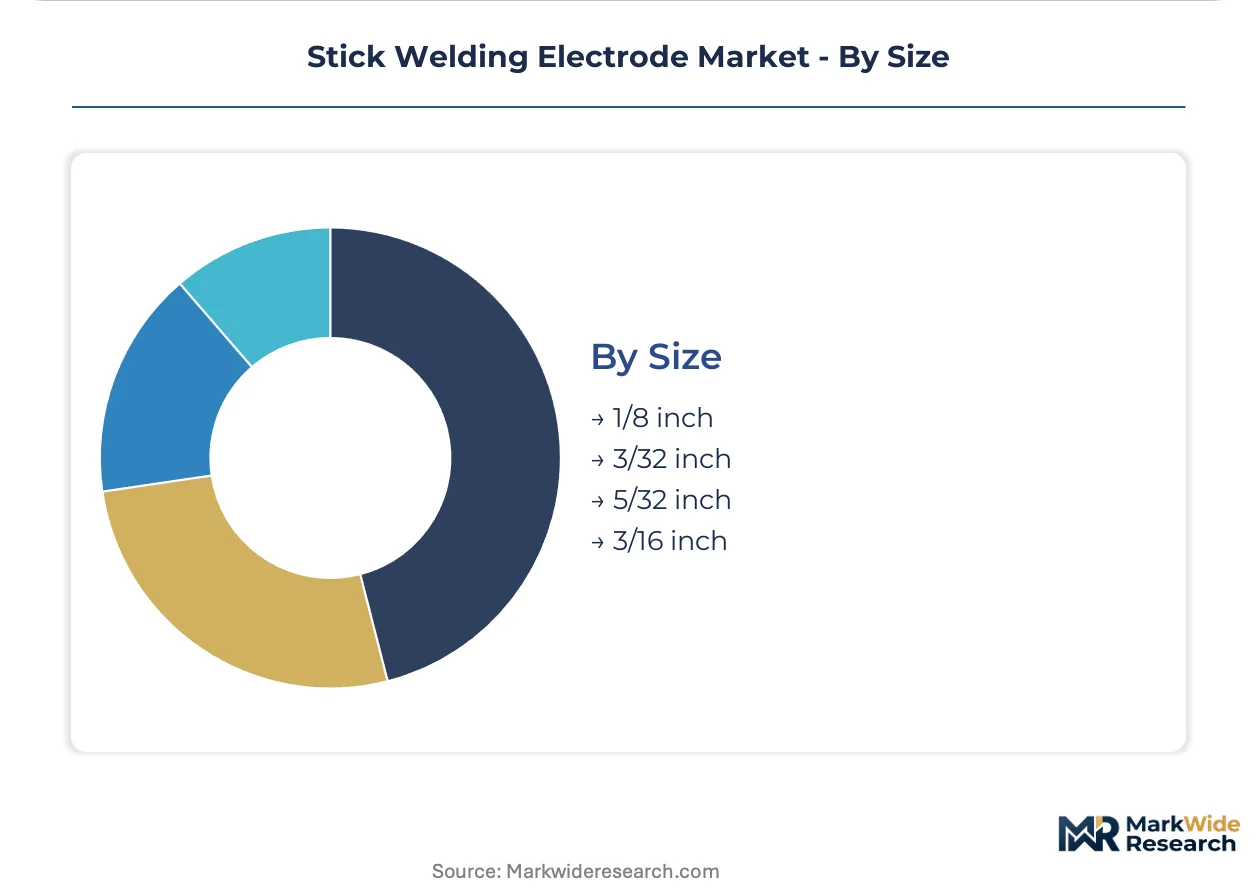
Size:
Volume concentration favors mid-range diameters, with 1/8 inch and 5/32 inch electrodes comprising the bulk of tonnage movement.
- 1/8 inch:All-position workhorse diameter for general fabrication and light structural applications. Indian infrastructure contractors consume this specification heavily for field welding of rebar and secondary steel.
- 5/32 inch:Heavy deposition diameter for flat and horizontal fillet welds in thick plate. Offshore wind transition piece fabrication and shipyard block assembly specify this size for productivity gains.
- 3/32 inch:Thin material and overhead position preference for sheet metal and maintenance applications.
- 3/16 inch:High-amperage diameter for massive structural connections and equipment repair in mining and heavy machinery.
1/8 inch dominates installed base tonnage. 5/32 inch is where volume expansion concentrates as heavy industrial projects scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes stick welding electrodes differently than mature industrial economies, prioritizing low-cost rutile formulations for field construction over the low-hydrogen grades dominating European offshore wind fabrication. This consumption-mix differential shapes regional supply strategies and margin structures.
United States
Pipeline construction in the Permian Basin and shale gathering systems drives concentrated cellulosic electrode demand during narrow seasonal windows. OSHA welding fume standards are forcing fabricators toward H4-classified formulations and upgraded ventilation infrastructure. Houston-area distributors maintain large inventories to serve Gulf Coast petrochemical maintenance turnarounds.
Germany
North Sea offshore wind monopile fabrication absorbs premium low-hydrogen electrodes in 700E and 800E strength grades. The EU F-Gas Regulation and Chemical Agents Directive are accelerating shop-floor ventilation retrofits and electrode substitution protocols. Bremerhaven and Cuxhaven welding clusters face the steepest compliance costs and longest qualification timelines.
China
Domestic shipyard recovery and infrastructure steel fabrication sustain massive electrode volume, though flux mineral supply concentrates among integrated steelmakers. The country's national emissions regulator is tightening industrial fume exposure limits in coastal manufacturing zones. Jiangsu and Shandong provinces host the densest electrode compounding capacity.
India
National highway expansion and domestic shipyard construction are absorbing record electrode volumes that outpace local manufacturing capacity. The Bureau of Indian Standards is strengthening certification requirements for structural welding consumables. Gujarat and Maharashtra industrial corridors draw supply from both domestic producers and imported sources.
South Korea
Classification society-certified shipbuilding demand is recovering as naval and commercial orderbooks rebuild from multi-year lows. The Ministry of Trade, Industry and Energy is promoting domestic welding consumable production through industrial technology development programs. Busan-Ulsan shipyard clusters specify dual-certified electrodes for hull and tank welding applications.
Stick Welding Electrode Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where premium formulation expertise and mass-market production efficiency rarely coexist. The vendor base spans integrated steelmakers with captive wire supply, specialized welding consumable houses with deep flux formulation libraries, and regional compounders serving price-sensitive construction markets. Dominant competitive moves include backward integration into flux mineral sourcing and geographic expansion through distributor network acquisitions.
Among North American-based manufacturers, Lincoln Electric Holdings, Inc. and Illinois Tool Works Inc. occupy positions emphasizing technical service bundling and distributor infrastructure. Japanese and Korean producers including Kobe Steel Ltd. and Kiswel Co., Ltd. exemplify the integrated steelmaker archetype with captive wire-to-electrode conversion capabilities. European specialists such as voestalpine Böhler Welding and ESAB Group, Inc. represent premium-tier positioning around extreme-service formulations and project-level technical support.
| Leading Market Players |
|---|
| Lincoln Electric Holdings, Inc. |
| ESAB Group, Inc. |
| Kobe Steel Ltd. |
| voestalpine Böhler Welding |
| Tianjin Golden Bridge Welding Materials Group |
| Ador Welding Limited |
| Jiangsu Boda Welding Group |
| Kiswel Co., Ltd. |
| Illinois Tool Works Inc. |
| Others |
Value Network & Pricing Analysis
Jiangsu and Shandong provinces anchor global electrode compounding capacity, with their flux mineral processing clusters feeding downstream pricing power to integrated steelmakers who control wire rod supply. This geographic concentration lets captive producers dictate terms to independent compounders while spot rutile and ilmenite volatility transmits directly into margin compression for non-integrated players.
Pricing Analysis
Long-term offtake agreements between EPC contractors and electrode manufacturers dominate the procurement landscape, bundling technical training and storage conditioning into multi-project frameworks. Three-tier pricing structure across premium low-hydrogen, standard rutile, and economy basic electrodes reflects certification grade and after-sales service intensity. Cost compression in economy grades is intensifying because Chinese flux mineral supply concentrates among integrated producers. Pipeline contractors show the least price sensitivity due to narrow construction windows, while Indian highway fabricators drive the hardest volume discounts.
Supply Chain Analysis
Tariff exposure between China and Western fabrication markets dominates supply chain risk planning for electrode distributors. Over sixty percent of global flux coating raw materials and specialty core wire originate from Chinese integrated steelmakers, with secondary sourcing from Japanese and Korean wire mills. The electrode supply chain rests on rutile concentrate, ilmenite, and low-carbon steel wire rod as critical inputs. Single-source vulnerability in Chinese flux mineral processing creates systemic exposure. Distribution runs through welding supply houses and emerging B2B procurement platforms serving mid-sized fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as solid and flux-cored wire processes capture automated fabrication volume from stick electrodes in shop environments.
For Market Incumbents: Entrench technical service bundling through embedded welding engineers and storage conditioning contracts that raise switching costs for energy sector buyers. Deepen backward integration into flux mineral sourcing to offset Chinese supply concentration. Capture certified welder shortage value by expanding training infrastructure and qualification services. For New Entrants and Emerging Players: Indian domestic production gaps offer the most penetrable white-space, where shipyard and infrastructure demand outpaces local compounding capacity. Establish regional flux formulation facilities to displace imports and exploit Bureau of Indian Standards certification tightening. Lead with digital distributor platforms that disintermediate traditional welding supply houses and enable direct manufacturer-fabricator relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized welding consumable houses with deep flux formulation libraries over mass-market compounders. Long-term viability hinges on low-carbon feedstock certification capabilities as EU Green Deal steel mandates propagate. Watch offshore wind project FID velocity as the inflection signal for premium electrode demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flux Mineral Sourcing | Reduces exposure to Chinese rutile concentrate volatility and margin compression. |
| Low-Carbon Feedstock Certification Program | Positions electrode lines for EU Green Deal steel mandates and premium pricing. |
| Regional Compounding Facility Expansion | Captures Indian import substitution demand and shortens logistics to shipyard clusters. |
| Digital Distributor Platform Launch | Disintermediates traditional supply houses and locks direct technical support relationships. |
| Certified Welder Training Infrastructure Buildout | Monetizes operator shortage through bundled qualification and procedure development services. |
Research Methodology
Operator-level perspectives from welding engineers, EPC procurement leads, shipyard quality managers, and distributor technical sales anchored the qualitative base. Primary interviews combined with secondary validation from AWS A5.1 certification databases, ISO 2560 test records, customs trade flows, and SEC filings from listed welding consumable producers. Bottom-up electrode consumption estimates triangulated against top-down steel fabrication activity indices.
Scenario-bracketing around offshore wind deployment velocity and pipeline construction seasonality shaped the analytical framework across the analysis window. Segmentation modeling covered electrode formulation type, application end-use, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating flux mineral price cycles and welder availability constraints. Forecast inputs included monopile fabrication contract awards and Bureau of Indian Standards enforcement timelines.
Practitioners should monitor EU F-Gas Regulation enforcement intensity and Chinese flux mineral export licensing for early signals of supply-cost revision. Forecasts reflect assumptions about certified welder pipeline completion rates and low-carbon wire rod commercialization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Global Welding Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Bale Openers Market
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
GCC Crane Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
Shield Machines Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Latin America Construction Equipment Market