
 Electric Excavators Market | 2026-2036
Electric Excavators Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Excavators Market Analytics
High-voltage battery certification above 600V is bifurcating the competitive landscape. Hitachi Construction Machinery leverages its integrated motor-drive manufacturing to control premium platform costs. Volvo Construction Equipment anchors European municipal tenders with region-specific charging infrastructure. JCB differentiates through compact electric architecture purpose-built for urban demolition envelopes.
Electric excavators replace diesel-hydraulic powertrains with lithium-ion battery packs, permanent magnet synchronous motors, and regenerative hydraulics to perform earthmoving, trenching, and material handling without tailpipe emissions. Mini excavators dominate urban rental fleets where noise ordinances and indoor operation requirements restrict combustion equipment. Battery-operated technology captures the fastest expansion as energy density improvements extend runtime beyond single-shift thresholds. Site preparation applications concentrate margin pools where emission-sensitive infrastructure contracts command equipment premiums.
EPA Tier 4 Final and California CARB zero-emission mandates in the United States, EU Stage V and F-Gas Regulation in Europe, and China's MIIT new energy equipment catalog collectively restrict diesel-powered machinery access to regulated project sites. Compliance with these frameworks now determines fleet eligibility for public infrastructure tenders across multiple jurisdictions. Stakeholders must monitor battery recycling liability frameworks and charging standard harmonization as these factors will determine total cost of ownership advantages against diesel baselines.
Market Dynamics
High-voltage battery architecture above 600V is bifurcating competitive positioning between integrated motor-drive manufacturers and charging infrastructure specialists, forcing equipment OEMs to choose between captive powertrain production or ecosystem partnerships.
Growth Catalysts
- EU Stage V and F-Gas Regulation:Berlin's diesel restrictions for urban construction sites are accelerating zero-emission fleet procurement among German infrastructure contractors.
- Battery energy density improvements:Single-shift runtime thresholds now extend beyond eight hours, enabling full-shift deployment in tunneling operations across Seoul's metropolitan transit expansion.
- Site preparation premiums:Emission-sensitive infrastructure contracts in California command equipment premiums under CARB zero-emission mandates, concentrating margin pools for compliant fleets.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing concentrates in China, exposing non-Chinese OEMs to supply chain vulnerability and input cost volatility.
- High-voltage certification timelines:IEC 60204-1 compliance for systems above 600V extends product development cycles by 12-18 months versus standard voltage platforms.
- Used diesel equipment arbitrage:Secondary markets in Southeast Asia absorb retiring European diesel fleets, delaying net fleet turnover and extending competitive pressure from combustion alternatives.
Strategic Opportunities
- India's PLI scheme for new energy equipment:Domestic manufacturing incentives for battery-electric construction machinery create localized production cost advantages for early entrants.
- Battery-swappable mini excavator architecture:South Korean tunneling contractors are piloting hot-swap systems that eliminate charging downtime in continuous-operation environments.
- Regenerative hydraulics convergence:Integration of permanent magnet synchronous motors with energy recovery systems opens retrofit potential for existing hydraulic excavator installed base.
Industry Challenges
- High-voltage technician certification gaps:Qualified service personnel for 600V+ battery systems remain scarce across European dealer networks, constraining after-sales support scaling.
- Charging infrastructure interoperability:Fragmented connector standards between CCS2, CHAdeMO, and proprietary OEM protocols complicate multi-brand fleet charging deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Excavators Market |
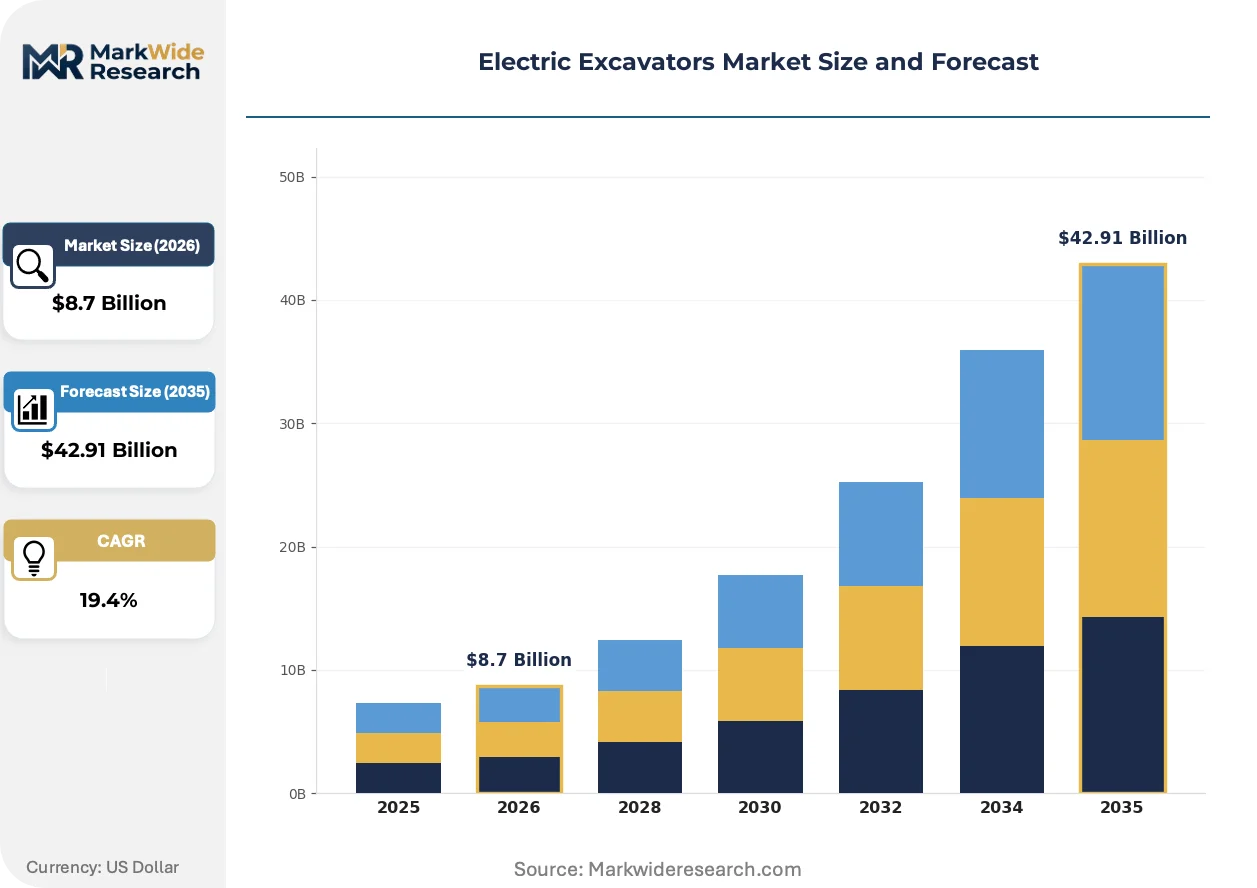
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Excavators, Standard Excavators, Large Excavators, Hybrid Excavators End User: Construction, Mining, Demolition, Landscaping Technology: Battery Operated, Plug-in Hybrid, Solar Powered, Fuel Cell Application: Site Preparation, Material Handling, Trenching, Excavation |
| Companies Covered | Hitachi Construction Machinery, Liebherr Group, Volvo Construction Equipment, JCB, Kobelco Construction Machinery, Develon, Doosan Infracore, L&T Construction & Mining Machinery, Caterpillar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Excavators Market Evolving Landscape
Electrification is compressing the traditional powertrain value chain, merging battery chemistry, motor control, and hydraulic system engineering into unified platform architectures that redefine equipment lifecycle economics.
Permanent magnet synchronous motor systems are supplanting diesel-hydraulic powertrains in urban demolition envelopes where noise ordinances restrict combustion equipment. Municipal rental fleets in German metropolitan zones are standardizing compact electric excavators for indoor renovation contracts. This technology compression is enabling OEMs to capture service revenue streams previously lost to independent engine rebuilders.
EPA Tier 4 Final and California CARB zero-emission mandates are prohibiting diesel-powered machinery access to public infrastructure tenders across regulated U.S. project sites. Compliance now determines fleet eligibility for federal highway and transit construction awards. Equipment lessors in Texas and Florida are accelerating electric inventory builds to maintain contractor relationships as state-level adoption spreads.
Rental fleet operators are unbundling after-sales service from equipment procurement, creating separate contracting vehicles for battery maintenance and charging infrastructure. This model shift concentrates buyer power among national rental chains with captive service capabilities. The transformation is most visible in South Korea, where Seoul's transit authority mandates performance-based availability contracts rather than traditional lease arrangements.
Electric Excavators Market Segmentation
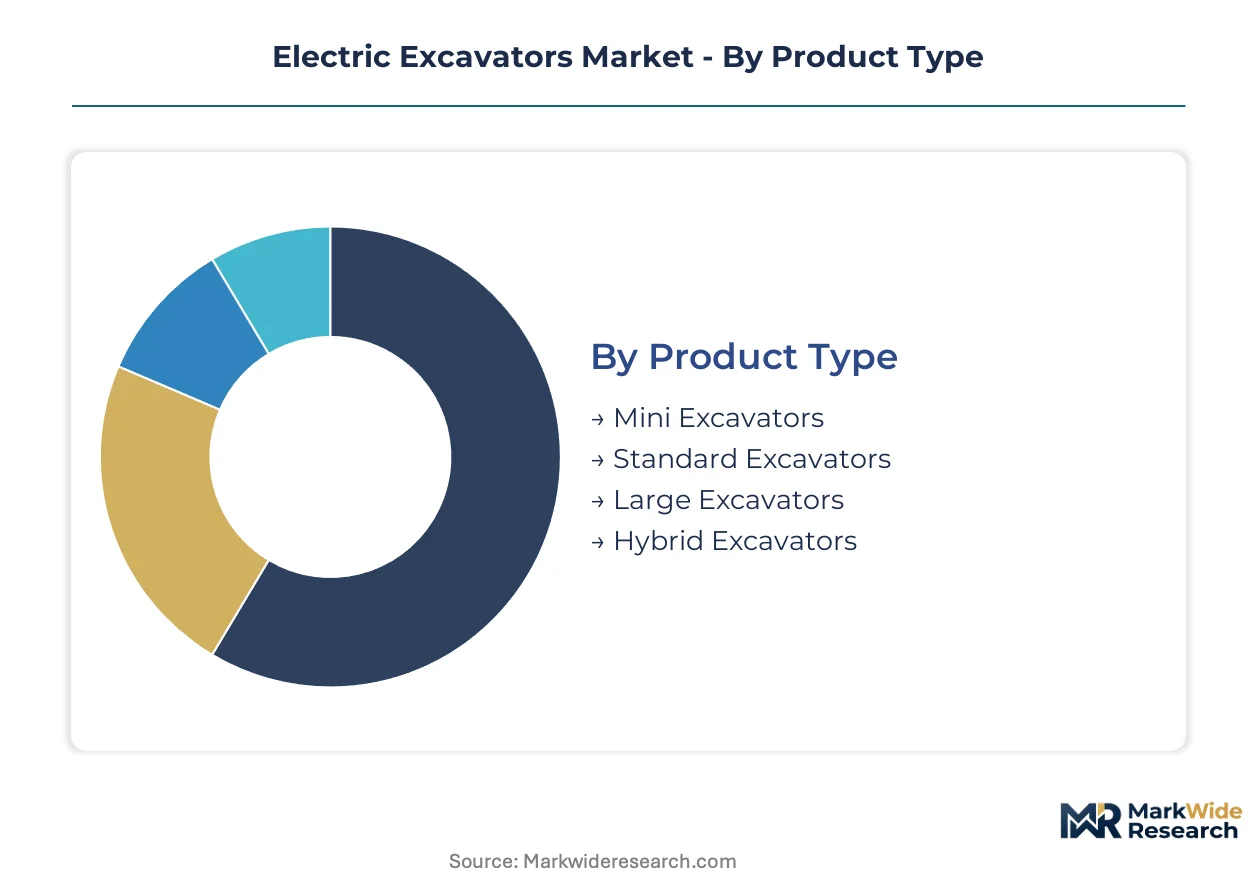
Segmentation in electric excavators reveals divergent channel strategies across product architectures. Rental fleets favor compact formats with swappable batteries, while infrastructure contractors procure larger platforms with integrated charging. Technology choices determine margin structures and service revenue potential.
Product Type:
Mini excavators flow through municipal rental channels where noise ordinances restrict combustion equipment. Standard and large formats concentrate in fleet procurement by infrastructure contractors with captive charging infrastructure. Hybrid architectures serve transitional customers bridging diesel retirement timelines.
- Mini Excavators:Compact electric platforms below 6 metric tons deploy lithium-ion packs under 300V for urban demolition envelopes. Seoul's metropolitan transit contractors specify these for tunneling contracts with hot-swap battery systems. German municipal rental fleets standardize this format for indoor renovation work under Berlin's diesel restrictions.
- Standard Excavators:Mid-size platforms between 6-20 metric tons integrate 600V+ high-voltage architectures with permanent magnet synchronous motors. California infrastructure contractors command equipment premiums under CARB zero-emission mandates for site preparation contracts. This segment concentrates OEM investment in integrated motor-drive manufacturing.
- Large Excavators:Heavy platforms above 20 metric tons face energy density constraints for all-day operation without battery swap infrastructure.
- Hybrid Excavators:Diesel-electric parallel architectures serve contractors in regions with sparse charging networks or intermittent duty cycles.
Mini excavators dominate installed base in urban rental fleets. Standard excavators are where expansion concentrates for emission-sensitive infrastructure contracts.
End User:
Customer type determines procurement modality and service bundling. Municipal authorities mandate performance-based availability contracts. Private contractors optimize for total cost of ownership against diesel baselines.
- Construction:General building contractors represent the largest equipment procurement volume, with fleet decisions driven by project eligibility under EPA Tier 4 Final and EU Stage V regulations. Urban infrastructure specialists in Germany accelerate zero-emission procurement as Berlin tightens diesel restrictions for building sites.
- Mining:Underground operations prioritize zero-emission platforms for ventilation cost reduction and worker safety compliance. Battery energy density improvements now extend runtime beyond single-shift thresholds for continuous tunneling operations.
- Demolition:Indoor deconstruction specialists specify compact electric excavators where noise ordinances prohibit combustion equipment.
- Landscaping:Residential and commercial grounds maintenance contractors favor mini excavators for noise-sensitive neighborhood work.
Construction commands the largest equipment volume. Mining is climbing the fastest as underground emission regulations tighten.
Technology:
Powertrain architecture bifurcates between battery-dominant platforms and transitional hybrid systems. Energy source selection locks in charging infrastructure requirements and technician certification needs.
- Battery Operated:Pure electric platforms with lithium-ion packs and regenerative hydraulics capture the steepest expansion trajectory. South Korean tunneling contractors pilot hot-swap systems that eliminate charging downtime. Energy density improvements now enable full-shift deployment beyond eight hours.
- Plug-in Hybrid:Diesel-electric architectures bridge regions with incomplete charging infrastructure or contractors managing mixed fleet transitions.
- Solar Powered:Photovoltaic-integrated systems serve remote or off-grid applications with intermittent duty requirements.
- Fuel Cell:Hydrogen fuel cell platforms target heavy-duty cycles where battery weight compromises payload capacity.
Battery operated systems dominate new product development investment. Plug-in hybrid retains share in markets with charging infrastructure gaps.
Application:
Work function determines duty cycle intensity and energy consumption profiles. High-intermittency applications favor battery platforms with regenerative recovery.
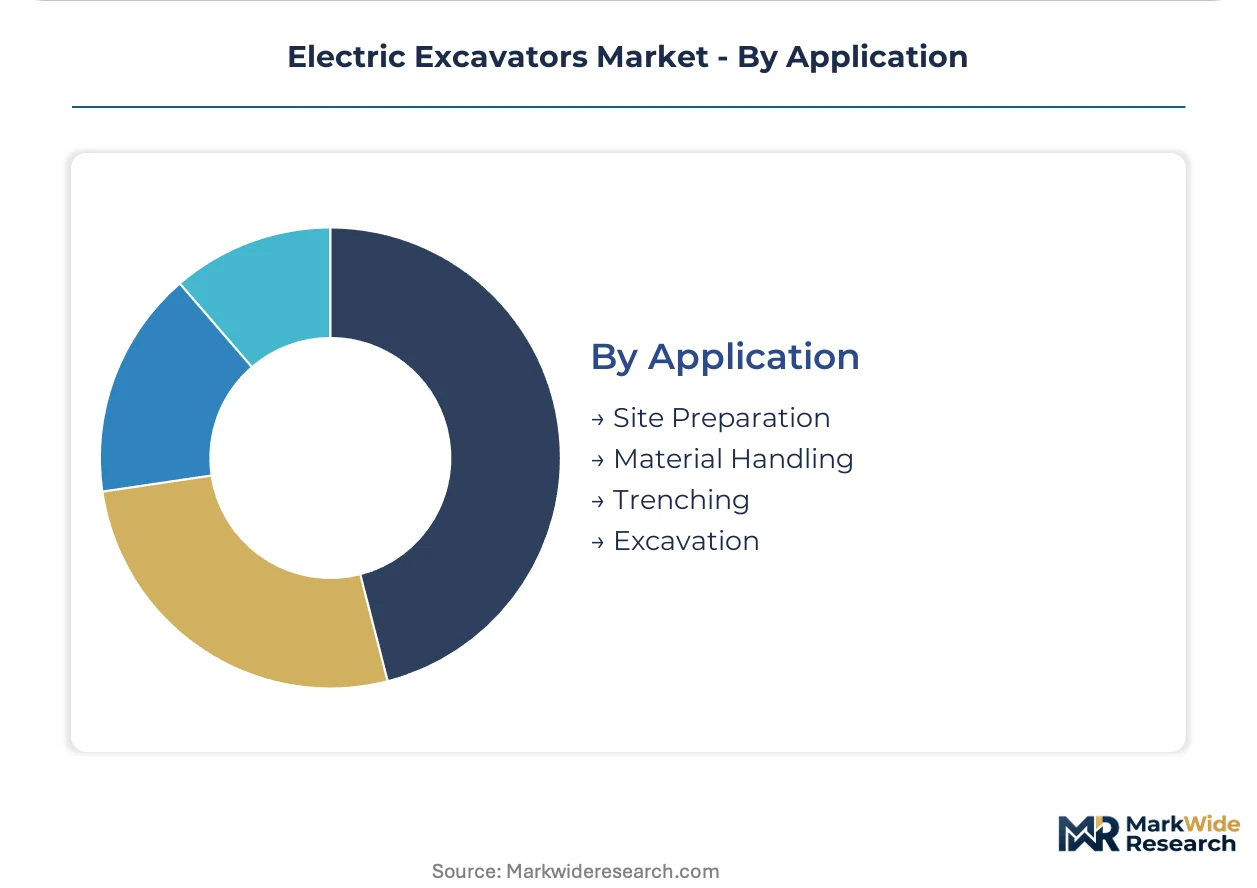
- Site Preparation:Grading and clearing operations concentrate margin pools where emission-sensitive contracts command equipment premiums. California contractors under CARB mandates drive specification intensity for this application.
- Material Handling:Load-and-carry cycles with frequent deceleration benefit from regenerative hydraulic energy recovery systems.
- Trenching:Continuous digging operations test battery endurance and thermal management in high-voltage architectures.
- Excavation:General earthmoving spans product sizes from mini urban formats to large mining platforms.
Site preparation dominates premium pricing capture. Material handling is gaining share fastest from regenerative energy recovery integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-voltage battery systems tilts trade balances toward East Asian manufacturing clusters. Equipment OEMs in Europe and North America source lithium-ion cells from concentrated cathode processing centers, creating procurement vulnerabilities that shape regional fleet deployment timelines.
United States
California infrastructure contractors command equipment premiums under CARB zero-emission mandates for site preparation contracts. EPA Tier 4 Final regulations prohibit diesel machinery access to federal highway tenders. Los Angeles and San Francisco metropolitan zones drive specification intensity for compact electric formats in urban demolition envelopes.
Germany
Berlin's tightening diesel restrictions for building sites accelerate zero-emission fleet procurement among urban infrastructure specialists. EU Stage V and F-Gas Regulation determine fleet eligibility for municipal tenders across German metropolitan zones. Munich and Hamburg rental fleets standardize battery-swappable mini excavators for indoor renovation contracts.
South Korea
Seoul's metropolitan transit expansion drives tunneling contracts specifying hot-swap battery systems that eliminate charging downtime. The country's new energy equipment catalog under MIIT influences regional technology roadmaps. Busan-Ulsan industrial clusters pilot performance-based availability contracts replacing traditional lease arrangements.
China
Domestic cathode material processing concentration exposes non-Chinese OEMs to supply chain vulnerability and input cost volatility. MIIT new energy equipment catalog restricts diesel-powered machinery access to regulated project sites. Yangtze River Delta manufacturing clusters integrate permanent magnet synchronous motor production with battery pack assembly.
India
The PLI scheme for new energy equipment creates localized production cost advantages for battery-electric construction machinery entrants. Central Electricity Authority regulations shape charging infrastructure deployment timelines for fleet operators. Maharashtra and Gujarat industrial corridors concentrate early entrant manufacturing capacity for domestic and export markets.
Electric Excavators Market Competitive Landscape
Concentration sits with integrated motor-drive manufacturers controlling premium platform costs through captive powertrain production. Equipment OEMs bifurcate between high-voltage architecture specialists above 600V and compact electric architects purpose-built for urban demolition envelopes. Strategic moves center on charging infrastructure partnerships and battery-swappable format development for continuous-operation environments.
Within the integrated manufacturing tier, Hitachi Construction Machinery and Volvo Construction Equipment exemplify archetypes leveraging in-house motor-drive production to control platform economics. JCB occupies a distinct position in compact electric architecture optimized for municipal rental channels where noise ordinances restrict combustion equipment. These three anchors represent divergent strategic postures: captive vertical control, regional charging ecosystem anchoring, and purpose-built urban format specialization.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| Liebherr Group |
| Volvo Construction Equipment |
| JCB |
| Kobelco Construction Machinery |
| Develon |
| Doosan Infracore |
| L&T Construction & Mining Machinery |
| Caterpillar |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between South Korean tunneling contractors and cathode material processors lock in lithium-ion cell supply at fixed unit economics while insulating fleet operators from spot-market volatility in battery-grade nickel and cobalt. These contracts simultaneously secure charging infrastructure deployment timelines and stabilize total cost of ownership calculations against diesel baselines across Seoul's metropolitan transit expansion projects.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the electric excavator market. Premium tiers command certification premiums for IEC 60204-1 high-voltage compliance above 600V, while standard segments optimize for municipal rental fleet volume procurement. Cost compression in economy tiers is intensifying because used diesel equipment arbitrage from retiring European fleets delays net fleet turnover. Construction contractors managing mixed fleet transitions exhibit highest price sensitivity, whereas mining operators prioritizing ventilation cost reduction show lowest sensitivity to upfront equipment premiums.
Supply Chain Analysis
Port congestion along the Yangtze River Delta-to-Busan trade lane elevates inbound logistics costs for permanent magnet synchronous motors and integrated motor-drive assemblies. Cathode material processing concentrates in China, South Korea, and Japan, drawing from lithium carbonate feedstock anchored in Chile and Australia. Single-source vulnerability in high-voltage battery certification testing creates procurement bottlenecks extending product development cycles. Distribution runs through regional equipment lessors with captive service capabilities in German metropolitan zones and California infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric excavators sit in early-cycle expansion as battery energy density improvements displace single-shift runtime constraints that previously limited full-shift deployment in tunneling and site preparation applications.
For Market Incumbents: Secure captive powertrain production through backward integration into permanent magnet synchronous motor manufacturing to defend margin position against integrated specialists. Anchor charging infrastructure partnerships in German metropolitan zones where EU Stage V and F-Gas Regulation accelerate zero-emission fleet procurement. Prioritize high-voltage technician certification programs across European dealer networks to constrain after-sales support scaling by emerging competitors.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for new energy equipment to capture localized production cost advantages before domestic manufacturing incentives attract established OEM capacity. Target battery-swappable mini excavator architecture for South Korean tunneling contractors piloting hot-swap systems that eliminate charging downtime. Pursue performance-based availability contracting models replacing traditional lease arrangements in Busan-Ulsan industrial clusters.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated motor-drive manufacturers with in-house battery pack assembly capabilities and established high-voltage certification pathways. Long-term viability hinges on exposure to emission-sensitive infrastructure contracts commanding equipment premiums under CARB and EU Stage V mandates. Monitor harmonization progress between CCS2, CHAdeMO, and proprietary OEM charging protocols as inflection indicator for multi-brand fleet deployment scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Battery Certification Investment | IEC 60204-1 compliance above 600V unlocks premium platform access in California infrastructure tenders. |
| Charging Infrastructure Partnership | Regional ecosystem anchoring secures fleet eligibility under Berlin's tightening diesel restrictions. |
| Backward Integration into Motor-Drive Manufacturing | In-house permanent magnet synchronous motor production controls platform economics against supply chain volatility. |
| Battery-Swappable Architecture Development | Hot-swap systems eliminate charging downtime for continuous-operation tunneling contracts in Seoul. |
| Performance-Based Availability Contracting | Service revenue unbundling from equipment procurement concentrates buyer power among national rental chains. |
Research Methodology
A spread of perspectives from OEM platform engineers, municipal fleet procurement managers, aftermarket service heads, and high-voltage battery system technicians converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed construction equipment manufacturers, MIIT new energy equipment catalog updates, CARB zero-emission mandate documentation, and EU Stage V regulatory filings. Bottom-up equipment deployment estimates triangulated against top-down infrastructure contract value analysis.
Segmentation dimensions modeled span product type across mini, standard, large, and hybrid excavator formats; end user categories including construction, mining, demolition, and landscaping; technology architectures covering battery operated, plug-in hybrid, solar powered, and fuel cell systems; and application functions from site preparation through material handling and trenching. CAGRs were derived through regression analysis of historical fleet turnover rates against regulatory mandate implementation timelines, incorporating battery energy density improvement curves and charging infrastructure deployment schedules as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement for EPA Tier 4 Final, EU Stage V, and CARB zero-emission mandates; material deviation in lithium-ion cell supply concentration or charging standard harmonization would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Bulldozer Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Global Welding Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Used Backhoe Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Winch Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Wood Chipper Machines Market