
 Hydraulic Hose Market | 2026-2036
Hydraulic Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Hose Market Analysis
Synthetic rubber compounds are restructuring cost-performance trade-offs across hydraulic hose portfolios. Parker Hannifin leverages captive polymer compounding to sustain margin stability in North American distribution. Alfagomma Group anchors Mediterranean supply through vertically integrated rubber mixing and wire braiding operations. Eaton competes on aerospace certification density, differentiating its spiral-reinforced lines for flight-control hydraulics.
A hydraulic hose is a flexible, reinforced conduit engineered to transmit pressurized fluid, typically oil-based hydraulic fluid, between pumps, actuators, and control valves in machinery systems; construction-grade variants withstand operating pressures exceeding 6000 psi through alternating layers of high-tensile steel wire braid or spiral winding and oil-resistant synthetic rubber tubes manufactured via mandrel-built vulcanization. Spiral hoses command premium positioning in mining and oil-field applications where impulse fatigue resistance determines replacement intervals. Wire braid configurations dominate agricultural equipment for their balance of flexibility and cost. Thermoplastic lines are gaining specification share in industrial automation where weight reduction and chemical compatibility with biodegradable hydraulic fluids matter.
The US EPA regulates hydraulic fluid spill containment under Clean Water Act provisions, while OSHA mandates pressure-testing protocols for hose assemblies in industrial settings. ISO 18752 and SAE J517 define impulse-cycle benchmarks that determine product qualification for OEM supply contracts. Stakeholders must monitor evolving biodegradable fluid compatibility standards as European REACH restrictions and US bio-preferred procurement policies reshape material formulation requirements.
Market Dynamics
Construction machinery fleets are extending hydraulic hose replacement cycles through predictive maintenance integration, compressing aftermarket revenue pools while OEM specification density intensifies around impulse-fatigue certification benchmarks.
Growth Catalysts
- US EPA spill containment mandates:Clean Water Act enforcement drives replacement demand for legacy hose assemblies in coastal construction zones, accelerating specification upgrades to leak-resistant coupling designs.
- China infrastructure investment:Central government stimulus for high-speed rail and urban transit projects concentrates original equipment procurement in state-owned machinery fleets.
- Synthetic rubber compounding advances:Bio-based elastomer formulations compatible with biodegradable hydraulic fluids unlock specification wins in European municipal equipment tenders.
Market Restraints
- Steel wire price volatility:High-tensile wire braid feedstock costs swing with scrap metal and energy indices, squeezing margin stability for mandrel-built hose manufacturers.
- REACH formulation compliance:ECHA restrictions on phthalate plasticizers and short-chain chlorinated paraffins force reformulation cycles that extend qualification timelines for European OEM supply contracts.
- Thermoplastic substitution:Nylon-core thermoplastic lines displace rubber hoses in sub-3000 psi industrial automation applications where weight and routing flexibility dominate specification criteria.
Strategic Opportunities
- India construction equipment aftermarket:BIS certification requirements and infrastructure build-out create white space for impulse-tested hose assembly distributors in Mumbai and Delhi industrial corridors.
- Biodegradable fluid compatibility:USDA BioPreferred procurement preferences and EU Green Deal bio-lubricant mandates open premium positioning for HNBR and EPDM compound portfolios.
- Digital inventory integration:IoT-enabled hose condition monitoring converges with distributor ERP systems, enabling predictive replenishment contracts with mining and oil-field operators.
Industry Challenges
- ISO 18752 certification bottlenecks:Impulse-cycle testing capacity constraints at accredited laboratories extend OEM qualification timelines for spiral-reinforced product lines.
- Polymer compounding talent scarcity:Specialized rubber formulation expertise concentrates among aging technical workforces in Germany and Japan, constraining new facility ramp rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Hose Market |
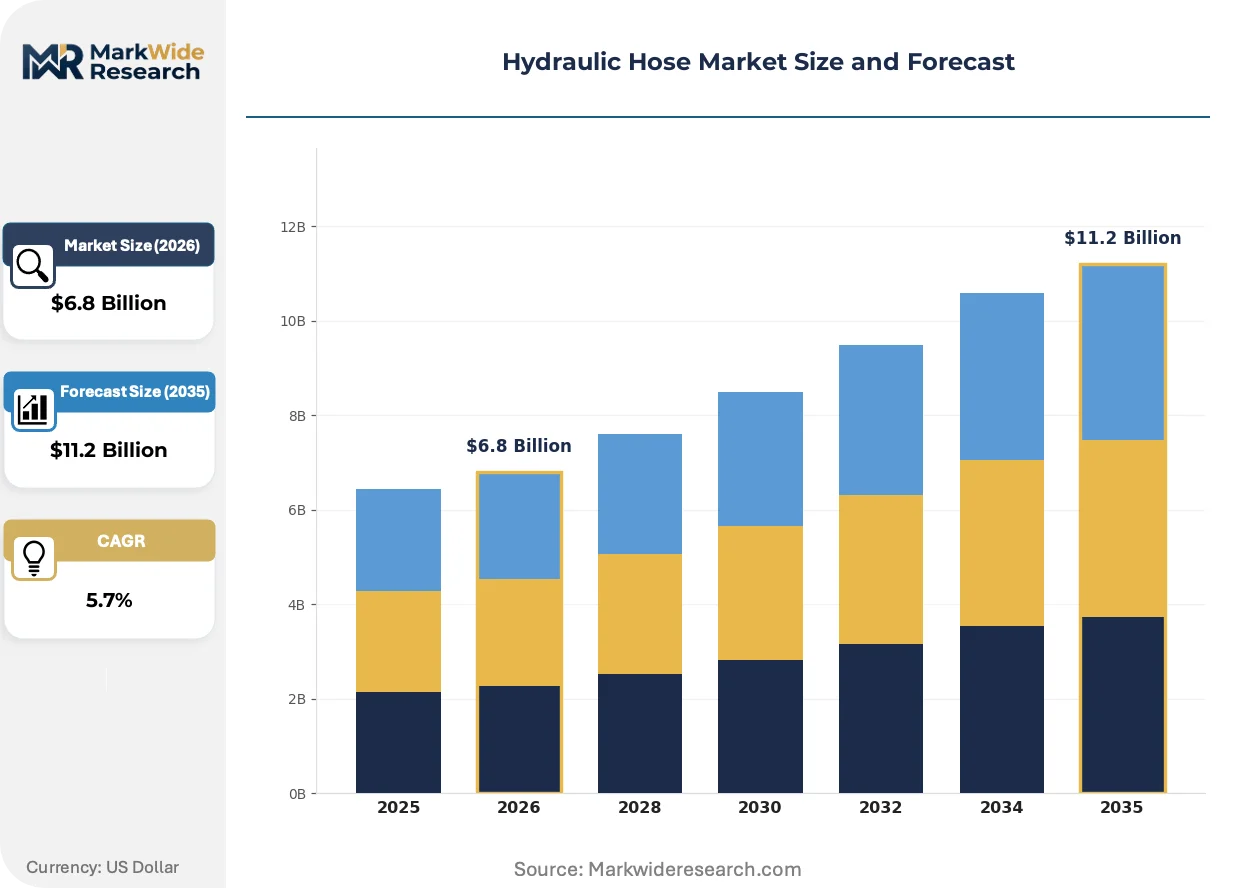
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Braid, Spiral, Rubber, Thermoplastic Application: Agricultural Equipment, Construction Machinery, Industrial Automation, Aerospace End User: Manufacturing, Transportation, Mining, Oil & Gas Size: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter |
| Companies Covered | Manuli Hydraulics, Alfagomma Group, Parker Hannifin, Utigoflex, Laike Hydraulics, Gates Corporation, RYCO Hydraulics, Semperit, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Hose Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry mandates are restructuring competitive positioning across pressure-rating tiers, while digital integration reshapes how operators manage hose lifecycle economics.
Electrohydraulic actuator integration is electrifying traditional hydraulic power transmission architectures in mobile machinery. Construction equipment OEMs in Germany and Japan are specifying intelligent hose assemblies with embedded pressure and temperature sensors. This convergence is electrifying aftermarket service models toward predictive replacement rather than scheduled interval maintenance.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of flame-retardant hydraulic fluid additives used in mining and tunneling applications. Compounders must validate new elastomer compatibility matrices against modified fluid chemistries. Spiral-reinforced product lines serving underground equipment face the steepest requalification burdens.
Consolidated fleet operators are unbundling hose assembly procurement from OEM service contracts, establishing direct relationships with tier-one distributors for specification-compliant bulk purchasing. Channel disintermediation concentrates volume with vertically integrated suppliers capable of same-day vulcanization and crimping services. This pattern is most visible in North American agricultural equipment markets where dealer networks cede aftermarket share to specialized fluid-power distributors.
Hydraulic Hose Market Segmentation
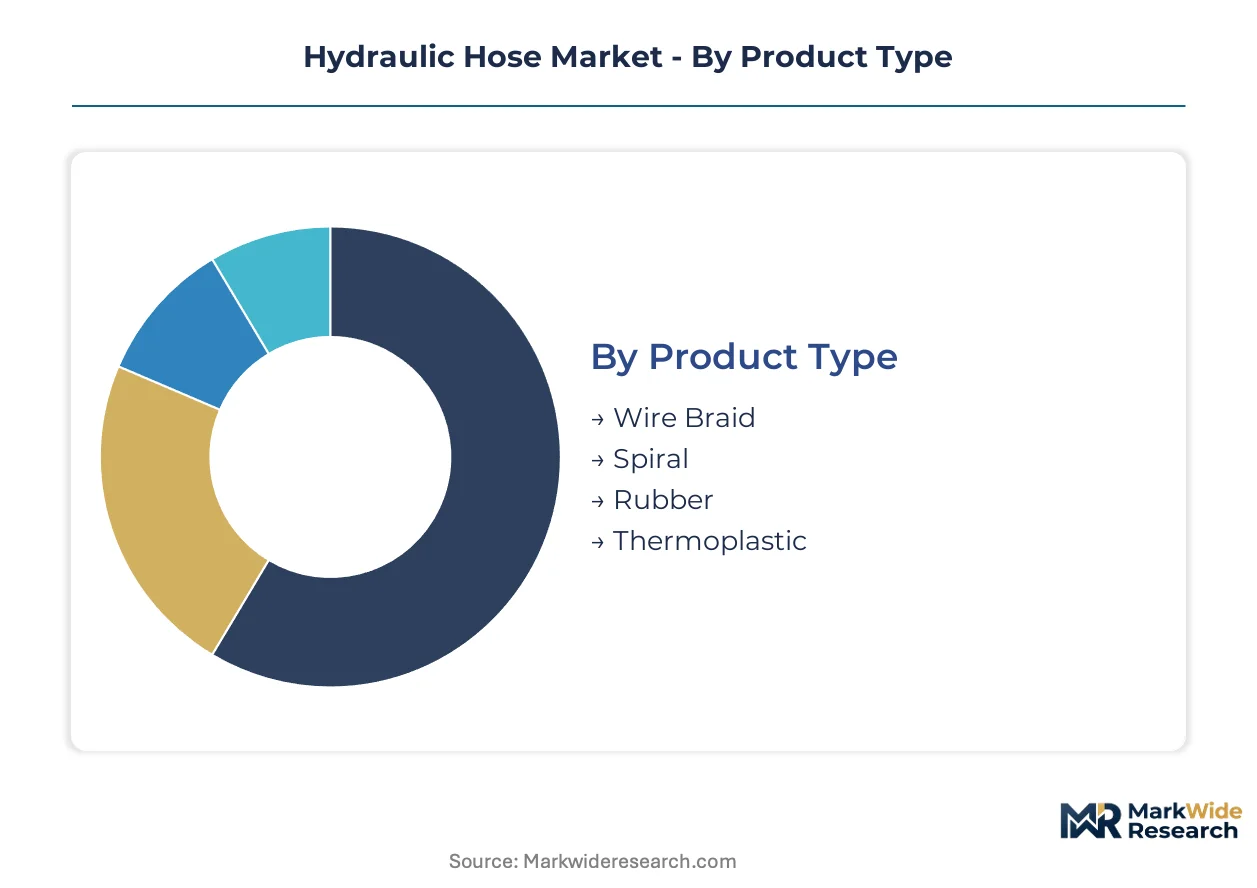
Hydraulic hose segmentation reflects divergent engineering requirements across pressure ratings, flexibility demands, and fluid compatibility regimes. Product architecture and end-use specifications determine margin profiles and qualification barriers for suppliers competing across mobile machinery, industrial automation, and energy extraction verticals.
Product Type:
The customization-vs-standardization spectrum runs from commodity wire braid configurations to application-engineered spiral and thermoplastic constructions requiring compound-specific validation.
- Wire Braid:Alternating layers of high-tensile steel wire wrapped around synthetic rubber tubes deliver flexibility for routing through confined machinery compartments. Agricultural equipment in the US Midwest concentrates procurement for tractor hydraulic systems where cost-performance balance outweighs impulse-fatigue specifications.
- Spiral:Multiple layers of helically wound wire create rigid, high-pressure conduits rated beyond 6000 psi for mining and oil-field applications. Underground equipment operators in Western Australia specify spiral constructions for their resistance to pressure spikes and extended cycle life under continuous load.
- Rubber:Mandrel-built vulcanization of nitrile or chloroprene compounds produces general-purpose hoses for medium-pressure industrial circuits. Standardized SAE J517 configurations dominate replacement demand in legacy manufacturing facilities.
- Thermoplastic:Nylon or polyester core tubes reinforced with synthetic fiber braid enable weight reduction and chemical resistance for sub-3000 psi automation systems. German automotive production lines specify thermoplastic lines for robotic arm actuation where routing flexibility reduces installation labor.
Leading the category by volume: Wire Braid. Growing fastest: Thermoplastic.
Application:
Cost tier stratification separates specification-intensive aerospace and oil-field segments from price-sensitive agricultural replacement cycles.
- Agricultural Equipment:Tractor and combine harvester hydraulics operate at moderate pressures with high flex-cycle demands. Brazilian soybean producers drive seasonal replacement volume through dealer network procurement concentrated around planting and harvest windows.
- Construction Machinery:Excavator and loader fleets subject hoses to abrasion, UV exposure, and impulse loading. Chinese state-owned equipment manufacturers anchor OEM specification density for high-speed rail and urban transit infrastructure projects.
- Industrial Automation:Factory robotics and material handling systems prioritize leak-free operation and precise pressure control. Japanese automotive assembly plants specify ISO 18752-certified assemblies for just-in-time production reliability.
- Aerospace:Flight-control hydraulics demand zero-failure tolerance under extreme temperature and vibration conditions. FAA certification density restricts qualified suppliers to spiral-reinforced lines with embedded sensor integration for condition monitoring.
Construction Machinery generates the largest revenue pool. Aerospace expands most quickly on sensor-integrated intelligent hose architectures.
End User:
Customer type determines procurement modality, with consolidated mining and oil-field operators unbundling assembly procurement from OEM service contracts.
- Manufacturing:Discrete and process industries specify hoses for machine tool coolant systems, press operations, and material handling. German Mittelstand metalworking shops prioritize DIN-standard compatibility for interoperability across mixed-vendor machinery parks.
- Transportation:Commercial vehicle braking and suspension systems, plus rail and marine hydraulics, require vibration-resistant constructions. Indian commercial vehicle manufacturers drive specification volume for Bharat Stage VI-compliant power steering circuits.
- Mining:Surface and underground extraction equipment subjects hoses to rock abrasion, chemical exposure, and pressure pulsation. South African platinum belt operators specify flame-resistant constructions meeting ISO 6805 for continuous miner hydraulic circuits.
- Oil & Gas:Drilling rigs, wellhead control systems, and subsea production equipment demand corrosion-resistant, high-pressure performance. Norwegian North Sea platforms specify API-certified spiral hoses for blowout preventer control lines.
Mining commands premium pricing per meter. Transportation offers the broadest volume base across replacement cycles.
Size:
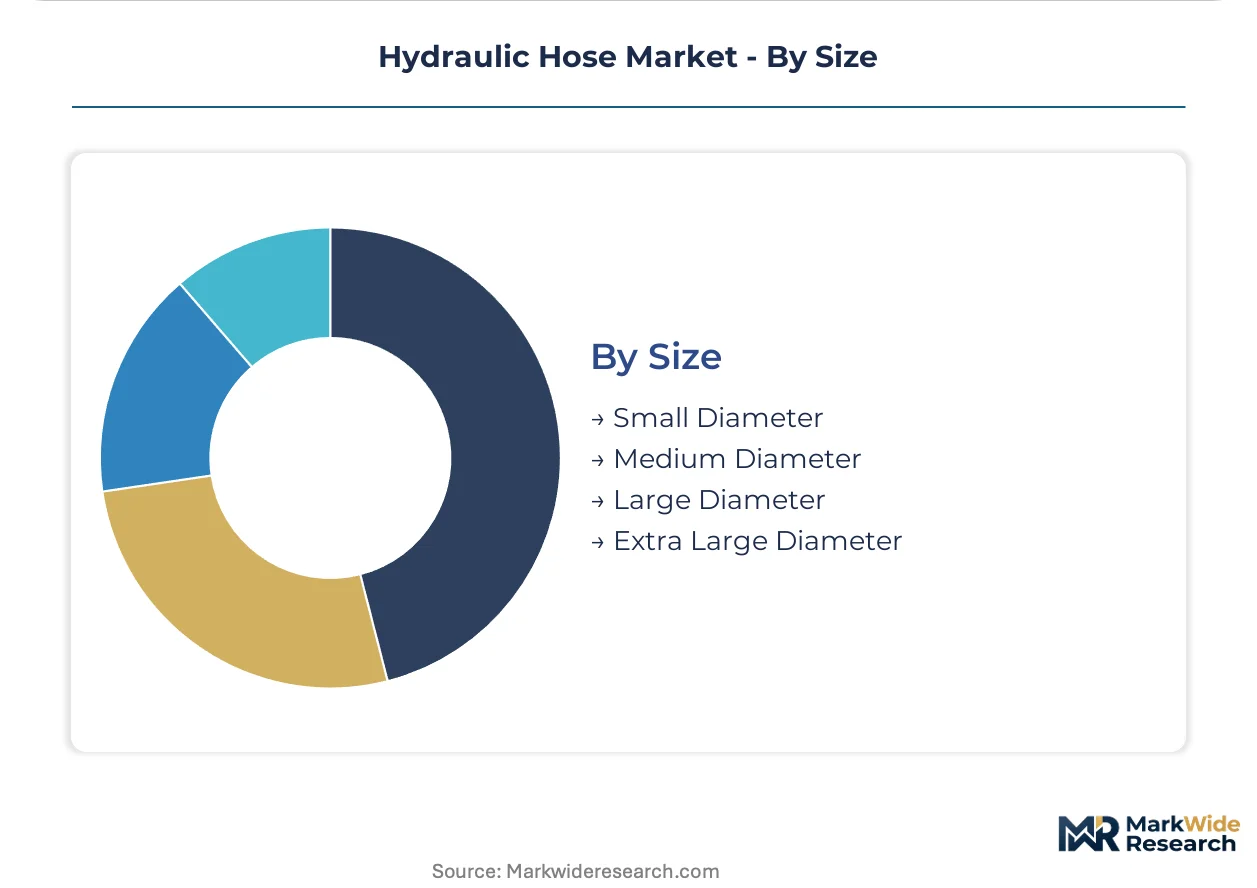
Volume concentration sits with medium-diameter configurations, while margin expansion tracks large and extra-large engineered-to-order specifications.
- Small Diameter:Inner diameters below 12mm serve instrument lines, pilot circuits, and compact mobile equipment. Japanese compact excavator manufacturers specify small-diameter thermoplastic lines for auxiliary hydraulic attachments.
- Medium Diameter:12-25mm range dominates general-purpose mobile machinery and industrial power transmission. US agricultural equipment fleets standardize medium-diameter wire braid configurations for three-point hitch and loader circuits.
- Large Diameter:25-50mm constructions handle high-flow suction and return lines in mining shovels and dredging equipment. Australian iron ore operations specify large-diameter spiral suction hoses for slurry transport with abrasion-resistant tube compounds.
- Extra Large Diameter:Above 50mm, custom-engineered suction and discharge hoses serve offshore oil transfer and marine applications. Brazilian pre-salt field operators procure extra-large diameter floating hoses for dynamic positioning systems.
Medium Diameter leads absolute volume. Extra Large Diameter shows the steepest expansion trajectory on offshore project revivals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates original equipment procurement for hydraulic hose systems through state-owned machinery fleets serving high-speed rail and urban transit build-outs. Infrastructure stimulus programs channel specification volume toward domestic OEM supply chains. Secondary demand nodes operate in Germany, the United States, India, and Brazil through distinct regulatory and procurement modalities.
China
Central government infrastructure stimulus drives hydraulic hose specification through state-owned construction equipment manufacturers. MIIT enforces GB standards for fluid-power equipment safety and emissions compliance. Shanghai and Jiangsu province industrial clusters concentrate mandrel-built hose production for domestic OEM supply contracts.
Germany
Automotive and industrial automation OEMs specify ISO 18752-certified assemblies for just-in-time production reliability. ECHA REACH restrictions on phthalate plasticizers force compound reformulation cycles extending qualification timelines. Baden-Württemberg and Bavaria host specialized rubber formulation expertise concentrated among technical workforces.
United States
EPA Clean Water Act spill containment mandates accelerate replacement demand for legacy hose assemblies in coastal construction zones. OSHA pressure-testing protocols govern hose assembly qualification in industrial settings. Midwest agricultural equipment fleets standardize medium-diameter wire braid configurations through dealer network procurement.
India
BIS certification requirements and infrastructure build-out create aftermarket white space for impulse-tested hose assembly distributors. CDSCO and national standards bodies regulate equipment safety for commercial vehicle applications. Mumbai and Delhi industrial corridors concentrate specification-compliant bulk purchasing for construction machinery fleets.
Brazil
Soybean producers drive seasonal replacement volume through dealer network procurement concentrated around planting and harvest windows. ANVISA regulates equipment safety standards for agricultural machinery. São Paulo state anchors distribution infrastructure serving pre-salt field operators procuring extra-large diameter floating hoses.
Hydraulic Hose Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated tier-one suppliers commanding OEM specification density while regional fabricators capture aftermarket replacement cycles. Market structure tilts toward vertically integrated compounders capable of captive polymer mixing and wire braiding operations. Three archetypes dominate: diversified industrial conglomerates with aerospace certification density, Mediterranean specialists with backward integration into rubber mixing, and Asia-Pacific scale producers serving cost-sensitive agricultural segments. Competitive moves center on M&A for testing laboratory capacity and geographic expansion into Indian and Southeast Asian industrial corridors.
Among diversified industrial conglomerates, Parker Hannifin and Eaton exemplify archetypes built on certification density and sensor-integrated intelligent hose architectures. Alfagomma Group anchors Mediterranean supply through in-house rubber mixing and wire braiding operations. These three occupy positions spanning premium aerospace and industrial automation specifications through cost-optimized agricultural replacement cycles.
| Leading Market Players |
|---|
| Manuli Hydraulics |
| Alfagomma Group |
| Parker Hannifin |
| Utigoflex |
| Laike Hydraulics |
| Gates Corporation |
| RYCO Hydraulics |
| Semperit |
| Eaton |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII reformulation mandates for phthalate-free compounds are forcing compounders to absorb extended qualification costs, compressing margins on European-bound production while rewarding captive polymer mixing capabilities with pricing power.
Pricing Analysis
Volume concentrates in wire braid configurations serving agricultural replacement cycles where cost-per-meter sensitivity dominates procurement decisions, while margin expansion tracks spiral-reinforced and thermoplastic lines certified to ISO 18752 impulse-fatigue benchmarks. Price differentiation hinges on certification density and captive rubber compounding capabilities. Pricing pressure stems from steel wire feedstock volatility and thermoplastic substitution in sub-3000 psi industrial automation. Brazilian soybean producers exhibit highest price sensitivity through seasonal dealer procurement; aerospace flight-control specifications show lowest sensitivity due to zero-failure tolerance requirements.
Supply Chain Analysis
Single-source vulnerability sits with specialized rubber formulation expertise concentrated in Germany and Japan, constraining new facility ramp rates for mandrel-built vulcanization capacity. Manufacturing gravity centers on China, Italy, and the United States, with Jiangsu province and Baden-Württemberg hosting critical technical workforces. Feedstock dependencies include high-tensile steel wire braid, synthetic rubber compounds, and nylon-core thermoplastic resins. Tariff exposure on steel wire imports threatens margin stability for non-integrated fabricators. Distribution runs through tier-one fluid-power distributors capable of same-day vulcanization and crimping services, bypassing traditional OEM dealer networks in North American agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH and EPA compliance costs are constructing a barrier-to-entry moat around qualified suppliers, with ISO 18752 certification timelines extending beyond 18 months for spiral-reinforced product lines.
For Market Incumbents: Lock in specification density with Chinese state-owned construction equipment manufacturers through GB-standard compliance and backward integration into captive wire braiding operations. Thermoplastic substitution in industrial automation threatens rubber hose volumes; defend through sensor-integrated intelligent hose architectures for predictive maintenance contracts. For New Entrants and Emerging Players: Capture white space in Indian aftermarket distribution corridors around Mumbai and Delhi industrial belts where BIS certification requirements filter out unqualified competitors. Agricultural equipment in Brazil offers penetrable volume through seasonal dealer network relationships. Lead with biodegradable fluid compatibility positioning for European municipal equipment tenders. For Investors and Strategic Acquirers: The window for entry favors vertically integrated compounders with in-house rubber mixing and accredited impulse-cycle testing capacity. Long-term viability hinges on consolidation of testing laboratory assets as ISO 18752 bottlenecks intensify. Watch for REACH reformulation completion timelines as inflection signal for European OEM contract requalification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Parker Hannifin and Alfagomma sustain margin stability through captive polymer mixing operations. |
| ISO 18752 Testing Laboratory Acquisition | Accredited impulse-cycle capacity constraints extend OEM qualification timelines for spiral-reinforced lines. |
| Biodegradable Fluid Compatibility Certification | USDA BioPreferred and EU Green Deal mandates unlock premium positioning for HNBR compound portfolios. |
| Sensor-Integrated Intelligent Hose Development | Eaton leverages aerospace certification density for flight-control condition monitoring architectures. |
| Indian Distribution Corridor Expansion | BIS compliance requirements and infrastructure build-out concentrate aftermarket opportunity in Mumbai and Delhi. |
Methodological Framework
Multi-period observation of hydraulic hose replacement cycle extensions, predictive maintenance integration rates, and OEM specification density shifts anchored the trend analysis, supplemented by interviews with maintenance directors at mining and oil-field operators, OEM procurement teams at Chinese construction equipment manufacturers, aftermarket service heads at North American fluid-power distributors, and technical R&D directors at synthetic rubber compounders. Secondary validation drew from EPA Clean Water Act enforcement records, ECHA REACH restriction updates, MIIT GB standard filings, ISO 18752 certification databases, and customs trade data on high-tensile steel wire imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for construction machinery fleet expansion.
Segment-weighting across product type, application, end user, and pressure rating tiers structured the analytical framework, with wire braid, spiral, rubber, and thermoplastic configurations modeled separately. CAGRs derived from trend extrapolation of specification density shifts and replacement cycle compression patterns. Industry-specific inputs included biodegradable fluid compatibility adoption curves, REACH reformulation completion timelines, and Chinese infrastructure stimulus disbursement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel wire price volatility, thermoplastic substitution rates in industrial automation, and REACH restriction scope expansions. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM procurement modality shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Crushing Screening Equipment Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
ASEAN Conveyor System Market