
 Global Hydraulic Demolition Machine and Breaker Market | 2026-2036
Global Hydraulic Demolition Machine and Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Demolition Machine and Breaker Market Outlook
Infrastructure development is repositioning the buyer base away from pure mining customers toward urban demolition and road construction contractors. Caterpillar Inc leverages its integrated dealer network to dominate aftermarket parts and service revenue in North American breaker markets. Komatsu Limited anchors its competitive stance through in-house production of carrier machines matched to proprietary hydraulic attachment lines. Atlas Copco Ltd specializes in premium breaker designs for tunneling and quarrying applications where percussion efficiency determines operating economics.
Hydraulic demolition machines and breakers are percussive attachments mounted on excavators or dedicated carriers, utilizing pressurized oil flow from the host machine to drive a piston that strikes a tool bit at frequencies reaching 1,000 to 1,500 blows per minute for fracturing concrete, rock, or asphalt. Their primary commercial purpose is to deliver controlled material fragmentation without blasting in confined or populated environments where explosive methods are prohibited. Hydraulic breakers command the largest product type share due to universal compatibility with standard excavator hydraulic circuits across demolition and quarrying applications. Electro-hydraulic technology is gaining fastest in urban job sites where noise ordinances and emissions restrictions limit conventional pneumatic and mechanical alternatives. Rock hammers and rippers serve mature replacement demand in mining firms, while pile drivers concentrate margin pools with infrastructure developers on bridge and port projects requiring deep foundation work.
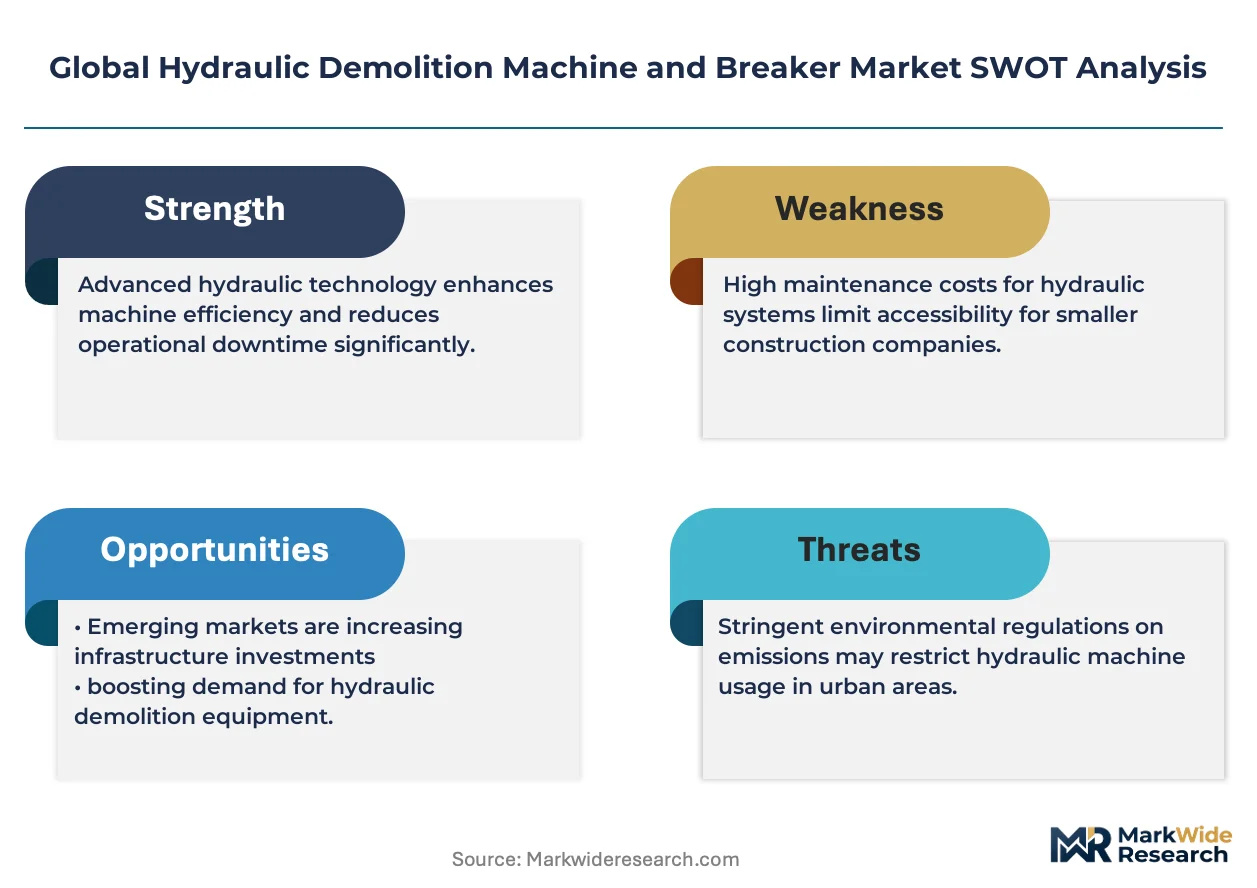
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by national type-approval authorities are compelling breaker OEMs to integrate hybrid power systems and acoustic dampening into new designs. Japan's METI energy-efficiency benchmarks and China's MEE emissions protocols are adding compliance layers for equipment exported into East Asian construction markets. Stakeholders must monitor how evolving carbon-border adjustments and local-content rules reshape manufacturing location decisions and aftermarket service requirements.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are compressing diesel-hydraulic architectures and forcing OEMs toward hybrid electro-hydraulic powerpack redesigns, restructuring competitive advantage around energy density and acoustic compliance rather than raw percussion output.
Growth Catalysts
- Urban Renewal Infrastructure:Southeast Asian megacities are mandating controlled demolition methods for building stock replacement, pulling hydraulic breaker deployment into dense metropolitan cores where blasting prohibitions apply.
- Smart City Mandates:India's national infrastructure pipeline is accelerating breaker procurement for road widening and utility corridor projects across tier-2 and tier-3 urban centers.
- Hybrid Powerpack Architecture:Electro-hydraulic systems integrating battery-electric assist modules are opening compliance pathways in noise-restricted European job sites governed by local acoustic ordinances.
Market Restraints
- High-Alloy Steel Input Volatility:Tool bit manufacturing depends on nickel-chromium-molybdenum alloys whose price swings compress margin predictability for attachment specialists.
- Carrier Machine Supply Concentration:Base excavator production clusters in Japan, South Korea, and China create dependency bottlenecks for breaker OEMs without captive carrier supply.
- Substitution by Mechanical Pulverizers:Urban concrete recycling yards are adopting fixed crushing stations with lower operating costs for high-volume material processing.
Strategic Opportunities
- Underpenetrated Indonesian Mining:Nickel and bauxite expansion in Sulawesi and Maluku is creating first-time demand for heavy-class breakers in surface extraction applications.
- EU Carbon Border Adjustment:CBAM phase-in is incentivizing local breaker assembly within European customs territory to avoid embedded emissions tariffs on imported finished attachments.
- Telematics-Enabled Rental:IoT-hour metering platforms are allowing equipment rental fleets to unbundle breaker attachments from carrier machines on short-term urban demolition contracts.
Industry Challenges
- Certification Timeline Compression:Dual homologation requirements for EPA Tier 4 Final and EU Stage V are extending product development cycles and delaying revenue recognition on new breaker platforms.
- Electro-Hydraulic Integration Complexity:Legacy excavator hydraulic circuits lack standardized electronic control architectures, forcing case-by-case retrofit engineering for hybrid breaker compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Demolition Machine and Breaker Market |
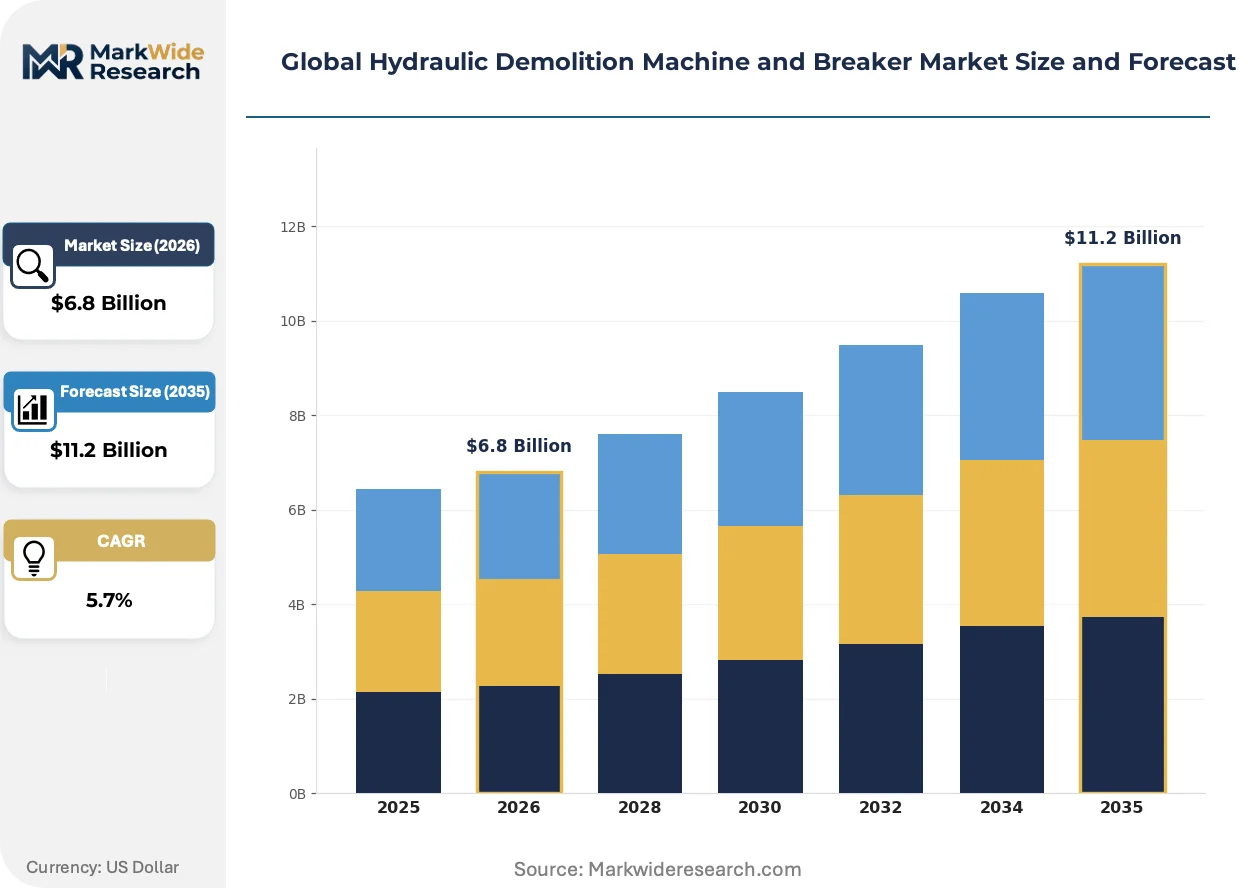
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Breakers, Rock Hammers, Pile Drivers, Rippers End User: Construction Companies, Demolition Contractors, Mining Firms, Infrastructure Developers Application: Road Construction, Building Demolition, Site Excavation, Quarrying Technology: Electro-Hydraulic, Pneumatic, Mechanical, Hybrid |
| Companies Covered | Caterpillar Inc, Komatsu Limited, Atlas Copco Ltd, INDECO N.A., Hitachi Construction Machinery, J C Bamford Excavators Ltd, Sandvik Construction, Montabert, Volvo Construction Equipment North America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Demolition Machine and Breaker Market Strategic Shifts
Active vibration suppression and energy recuperation systems are repositioning breaker performance metrics from raw impact energy to operator fatigue reduction and fuel consumption efficiency, altering procurement evaluation criteria across contractor segments.
Regenerative hydraulic accumulators are absorbing recoil energy from piston return strokes and feeding it back into the next impact cycle. Tunneling contractors in Alpine regions are adopting these systems most aggressively to meet strict diesel fuel allocation limits. The technology is absorbing capital investment that previously flowed into larger carrier machine purchases, compressing fleet expansion requirements.
EU Stage V type-approval authorities are enforcing real-driving emissions testing protocols for mobile machinery powerpacks. Breaker OEMs are responding by integrating selective catalytic reduction and diesel particulate filters into compact attachment housings. Urban demolition fleets in German and French metropolitan zones face the tightest compliance windows, accelerating pre-buy activity ahead of enforcement deadlines.
Rental channel penetration is displacing direct ownership models among mid-tier demolition contractors. Equipment-as-a-service platforms in North American metropolitan markets are unbundling maintenance and telemetry from capital acquisition, compressing traditional dealer finance penetration. This shift concentrates most visibly in California and New York state markets where environmental compliance costs amplify ownership risk.
Global Hydraulic Demolition Machine and Breaker Market Segmentation
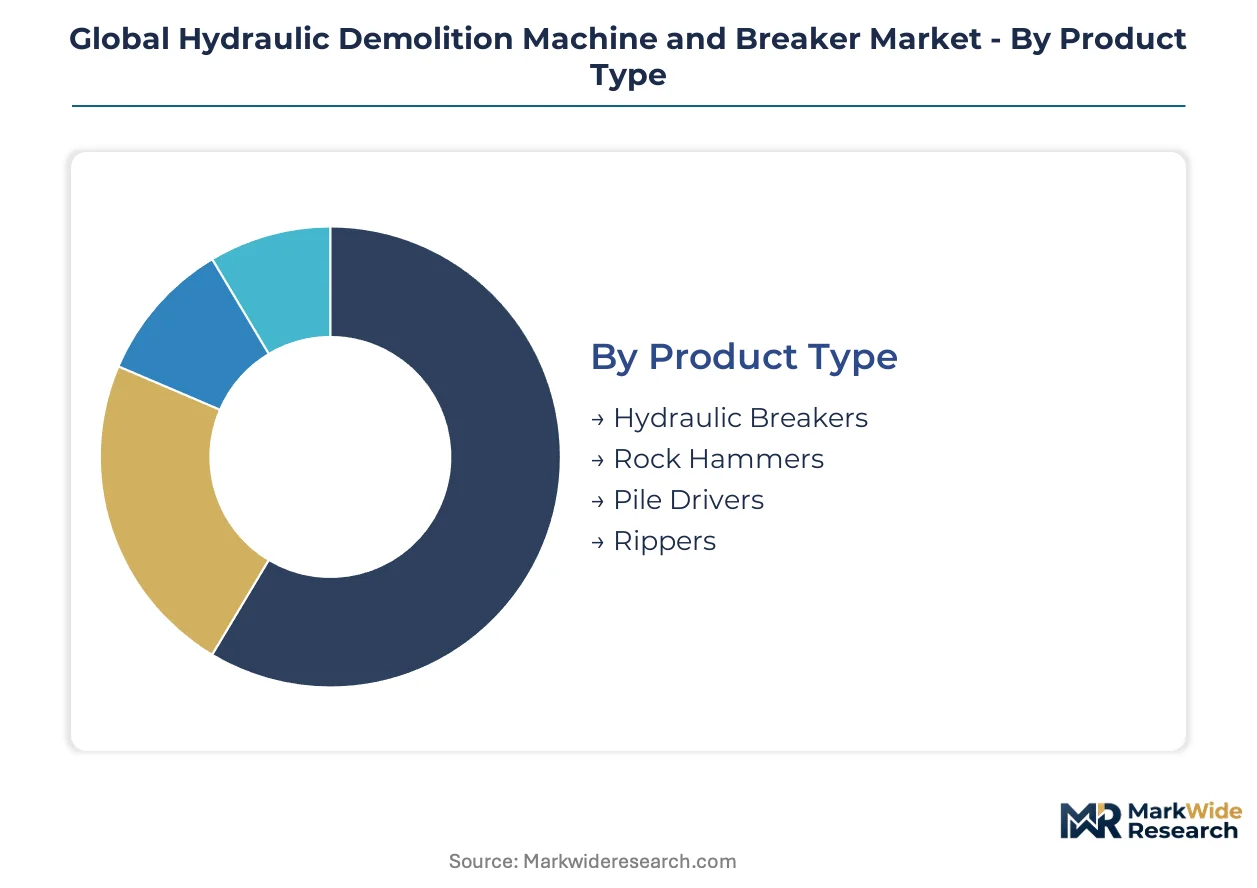
Segmentation in hydraulic demolition equipment reveals how regulatory pressure and application specificity reshape procurement patterns across contractor tiers. Certification burdens vary sharply by power source and deployment environment, forcing buyers to match segment selection to compliance timelines and job site constraints.
Product Type:
EPA Tier 4 Final and EU Stage V type-approval requirements fall most heavily on larger displacement units, while smaller breakers navigate lighter certification paths.
- Hydraulic Breakers:Percussive attachments utilizing pressurized oil flow to drive piston-strike mechanisms at 1,000 to 1,500 blows per minute. Demand concentrates with urban demolition contractors in Indian metropolitan zones where smart city mandates accelerate building replacement cycles. These units face the stiffest acoustic compliance burdens under German and French municipal noise ordinances.
- Rock Hammers:Heavy-class percussive tools engineered for fracturing consolidated rock formations in surface extraction. Mining firms across Indonesian Sulawesi and Maluku are expanding fleets for nickel and bauxite expansion projects. METI energy-efficiency benchmarks in Japan add compliance layers for units exported into East Asian construction markets.
- Pile Drivers:Vertical impact systems for deep foundation work on bridge and port infrastructure.
- Rippers:Scarification attachments for asphalt removal and soil loosening in road reconstruction.
Hydraulic Breakers sits at the top of the volume ranking, with Rock Hammers climbing the fastest.
End User:
Customer type determines financing structure and service bundling, with rental penetration reshaping mid-tier ownership patterns.
- Construction Companies:General contractors deploying breakers across road widening and utility corridor projects. India's national infrastructure pipeline pulls procurement toward tier-2 and tier-3 urban centers where fleet utilization rates justify direct ownership over rental.
- Demolition Contractors:Specialized operators in dense metropolitan cores governed by blasting prohibitions. California and New York state markets show the sharpest shift toward equipment-as-a-service platforms that unbundle maintenance from capital acquisition.
- Mining Firms:Surface extraction operators in geographies with expanding mineral development.
- Infrastructure Developers:Public-private project sponsors requiring deep foundation and controlled demolition capacity.
Construction Companies holds the largest installed base, though Demolition Contractors are expanding most quickly through rental channel migration.
Application:
Job site environment dictates powerpack architecture selection, with urban proximity favoring electro-hydraulic compliance pathways.
- Road Construction:Asphalt fracturing and subgrade preparation for highway expansion and rehabilitation. Southeast Asian megacities are mandating controlled methods for utility corridor projects, pulling breaker deployment into dense metropolitan cores.
- Building Demolition:Structural fragmentation of concrete and masonry in populated environments. Acoustic ordinances in European metropolitan zones accelerate pre-buy activity ahead of Stage V enforcement deadlines.
- Site Excavation:General earthmoving and material loosening in greenfield development.
- Quarrying:Hard rock extraction in surface mining operations where percussion efficiency determines operating economics.
Road Construction leads by deployment volume, while Building Demolition gains share fastest on urban renewal mandates.
Technology:
Power source selection increasingly tracks regulatory geography rather than raw performance metrics.
- Electro-Hydraulic:Battery-electric assist modules integrated with hydraulic percussion systems. Tunneling contractors in Alpine regions adopt these most aggressively to meet strict diesel fuel allocation limits, with energy recuperation systems absorbing capital that previously flowed to larger carrier purchases.
- Hybrid:Dual-mode architectures switching between diesel and electric powerpacks. Urban demolition fleets in German and French metropolitan zones face the tightest compliance windows for this transitional technology.
- Pneumatic:Compressed-air drive systems for specialized mining applications.
- Mechanical:Direct mechanical linkage systems in mature replacement demand segments.
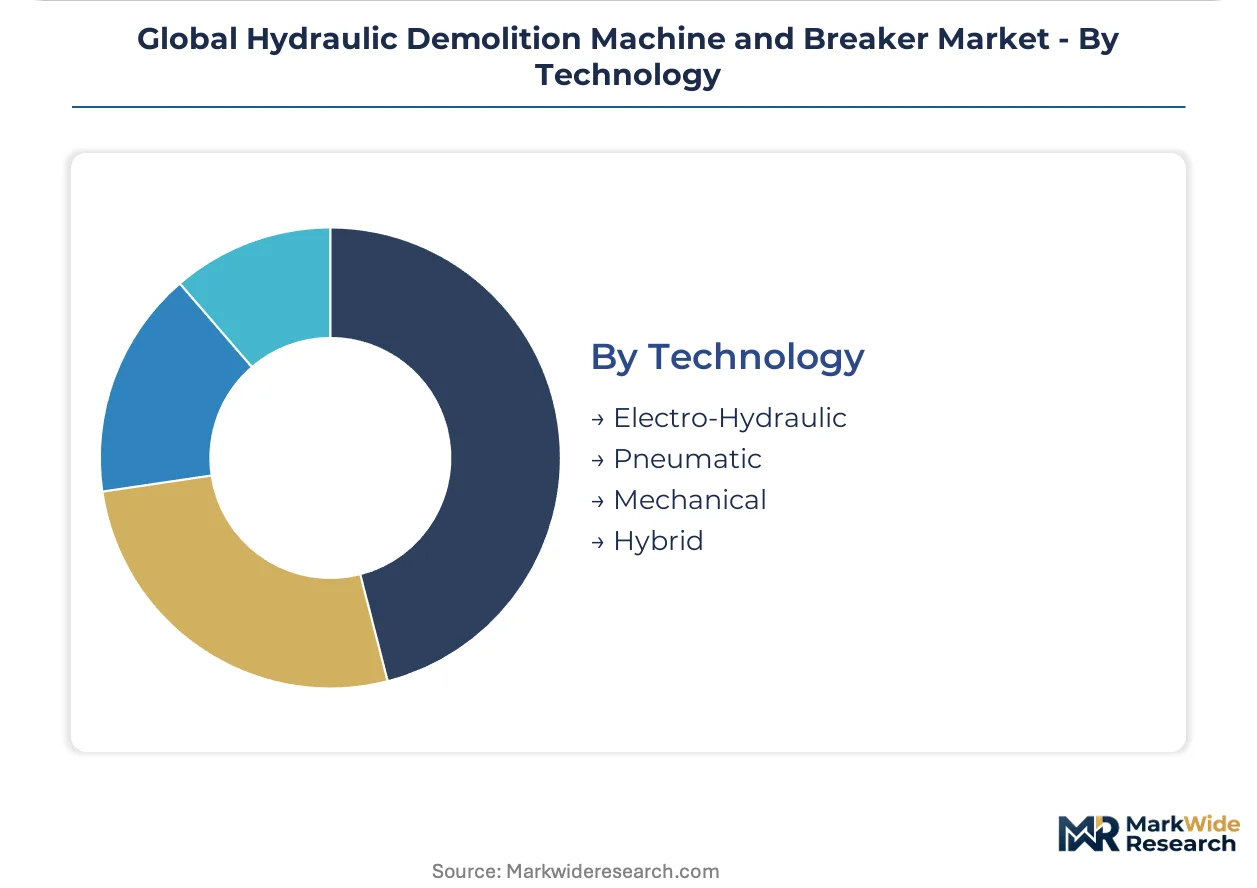
Electro-Hydraulic dominates new platform development, with Hybrid representing the steepest expansion trajectory as OEMs bridge compliance generations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between EPA Tier 4 Final and EU Stage V compliance costs is redirecting assembly capacity toward jurisdictions with lighter certification burdens. Manufacturers are relocating final-stage production to exploit gaps in enforcement timelines and local-content incentives.
United States
Urban demolition contractors in California and New York are accelerating fleet turnover ahead of state-level emissions deadlines. EPA Tier 4 Final regulations compress diesel-hydraulic product lifecycles in metropolitan zones. Equipment-as-a-service platforms concentrate in Los Angeles and New York City metro areas.
Germany
Acoustic ordinances in Berlin and Hamburg metropolitan zones enforce the strictest noise thresholds for urban demolition. EU Stage V type-approval authorities mandate real-driving emissions testing for mobile machinery powerpacks. Tunneling contractors in the Alpine regions adopt regenerative hydraulic systems to meet diesel fuel allocation limits.
China
MEE emissions protocols add compliance layers for breakers exported into domestic construction markets. Yangtze River Delta manufacturers integrate selective catalytic reduction into compact attachment housings. Shanghai and Suzhou industrial clusters specialize in electro-hydraulic system component fabrication.
India
The national infrastructure pipeline accelerates breaker procurement for road widening across tier-2 and tier-3 urban centers. BIS certification requirements apply to imported attachments deployed in public works projects. Maharashtra and Gujarat host the densest concentrations of demolition contractors serving smart city mandates.
Indonesia
Nickel and bauxite expansion in Sulawesi and Maluku creates first-time demand for heavy-class breakers in surface extraction. The country's national mining regulator imposes equipment safety standards on mineral development licenses. Jakarta-based fleet operators are expanding rental availability for mining contractors.
Global Hydraulic Demolition Machine and Breaker Market Competitive Environment
Strategic partnerships dominate the current landscape as attachment specialists seek captive carrier supply agreements. The vendor base stratifies across three tiers: diversified construction equipment conglomerates with in-house breaker lines, independent attachment specialists dependent on third-party carrier compatibility, and regional fabricators serving replacement demand. Archetypes include integrated full-line manufacturers, premium percussion engineering houses, and volume-oriented standard-breaker suppliers. M&A activity and technology licensing agreements represent the dominant competitive moves.
Among diversified construction equipment manufacturers, Caterpillar Inc and Komatsu Limited exemplify the integrated archetype with captive carrier-breaker matching capabilities. Atlas Copco Ltd occupies a position within the premium engineering tier, representing specialists in high-specification percussion systems. These three companies anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Caterpillar Inc |
| Komatsu Limited |
| Atlas Copco Ltd |
| INDECO N.A. |
| Hitachi Construction Machinery |
| J C Bamford Excavators Ltd |
| Sandvik Construction |
| Montabert |
| Volvo Construction Equipment North America |
| Others |
Value Chain & Pricing Dynamics
Construction company procurement clusters in India's tier-2 urban centers operate on project-based contract pricing that bundles breaker attachments with carrier machine lease terms. This buyer concentration compresses standalone attachment margins while elevating total-cost-of-ownership negotiations.
Pricing Analysis
Distributor margin layers absorb 15-25 points before equipment reaches demolition contractors, with premium-mid-economy pricing differentiation separating electro-hydraulic certified units from conventional diesel-hydraulic alternatives. Price differentiation hinges on EPA Tier 4 Final compliance tier and after-sales telemetry bundling. Cost compression in standard breaker tiers is intensifying because Indonesian mining demand pulls alloy steel inputs toward heavy-class rock hammer production. Rental fleet operators show highest price sensitivity; integrated OEM direct sales to infrastructure developers show lowest.
Supply Chain Analysis
High-alloy steel input supply rests on Japanese and South Korean specialty metallurgy producers, with tool bit fabrication concentrated in China and Germany. Nickel-chromium-molybdenum alloy sourcing draws from Indonesian mining expansion zones and Russian refined metal flows. Single-source vulnerability concentrates in Japanese hydraulic component suppliers serving electro-hydraulic system integrators. Distribution runs through captive OEM dealer networks in North America and independent attachment distributors in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydraulic demolition equipment market functions as a stable compounder anchored by irreplaceable urban infrastructure replacement cycles. Regulatory compliance mandates ensure steady equipment turnover regardless of construction cyclicality.
For Market Incumbents: To counter rental channel disintermediation, deepen captive carrier-breaker matching capabilities through in-house production of electro-hydraulic powerpack modules. Prioritize certification investment for EU Stage V type-approval ahead of enforcement deadlines to lock out latecomers from German and French metropolitan markets. For New Entrants and Emerging Players: Tier-2 Indian demolition contractors represent the most penetrable buyer archetype, with BIS certification gaps creating entry windows for cost-optimized standard breaker designs. A telematics-enabled rental partnership model with Maharashtra-based fleet operators offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Diversified construction equipment conglomerates are the most active acquirer in this space, seeking attachment specialists to fill breaker line gaps. The five-to-ten year viability framing favors premium percussion engineering houses with proprietary energy recuperation IP. Watch pre-buy activity spikes ahead of EPA and EU enforcement deadlines as inflection indicators for valuation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Hydraulic Powerpack Development | Battery-electric assist modules unlock German and French urban job sites under strict acoustic ordinances. |
| Backward Integration into Tool Bit Metallurgy | In-house nickel-chromium-molybdenum alloy sourcing insulates margin predictability from commodity volatility. |
| Telematics-Enabled Rental Platform Launch | IoT-hour metering unbundles attachments from carriers for California and New York demolition contractors. |
| Joint Venture with Indonesian Mining Fleet Operator | Local assembly partnerships bypass carbon-border exposure for Sulawesi nickel extraction projects. |
| Selective Catalytic Retrofit Certification | Compact SCR housing integration secures EU Stage V type-approval for Alpine tunneling contractor demand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment procurement managers at Indian infrastructure developers, aftermarket service heads at North American dealer networks, plant engineers at Japanese hydraulic component suppliers, and rental fleet operators in Indonesian mining zones with secondary validation through customs trade data, EPA certification filings, EU type-approval registers, and OEM SEC disclosures. Bottom-up attachment shipment tallies and top-down carrier machine installation rates were triangulated against regional construction spending indices.
Historical reference periods anchored the projection horizon to pre-regulatory and post-regulatory equipment turnover cycles, with segmentation modeled across product type, end user archetype, application environment, and power source technology. CAGRs were derived from fitted growth curves incorporating alloy steel price trajectories, urban demolition permit issuance trends, and mining license expansion patterns in Southeast Asia.
Underlying measurement precision varies by segment; electro-hydraulic and hybrid technology categories carry tighter precision than mature pneumatic alternatives due to faster platform turnover. Forecasts reflect assumptions around enforcement timelines for EPA Tier 4 Final and EU Stage V, with carbon-border adjustment phase-ins and local-content rule shifts representing specific risk factors that could revise trajectory. A small set of triggers—pre-buy acceleration patterns, alloy price spikes, and carrier machine supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market